
 At-Home Beauty Devices Market | 2026-2036
At-Home Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
At-Home Beauty Devices Market Analysis
South Korean OEM manufacturers is decoupling from legacy Japanese component suppliers for at-home beauty device production. L'Oréal Group leverages its dermatological research infrastructure to anchor premium device development across European and North American markets. Koninklijke Philips N.V. competes through its broad appliance distribution network, while NuFACE specializes in microcurrent technology for facial toning applications.
At-home beauty devices comprise electrically powered instruments designed for personal cosmetic treatment, typically operating at wavelengths between 400-700 nanometers for LED therapy or delivering 300-400 microamperes in microcurrent configurations, with primary purpose to deliver salon-equivalent skin rejuvenation, hair removal, or anti-aging outcomes without clinical supervision. LED masks and microcurrent devices command the highest margin pools due to consumable attachment cycles and subscription skincare pairing, whereas hair removal systems represent a maturing segment with slower replacement frequencies. Hair growth functionality within the anti-aging and skin rejuvenation cluster is expanding fastest among male consumers entering the thirty-five to fifty-four demographic.
FDA 510(k) clearance requirements for intense pulsed light and laser hair removal devices create substantial barriers to US market entry, while EU MDR reclassification of certain RF and ultrasonic devices as Class IIa medical instruments imposes additional clinical evidence burdens on manufacturers. China's NMPA cosmetic device filing system and South Korea's MFDS electrical safety standards further fragment compliance obligations across major production hubs. Stakeholders must monitor regulatory divergence between cosmetic and medical device classifications, as reclassification waves in Europe and North America could force portfolio restructuring or channel shifts toward professional-only distribution.
Market Dynamics
Regulatory reclassification of RF and ultrasonic devices as medical instruments under EU MDR is forcing manufacturers to rebuild clinical evidence portfolios or abandon European distribution channels entirely.
Growth Catalysts
- FDA 510(k) pathway maturation:Established clearance frameworks for intense pulsed light devices reduce time-to-market uncertainty for US-bound manufacturers.
- LED wavelength optimization:633 nanometer red-light and 415 nanometer blue-light configurations demonstrate measurable collagen induction and acne reduction in peer-reviewed dermatology literature.
- Subscription skincare pairing:Device-anchored consumable cycles generate recurring revenue streams that offset high customer acquisition costs for direct-to-consumer brands.
Market Restraints
- EU MDR Class IIa reclassification:Radiofrequency and ultrasonic devices now require clinical investigation reports and notified body involvement, adding eighteen to thirty-six months to European launch timelines.
- Japanese component dependency:Premium microcurrent control modules and optical-grade sapphire substrates concentrate production in Osaka and Nagoya manufacturing clusters.
- IPL device substitution:Professional clinic-based laser hair removal prices have compressed forty percent in metropolitan US and South Korean markets, narrowing the at-home value proposition.
Strategic Opportunities
- Indian market underpenetration:BIS electrical safety certification remains underutilized by foreign device manufacturers, creating first-mover positioning for compliant entrants in Mumbai and Delhi NCR retail channels.
- Hair growth application expansion:Male consumers aged thirty-five to fifty-four represent unaddressed demand for low-level laser therapy devices targeting androgenetic alopecia.
- Telemedicine integration:Remote dermatologist consultation platforms enable prescription-grade device recommendations without physical clinic infrastructure.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity and sensitization studies face eighteen-month queues at accredited European laboratories, delaying MDR technical documentation completion.
- Optical calibration drift:LED array intensity degradation over twelve-to-eighteen-month usage cycles creates warranty exposure and consumer trust erosion if unaddressed through predictive maintenance algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | At-Home Beauty Devices Market |
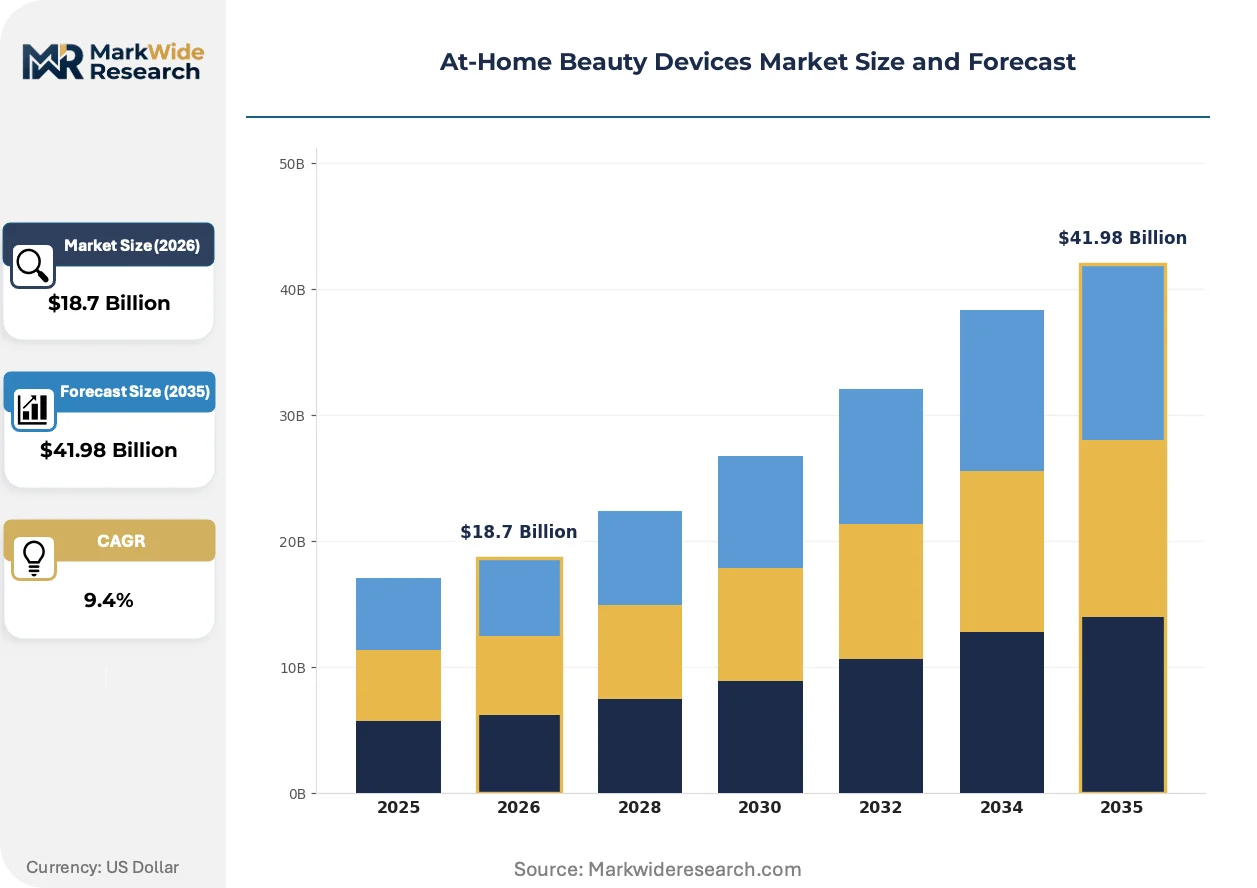
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: LED Masks, Microcurrent Devices, Hair Removal Systems, Cleansing Brushes Functionality: Anti-Aging, Skin Rejuvenation, Hair Growth, Acne Treatment End User: Consumers, Aestheticians, Salons, Dermatologists Technology: Ultrasonic, Radiofrequency, Thermal, Light Therapy |
| Companies Covered | Tria Beauty Inc., Home Skinovations Ltd., L'Oréal Group, Conair Corporation, Panasonic Corporation, Koninklijke Philips N.V., Procter & Gamble, NuFACE, Nu Skin Enterprises Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
At-Home Beauty Devices Market Emerging Trajectories
Convergence of microcurrent delivery systems with real-time skin impedance feedback is compressing the performance gap between professional aesthetic equipment and at-home alternatives.
Multi-wavelength LED arrays with programmable sequencing protocols are consolidating treatment efficacy claims across anti-aging, acne management, and hyperpigmentation applications. Millennial and Gen Z consumers in Seoul and Los Angeles metropolitan areas adopt these systems at replacement cycles of eighteen to twenty-four months. The technology is consolidating formerly separate device categories into single-platform solutions that reduce bathroom counter footprint and total cost of ownership.
EU MDR transitional provisions for legacy devices expire in staggered phases through 2027 and 2028, forcing manufacturers to choose between costly clinical evidence generation and market withdrawal. Notified body capacity constraints in Germany and the Netherlands extend certification timelines to fourteen months for novel RF-based skin tightening devices. Premium European brands with existing dermatology clinic partnerships are redirecting R&D budgets toward professional-only distribution to bypass at-home medical device classification.
Direct-to-consumer brands now bundle hardware with personalized skincare formulations and mobile application-guided treatment protocols. Sephora and Ulta Beauty retail footprints in the United States have displaced traditional electronics channels as primary discovery environments for first-time buyers. South Korean social commerce platforms Kakao and Naver accelerate purchase decisions through live-streamed dermatologist demonstrations and user-generated before-and-after content.
At-Home Beauty Devices Market Segmentation
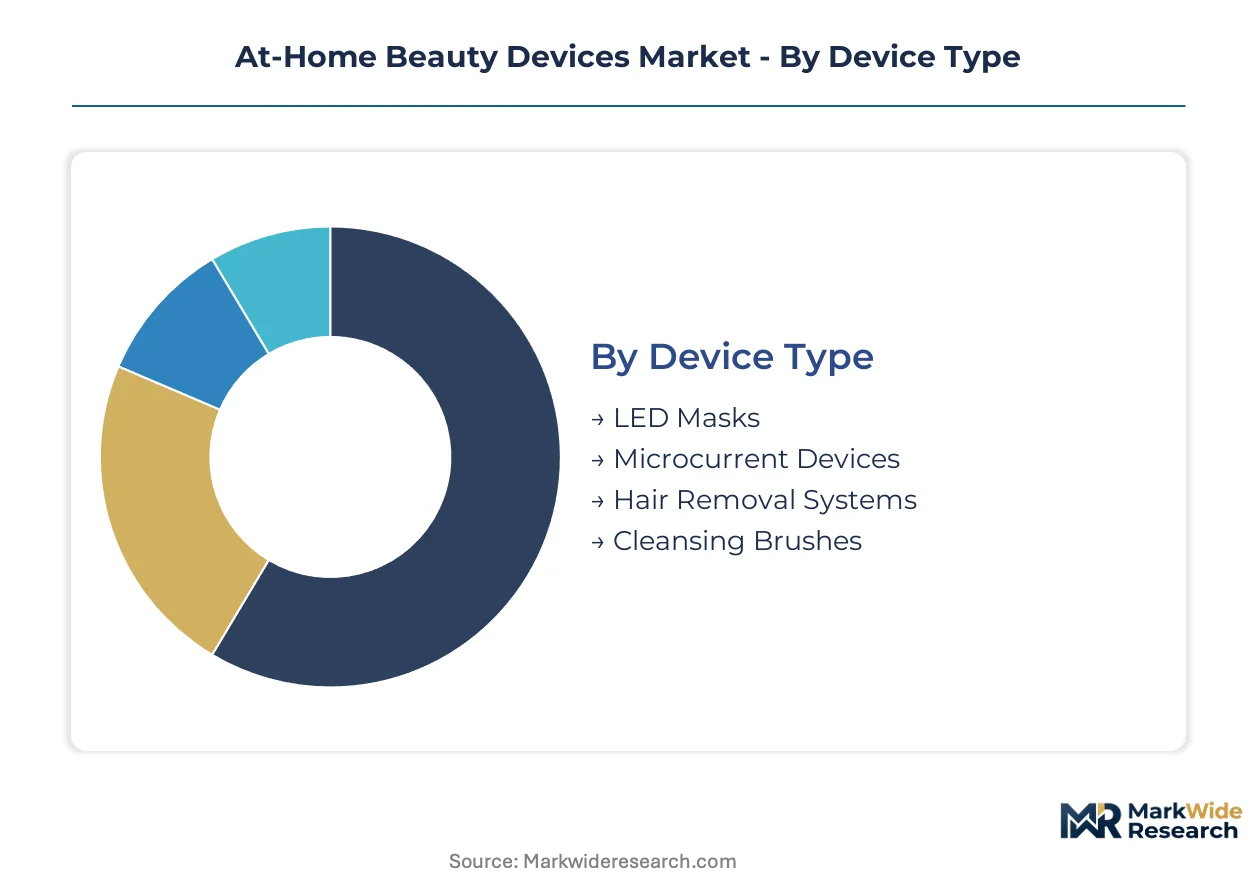
Device classification in this market determines regulatory pathway, margin structure, and replacement cycle economics. Buyers prioritize efficacy claims validated by clinical literature over price-point alone, reshaping how manufacturers configure product portfolios across consumer and professional channels.
Device Type:
Purchase decisions hinge on treatment modality compatibility with existing skincare routines and bathroom countertop space constraints.
- LED Masks:Full-face arrays operating at 633nm red and 415nm blue wavelengths deliver collagen induction and acne reduction through photobiomodulation. Demand concentrates in Seoul and Los Angeles metropolitan areas where Millennial and Gen Z consumers replace units every eighteen to twenty-four months, driven by wavelength optimization claims in peer-reviewed dermatology journals.
- Microcurrent Devices:Handheld instruments delivering 300-400 microamperes mimic the body's natural electrical currents for facial toning applications. NuFACE anchors this segment through subscription skincare pairing that generates recurring revenue streams offsetting high customer acquisition costs in direct-to-consumer channels.
- Hair Removal Systems:Intense pulsed light and laser-based instruments target follicular melanin for permanent hair reduction. Professional clinic-based laser prices have compressed forty percent in metropolitan US and South Korean markets, narrowing the at-home value proposition and extending replacement cycles.
- Cleansing Brushes:Rotating or sonic-vibration tools for surface-level skin cleansing. L'Oréal Group and Koninklijke Philips N.V. compete through appliance distribution networks and dermatological research infrastructure.
LED Masks lead on scale; Microcurrent Devices lead on momentum.
Functionality:
Clinical outcome specificity determines reimbursement potential and cross-selling opportunities with topical formulations.
- Anti-Aging:RF and microcurrent technologies targeting wrinkle reduction and skin laxity now face EU MDR Class IIa reclassification, adding eighteen to thirty-six months to European launch timelines and forcing portfolio restructuring toward professional-only distribution.
- Skin Rejuvenation:Multi-wavelength LED protocols consolidating formerly separate device categories into single-platform solutions. Kakao and Naver social commerce platforms accelerate purchase decisions through live-streamed dermatologist demonstrations in South Korea.
- Hair Growth:Low-level laser therapy devices targeting androgenetic alopecia. Male consumers aged thirty-five to fifty-four in the United States represent unaddressed demand, climbing the fastest among functionality clusters.
- Acne Treatment:Blue-light therapy at 415nm wavelengths demonstrates measurable bacterial reduction in clinical studies. FDA 510(k) clearance frameworks reduce time-to-market uncertainty for US-bound manufacturers.
Anti-Aging commands the highest margin pool; Hair Growth gains share fastest.
End User:
Channel selection dictates pricing architecture, with professional segments requiring clinical evidence portfolios that consumer segments bypass.
- Consumers:Direct-to-first-time buyers through Sephora and Ulta Beauty retail footprints in the United States, displacing traditional electronics channels as primary discovery environments.
- Aestheticians:Licensed practitioners seeking portable devices for mobile service delivery. EU MDR transitional provisions expire through 2027 and 2028, forcing evidence generation or market withdrawal.
- Salons:High-volume commercial operators prioritizing device durability and warranty terms over feature sophistication.
- Dermatologists:Prescription-grade device recommendations enabled by telemedicine integration platforms without physical clinic infrastructure.
Consumers dominate volume; Dermatologists anchor premium pricing.
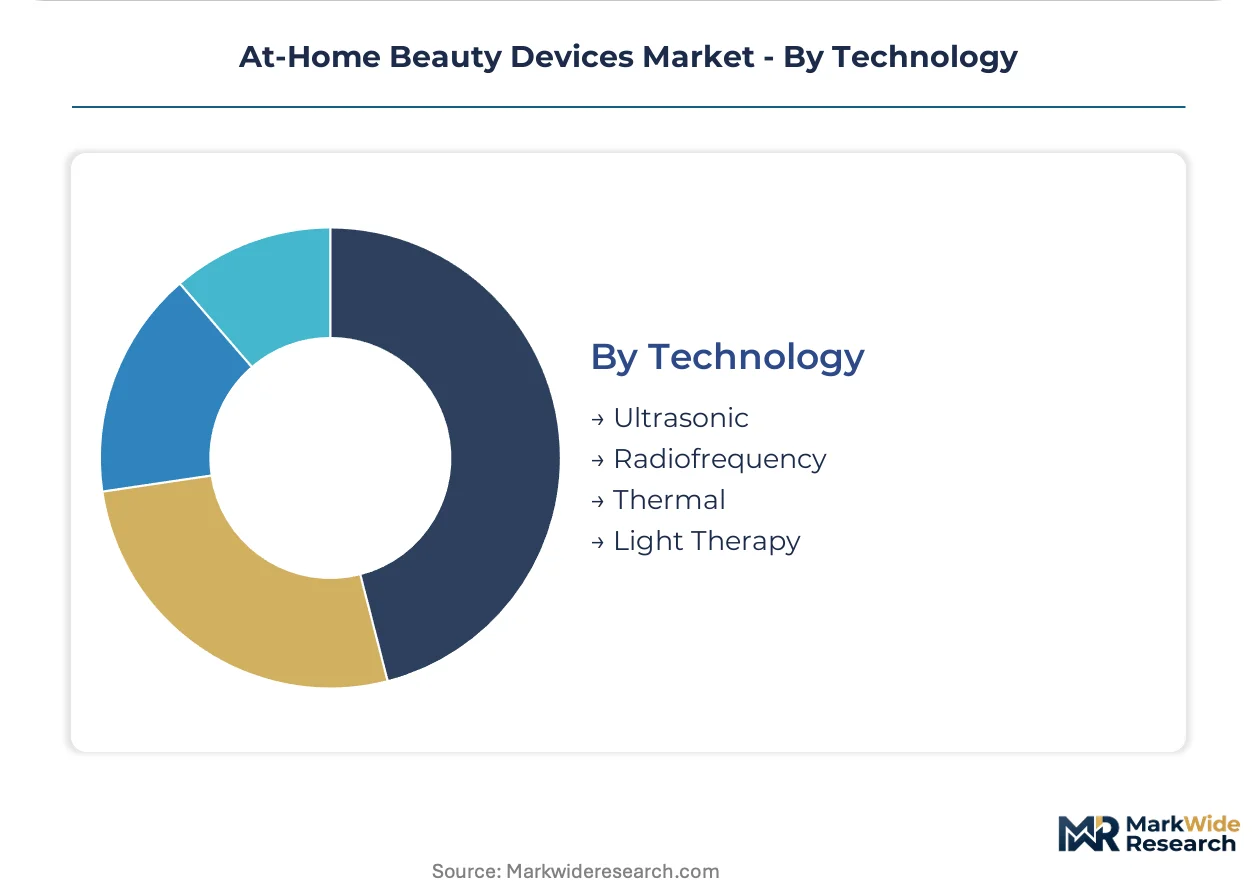
Technology:
Component sourcing geography and calibration precision requirements differentiate competitive positioning across technology platforms.
- Ultrasonic:High-frequency vibration devices for product penetration and exfoliation. Japanese component dependency in premium microcurrent control modules concentrates production in Osaka and Nagoya manufacturing clusters.
- Radiofrequency:Thermal collagen remodeling systems now reclassified as Class IIa medical instruments under EU MDR. Notified body capacity constraints in Germany and the Netherlands extend certification timelines to fourteen months.
- Thermal:Heat-based devices for pore opening and circulation enhancement. Biocompatibility testing backlog at ISO 10993-accredited European laboratories creates eighteen-month queues for cytotoxicity studies.
- Light Therapy:LED and laser-based systems with FDA 510(k) clearance pathways for intense pulsed light devices creating substantial barriers to US market entry.
Light Therapy leads on regulatory clarity; Radiofrequency faces the steepest compliance headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States consumers replace LED masks every eighteen to twenty-four months, while South Korean buyers concentrate purchases through Kakao and Naver social commerce platforms. These contrasting channel patterns illustrate how geographic context reshapes go-to-market architecture for device manufacturers.
United States
Sephora and Ulta Beauty retail footprints displace traditional electronics channels as primary discovery environments for first-time buyers. FDA 510(k) clearance requirements for intense pulsed light devices create substantial barriers to market entry for foreign manufacturers. The Los Angeles metropolitan area anchors demand concentration for multi-wavelength LED arrays among Millennial and Gen Z consumers.
South Korea
Live-streamed dermatologist demonstrations on social commerce platforms accelerate purchase decisions for microcurrent and LED-based systems. MFDS electrical safety standards impose certification requirements that favor domestic OEM manufacturers decoupling from legacy Japanese component suppliers. Seoul Capital Area concentrates replacement cycle demand for full-face LED arrays operating at optimized wavelengths.
China
NMPA cosmetic device filing system fragments compliance obligations for international brands seeking direct-to-consumer distribution. Male consumers aged thirty-five to fifty-four drive fastest growth in low-level laser therapy devices targeting androgenetic alopecia. Yangtze River Delta manufacturing clusters specialize in optical-grade sapphire substrates for premium device production.
Germany
Notified body capacity constraints extend certification timelines to fourteen months for novel RF-based skin tightening devices seeking EU MDR compliance. EMA and national regulator oversight of reclassified medical devices forces portfolio restructuring toward professional-only distribution channels. Bavaria and Baden-Württemberg industrial regions concentrate biocompatibility testing laboratory capacity facing eighteen-month queues.
India
BIS electrical safety certification remains underutilized by foreign device manufacturers, creating first-mover positioning for compliant entrants. Central Drugs Standard Control Organization pathways for cosmetic versus medical device classification remain unresolved for RF and ultrasonic technologies. Mumbai and Delhi NCR retail channels represent underpenetrated demand for subscription skincare pairing models.
At-Home Beauty Devices Market Vendor Landscape
United States producers anchor the direct-to-consumer tier; South Korean specialists hold the OEM manufacturing tier. The vendor base stratifies across three tiers: multinational appliance conglomerates with dermatology research infrastructure, pure-play device specialists with subscription revenue models, and contract manufacturers serving private-label brands. Two dominant competitive moves are reshaping positioning: strategic partnerships between device makers and telemedicine platforms for prescription-grade recommendations, and geographic expansion into Indian retail channels ahead of BIS certification saturation.
Within the multinational conglomerate tier, L'Oréal Group and Koninklijke Philips N.V. occupy positions anchored by broad distribution networks and research infrastructure. Among pure-play specialists, NuFACE exemplifies the subscription-anchored revenue model that offsets direct-to-consumer acquisition costs. Panasonic Corporation represents the Japanese electronics conglomerate archetype with legacy appliance channel access. These three company types illustrate how competitive positioning depends on whether scale, recurring revenue architecture, or manufacturing depth serves as the primary capability.
| Leading Market Players |
|---|
| Tria Beauty Inc. |
| Home Skinovations Ltd. |
| L'Oréal Group |
| Conair Corporation |
| Panasonic Corporation |
| Koninklijke Philips N.V. |
| Procter & Gamble |
| NuFACE |
| Nu Skin Enterprises Inc. |
| Others |
Supply Flow & Price Mechanics
Direct-to-consumer brands with subscription skincare pairing models command pricing power through recurring revenue architectures that offset customer acquisition costs in the United States and South Korea. Their procurement concentration around LED wavelength optimization and microcurrent control modules ties pricing flexibility to component sourcing geography.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing clusters are reshaping price floors for optical-grade sapphire substrates and LED arrays. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 510(k) certification status and dermatology clinic partnership depth. Cost compression in economy-tier hair removal systems intensifies because professional clinic-based laser prices have compressed in metropolitan US markets. Mass-market consumers through Sephora and Ulta Beauty retail footprints exhibit highest price sensitivity; dermatologist-recommended professional tiers show lowest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from South Korean OEM manufacturers mandate multi-supplier qualification for premium microcurrent control modules and optical-grade sapphire substrates. Geographic supply concentration centers on China for LED array fabrication, South Korea for device assembly, and Japan for precision control components. Raw material dependencies include gallium nitride for LED chips, copper windings for microcurrent delivery, and medical-grade polymers for biocompatible housings. Single-source vulnerability concentrates in Osaka and Nagoya manufacturing clusters for sapphire substrates. Distribution runs through direct-to-consumer brand websites, Sephora and Ulta Beauty retail footprints, and social commerce platforms.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR Class IIa reclassification costs in Germany and the Netherlands run eighteen to thirty-six months longer than FDA 510(k) clearance timelines in the United States.
For Market Incumbents: Acquire clinical evidence generation capabilities to defend against EU MDR transitional provision expirations forcing portfolio restructuring. Backward integration into optical-grade sapphire substrate production reduces dependency on Japanese component suppliers. Capacity addition in Indian manufacturing clusters with BIS electrical safety certification captures first-mover positioning before foreign entrant saturation.
For New Entrants and Emerging Players: Telemedicine platform partnerships enable prescription-grade device recommendations without physical clinic infrastructure investment. Male consumers aged thirty-five to fifty-four in the United States represent the most penetrable segment for low-level laser therapy devices targeting androgenetic alopecia. Social commerce live-streaming demonstrations on Kakao and Naver accelerate purchase decisions in South Korea.
For Investors and Strategic Acquirers: Appliance conglomerates with dermatology research infrastructure are the most active acquirer in this space. The five-to-ten year viability window favors targets with subscription-anchored revenue models and FDA 510(k) clearance portfolios. Watch notified body capacity constraints in Germany and the Netherlands as inflection indicators for European market withdrawal versus compliance investment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Skincare Pairing Launch | Recurring revenue offsets customer acquisition costs for direct-to-consumer brands. |
| Telemedicine Platform Partnership | Remote dermatologist consultations enable prescription-grade device recommendations. |
| EU MDR Clinical Evidence Investment | Notified body certification timelines extend fourteen months for RF-based devices. |
| Indian BIS Certification Entry | Underutilized compliance pathway creates first-mover positioning in Mumbai retail. |
| Multi-Wavelength LED Array Development | Programmable sequencing consolidates anti-aging, acne, and hyperpigmentation claims. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged device development executives at L'Oréal Group and Koninklijke Philips N.V., regulatory affairs leads navigating FDA 510(k) and EU MDR pathways, dermatology clinic procurement managers, and direct-to-consumer brand marketing heads. Secondary validation drew from FDA 510(k) clearance databases, EMA medical device classification notices, NMPA cosmetic device filings, and MFDS electrical safety standards. Bottom-up unit shipment modeling and top-down market sizing triangulated across manufacturer disclosures and retail channel audits.
Comparable-period anchoring tied projection assumptions to historical replacement cycle patterns and regulatory pathway maturation trajectories across the analysis window. Segmentation dimensions modeled include device type, functionality cluster, end-user channel, and technology platform. CAGRs derived from weighted average of segment-level growth rates calibrated to peer-reviewed dermatology literature adoption curves. Industry-specific inputs incorporated LED wavelength optimization claims and microcurrent impedance feedback convergence timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR reclassification waves and notified body capacity constraints. Forecasts reflect documented assumptions regarding Millennial and Gen Z replacement cycle persistence and social commerce platform penetration rates. Deviation in FDA 510(k) clearance timeline compression or professional clinic-based laser price trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
China Eyelash Serum Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Facial Cleansers and Toners Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market