
 Cosmetic Wax Market | 2026-2036
Cosmetic Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Wax Market Analysis
Asset-light contract manufacturing and private-label financing is reshaping competitive entry in cosmetic wax production, enabling smaller brands to bypass capital-intensive refining infrastructure. Koster Keunen leverages its vertical integration in natural wax cultivation to sustain premium positioning across European and North American supply chains. Dow Inc. anchors industrial-scale synthetic wax output, competing on consistent polymer-grade specifications for high-volume salon distributors. Rica Group specializes in Mediterranean-sourced formulations, differentiating through regional ingredient provenance and ISO-certified processing protocols.
Cosmetic wax comprises lipophilic solid mixtures of esters, fatty acids, and hydrocarbons derived from petroleum, botanical, or mineral sources, with melting points typically ranging from 50°C to 90°C depending on composition and intended dermal application. These materials function as depilatory substrates that adhere to hair shafts upon application and solidification, enabling mechanical extraction without water-based dissolution. Hard wax currently leads product type revenue pools due to superior performance on coarse hair and reduced skin irritation, while sugar wax represents the fastest-expanding category as clean-label and water-soluble formulations gain traction among environmentally conscious home users. Block and granule forms dominate professional channels where technicians require precise temperature control and portion flexibility, whereas roll-on formats concentrate margin in retail consumer segments prioritizing convenience.
EMA cosmetic ingredient safety assessments and REACH chemical registration requirements in Europe constrain synthetic additive portfolios, while FDA cosmetic labeling regulations and state-level professional licensing boards in the United States govern salon-grade product claims and practitioner application standards. Brazil's ANVISA mandates dermatological safety testing for imported depilatory formulations, creating compliance thresholds that filter lower-quality imports from Asian manufacturing hubs. Stakeholders must monitor evolving biopolymer certification schemes and regional restrictions on microplastic-containing synthetic waxes to anticipate reformulation costs and sourcing pivots.
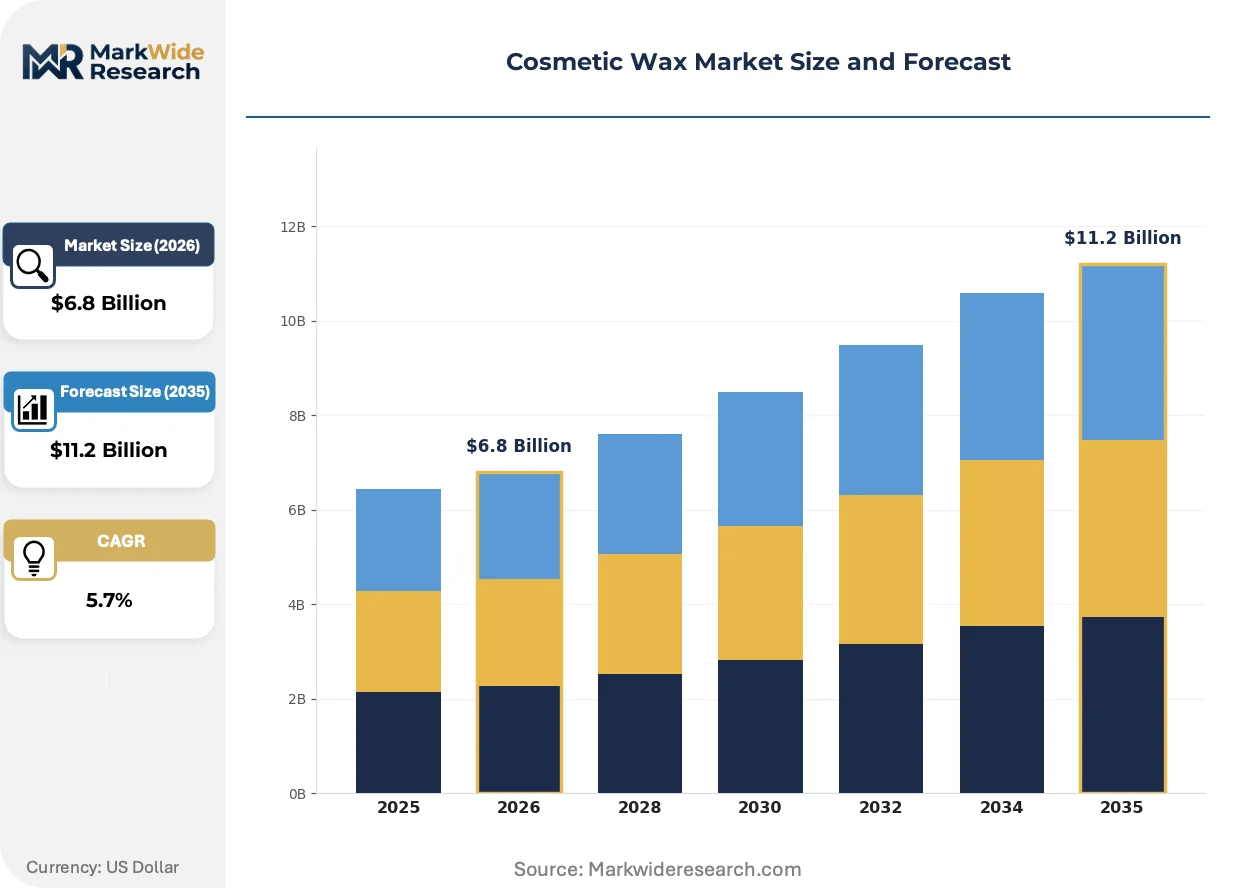
Market Dynamics
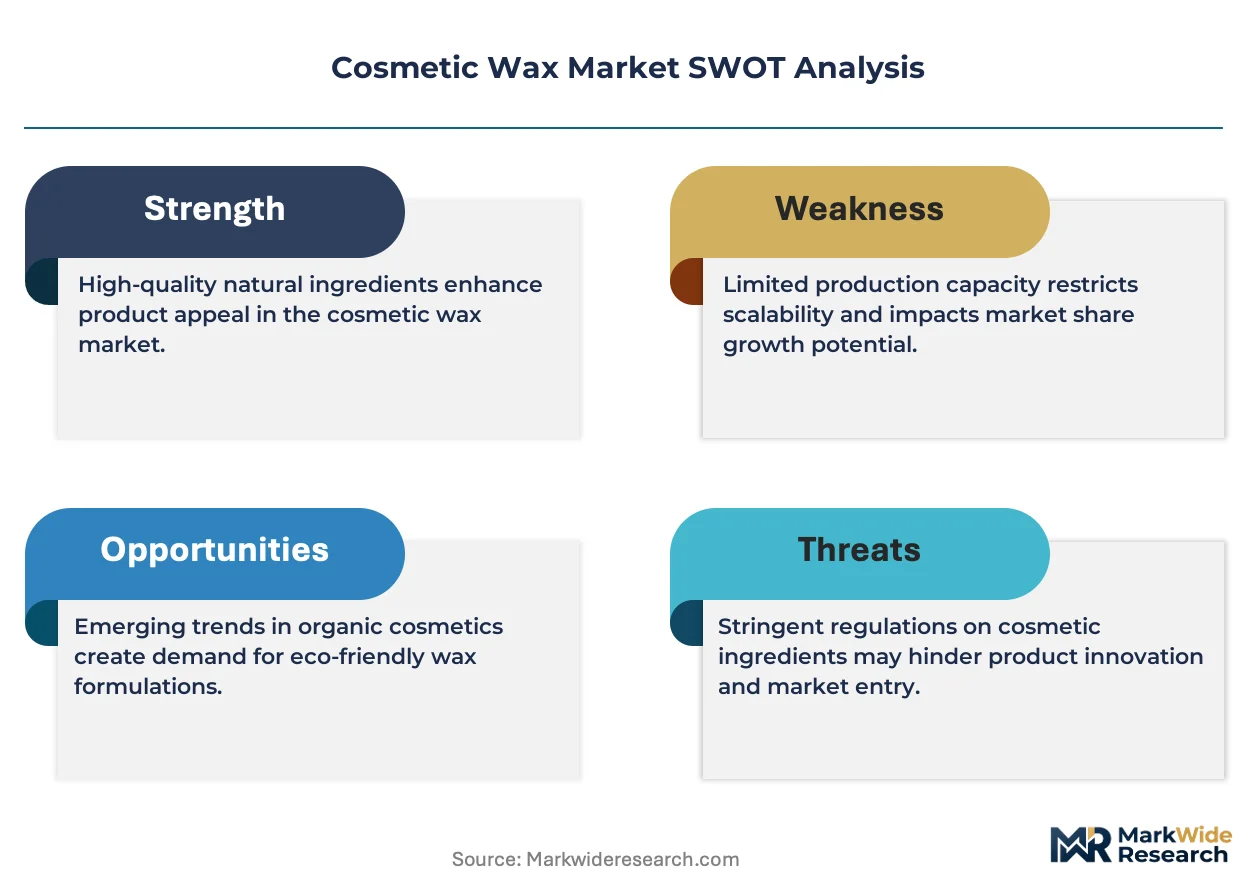
REACH chemical registration requirements and evolving FDA cosmetic ingredient standards are forcing simultaneous reformulation across synthetic and natural wax portfolios, compressing product development timelines while elevating compliance costs for multi-region suppliers.
Growth Catalysts
- Professional salon expansion:Brazil's dense network of waxing salons sustains high per-capita consumption of professional-grade depilatory products, with technicians driving preference for block and granule formats that enable precise temperature control.
- Clean-label formulation pull:EMA cosmetic ingredient safety assessments are elevating demand for botanical-derived waxes, particularly sugar wax formulations that offer water-soluble, environmentally compatible alternatives to petroleum-based substrates.
- Hard wax performance premium:Superior adhesion to coarse hair and reduced dermal irritation is concentrating revenue in hard wax product types across European and North American professional channels.
Market Restraints
- Petroleum feedstock volatility:Synthetic wax producers face margin compression from fluctuating polymer-grade hydrocarbon input costs, particularly affecting Dow Inc.'s industrial-scale output for high-volume salon distributors.
- Import filtration thresholds:Brazil's ANVISA dermatological safety testing mandates create compliance barriers that systematically exclude lower-quality formulations from Asian manufacturing hubs.
- Microplastic regulatory horizon:Evolving EU restrictions on microplastic-containing synthetic waxes are forcing anticipatory reformulation investments before formal prohibition timelines.
Strategic Opportunities
- Home-use convenience formats:Roll-on applicator designs are capturing margin in retail consumer segments prioritizing at-home depilation, displacing traditional salon-dependent purchasing patterns.
- Mediterranean ingredient provenance:ISO-certified processing protocols for regional botanical sourcing, as practiced by Rica Group, enable premium positioning through supply chain traceability claims.
- Biopolymer certification schemes:Early alignment with emerging sustainability standards creates first-mover advantage in synthetic wax replacement categories.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Formulators must reconcile divergent FDA labeling regulations, REACH chemical registration requirements, and ANVISA safety testing protocols within compressed product launch windows.
- Technician certification standardization:State-level professional licensing boards in the United States impose variable practitioner training requirements that fragment market access for salon-grade product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Wax Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Wax, Soft Wax, Sugar Wax, Gel Wax Application: Hair Removal, Skin Care, Spa Treatments, Aesthetic Procedures Form: Block, Granule, Roll-on, Cream End User: Beauty Salons, Spas, Home Users, Dermatology Clinics |
| Companies Covered | Cirepil, Italwax, Dow Inc., Cosmewax, GiGi, Koster Keunen, Rica Group, Depileve, Starpil Wax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Wax Market Emerging Trajectories
Digital formulation tools and biopolymer substitution pathways are compressing traditional R&D cycles while regulatory pressure on synthetic additives accelerates botanical wax innovation across professional and consumer channels.
Temperature-controlled dispensing systems are virtualizing the application experience in professional settings. Salon technicians now deploy precision-heated cartridge systems that eliminate manual temperature judgment errors. This virtualization of technique-dependent processes is compressing training requirements while standardizing service outcomes across franchise networks.
REACH chemical registration requirements are systematically constraining synthetic additive portfolios across European supply chains. ECHA substance evaluation protocols are forcing removal of specific polymer modifiers previously standard in low-cost depilatory formulations. Professional-grade suppliers are responding with accelerated natural wax blend development to maintain market access.
Consumer preference for water-soluble, residue-free removal is rotating demand toward sugar wax formulations. Home users in environmentally conscious segments are abandoning petroleum-based strips in favor of compostable alternatives. This shift is most visible in urban European markets where municipal waste regulations amplify clean-label purchasing criteria.
Cosmetic Wax Market Segmentation
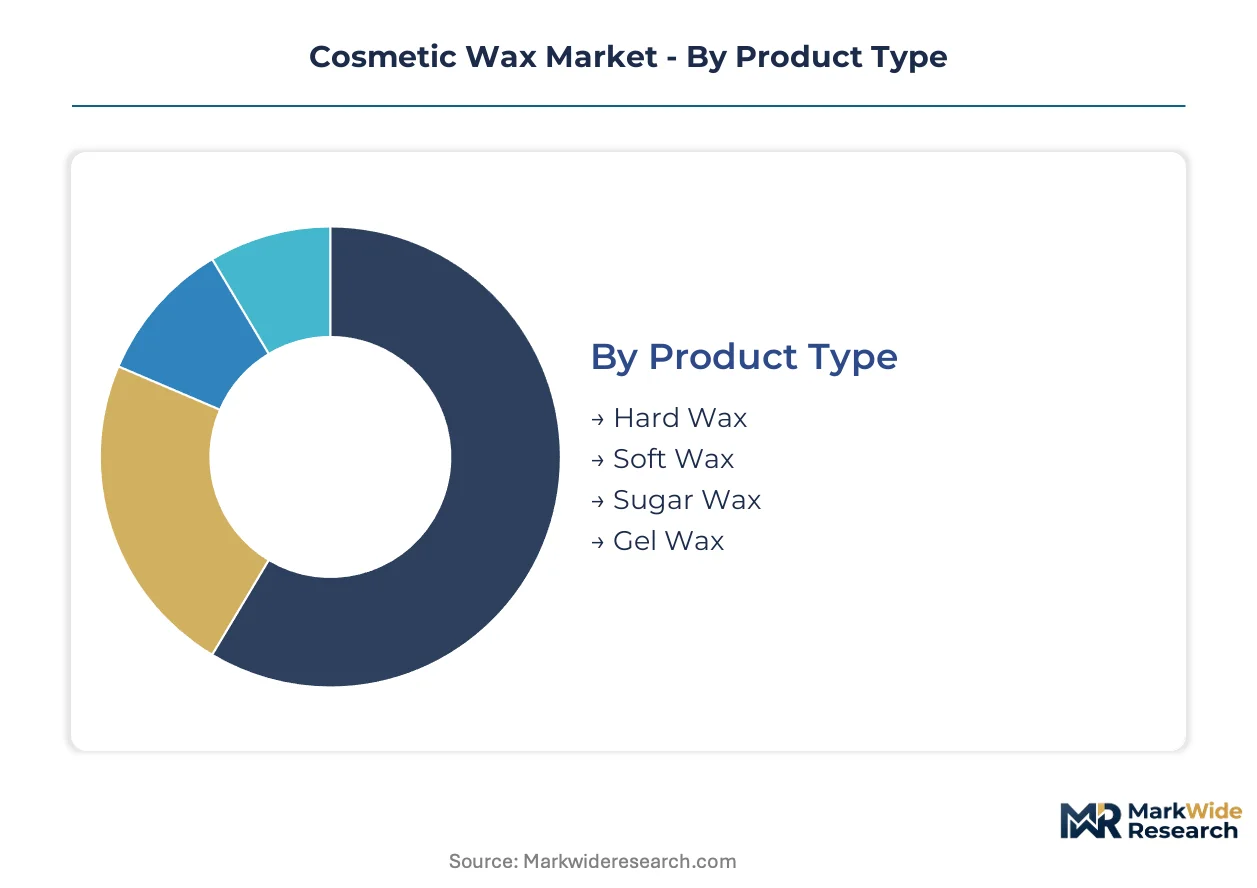
Cosmetic wax segmentation reflects divergent technical requirements between professional technicians and home consumers. Product viscosity, melting point precision, and application method dictate purchasing patterns across salon supply chains and retail channels.
Product Type:
After-sales service intensity varies sharply across wax chemistries, with hard wax demanding technician training programs and soft wax requiring temperature calibration support.
- Hard Wax:Polymer-rich formulations solidify independently without strip assistance, enabling single-pass extraction on coarse hair. Brazilian technicians favor block formats for precise temperature control during high-volume salon operations. EMA safety assessments are elevating formulation standards for polymer modifiers.
- Sugar Wax:Water-soluble blends of sucrose, citric acid, and water permit compostable disposal and residue-free removal. Urban European consumers are rotating demand toward this category as municipal waste regulations tighten. This segment is climbing the fastest among environmentally conscious home users.
- Soft Wax:Requires fabric strip adhesion for hair removal, offering lower material cost per treatment.
- Gel Wax:Transparent formulations enable visual monitoring of application thickness.
Hard wax holds the largest share; momentum sits with sugar wax.
Application:
Cost tier differentiation separates commodity depilatory supplies from premium aesthetic service inputs.
- Hair Removal:Professional-grade formulations prioritize adhesion strength and skin irritation minimization. Brazilian salon networks sustain concentrated demand for block and granule formats with precise thermal specifications. ANVISA dermatological testing mandates filter lower-quality imports.
- Skin Care:Paraffin-based treatments for hydration and barrier repair command premium positioning in spa channels. Mediterranean-sourced botanical additives enable traceability claims. This segment is expanding most quickly as wellness tourism recovers.
- Spa Treatments:Multi-step protocols integrate waxing with post-depilatory soothing applications.
- Aesthetic Procedures:Pre-treatment skin preparation supports laser and light-based hair reduction.
Hair removal dominates volume; skin care exhibits the steepest expansion trajectory.
Form:
Volume concentration in professional channels favors formats enabling precise portion control and thermal management.
- Block:Solid slabs allow technicians to customize melt quantities and maintain consistent working temperatures. European salon distributors specify block dimensions for standard warming equipment compatibility. REACH compliance costs compress margins for synthetic block producers.
- Roll-on:Cartridge systems with integrated heating elements target convenience-seeking home users. US retail channels prioritize single-use applicator designs. This format is gaining share fastest in consumer segments.
- Granule:Pelletized forms accelerate melting speed and reduce thermal degradation risk.
- Cream:Pre-emulsified preparations eliminate heating requirements for sensitive-skin applications.
Block formats command professional channel volume; roll-on designs are displacing traditional home-use purchases.
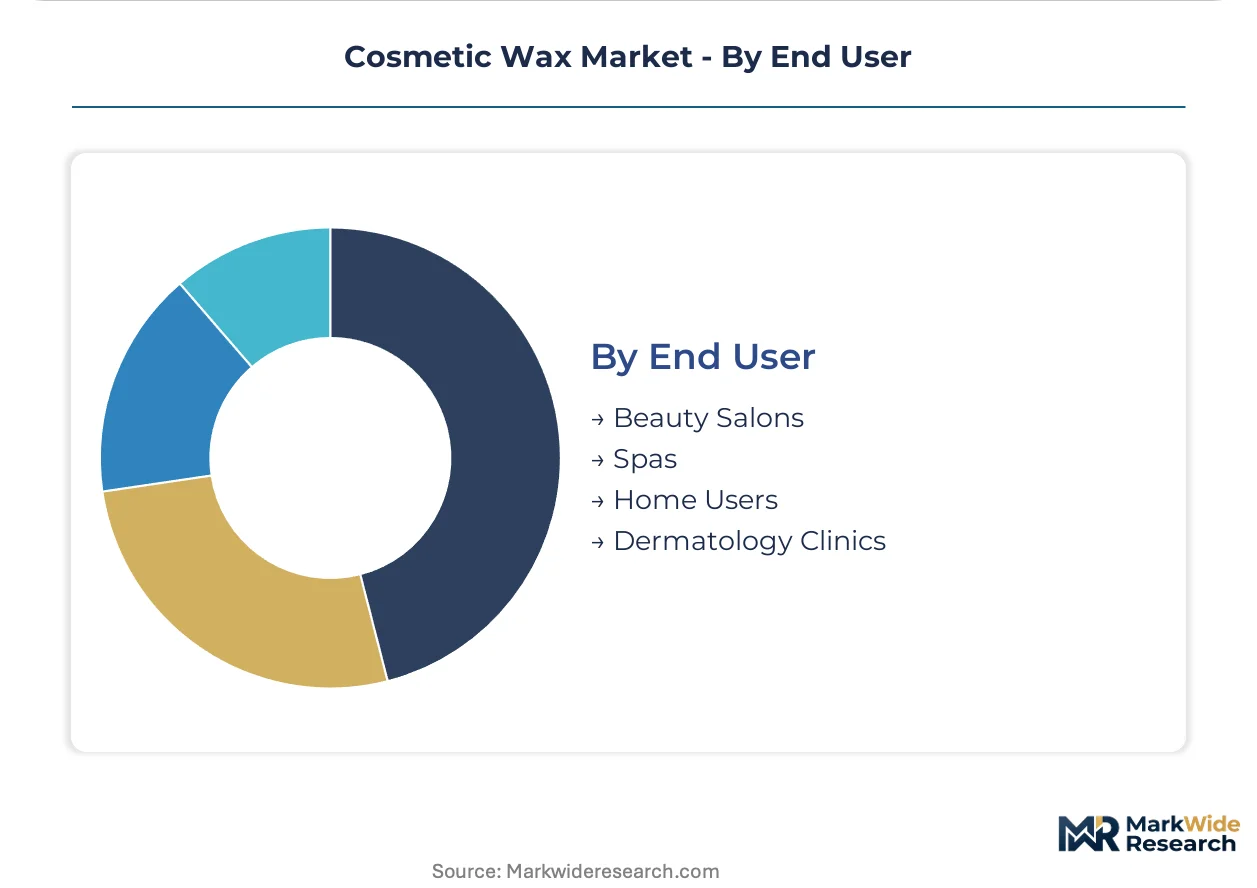
End User:
Customer type determines packaging scale, certification requirements, and support service intensity.
- Beauty Salons:High-frequency purchasers negotiate bulk supply agreements with technical training inclusion. Brazilian franchise networks standardize wax specifications across locations. State-level US licensing boards impose variable practitioner certification requirements.
- Home Users:Convenience-oriented buyers prioritize microwave-compatible formats and simplified instruction protocols. European consumers exhibit strongest preference for sugar-based, water-soluble alternatives. This segment is expanding most quickly in urban markets.
- Spas:Wellness-focused establishments integrate waxing within broader treatment menus.
- Dermatology Clinics:Medical settings demand hypoallergenic certifications and clinical safety documentation.
Beauty salons anchor professional-grade volume; home users represent the fastest-climbing demand pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical registration requirements and evolving FDA cosmetic ingredient standards are forcing simultaneous reformulation across synthetic and natural wax portfolios, compressing product development timelines while elevating compliance costs for multi-region suppliers.
United States
Professional salon networks in Florida and Texas sustain concentrated demand for hard wax block formats. FDA cosmetic labeling regulations and state-level professional licensing boards govern salon-grade product claims and practitioner application standards. Greater Los Angeles hosts a dense cluster of waxing franchise operations standardizing procurement specifications.
Brazil
A dense network of waxing salons in São Paulo and Rio de Janeiro sustains high per-capita consumption of professional-grade depilatory products. ANVISA mandates dermatological safety testing for imported formulations, creating compliance thresholds that filter lower-quality imports from Asian manufacturing hubs. Technicians in Belo Horizonte drive preference for block and granule formats enabling precise temperature control.
Germany
EMA cosmetic ingredient safety assessments and ECHA substance evaluation protocols constrain synthetic additive portfolios across European supply chains. REACH chemical registration requirements force removal of specific polymer modifiers previously standard in low-cost depilatory formulations. The Rhine-Ruhr industrial corridor concentrates refining capacity for pharmaceutical-grade wax derivatives.
France
Urban consumers in Paris and Lyon exhibit strong preference for sugar wax formulations as municipal waste regulations amplify clean-label purchasing criteria. ANSM oversees cosmetic ingredient safety assessments complementary to EMA protocols. The Provence-Alpes-Côte d'Azur region anchors Mediterranean-sourced botanical wax cultivation for premium spa channels.
India
Beauty salon expansion in Maharashtra and Karnataka is accelerating adoption of professional-grade depilatory products. CDSCO regulates cosmetic ingredient safety through the Drugs and Cosmetics Act, with state-level licensing boards governing practitioner standards. Mumbai's dense network of beauty training institutes standardizes waxing technique protocols across western India.
Cosmetic Wax Market Vendor Landscape
On the supply side, the industry is tiered between industrial-scale synthetic producers, vertically integrated natural wax cultivators, and specialized regional formulators. Three strategic archetypes dominate: polymer-grade specification suppliers competing on volume consistency, botanical-sourced specialists leveraging provenance claims, and private-label contract manufacturers enabling brand entry without capital-intensive refining infrastructure. Competitive moves concentrate on portfolio diversification into clean-label formulations and geographic expansion through distributor partnerships in high-growth salon markets.
Within the vertically integrated natural wax tier, Koster Keunen exemplifies upstream control over cultivation assets, while Rica Group occupies a position emphasizing Mediterranean ingredient provenance and ISO-certified processing protocols. Dow Inc. anchors the industrial-scale synthetic vector, competing on consistent polymer-grade specifications for high-volume salon distributors. These three represent distinct strategic postures: captive supply chain control, regional specialization, and scale-driven standardization.
| Leading Market Players |
|---|
| Cirepil |
| Italwax |
| Dow Inc. |
| Cosmewax |
| GiGi |
| Koster Keunen |
| Rica Group |
| Depileve |
| Starpil Wax |
| Others |
Supply Flow & Price Mechanics
Petroleum feedstock volatility determines both pricing tier spreads and supply chain shape across cosmetic wax manufacturing, compressing margins for synthetic producers while accelerating backward integration into captive botanical cultivation among premium-positioned competitors.
Pricing Analysis
Certification level (ISO/FDA-grade) creates the primary spread between professional salon-grade and retail consumer tiers. Three-tier pricing structure across premium, standard, and economy levels reflects dermatological testing intensity, with ANVISA-compliant imports commanding substantial premiums over untested alternatives. Cost compression in economy synthetic waxes is intensifying because polymer-grade hydrocarbon input costs fluctuate with crude oil benchmarks. Home users exhibit highest price sensitivity, while Brazilian franchise salon networks prioritize thermal consistency over per-unit cost.
Supply Chain Analysis
Export-control restrictions on pharmaceutical-grade refining equipment limit capacity expansion in emerging manufacturing hubs. Supply concentrates in the United States, Germany, and Brazil, with raw material dependencies spanning petroleum distillates, Mediterranean botanicals, and refined sucrose feedstocks. Single-source vulnerability sits with polymer-grade hydrocarbon suppliers serving Dow Inc.'s industrial-scale output. Distribution runs through specialized salon supply distributors in professional channels and mass retail in consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cosmetic wax demand sits in early-cycle expansion as professional salon penetration accelerates in underserved metropolitan clusters and home-use convenience formats capture first-time buyers previously deterred by technique complexity.
For Market Incumbents: Pre-empt sugar wax substitution threats by accelerating biopolymer certification alignment before EU microplastic prohibitions formalize. Deepen backward integration into Mediterranean botanical cultivation to secure traceability claims that Rica Group has exploited. Fortify Brazilian distributor relationships against private-label contract manufacturers enabling smaller brand entry without capital-intensive refining infrastructure. For New Entrants and Emerging Players: Establish a beachhead in Indian metropolitan salon networks where CDSCO regulatory frameworks are stabilizing but technician certification standardization remains fragmented. Target Maharashtra and Karnataka beauty training institutes as channel anchors for professional-grade block wax distribution. Lead with microwave-compatible sugar wax formats that bypass the temperature-control complexity barrier for home users. For Investors and Strategic Acquirers: REACH chemical registration deadlines reshape the acquisition landscape by elevating compliance infrastructure value above formulation IP alone. Five-to-ten year viability favors targets with validated ANVISA and EMA dossiers rather than pure-play natural wax cultivators lacking regulatory documentation. Monitor ECHA substance evaluation protocols as the signal for forced reformulation waves that will strand non-compliant synthetic portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Certification Alignment | Early REACH compliance secures market access before synthetic wax prohibitions phase in across European supply chains. |
| Backward Integration into Botanical Cultivation | Captive supply of Mediterranean beeswax and sugar cane feedstocks locks in provenance claims for premium spa channels. |
| Roll-on Format Manufacturing Scale-Up | Cartridge system expansion captures margin migration from salon-dependent to at-home depilation purchasing patterns. |
| ANVISA Regulatory Dossier Investment | Dermatological safety documentation creates import filtration barriers that systematically exclude lower-quality Asian competitors. |
| Temperature-Controlled Dispensing Partnerships | Precision-heated cartridge alliances with franchise networks standardize service outcomes while reducing technician training costs. |
Methodological Framework
Desk research of customs trade databases, ECHA substance registration filings, and ANVISA import approval records preceded structured interviews with salon supply distributors, wax formulation chemists, professional licensing board administrators, and franchise procurement managers. Primary fieldwork across São Paulo, Mumbai, and the Rhine-Ruhr corridor validated secondary estimates of block wax consumption patterns and thermal specification requirements. Bottom-up volume builds from salon census data and per-location consumption rates triangulated against top-down chemical industry production disclosures.
Fixed assumptions held regulatory prohibition timelines and petroleum feedstock cost trajectories constant across the projection horizon, while segment-level CAGRs incorporated variable penetration rates for sugar wax substitution and roll-on format adoption. Segmentation dimensions modeled include product chemistry, application method, end-user channel, and regional regulatory cluster. Forecast inputs drew from technician certification velocity in Indian states and municipal waste regulation enforcement intensity in urban European markets.
Sensitivities concentrate around EU microplastic restriction implementation pacing and Brazilian real exchange rate volatility affecting import cost structures. Forecasts reflect documented assumptions regarding salon network expansion rates and clean-label formulation preference shifts. Material changes in REACH substance evaluation outcomes or ANVISA testing protocol revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Facial Massager Market
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Global Electric Head and Scalp Massager Market
Beauty & Personal Care
Colombia Cosmetics Products Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Natural Cosmetics Market