
 Sales Gamification Software Market | 2026-2036
Sales Gamification Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sales Gamification Software Market Analytics
GDPR Article 22 is shifting the cost-of-entry calculus for vendors deploying automated decision-making in sales leaderboards, forcing engineering teams to build explainability layers and consent workflows into core architectures. Microsoft Corporation leverages its Azure compliance infrastructure to anchor enterprise trust in regulated European deployments. SAP SE competes through deep ERP integration that sustains renewal rates among industrial clients with complex commission structures.
Sales gamification software refers to enterprise applications that apply game mechanics—point systems, badges, leaderboards, and real-time feedback loops—to revenue team motivation and performance optimization, typically delivered through API-connected platforms that ingest CRM pipeline data and output behavioral nudges. The cloud-based deployment model dominates current bookings as IT procurement teams prioritize zero-footprint implementations with SOC 2 Type II certification. Employee engagement solutions within the solution category are capturing disproportionate expansion spend as CHROs link retention metrics to interactive coaching dashboards.
The EU AI Act and GDPR collectively constrain how European vendors algorithmically rank personnel, while the US FTC monitors claims about productivity gains from gamified systems for potential deceptive advertising violations. HIPAA considerations extend to healthcare end users where patient-facing sales teams require audit trails for all performance data. Stakeholders must weigh regulatory exposure against velocity of feature deployment when selecting geographic rollout sequencing.
Market Dynamics
Enterprise incentive modernization is compressing sales gamification procurement cycles as CHROs demand native CRM connectivity and real-time behavioral analytics without IT infrastructure overhead.
Growth Catalysts
- EU AI Act compliance tooling:Vendors embedding explainability layers into algorithmic scoring systems are capturing renewal premiums from European financial services institutions.
- Mid-market SaaS procurement:United States buyers with 200-2,000 employees are consolidating point solutions into unified engagement platforms with pre-built Salesforce and HubSpot connectors.
- Behavioral nudge science:Advances in micro-incentive timing and loss-aversion framing are improving quota attainment metrics in enterprise software sales teams.
Market Restraints
- GDPR Article 22 friction:Automated decision-making restrictions in European deployments force dual-track product architectures that inflate engineering overhead.
- API dependency concentration:Salesforce platform policy changes or rate-limiting adjustments can disrupt real-time leaderboard functionality for connected deployments.
- Legacy ERP integration costs:SAP ECC and Oracle E-Business Suite environments require custom middleware that extends implementation timelines.
Strategic Opportunities
- Healthcare vertical expansion:HIPAA-compliant audit trails for patient-facing sales teams remain underdeveloped relative to financial services saturation.
- Generative AI coaching convergence:Large language models paired with performance data are enabling dynamic feedback loops that static badge systems cannot replicate.
- CSRD reporting integration:European sustainability disclosure mandates create openings for gamification platforms that track and visualize ESG-linked sales behaviors.
Industry Challenges
- Behavioral data science talent scarcity:Vendors struggle to hire practitioners who combine machine learning expertise with organizational psychology credentials.
- Multi-tenant security certification delays:SOC 2 Type II and ISO 27001 audit cycles stretch 6-9 months, slowing enterprise deal velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sales Gamification Software Market |
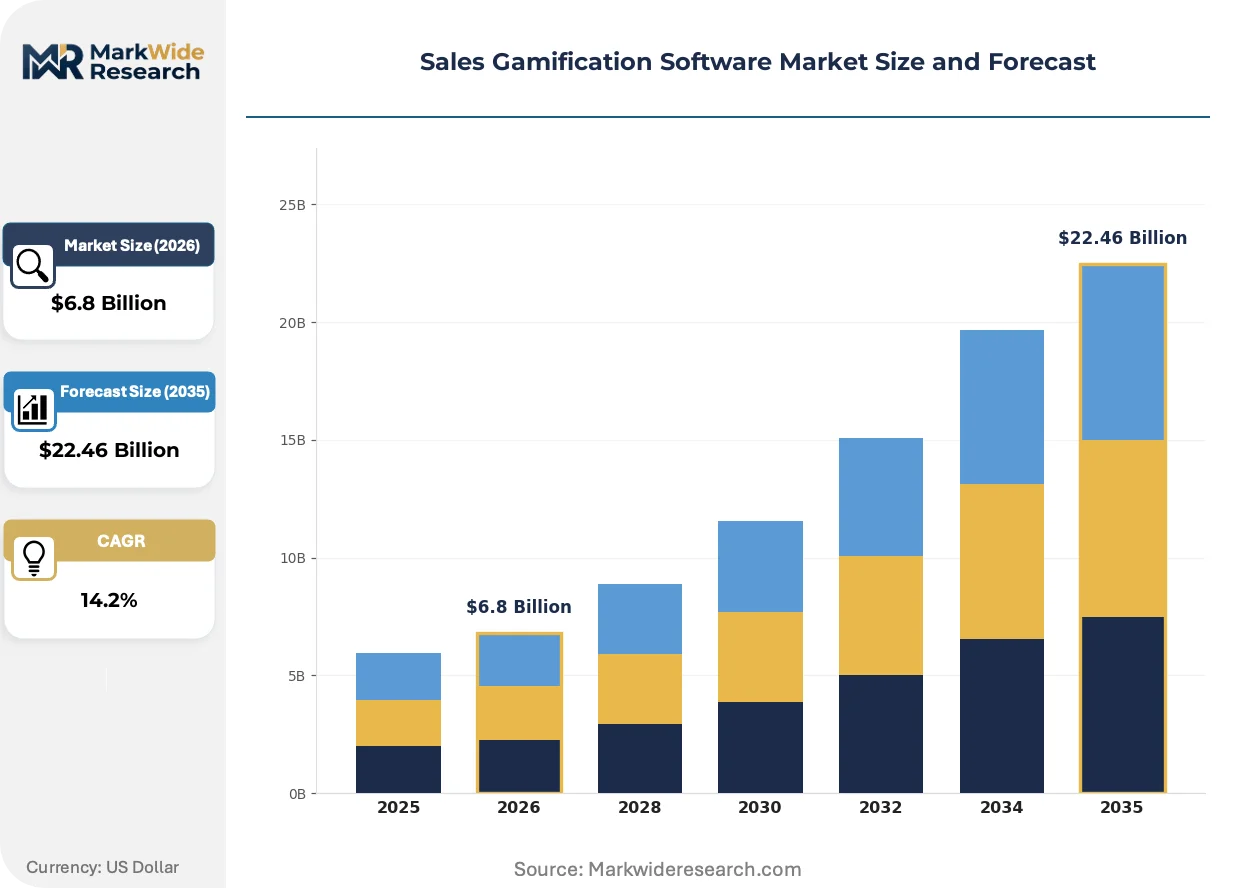
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile End User: Retail, Education, Financial Services, Healthcare Solution: Employee Engagement, Performance Management, Training Tools, Rewards Program Deployment: Single-Tenant, Multi-Tenant, Private Cloud, Public Cloud |
| Companies Covered | Ambition, Zoho Corporation, Raydiant, BI WORLDWIDE, Microsoft Corporation, Agile CRM, SAP SE, Spinify, SalesScreen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sales Gamification Software Market Evolving Landscape
Real-time predictive scoring and adaptive incentive calibration are displacing static quarterly contests as the dominant motivational architecture in revenue operations.
Machine learning models trained on historical win/loss patterns are automating personalized challenge generation and reward timing optimization. Enterprise SaaS vendors with 500+ seat deployments are adopting these systems fastest, typically replacing manual sales operations analyst functions. The technology is automating the translation of CRM pipeline signals into individualized behavioral interventions that previously required manager judgment.
The EU AI Act's risk classification framework for algorithmic personnel management is forcing architectural redesigns across European deployments. High-risk system designations trigger mandatory human-in-the-loop review requirements and documentation burdens. Financial services institutions in Germany and France are responding by procuring explainability modules as separate line items rather than accepting black-box vendor defaults.
Subscription pricing for engagement modules is displacing perpetual licensing in mid-market procurement. CHROs now favor annual contracts with usage-based tiers over upfront capital commitments. This pattern is most visible in United States technology and business services verticals where finance teams prioritize OpEx treatment for software spend.
Sales Gamification Software Market Segmentation
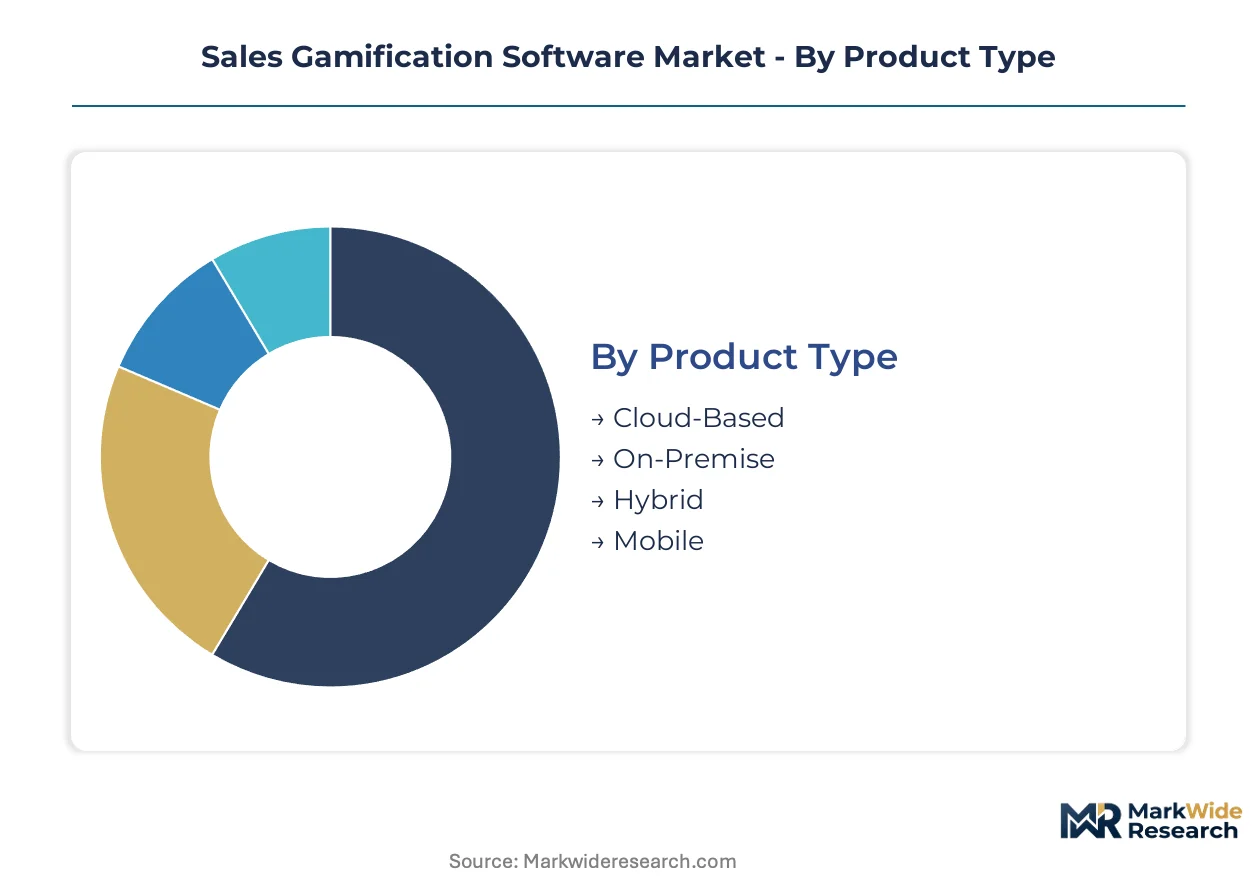
Segmentation in sales gamification software reveals how architectural choices determine integration complexity and regulatory exposure. Procurement patterns diver sharply between organizations prioritizing zero-footprint cloud deployments and those requiring air-gapped on-premise systems for sensitive personnel data.
Product Type:
Standalone cloud platforms dominate mid-market procurement cycles, while embedded modules within existing CRM stacks serve enterprise accounts with complex compliance requirements.
- Cloud-Based:Native SaaS architectures with SOC 2 Type II certification ingest CRM pipeline data through REST APIs, delivering real-time leaderboards without client-side infrastructure. United States technology vendors with 200-2,000 employees drive disproportionate bookings here, prioritizing OpEx treatment and rapid deployment.
- On-Premise:Air-gapped installations within client data centers satisfy GDPR Article 22 constraints and HIPAA audit trail mandates for healthcare and European financial services institutions. German and French banks procuring these systems demand explainability modules as separate line items rather than accepting vendor black-box defaults.
- Hybrid:Split architectures process sensitive personnel data on-premise while offloading analytics workloads to cloud environments.
- Mobile:Native iOS and Android applications extend gamification to field sales teams requiring offline functionality.
Cloud-Based deployments lead volumes today; Mobile is gaining share fastest among distributed workforces.
End User:
Vertical specialization determines feature roadmaps, with financial services demanding algorithmic transparency and healthcare requiring patient-data isolation.
- Retail:High-volume, low-margin sales environments leverage micro-incentive timing and loss-aversion framing to improve conversion rates across seasonal hiring cycles.
- Education:Enrollment management teams apply behavioral nudges to admissions pipelines, with demand concentrating in United States private universities facing demographic headwinds.
- Financial Services:EU AI Act compliance tooling and explainability layers anchor procurement decisions at German and French institutions modernizing incentive structures. The European Banking Authority's scrutiny of algorithmic personnel scoring drives premium pricing for audit-ready systems.
- Healthcare:Patient-facing sales teams require HIPAA-compliant audit trails that remain underdeveloped relative to financial services saturation, creating whitespace for specialized vendors.
Financial Services leads volumes today; Healthcare is expanding most quickly as ESG-linked sales behavior tracking aligns with CSRD reporting mandates.
Solution:
Module bundling patterns reveal whether CHROs prioritize retention metrics or quota attainment optimization in procurement decisions.
- Employee Engagement:Interactive coaching dashboards and social recognition systems capture disproportionate expansion spend as CHROs link retention metrics to platform investments.
- Performance Management:Machine learning models trained on historical win/loss patterns automate personalized challenge generation, displacing manual sales operations analyst functions at enterprise SaaS vendors with 500+ seat deployments.
- Training Tools:Microlearning modules with gamified completion tracking address onboarding velocity for high-churn sales roles.
- Rewards Program:Points-based redemption systems integrate with corporate benefit platforms and external merchant networks.
Performance Management leads volumes today; Employee Engagement is climbing the fastest as retention pressures intensify.
Deployment:
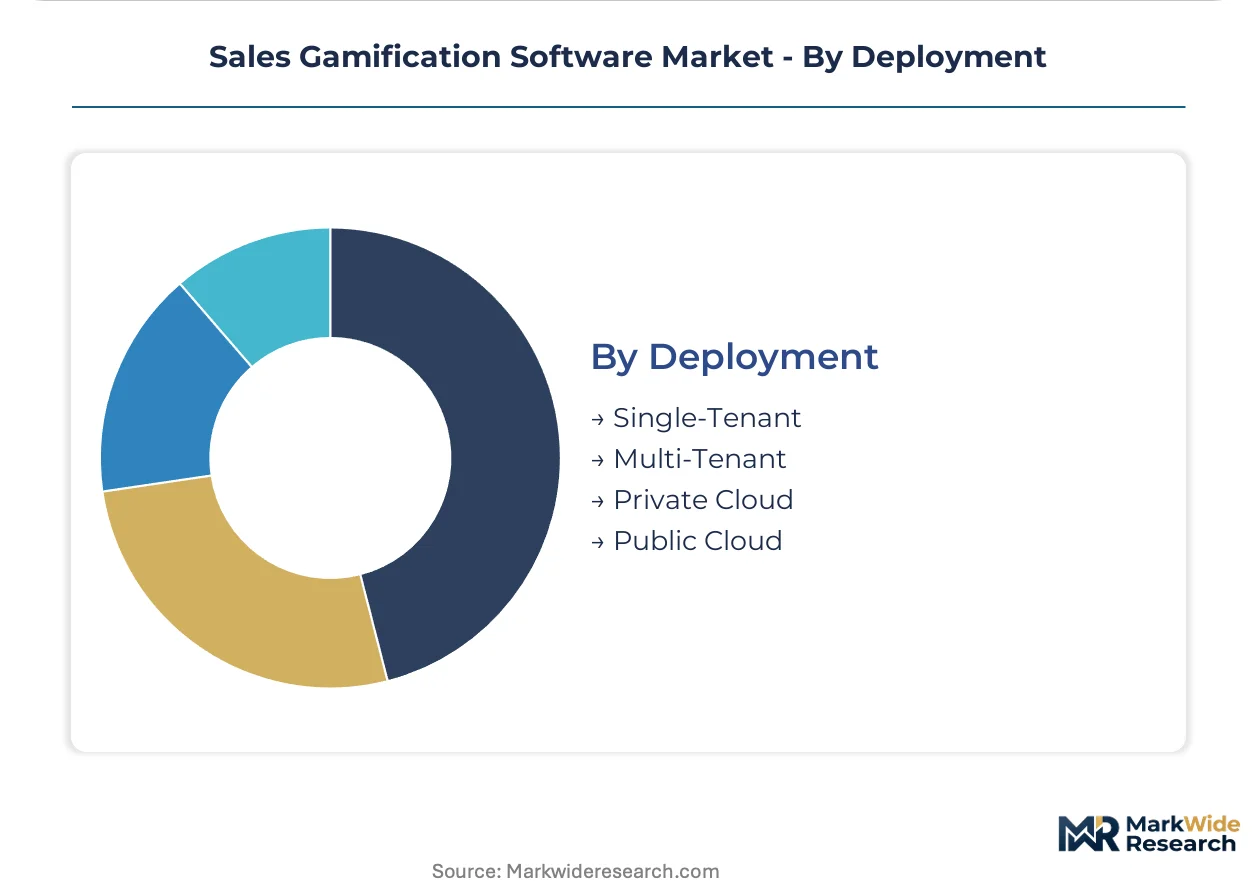
Tenancy models trade off operational flexibility against data isolation requirements, with certification timelines stretching 6-9 months for multi-tenant security validations.
- Multi-Tenant:Shared infrastructure with logical data separation achieves economies of scale that support usage-based pricing tiers preferred by United States mid-market buyers.
- Single-Tenant:Dedicated instances satisfy stringent data residency requirements at German automotive and industrial clients with complex SAP ECC commission structures.
- Private Cloud:Managed deployments within client-controlled VPC environments balance isolation with reduced infrastructure overhead.
- Public Cloud:Shared AWS, Azure, or GCP infrastructure delivers lowest per-seat costs for price-sensitive procurement teams.
Multi-Tenant leads volumes today; Single-Tenant is gaining share fastest among regulated European institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Revenue operations talent clusters in major metropolitan areas anchor demand for sales gamification platforms, with financial services and enterprise SaaS concentrations driving procurement intensity across distinct regulatory environments.
United States
Mid-market SaaS buyers with 200-2,000 employees consolidate point solutions into unified engagement platforms, prioritizing native Salesforce and HubSpot connectivity. FTC scrutiny of productivity gain claims shapes vendor marketing compliance. San Francisco Bay Area and Greater Boston technology clusters drive fastest adoption of machine learning-powered coaching modules.
Germany
Industrial clients with complex SAP ECC commission structures demand single-tenant deployments satisfying stringent data residency requirements. EU AI Act high-risk system designations trigger mandatory human-in-the-loop review for algorithmic personnel scoring. Frankfurt and Munich financial centers procure explainability modules as separate line items rather than accepting black-box defaults.
United Kingdom
Enterprise SaaS vendors with 500+ seat deployments automate personalized challenge generation to displace manual sales operations functions. GDPR Article 22 constraints force explainability layers into core product architectures. London fintech and enterprise software clusters anchor European expansion for vendors seeking English-language beachheads.
France
Financial services institutions modernizing incentive structures under European Banking Authority scrutiny drive premium pricing for audit-ready systems. CNIL enforcement of automated decision-making restrictions elevates consent workflow requirements. Paris banking headquarters and Lyon industrial zones concentrate procurement decision-making for regulated deployments.
India
Technology services exporters and domestic SaaS startups adopt cloud-based engagement platforms for sales team retention amid talent mobility pressures. RBI guidelines on digital lending sales practices extend to performance monitoring tools. Bangalore and Hyderabad technology corridors generate fastest-growing demand for mobile-native field sales functionality.
Sales Gamification Software Market Competitive Landscape
The competitive structure tilts toward platform-integrated specialists with deep CRM connectivity. Mid-market procurement consolidation favors vendors offering pre-built connectors over standalone point solutions. Three archetypes dominate: cloud-native SaaS platforms with SOC 2 certification, ERP-embedded modules leveraging existing enterprise relationships, and vertical specialists targeting HIPAA or EU AI Act compliance requirements. Competitive moves center on native connector expansion and explainability module development for regulated European deployments.
Within the platform-integrated tier, Microsoft Corporation and SAP SE exemplify divergent anchoring strategies, with the former leveraging Azure compliance infrastructure and the latter competing through deep ERP integration sustaining renewal rates among industrial clients. Zoho Corporation occupies a position among mid-market-focused providers with bundled productivity suite advantages. These three represent distinct competitive vectors: cloud infrastructure trust, enterprise system entrenchment, and suite-based pricing flexibility.
| Leading Market Players |
|---|
| Ambition |
| Zoho Corporation |
| Raydiant |
| BI WORLDWIDE |
| Microsoft Corporation |
| Agile CRM |
| SAP SE |
| Spinify |
| SalesScreen |
| Others |
Value Network & Pricing Analysis
Cloud infrastructure spot pricing indices cascade through SaaS vendor cost structures, compressing mid-market subscription tiers while enterprise buyers absorb premium single-tenant deployments. This cost transmission splits procurement patterns between OpEx-sensitive United States technology buyers and compliance-driven European financial institutions.
Pricing Analysis
Bundled engagement platforms with pre-built Salesforce connectors command 40-60% premiums over unbundled point solutions. Three-tier pricing structure across premium, standard, and economy levels differentiates by SOC 2 certification grade and API call volume thresholds. Pricing pressure stems from mid-market consolidation into unified suites rather than best-of-breed point solutions. CHROs at 200-2,000 employee organizations exhibit highest price sensitivity; German automotive clients with SAP ECC complexity show lowest.
Supply Chain Analysis
Logistics and freight cost volatility in hyperscaler data center equipment feeds through to cloud deployment pricing, particularly for EU data residency requirements. Engineering talent concentrates in United States, India, and Germany, with behavioral data science practitioners scarce across all three markets. The supply chain draws from API-dependent CRM platforms, creating single-source vulnerability to Salesforce policy changes. Distribution runs through direct enterprise sales teams and systems integrators embedding modules into larger digital transformation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sales gamification software functions as a stable compounder anchored by persistent enterprise incentive modernization cycles. CHROs consistently allocate expansion budget to retention-linked engagement tools regardless of macroeconomic volatility.
For Market Incumbents: Extend native connector portfolios beyond Salesforce and HubSpot into emerging CRM platforms like Pipedrive and Freshworks. Defend against generative AI coaching entrants by embedding explainability layers that preempt EU AI Act compliance reviews. Vertical integration into behavioral data science talent pipelines sustains differentiation as practitioner scarcity intensifies.
For New Entrants and Emerging Players: Launch via vertical-specific channel partnerships targeting HIPAA-compliant healthcare deployments where audit trail capabilities remain underdeveloped. White-space concentrates in patient-facing sales teams at United States health systems and ESG-linked behavior tracking for European CSRD reporting. Go-to-market angle: pre-built sustainability disclosure integrations that incumbent horizontal platforms lack.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertical specialists possessing regulatory moats in EU AI Act or HIPAA compliance. Five-to-ten year viability favors vendors with single-tenant deployment capabilities serving German industrial clients. Signal to watch: European Banking Authority enforcement actions against black-box algorithmic scoring systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Salesforce connectors reduce implementation friction for mid-market SaaS buyers consolidating point solutions. |
| Explainability Module Development | EU AI Act high-risk system designations force architectural redesigns that vendors can monetize as premium add-ons. |
| Vertical Expansion | Healthcare HIPAA compliance creates whitespace for specialized audit-trail capabilities absent in financial services-saturated incumbents. |
| Generative AI Convergence | Large language model coaching displaces static badge systems in enterprise SaaS vendors with 500+ seat deployments. |
| Geographic Localization | Single-tenant German deployments satisfy data residency requirements that multi-tenant architectures cannot meet. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with CHROs, sales operations leaders, IT procurement officers, and CRM integration specialists informed demand-side assumptions. Secondary sources include SEC filings of publicly traded SaaS vendors, EU regulatory documentation on AI Act implementation, and healthcare compliance databases. Bottom-up sizing of vendor bookings triangulates against top-down enterprise software spend allocation estimates.
Rate-of-change decomposition separates expansion revenue from new logo acquisition across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated to historical SaaS platform penetration patterns. Forecast inputs incorporate EU AI Act implementation timelines and mid-market SaaS procurement cycle compression observed in United States technology corridors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU AI Act enforcement or Salesforce platform policy disruption. Forecasts reflect documented assumptions about CRM connectivity standardization and behavioral science talent availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Software Defined Broadcasting Market
Software & Services
Lighting Control Software Market
Software & Services
Theatrical Distribution Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Sales Compensation Software Market
Software & Services
Auto Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
Global Disclosure Management Software Market
Software & Services
Global Open API Market
Software & Services
Drone Mapping Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Global Ad Server Software Market
Software & Services
Family Law Software Market
Software & Services
Independent Software Vendors (Isvs) Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market