
 Royalty Management Software and Services Market | 2026-2036
Royalty Management Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Royalty Management Software and Services Market Analytics
Enterprise-grade audit precision is unwinding legacy spreadsheet dependency across rights-holder operations. FADEL leverages cloud-native architecture to anchor multi-territory licensing workflows for media conglomerates. LicenseQ specializes in blockchain-verified provenance tracking, while IPwe competes through patent-centric royalty modules that extend into litigation analytics.
Royalty management software and services comprise digital platforms that automate contractual obligation tracking, usage monitoring, and payment distribution across intellectual property portfolios, typically processing millions of micro-transactions with sub-penny accuracy thresholds. These systems integrate with content delivery networks, financial ledgers, and legal databases to ensure rights holders receive contracted compensation. Cloud-based solutions dominate new procurement cycles as media companies and licensing agencies demand elastic capacity during quarterly reporting spikes. Consulting services capture disproportionate margin pools where custom contract interpretation requires embedded legal expertise, while traditional on-premise deployments retain footholds among authors and smaller publishers with rigid data-locality requirements.
FCC content identification mandates and EU GDPR data-processing standards shape platform architecture decisions, forcing vendors to maintain jurisdiction-specific audit trails. The US Copyright Office's modernization push and EMA-aligned transparency frameworks in European media markets further tighten compliance requirements. Stakeholders must evaluate whether hybrid deployment models or managed services better reconcile divergent regulatory timelines across their rights portfolios.
Market Dynamics
Micro-transaction volume from streaming platforms is fragmenting royalty calculation workflows, forcing rights holders to abandon batch-processing architectures in favor of real-time ledger systems that can reconcile sub-penny payments across millions of daily events.
Growth Catalysts
- EU AI Act compliance mandates:Automated rights-tracking platforms now embed algorithmic transparency modules to satisfy audit requirements for AI-driven content identification systems deployed across European territories.
- Music publishing consolidation:Major publishers are unifying fragmented catalog databases onto cloud-native platforms to streamline multi-territory licensing negotiations and reduce manual reconciliation overhead.
- Blockchain verification protocols:Distributed ledger technology is anchoring provenance records for digital assets, creating immutable audit trails that reduce disputes between rights holders and streaming platforms.
Market Restraints
- Data localization requirements:GDPR-mandated data residency rules force vendors to maintain separate infrastructure stacks across EU member states, elevating operational complexity and compliance costs.
- Legacy system integration friction:Decades-old contract databases in ASCII and proprietary formats resist standard API connections, requiring expensive middleware development for enterprise deployments.
- Specialized legal talent scarcity:The intersection of intellectual property law and software engineering commands premium compensation, constraining vendor scaling capacity.
Strategic Opportunities
- Latin American streaming expansion:Underpenetrated markets in Brazil and Mexico present whitespace for localized royalty platforms as regional streaming subscriber bases multiply.
- Podcast and audiobook verticals:Emerging spoken-word content categories lack standardized rights frameworks, creating first-mover advantage for platforms that establish contract templates.
- ISO 27001 certification differentiation:Information security credentials are becoming table stakes for procurement by major media conglomerates, favoring vendors with established compliance infrastructure.
Industry Challenges
- Cross-border tax treaty complexity:Withholding obligation calculations across bilateral agreements require embedded tax expertise that most software vendors lack.
- Real-time reconciliation latency:Streaming platforms' 45-day payment cycles clash with rights holders' demand for daily visibility, creating tension in platform design priorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Royalty Management Software and Services Market |
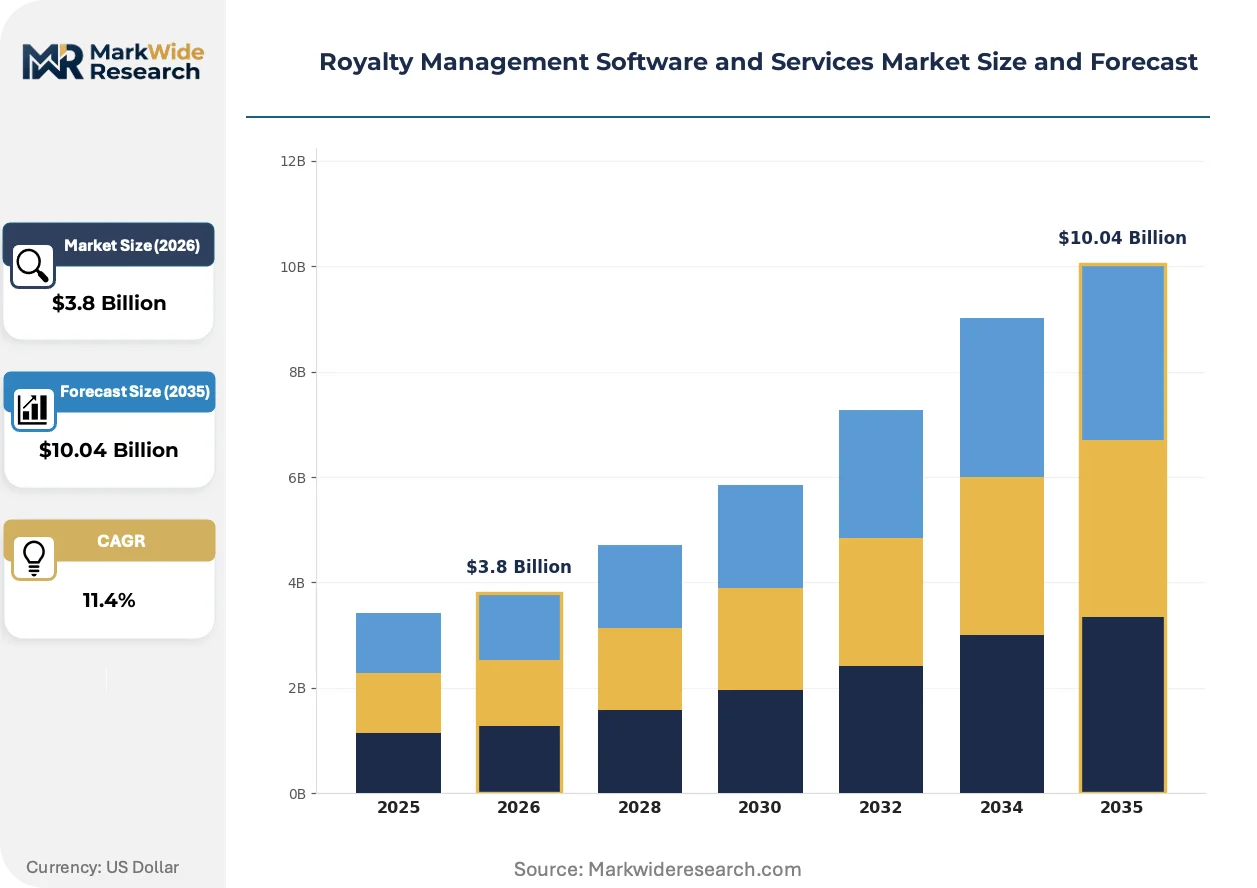
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Software, Cloud-Based Solutions, Integrated Platforms, Consulting Services End User: Media Companies, Music Publishers, Authors, Licensing Agencies Deployment: On-Premise, Cloud, Hybrid, Managed Services Service Type: Support Services, Custom Development, Training, Data Analytics |
| Companies Covered | FADEL, RevTrax, Tigunia, Rightscorp, LicenseQ, Integrail, IPwe, Auditron, Evello, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Royalty Management Software and Services Market Evolving Landscape
Cloud-native architectures are displacing on-premise deployments as media companies demand elastic capacity during quarterly reporting spikes, while regulatory pressure on algorithmic transparency is reshaping platform design requirements.
Machine learning-based content identification is fragmenting traditional fingerprinting methodologies. Audio recognition algorithms now process acoustic signatures across streaming, broadcast, and user-generated content platforms. Mid-tier publishers are adopting these tools to audit platform-reported usage against actual consumption patterns. The technology is fragmenting incumbent vendors' hold on enterprise accounts by democratizing access to detection capabilities previously reserved for major labels.
The EU AI Act's risk-classification framework is mandating explainability standards for automated rights-management decisions. Vendors must now document training data provenance and decision logic for content-matching algorithms. European music publishers are most affected, requiring platform vendors to retrofit audit trails that satisfy national data protection authorities. Compliance investments are compressing margins for smaller software providers.
Buyers are unbundling implementation services from software licenses, treating royalty platform deployment as specialized consulting engagements rather than turnkey purchases. Media companies now retain boutique legal-technology firms to configure contract interpretation rules before selecting underlying platforms. This pattern is most visible in the United States, where complex fractional-ownership structures in recorded music catalogs demand bespoke workflow design.
Royalty Management Software and Services Market Segmentation
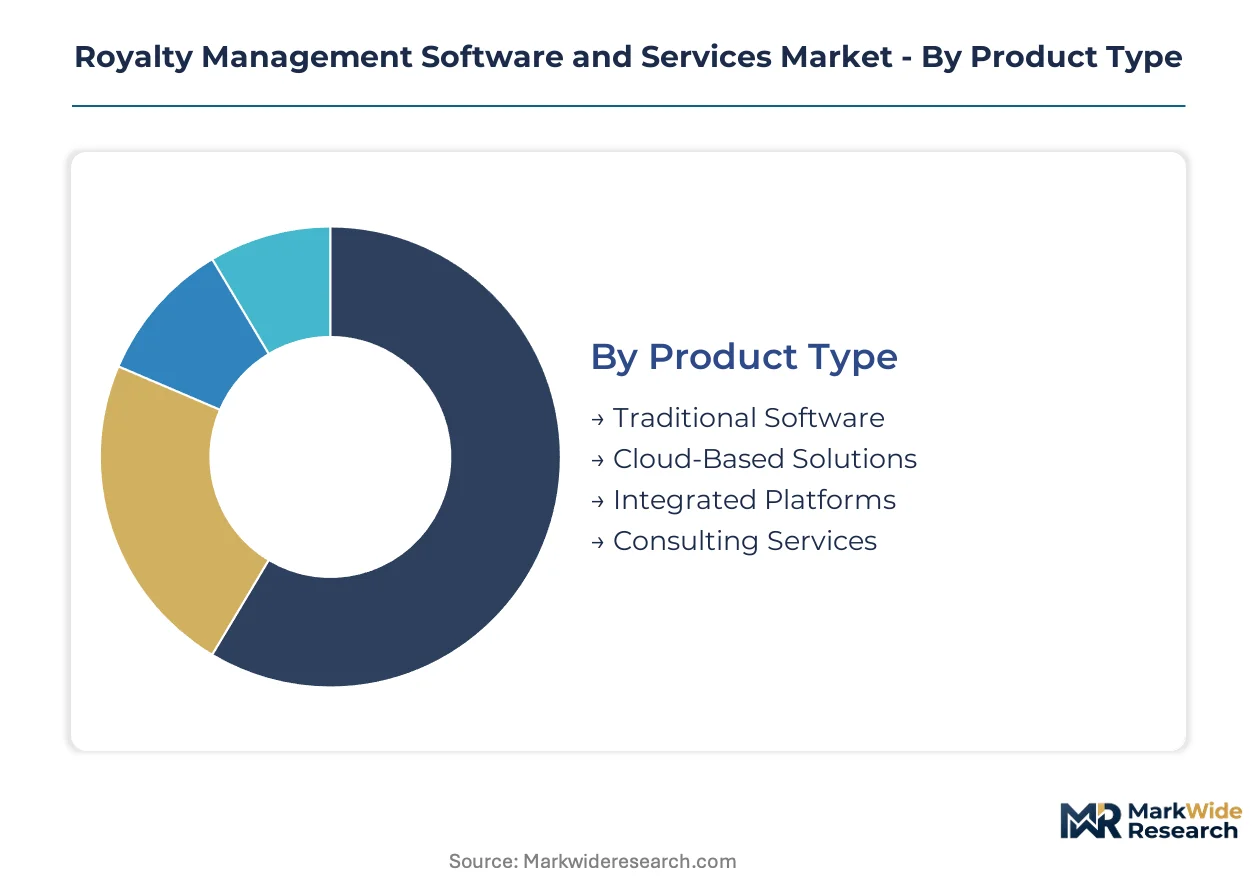
Royalty management procurement splits sharply between legacy infrastructure preservation and cloud-native replacement cycles. Rights holders weigh audit precision against data sovereignty constraints when selecting platform architectures across these four segmentation dimensions.
Product Type:
Cloud-native substitutes threaten traditional software incumbents as media conglomerates abandon batch-processing architectures for elastic capacity during quarterly reporting spikes.
- Traditional Software:Perpetual-license platforms installed on local servers process royalty calculations through scheduled batch jobs. Music publishers in Germany and France retain these systems to satisfy CNIL and BfDI data-locality interpretations. Compliance retrofit costs compress margins as vendors maintain parallel codebases for jurisdiction-specific audit trails.
- Cloud-Based Solutions:SaaS architectures auto-scale compute resources to reconcile millions of micro-transactions from streaming platforms. US media companies dominate procurement, driven by FCC content identification mandates and the Copyright Office's modernization push. Elastic capacity eliminates capital expenditure spikes during catalog acquisition periods.
- Integrated Platforms:Unified stacks embed contract management, usage monitoring, and payment distribution in single vendor relationships.
- Consulting Services:Embedded legal expertise configures custom contract interpretation rules before platform deployment.
Cloud-based solutions retain volume leadership; consulting services hold the steepest expansion curve.
End User:
Customer-type concentration varies by content category complexity and fractional ownership structures.
- Media Companies:Conglomerates operating film, television, and music assets demand multi-territory licensing workflows with real-time ledger reconciliation. US studios lead procurement volume, pressured by intellectual property litigation discovery requirements. These buyers unbundle implementation from licensing, treating deployment as specialized consulting engagements.
- Music Publishers:Catalog owners consolidate fragmented databases onto unified platforms to streamline multi-territory negotiations. EU AI Act compliance mandates force algorithmic transparency module adoption for content identification systems. Major publishers in the United Kingdom and Netherlands drive standardization efforts.
- Authors:Individual rights holders prioritize cost efficiency over feature depth, often retaining spreadsheet-dependent workflows.
- Licensing Agencies:Intermediaries managing third-party rights require audit-ready infrastructure to satisfy platform transparency demands.
Media companies retain volume leadership; music publishers hold the steepest expansion curve.
Deployment:
Infrastructure location decisions hinge on GDPR data residency rules and bilateral tax treaty complexity.
- On-Premise:Local server installations satisfy rigid data-locality requirements for authors and smaller publishers. German and French rights holders favor this model under national data protection authority guidance. Capital intensity limits adoption to organizations with dedicated IT operations.
- Cloud:Third-party hosted infrastructure delivers elastic capacity without hardware procurement cycles. US media companies dominate adoption, leveraging domestic cloud regions to minimize cross-border data transfer compliance burdens. Subscription pricing aligns costs with transaction volume fluctuations.
- Hybrid:Split architectures retain sensitive contract data on-premise while offloading compute-intensive reconciliation to cloud resources.
- Managed Services:Vendor-operated infrastructure shifts operational responsibility to specialized providers.
Cloud deployment retains volume leadership; hybrid configurations hold the steepest expansion curve.
Service Type:
Margin capture concentrates where specialized legal-technology expertise intersects with platform configuration.
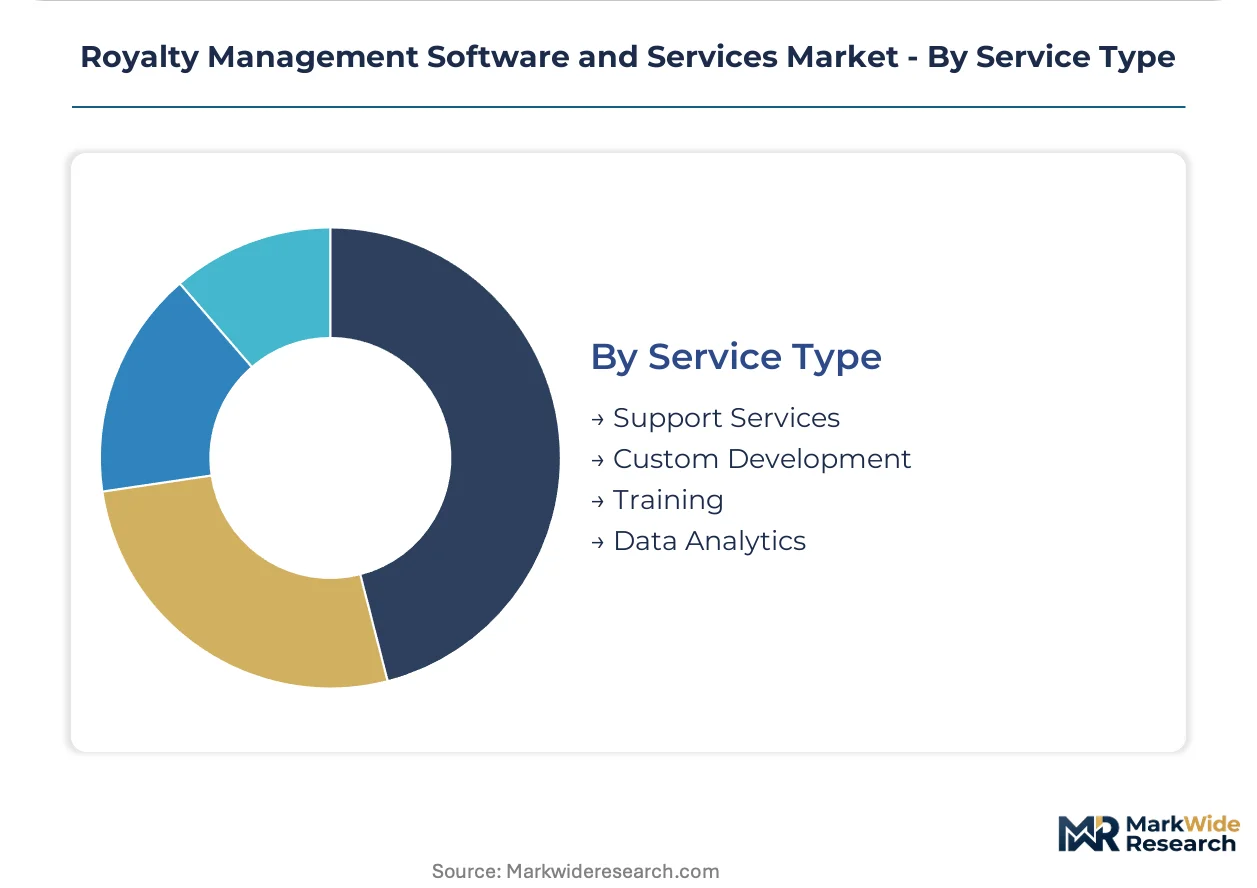
- Support Services:Ongoing technical assistance maintains platform uptime during critical reporting periods. US media companies demand 24/7 coverage aligned with quarterly financial close cycles. Service level agreements specify sub-hour response times for payment processing disruptions.
- Custom Development:Bespoke workflow creation addresses fractional-ownership structures in recorded music catalogs. Boutique legal-technology firms in New York and Los Angeles configure contract interpretation rules before underlying platform selection. These engagements capture disproportionate margin pools relative to software licensing.
- Training:Knowledge transfer programs reduce dependency on vendor personnel for routine configuration changes.
- Data Analytics:Usage pattern analysis identifies audit discrepancies between platform-reported and actual consumption.
Support services retain volume leadership; custom development holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software exports from the United States flow into European media conglomerates and Asian streaming platforms, establishing transatlantic and transpacific corridors as the dominant trade routes for royalty management infrastructure.
United States
FCC content identification mandates and Copyright Office modernization initiatives drive procurement volume among Hollywood studios and Nashville music publishers. US media companies unbundle implementation from licensing, treating deployment as specialized consulting engagements. New York and Los Angeles anchor the boutique legal-technology firms that configure contract interpretation rules.
Germany
BfDI data-locality interpretations and rigid data sovereignty requirements preserve on-premise installations among Frankfurt and Munich rights holders. German music publishers retain perpetual-license platforms to satisfy national data protection authority guidance. Compliance retrofit costs compress vendor margins as parallel codebases for jurisdiction-specific audit trails proliferate.
United Kingdom
Major publishers in London and Manchester drive standardization efforts for multi-territory catalog databases. Post-Brexit regulatory divergence complicates cross-border data transfers with EU member states. The UK Information Commissioner's Office guidance shapes hybrid deployment preferences among mid-tier rights holders.
Netherlands
Amsterdam-based music publishers consolidate fragmented databases onto unified platforms to streamline EU-wide licensing negotiations. GDPR-mandated data residency rules force maintenance of separate infrastructure stacks across member states. Dutch rights holders favor cloud-native architectures for elastic capacity during quarterly reporting spikes.
Japan
METI digital content initiatives and JIS standards compliance shape platform selection among Tokyo and Osaka media conglomerates. Japanese streaming platforms demand sub-penny accuracy thresholds for micro-transaction reconciliation. Domestic publishers balance cloud migration against lingering data-locality preferences inherited from legacy contractual frameworks.
Royalty Management Software and Services Market Competitive Landscape
Listed leaders compete with private specialists across deployment architecture preferences, creating a tiered structure where scale-driven vendors serve media conglomerates while boutique providers capture consulting-heavy engagements. Cloud-native specialists displace traditional software incumbents as batch-processing architectures yield to elastic capacity models. Three archetypes dominate: multi-territory licensing platforms, blockchain-verified provenance trackers, and patent-centric analytics modules. M&A activity concentrates on acquiring embedded legal expertise, while strategic partnerships with streaming platforms lock in usage data feeds.
Within the cloud-native tier, FADEL and LicenseQ exemplify divergent specialization vectors. FADEL anchors multi-territory licensing workflows for media conglomerates through cloud-native architecture. LicenseQ occupies a position among blockchain-verified provenance trackers, anchoring immutable audit trails for digital assets. IPwe represents the patent-centric module archetype, extending royalty systems into litigation analytics.
| Leading Market Players |
|---|
| FADEL |
| RevTrax |
| Tigunia |
| Rightscorp |
| LicenseQ |
| Integrail |
| IPwe |
| Auditron |
| Evello |
| Others |
Value Network & Pricing Analysis
Cloud-native architecture substitution for on-premise legacy systems is simultaneously redrawing supply geography toward US hyperscaler regions and compressing pricing economics for traditional software vendors maintaining parallel jurisdiction-specific codebases. This displacement dynamic concentrates procurement leverage among media conglomerates demanding elastic capacity without capital expenditure spikes.
Pricing Analysis
Prior-generation perpetual-license platforms command residual premiums among German and French rights holders under BfDI and CNIL data-locality mandates, while current-generation SaaS subscriptions scale with transaction volume, and next-generation blockchain-verified modules extract value through dispute-reduction guarantees. Price differentiation centers on ISO 27001 certification status and embedded legal-technology expertise depth. Pricing pressure intensifies in the consulting services tier as boutique legal-technology firms compete for contract interpretation engagements. Individual authors and smaller publishers exhibit highest price sensitivity, deferring platform migration for spreadsheet-dependent workflows.
Supply Chain Analysis
The United States anchors cloud infrastructure provisioning for media conglomerates, Germany preserves on-premise server manufacturing for data-sovereign deployments, and India supplies specialized software engineering talent for custom development engagements. Raw material dependencies span silicon wafer supply for server hardware, rare earth elements for data center cooling systems, and specialized legal-technology labor for contract configuration. Single-source vulnerability concentrates in hyperscaler region concentration for US media company procurement. Distribution runs through direct vendor relationships with enterprise accounts and channel partnerships serving mid-tier publishers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Royalty management platforms are crossing an interoperability inflection where API-first architecture determines ecosystem participation, with the EU AI Act's algorithmic transparency mandates forcing standardized audit trail formats across previously siloed vendor stacks.
For Market Incumbents: Compound defensive positioning through acquisition of embedded legal-technology expertise to offset boutique firm competition for contract interpretation engagements. Prioritize ISO 27001 certification maintenance as table stakes procurement requirements tighten among media conglomerates. Threat substitution from blockchain-verified provenance trackers demands rapid cloud-native feature parity to prevent account erosion.
For New Entrants and Emerging Players: ISO 27001 certification fast-track opens procurement doors among security-conscious media conglomerates previously locked to incumbent vendors. Latin American streaming expansion presents the most penetrable geography, with Brazil and Mexico subscriber growth outpacing localized platform supply. First-mover positioning in podcast and audiobook verticals lacking standardized rights frameworks offers template-setting advantage before incumbent adaptation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of boutique legal-technology firms with established contract interpretation rule libraries. Long-term viability over the next decade hinges on cloud-native architecture completeness and regulatory compliance module depth. Signal to monitor: EU AI Act enforcement patterns indicating which algorithmic transparency investments convert to sustained competitive differentiation versus commoditized compliance overhead.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architecture satisfies EU AI Act interoperability mandates for audit trail standardization. |
| Acquisition of Specialist Firm | Boutique legal-technology expertise captures disproportionate margin pools in contract interpretation services. |
| Geographic Expansion | Localized infrastructure addresses GDPR-mandated data residency rules across EU member states. |
| Strategic Partnership | Streaming platform data feed agreements lock in usage volume for reconciliation algorithm training. |
| Product Launch | Blockchain-verified provenance modules reduce rights holder disputes through immutable transaction records. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings from listed software vendors, Copyright Office modernization documentation, EU regulatory frameworks, and streaming platform transparency reports. Primary interviews engaged CTOs at media conglomerates, IP legal directors at music publishers, platform engineers at cloud infrastructure providers, and integration specialists at boutique legal-technology firms. Bottom-up transaction volume modeling triangulates against top-down market sizing from vendor revenue disclosures and procurement database analysis.
Segmentation dimensions modeled span deployment architecture, end-user category, service type, and regional regulatory cluster across the projection horizon. CAGRs derive from elasticity-adjusted adoption curves and compliance-driven replacement cycle acceleration. Forecast inputs incorporate EU AI Act implementation timelines and streaming platform micro-transaction volume trajectories without year-specific anchoring.
Underlying assumptions cover sustained streaming subscriber expansion and regulatory enforcement continuity, with deviation risk concentrated in cross-border tax treaty renegotiations and hyperscaler service discontinuation scenarios. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Push Notifications Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Video Server Software Market
Software & Services
Global Online Survey Software Market
Software & Services
Global Email Management Software Market
Software & Services
Performance Management Software Market
Software & Services
Global Gamification Software Market
Software & Services
Lease Accounting Software Market
Software & Services
Online Lottery Software Market
Software & Services
Mobile Tracking Software Market
Software & Services
Over the Air (OTA) Updates Market
Software & Services
Global Nosql Software Market
Software & Services
BIM Objects Software Market
Software & Services
Asia-Pacific Accounting Software Market
Software & Services
Collaborative Applications Market
Software & Services
Global Cinema Software Market