
 Denmark Data Center Physical Security Market | 2026-2036
Denmark Data Center Physical Security Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Data Center Physical Security Market Insights
Modular security bundling is broadening buyer choice across Danish data center operators seeking scalable physical protection. Johnson Controls leverages its building automation heritage to integrate access control with environmental monitoring. Schneider Electric anchors its position through power and security convergence, while Milestone Systems AS specializes in open-platform video management that interoperates with third-party analytics.
Denmark Data Center Physical Security encompasses perimeter barriers, biometric authentication, video surveillance, and intrusion detection systems engineered to IEC 62676-1 video standards and EN 50133 alarm protocols, primarily defending mission-critical computing infrastructure against unauthorized physical access. Surveillance Cameras and Video Analytics command the largest current spend as operators prioritize real-time threat verification over reactive alarm response. Access Control and Biometric Systems represent the fastest-expanding margin pool, driven by zero-trust physical architecture mandates across Copenhagen-area hyperscale campuses.
Denmark's transposition of EU NIS2 through national legislation imposes physical security audits on critical data infrastructure, enforced by the Danish Centre for Cyber Security. The Danish Working Environment Authority supplements these requirements through facility safety inspections that influence camera placement and emergency egress design. Facility operators and security vendors must monitor evolving EU AI Act classifications for automated video analytics to ensure compliance timelines align with procurement cycles.
Market Dynamics
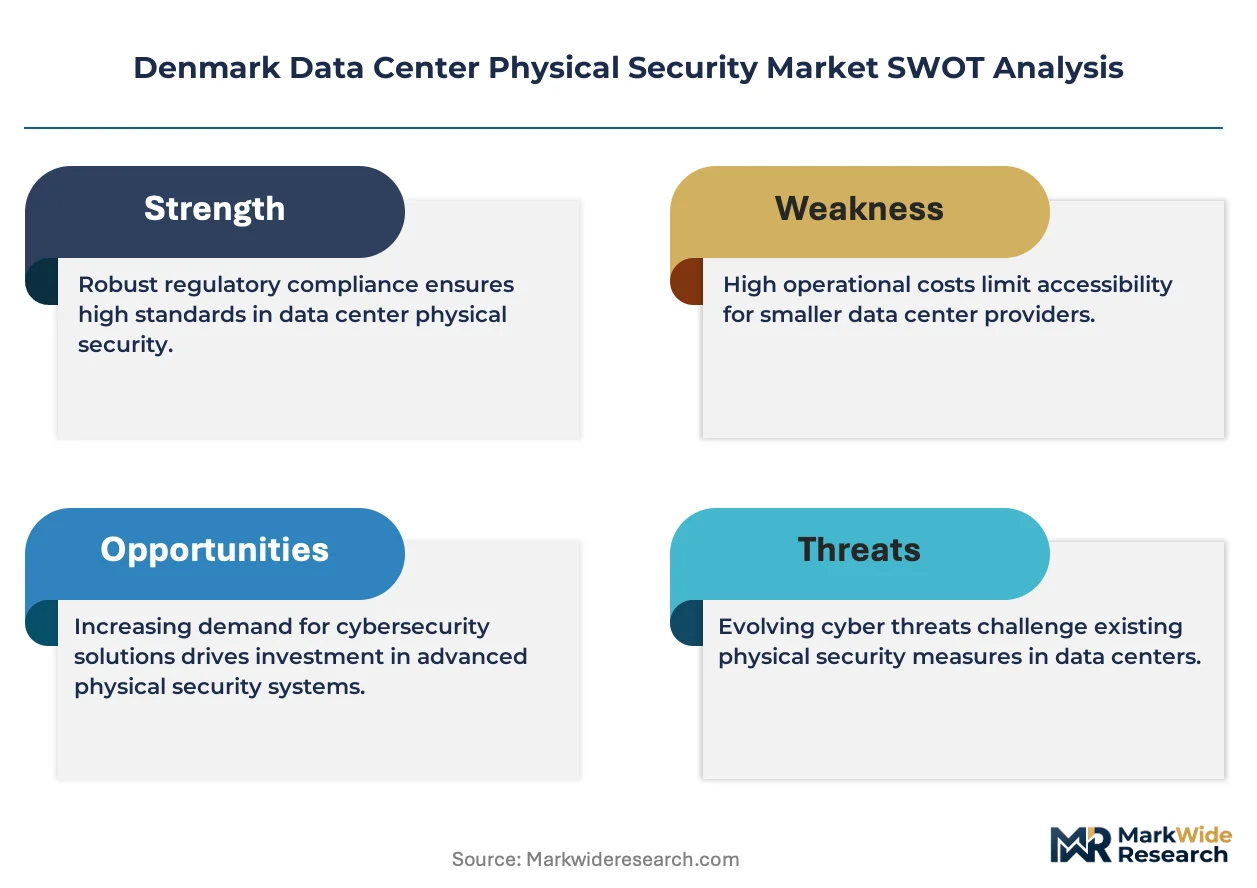
EU NIS2 transposition through Danish national law is compressing procurement timelines for physical security upgrades across Copenhagen-area hyperscale campuses, forcing simultaneous compliance and technology refresh cycles.
Growth Catalysts
- Zero-trust physical architecture:Hyperscale operators in Greater Copenhagen mandate biometric multi-factor authentication at every perimeter layer, expanding deployment of palm-vein and facial recognition systems.
- EN 50133 alarm protocol harmonization:Standardized intrusion detection requirements across Nordic critical infrastructure reduce vendor qualification friction and accelerate replacement cycles.
- Odense cloud corridor expansion:Microsoft and Apple facility investments create concentrated demand for integrated perimeter-video-analytics bundles serving multi-tenant colocation environments.
Market Restraints
- Specialized installer scarcity:IEC 62676-1 certified technicians concentrate in Copenhagen, extending deployment timelines for Odense and Aarhus projects by 4-8 weeks.
- Copper and rare-earth magnet cost volatility:Camera motor assemblies and biometric sensor components face input price swings that compress hardware margins.
- Legacy analog infrastructure:Older Danish enterprise data centers carry sunk investment in coaxial cabling, delaying IP-based video analytics migration.
Strategic Opportunities
- EU AI Act compliance services:Automated video analytics classification requirements create advisory and retrofit demand for Danish security integrators ahead of enforcement deadlines.
- Edge-to-cloud security convergence:Integration of on-premise access control with cloud-native identity platforms opens margin expansion for hybrid architecture specialists.
- Modular perimeter-as-a-service:Subscription-based barrier and detection system deployment reduces upfront capex barriers for mid-tier colocation entrants in Aarhus and Esbjerg.
Industry Challenges
- Cyber-physical security skill fusion:Danish operators struggle to recruit personnel fluent in both IT network security and physical access system engineering.
- Multi-vendor integration complexity:Open-platform VMS interoperability with proprietary biometric readers requires custom middleware development, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Data Center Physical Security Market |
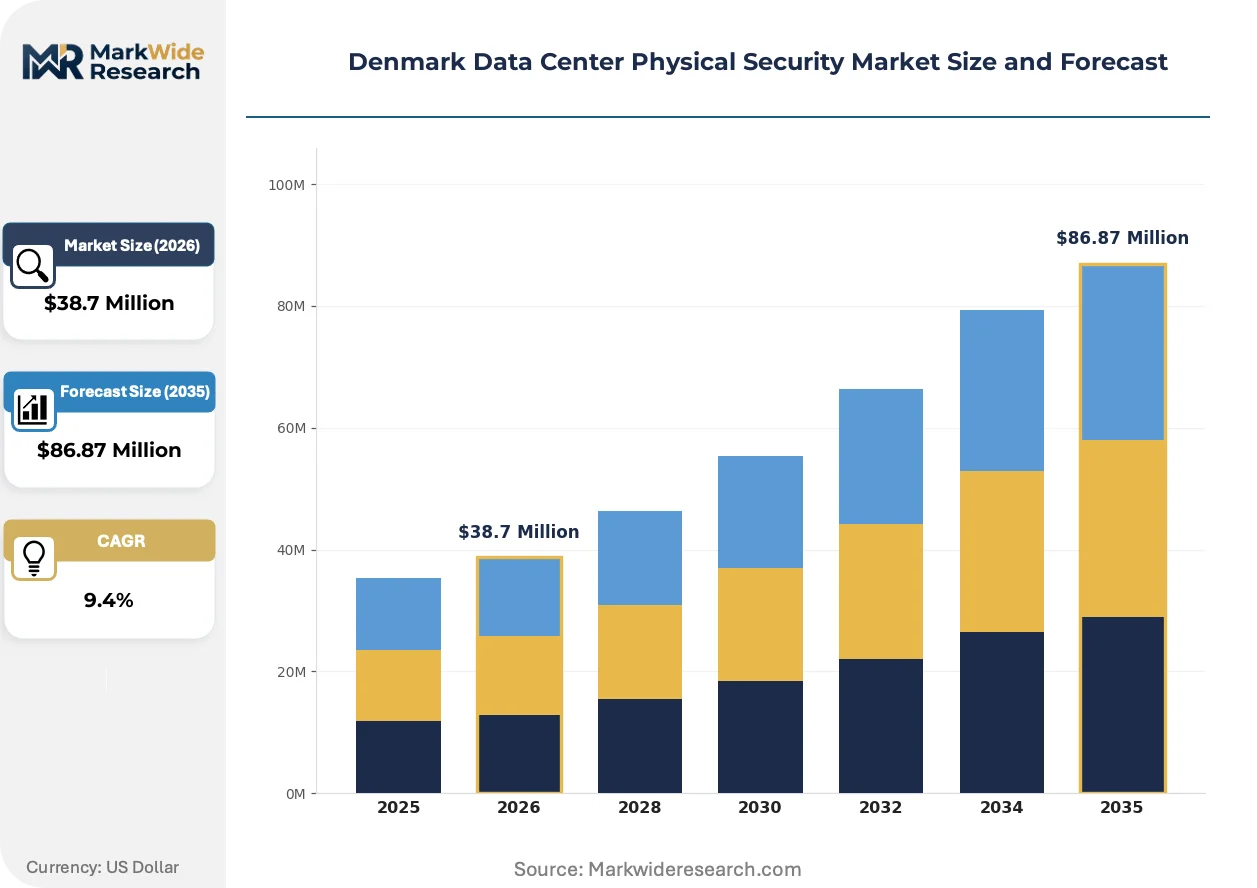
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Security Type: Access Control, Surveillance Cameras, Intrusion Detection, Perimeter Security Technology: Biometric Systems, RFID Solutions, Video Analytics, Alarms Application: Cold Storage Facilities, Server Farms, Network Operations Centers, Data Warehouses End User: Cloud Providers, Enterprises, Telecommunication Companies, Government Agencies |
| Companies Covered | ABB Ltd., Securitas Technology, Bosch Sicherheitssysteme GmbH, Johnson Controls, Honeywell International Inc., Siemens AG, Schneider Electric, Cisco Systems Inc., Milestone Systems AS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Data Center Physical Security Market Trends and Innovations
Behavioral biometric authentication and AI-augmented video verification are displacing credential-based access models across Danish critical infrastructure, while regulatory pressure accelerates compliance-driven technology replacement.
Passive infrared and millimeter-wave sensor fusion for tailgating detection is electrifying perimeter security design in Copenhagen hyperscale facilities. Operators at Facebook's Odense campus and regional colocation providers deploy these systems to eliminate guard-dependent monitoring. The technology compresses staffing models while raising detection accuracy thresholds beyond conventional pressure-mat alternatives.
The Danish Centre for Cyber Security's NIS2 implementation guidelines mandate documented physical access audit trails for operators of essential services. Facility managers must demonstrate continuous monitoring coverage across all entry points with 90-day video retention. Colocation providers in the Greater Copenhagen cluster respond by over-provisioning camera density to preempt compliance gaps.
Consolidated security procurement through Nordic data center developers is displacing fragmented vendor relationships. MT Højgaard and NCC now specify integrated physical-electronic security packages in design-build contracts, compressing supplier selection windows. This concentration is most visible in new Copenhagen harbor district developments where single-source accountability reduces interface risk.
Denmark Data Center Physical Security Market Segmentation
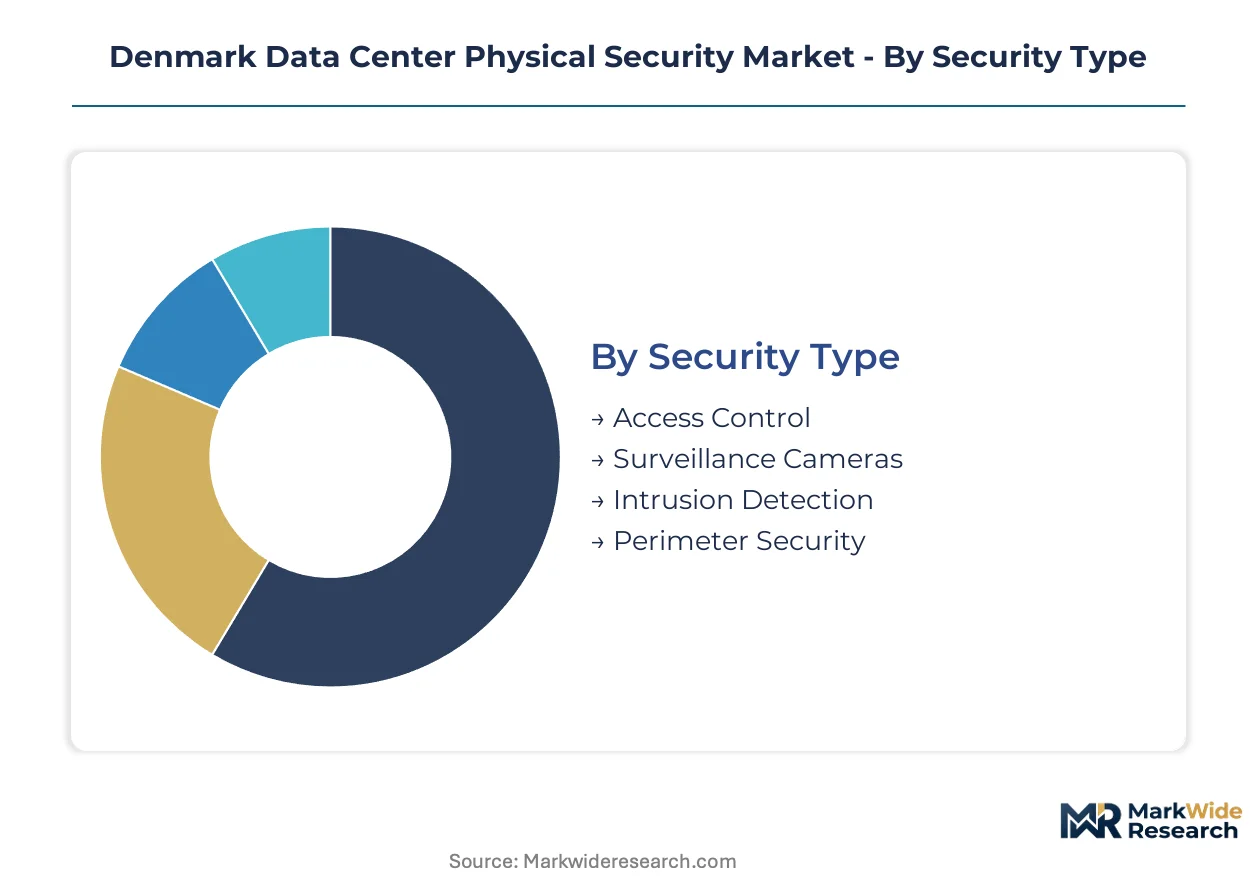
Segmentation reveals how Danish data center operators allocate security expenditure across facility types and threat vectors. Procurement patterns diverge sharply between hyperscale campuses in Greater Copenhagen and enterprise facilities in provincial markets.
Security Type:
Supply concentration for IEC-certified components favors integrated platform vendors with Copenhagen-area service networks.
- Surveillance Cameras:IP-based camera systems with 4K resolution and low-light performance dominate new installations. Copenhagen hyperscale campuses require 90-day retention with edge analytics, compressing procurement toward Milestone-integrated bundles.
- Access Control:Multi-factor authentication platforms combining card readers with biometric verification. Zero-trust mandates at Facebook Odense and Apple Viborg facilities drive replacement of legacy credential systems.
- Intrusion Detection:EN 50133-compliant sensor networks for perimeter and internal zone monitoring. Mid-tier colocation providers in Aarhus prioritize cost-optimized microwave barriers over fiber-optic alternatives.
- Perimeter Security:Physical barriers including crash-rated bollards, anti-climb fencing, and vehicle arrest systems. Harbor district developments specify integrated perimeter-video bundles in design-build contracts.
Surveillance Cameras absorb the bulk of installed capacity; Access Control is expanding most quickly.
Technology:
Cost tiering separates premium biometric platforms from commodity RFID and alarm hardware.
- Biometric Systems:Palm-vein and facial recognition authentication with liveness detection. Copenhagen cloud campuses mandate these for mantrap entry points under NIS2 audit requirements.
- Video Analytics:AI-augmented behavior detection for tailgating, loitering, and unauthorized zone entry. Danish Centre for Cyber Security guidelines drive over-provisioning to preempt compliance gaps.
- RFID Solutions:Proximity and smart card credentials for tiered access zones. Enterprise data centers in provincial Denmark retain these for cost-sensitive secondary perimeter layers.
- Alarms:Integrated intrusion notification systems with central station connectivity. Legacy analog installations in older facilities delay IP migration due to sunk cabling investment.
Video Analytics claims the largest share of new technology spend; Biometric Systems demonstrate the steepest expansion trajectory.
Application:
Facility scale determines security architecture complexity and vendor qualification thresholds.
- Server Farms:Hyperscale computing halls with 10MW+ power draw requiring multi-layered physical protection. Facebook Odense and Microsoft Copenhagen campuses specify biometric mantraps and millimeter-wave tailgating detection.
- Network Operations Centers:Mission-critical monitoring facilities with 24/7 staffed security. Real-time threat verification demands dense camera coverage with integrated access logging.
- Data Warehouses:Storage-intensive facilities with lower staffing levels. Automated perimeter monitoring reduces guard dependency in Aarhus and Esbjerg secondary markets.
- Cold Storage Facilities:Archive and backup infrastructure with restricted access protocols. Simplified intrusion detection suffices given limited personnel traffic.
Server Farms command the highest security spend per square meter; Network Operations Centers show the fastest upgrade cycle.
End User:
Customer type shapes procurement centralization and compliance stringency.
- Cloud Providers:Hyperscale operators with standardized global security specifications. Amazon, Google, and Microsoft drive volume for integrated biometric-video platforms.
- Enterprises:Corporate-owned facilities with variable security maturity. Financial services operators in Copenhagen exceed baseline NIS2 requirements; manufacturing data centers lag in IP migration.
- Telecommunication Companies:TDC and regional carriers with legacy central office adaptations. Co-location security upgrades compete with network infrastructure capital priorities.
- Government Agencies:Public sector operators under Danish Centre for Cyber Security direct oversight. Mandatory physical access audits accelerate compliance-driven procurement.
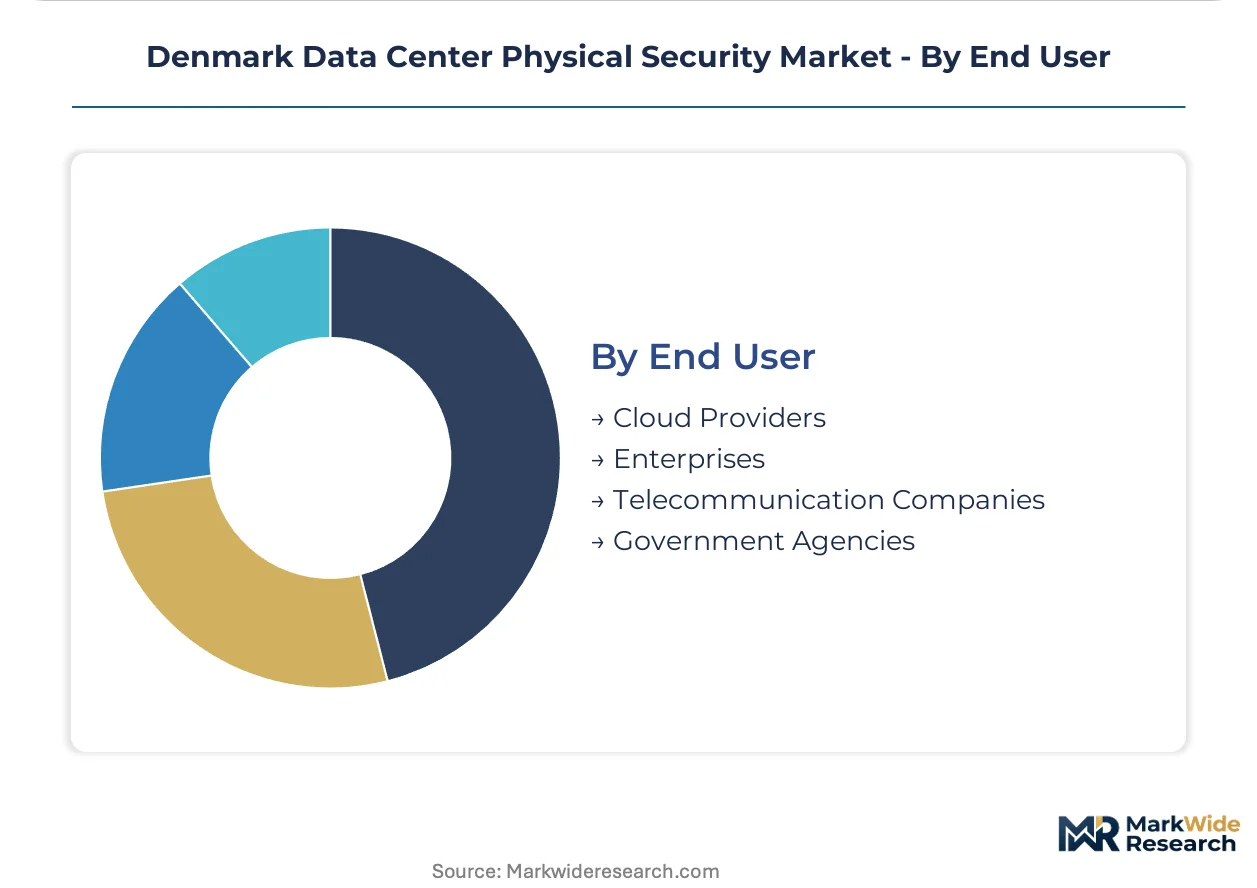
Cloud Providers dominate absolute security investment; Government Agencies exhibit the most compressed procurement timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Copenhagen Data Center Corridor tax incentive zone concentrates Nordic hyperscale investment, compressing procurement timelines for integrated physical security platforms across Denmark's eastern seaboard.
Greater Copenhagen
Hyperscale campuses in Høje-Taastrup and Kalundborg drive demand for biometric mantraps and millimeter-wave tailgating detection. The Danish Centre for Cyber Security enforces NIS2 physical access audit trails with 90-day video retention mandates. Facebook's Odense facility and Apple's Viborg data center anchor the corridor's security specification standards.
Odense Cloud Corridor
Microsoft and Apple facility expansions create concentrated demand for perimeter-video-analytics bundles serving multi-tenant colocation environments. Municipal zoning in Odense Municipality fast-tracks critical infrastructure permits with embedded security compliance checkpoints. The city's industrial harbor district hosts Denmark's densest cluster of cloud-adjacent logistics and backup facilities.
Aarhus Secondary Market
Mid-tier colocation providers prioritize cost-optimized microwave barriers over fiber-optic alternatives for perimeter intrusion detection. The Central Denmark Region's digital infrastructure fund subsidizes physical security upgrades for regional enterprise data centers. Aarhus University's research computing facilities drive specialized access control requirements for sensitive academic datasets.
Esbjerg Energy Hub
Offshore wind power interconnectors and submarine cable landing stations require hardened perimeter protection against sabotage threats. The Danish Energy Agency coordinates physical security standards with the Centre for Cyber Security for cross-sector critical infrastructure. Esbjerg Port's free zone status attracts international cable system operators with standardized security procurement frameworks.
North Jutland Edge Cluster
Low-latency gaming and content delivery nodes deploy automated perimeter monitoring to reduce guard dependency in sparsely staffed facilities. Aalborg Municipality's smart city infrastructure program integrates data center physical security with municipal surveillance networks. The region's renewable energy surplus attracts modular data center deployments with subscription-based security service models.
Denmark Data Center Physical Security Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Denmark's data center physical security market, creating a tiered structure where building automation heritage confers integration advantages. The vendor base separates into three strategic archetypes: integrated building technology conglomerates, open-platform video management specialists, and Nordic security service integrators. M&A activity concentrates on biometric authentication capabilities, while strategic partnerships dominate the convergence of physical access with cloud-native identity platforms.
Among building automation conglomerates, Johnson Controls and Schneider Electric occupy positions where power and environmental system integration creates account control. Johnson Controls leverages its Copenhagen-area service network to bundle access control with HVAC monitoring. Schneider Electric anchors the premium tier through power-security convergence offerings. Milestone Systems AS exemplifies the open-platform specialist archetype, with its Danish headquarters providing localized video analytics integration capabilities.
| Leading Market Players |
|---|
| ABB Ltd. |
| Securitas Technology |
| Bosch Sicherheitssysteme GmbH |
| Johnson Controls |
| Honeywell International Inc. |
| Siemens AG |
| Schneider Electric |
| Cisco Systems Inc. |
| Milestone Systems AS |
| Others |
Pricing and Supply Chain Analysis
Rare-earth magnet cost volatility in biometric sensor assemblies cascades through Danish data center security procurement, compressing hardware margins for mid-tier colocation providers in Aarhus while hyperscale operators in Copenhagen absorb premiums for IEC 62676-1 certified components.
Pricing Analysis
Margin tightening in the mid-tier colocation segment reflects copper price swings in camera motor assemblies and biometric reader production. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale-integrated bundles from standalone perimeter hardware. Certification grade under EN 50133 alarm protocols and volume scale through Nordic developer consolidation drive price differentiation. Danish enterprise data centers exhibit highest price sensitivity due to legacy analog infrastructure sunk costs, while cloud providers demonstrate lowest sensitivity given standardized global security specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated biometric-video platforms, while value-added resellers serve provincial enterprise facilities. Component manufacturing concentrates in Germany, China, and Taiwan for IP cameras and access control systems. Danish security integrators draw from South Korean and Japanese suppliers for palm-vein and facial recognition modules. Single-source vulnerability in IEC 62676-1 certified technician availability creates deployment bottlenecks for Odense and Aarhus projects. Distribution runs through Copenhagen-area service networks for integrated building automation bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Denmark Data Center Physical Security Market functions as a cost-of-compliance arena where EU NIS2 transposition through Danish national law erects certification barriers that favor incumbent integrators with established Centre for Cyber Security audit relationships.
For Market Incumbents: To counter specialized installer scarcity extending regional deployment timelines, Johnson Controls and Schneider Electric should deepen Copenhagen-area technician certification pipelines while anchoring account control through power-security convergence offerings that bundle environmental monitoring with access control platforms. For New Entrants and Emerging Players: A 40-60% price-point gap between premium hyperscale-integrated bundles and economy-tier standalone hardware creates entry latitude for modular perimeter-as-a-service providers targeting mid-tier colocation facilities in Aarhus and Esbjerg with subscription-based barrier deployments that reduce upfront capex barriers. For Investors and Strategic Acquirers: Accelerated procurement timelines following NIS2 enforcement deadlines is the leading indicator that compliance-service capabilities will command acquisition premiums; target Danish security integrators with documented Danish Centre for Cyber Security audit relationships and EU AI Act advisory competencies as the market consolidates around hybrid cyber-physical expertise.| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Capability Acquisition | Consolidation of palm-vein and facial recognition specialists addresses zero-trust physical architecture mandates at Facebook Odense and Apple Viborg campuses. |
| EU AI Act Compliance Service Launch | Advisory and retrofit demand for automated video analytics classification creates recurring revenue streams ahead of enforcement deadlines. |
| Copenhagen-Area Technician Certification Expansion | IEC 62676-1 certified labor pools reduce deployment bottlenecks that currently extend Odense and Aarhus project timelines by 4-8 weeks. |
| Cloud-Native Identity Platform Integration | Hybrid architecture specialists capture margin expansion from edge-to-cloud security convergence in multi-tenant colocation environments. |
| Modular Perimeter-as-a-Service Rollout | Subscription-based barrier and detection system deployment lowers capex barriers for mid-tier entrants in Aarhus and Esbjerg secondary markets. |
Research Methodology
Multi-period observation of hyperscale facility expansion permits, NIS2 compliance audit filings, and security procurement contract awards anchored the trend analysis, supplemented by interviews with data center facility managers, security systems integrators, Danish Centre for Cyber Security officials, and procurement leads at cloud providers and colocation operators. Secondary validation drew from Danish Working Environment Authority inspection records, EU AI Act implementation guidance, IEC 62676-1 certification databases, and EN 50133 protocol harmonization documents. Bottom-up project pipeline aggregation triangulated against top-down infrastructure investment tracking.
Input-output matrices modeled facility-scale security spend across server farms, network operations centers, data warehouses, and cold storage applications, segmented by security type, technology tier, and end-user category. CAGRs were derived from facility footprint expansion rates, replacement cycle compression under NIS2 mandates, and technology refresh patterns for analog-to-IP video migration. Forecast inputs incorporated hyperscaler capex disclosure patterns, municipal zoning approval timelines for Odense harbor district developments, and copper and rare-earth magnet price trajectory assumptions.
Inputs from Danish regulatory filings and Nordic data center developer procurement databases were available through the study window; gaps in real-time contract award values for confidential hyperscale security specifications introduce uncertainty bands around installed base estimates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Asia-Pacific Hyperscale Data Center Market
Data Center Infrastructure
Denmark Data Center Power Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
South America Data Center Power Market
Data Center Infrastructure
Middle East and Africa Data Center Infrastructure Management Market
Data Center Infrastructure
China Data Center Storage Market
Data Center Infrastructure
Stockholm Data Center Market
Data Center Infrastructure
Philippines Data Center Server Market
Data Center Infrastructure
Indonesia Data Center Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Spain Data Center Power Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Japan Data Center Physical Security Market