
 Pallet Drum Filler Capper Market | 2026-2036
Pallet Drum Filler Capper Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Drum Filler Capper Market Analytics
Servo-driven precision control is reconfiguring how pallet drum filler capper systems achieve throughput and containment standards in hazardous chemical environments. Feige GmbH leverages German engineering heritage to dominate high-precision filling applications for flammable liquids. PACK'R anchors its position through integrated cap sealing technology that reduces vapor loss during drum closure operations. Krones AG extends its beverage equipment expertise into chemical-adjacent filling systems with modular platform designs.
A pallet drum filler capper is an industrial packaging machine engineered to meter liquid, powder, or granular materials into standardized drum containers mounted on pallets, typically achieving fill accuracies within plus or minus 0.1 percent for liquid applications and incorporating torque-controlled capping mechanisms rated for UN-certified closures. The equipment serves primarily to automate bulk material handling while ensuring regulatory compliance for hazardous substance containment and transport. Automated fillers command the dominant share of installed capacity as chemical processors prioritize throughput over capital flexibility, while combination systems that integrate filling and capping on single platforms represent the fastest-expanding category by project pipeline. Servo systems displace pneumatic alternatives in new installations where programmable motion profiles enable recipe-driven changeovers between drum sizes without mechanical retooling.
OSHA process safety management standards and EPA risk management plan requirements in the United States mandate engineered controls for drum filling operations involving toxic or reactive chemicals, directly shaping equipment specification sheets and procurement criteria. REACH registration obligations and ATEX equipment directives in Europe compel manufacturers to certify electrical components for explosive atmospheres, creating compliance barriers for non-certified suppliers. Stakeholders must monitor evolving UN dangerous goods packaging standards and regional carbon border adjustment mechanisms as these frameworks increasingly influence total cost of ownership calculations for drum packaging infrastructure investments.
Market Dynamics
Servo-driven automation is reconfiguring capital allocation patterns across drum packaging infrastructure. Chemical processors now specify programmable motion systems over pneumatic legacy equipment to achieve recipe-driven changeovers without mechanical retooling.
Growth Catalysts
- REACH registration obligations:European chemical manufacturers must certify drum handling equipment for explosive atmospheres, compelling ATEX-compliant filler capper procurement cycles.
- India's specialty chemical expansion:Manufacturing clusters in Gujarat and Maharashtra are scaling drum packaging capacity to serve agrochemical and pharmaceutical export markets.
- Servo motor precision control:Programmable torque profiles enable fill accuracies within plus or minus 0.1 percent for flammable liquid applications, reducing vapor loss incidents.
Market Restraints
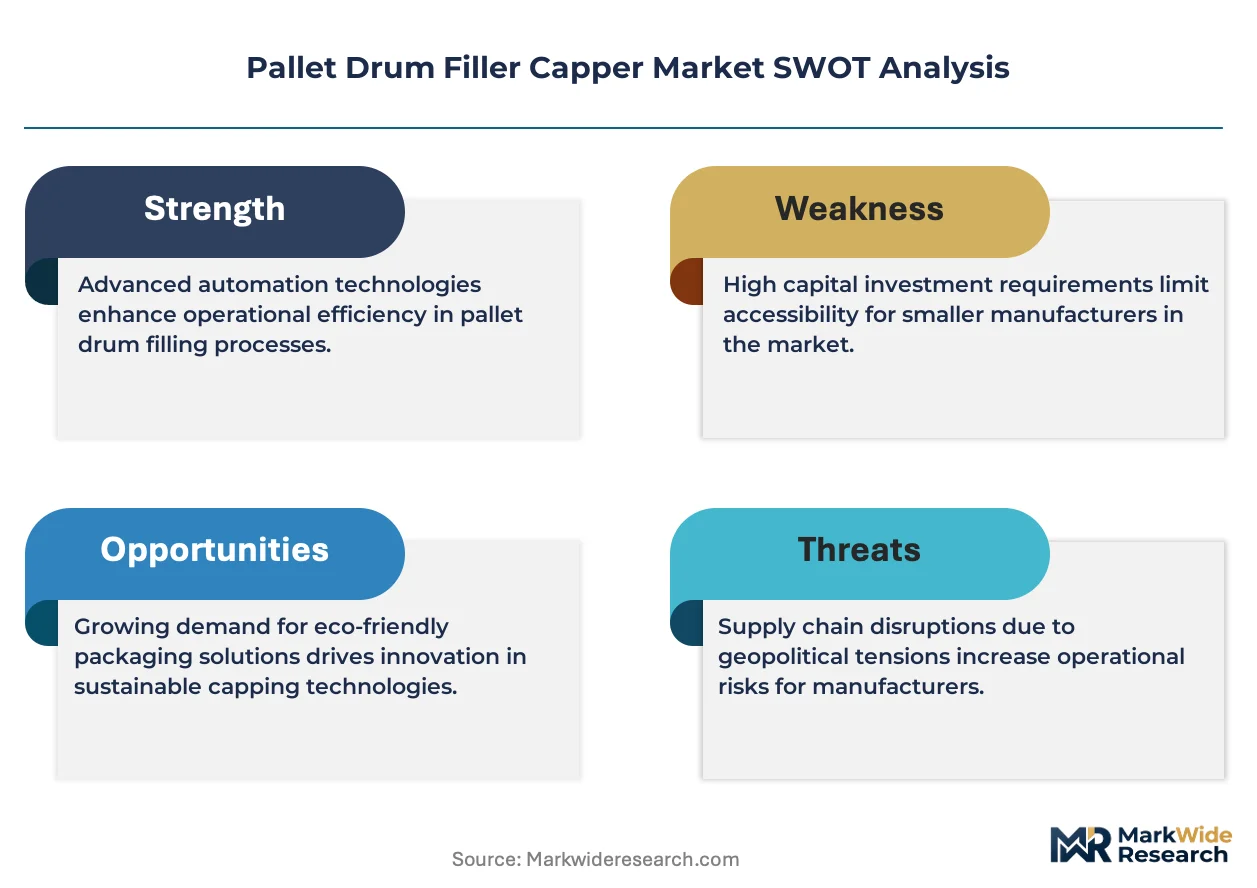
- Stainless steel input volatility:Grade 316L component costs fluctuate with nickel pricing, compressing margins for equipment fabricators serving mid-tier chemical processors.
- Component supply concentration:High-precision servo drives and explosion-proof sensors concentrate among German and Japanese suppliers, creating lead time vulnerabilities.
- ATEX certification friction:Third-party conformity assessment timelines for electrical components in explosive atmospheres extend project commissioning by four to eight months.
Strategic Opportunities
- Secondary packaging integration:Converging drum filling, capping, and palletizing onto single-platform systems reduces floor space requirements and vapor exposure points.
- China's dual carbon goals:Provincial environmental inspections are accelerating replacement of pneumatic systems with energy-efficient servo alternatives in Jiangsu and Zhejiang chemical parks.
- Modular platform architectures:Skid-mounted filler capper units enable rapid redeployment between contract manufacturing sites, serving the toll processing segment.
Industry Challenges
- Servo commissioning expertise:Chemical plant maintenance teams lack proficiency in programmable drive parameterization, forcing reliance on OEM field service.
- Legacy system integration:Brownfield installations require custom interface engineering between new servo fillers and existing distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Drum Filler Capper Market |
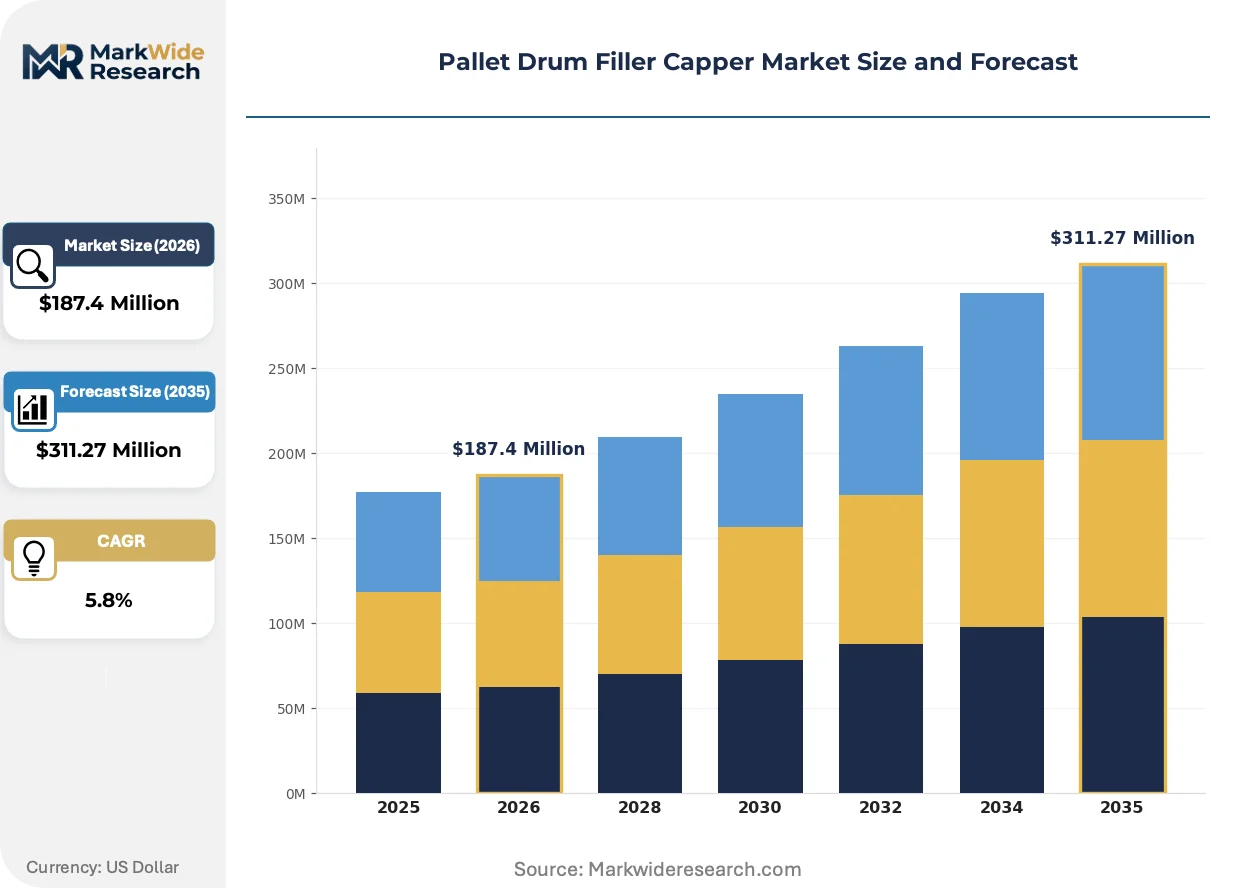
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Fillers, Manual Fillers, Cap Sealing Machines, Combination Systems Technology: Pneumatic Systems, Servo Systems, Mechanical Systems, Gravity Fillers End User: Food & Beverage, Chemical Processing, Pharmaceuticals, Oil & Gas Application: Liquid Filling, Powder Filling, Granular Filling, Bulk Packaging |
| Companies Covered | Feige GmbH, Epic Packaging Systems, PACK'R, Krones AG, Accutek Packaging Equipment, Premier Tech Chronos, Filamatic, Inc., Bosch Packaging Technology, Barry-Wehmiller Companies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Drum Filler Capper Market Evolving Landscape
Drum packaging equipment is converging with adjacent automation layers. Control architectures, sensing modalities, and service delivery models are simultaneously evolving to reduce total cost of ownership while tightening hazardous material containment.
Coriolis mass flow measurement is migrating from laboratory calibration to in-line filling operations. Specialty chemical manufacturers in Germany and Switzerland now specify Coriolis-based systems for high-value solvent batches. This technology is migrating from premium applications toward standard chemical processing, compressing the price premium between gravimetric and volumetric filling methods.
EPA risk management plan amendments are tightening engineered control requirements for toxic chemical drum filling. Facilities handling anhydrous ammonia or chlorine derivatives must demonstrate redundant containment systems. Chemical processors in Texas and Louisiana are responding by specifying double-seated valve manifolds and vapor recovery integration on new filler capper purchases.
Integrated service contracts are displacing transactional spare parts purchasing. Large chemical conglomerates now bundle preventive maintenance, remote diagnostics, and consumable replenishment into multi-year agreements. This pattern is most visible among North American petrochemical operators seeking to internalize less packaging equipment expertise while guaranteeing uptime performance.
Pallet Drum Filler Capper Market Segmentation
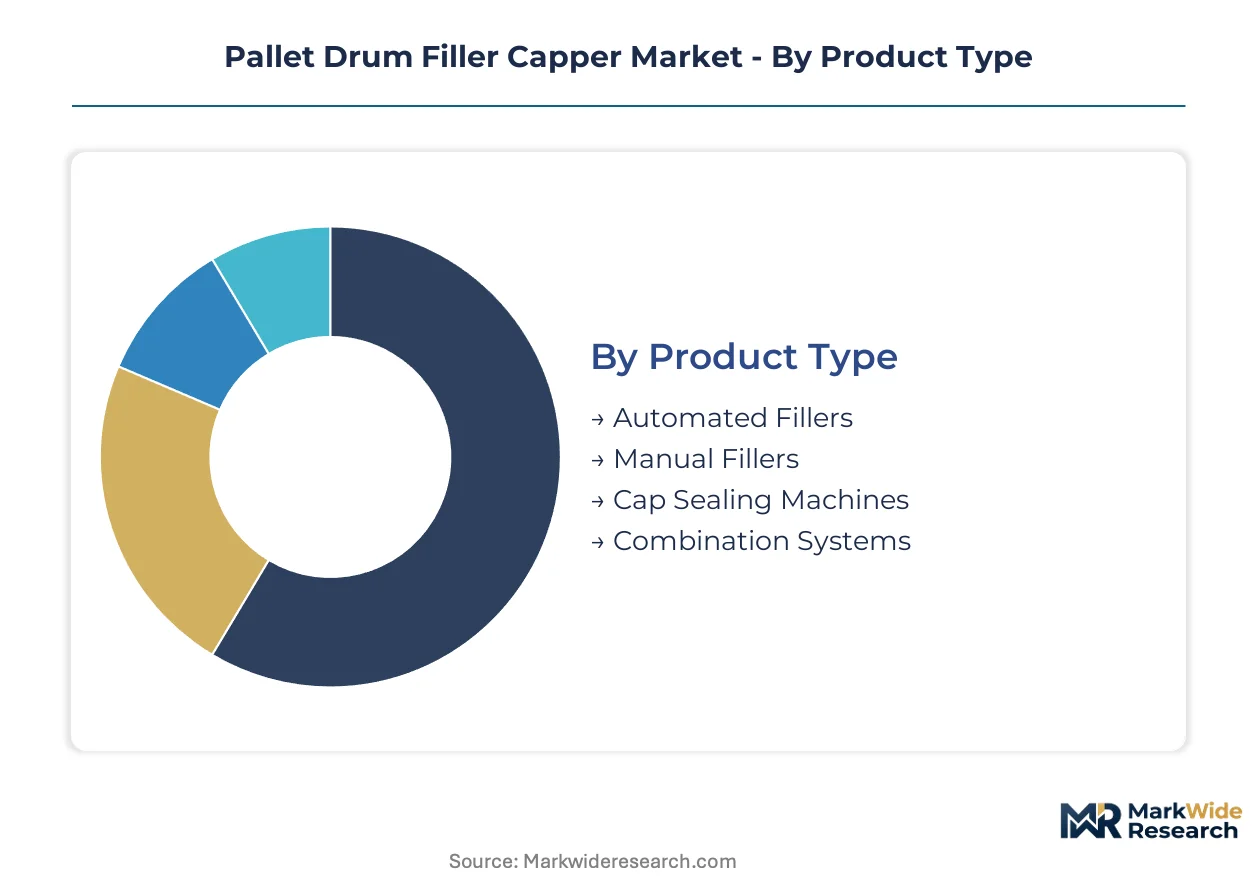
Equipment configuration choices in the Pallet Drum Filler Capper Market directly determine service contract structures and spare parts revenue streams for manufacturers. Segmentation reveals how automation intensity, hazardous material exposure, and throughput requirements reshape procurement patterns across chemical processing and adjacent industries.
Product Type:
After-sales service intensity varies dramatically across product configurations, with automated systems generating recurring calibration and software maintenance revenue while manual equipment relies on break-fix models.
- Automated Fillers:These systems integrate programmable logic controllers with servo-driven dispensing mechanisms capable of handling multiple drum sizes without mechanical changeover. Chemical processing plants in Germany and Switzerland specify these units for REACH-compliant solvent handling where precision containment prevents vapor loss incidents. Service contracts typically span five to seven years with quarterly calibration intervals.
- Combination Systems:Single-platform architectures merge filling, capping, and torque verification into continuous workflows, reducing vapor exposure points by eliminating drum transfers between stations. India's specialty chemical clusters in Gujarat are expanding procurement of these integrated units to serve agrochemical export markets with UN-certified packaging requirements. Commissioning complexity drives higher OEM field service attachment rates.
- Cap Sealing Machines:Standalone torque-controlled capping units serve toll processors requiring rapid redeployment between contract manufacturing sites.
- Manual Fillers:Operator-dependent gravimetric systems persist in small-batch pharmaceutical compounding where recipe flexibility outweighs throughput priorities.
By volume, Automated Fillers leads. By growth pace, Combination Systems is ahead.
Technology:
Capital allocation patterns favor motion control platforms that reduce energy consumption and enable recipe-driven parameter changes without mechanical intervention.
- Servo Systems:Programmable torque and velocity profiles achieve fill accuracies within plus or minus 0.1 percent for flammable liquid applications while cutting compressed air consumption versus pneumatic alternatives. China's Jiangsu and Zhejiang chemical parks are accelerating replacement cycles under provincial environmental inspections tied to dual carbon goals. Component supply concentrates among German and Japanese drive manufacturers, creating lead time vulnerabilities.
- Pneumatic Systems:Legacy compressed-air architectures dominate installed base in mature chemical processing regions but face displacement as energy efficiency regulations tighten.
- Mechanical Systems:Cam-driven volumetric mechanisms serve low-margin bulk chemical segments where capital constraints override precision requirements.
- Gravity Fillers:Simple head-pressure dispensing persists in non-hazardous food-grade applications with limited viscosity variation.
Servo Systems commands the premium tier. Pneumatic Systems retains the largest installed base.
End User:
Regulatory exposure and batch value determine equipment specification intensity across customer verticals.
- Chemical Processing:OSHA process safety management standards and EPA risk management plan requirements mandate engineered controls for toxic or reactive chemical drum filling, directly shaping procurement criteria. Facilities in Texas and Louisiana handling anhydrous ammonia or chlorine derivatives specify redundant containment systems with vapor recovery integration. ATEX certification timelines extend project commissioning by four to eight months.
- Pharmaceuticals:High-value solvent batches in Germany and Switzerland drive specification of Coriolis mass flow measurement systems migrating from laboratory calibration to in-line operations.
- Oil & Gas:Lubricant blending operations in the US Gulf Coast favor modular skid-mounted units enabling rapid redeployment between toll processing contracts.
- Food & Beverage:Edible oil and syrup handling requires sanitary-grade stainless steel construction with CIP-compatible designs.
Chemical Processing generates the highest equipment value per installation. Pharmaceuticals is climbing the fastest.
Application:
Material state and flow characteristics dictate sensor modalities and containment architectures.
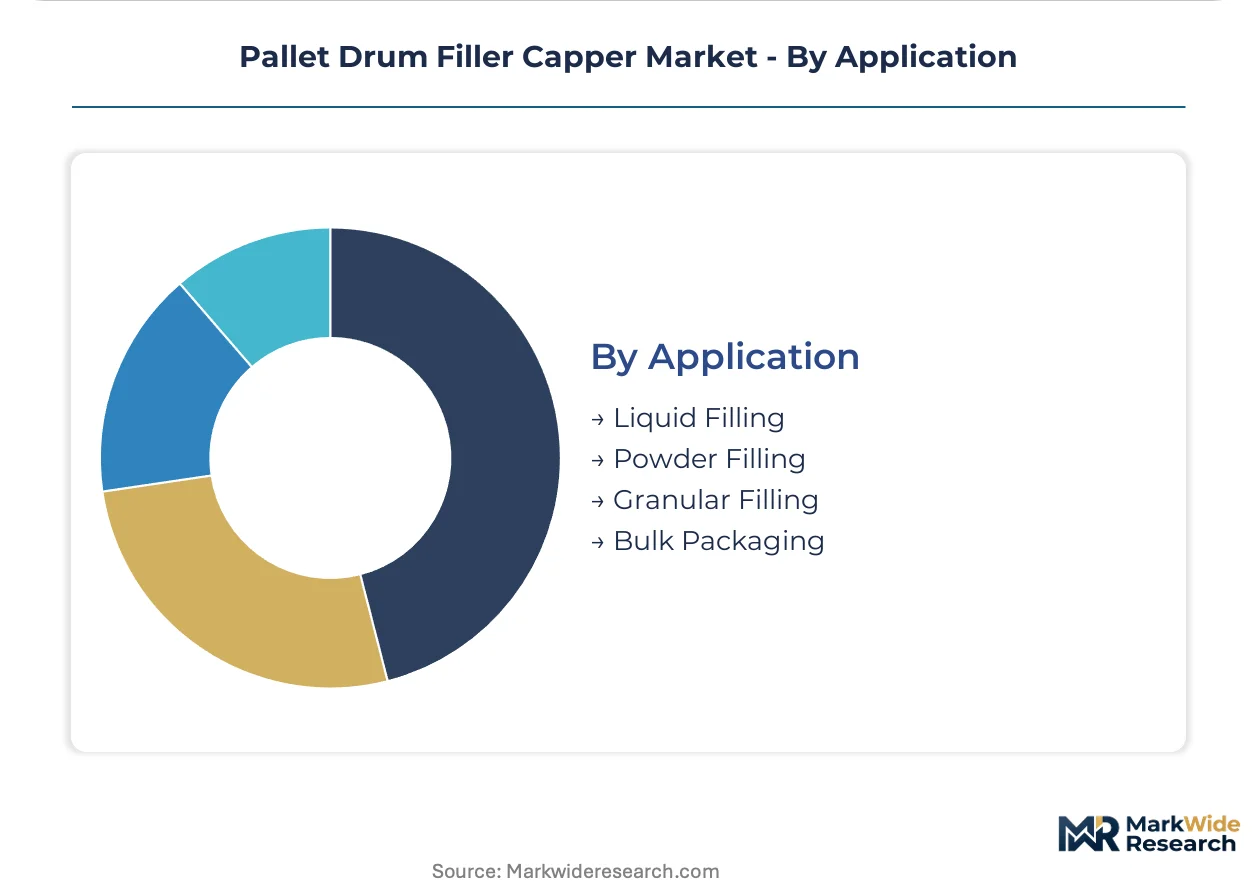
- Liquid Filling:Viscosity-variable solvent and resin handling demands Coriolis mass flow or electromagnetic flowmeter integration with vapor recovery manifolds. REACH registration obligations in Europe compel ATEX-certified electrical components for explosive atmospheres. Grade 316L stainless steel component costs fluctuate with nickel pricing, compressing margins for equipment fabricators.
- Powder Filling:Dust containment and electrostatic dissipation requirements drive specification of sealed transfer systems with nitrogen inerting.
- Granular Filling:Abrasive plastic pellet and catalyst handling accelerates wear component replacement cycles.
- Bulk Packaging:High-throughput intermediate bulk container filling converges with drum packaging on shared platform architectures.
Liquid Filling dominates project pipelines. Powder Filling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large chemical conglomerates and specialty solvent manufacturers constitute the dominant buyer archetype, concentrating procurement decisions in industrial clusters where REACH, OSHA, and ATEX compliance mandates reshape equipment specifications. Procurement patterns track regulatory enforcement intensity rather than pure capacity expansion.
United States
Petrochemical operators along the Gulf Coast drive demand for vapor recovery-integrated filler cappers handling anhydrous ammonia and chlorine derivatives. OSHA process safety management standards and EPA risk management plan amendments mandate redundant containment systems, extending equipment qualification timelines. Facilities in Texas and Louisiana are retrofitting legacy pneumatic installations with servo-driven alternatives to meet tightened engineered control requirements.
Germany
High-precision solvent batching operations in Rhineland chemical parks specify Coriolis mass flow measurement systems migrating from laboratory calibration to in-line production. REACH registration obligations and ATEX equipment directives compel electrical component certification for explosive atmospheres, creating compliance barriers for non-certified suppliers. Bavarian and North Rhine-Westphalian fabricators anchor European demand for premium servo-driven platforms.
China
Provincial environmental inspections in Jiangsu and Zhejiang chemical parks are accelerating displacement of pneumatic systems with energy-efficient servo alternatives under dual carbon goals. MIIT equipment efficiency standards and MEE enforcement actions in the Yangtze River Delta reshape procurement criteria toward programmable motion control. Manufacturing clusters in Ningbo and Suzhou are expanding drum packaging capacity for agrochemical export markets.
India
Specialty chemical manufacturers in Gujarat and Maharashtra are scaling drum packaging infrastructure to serve pharmaceutical and agrochemical export markets with UN-certified packaging requirements. BIS equipment safety standards and CDSCO pharmaceutical manufacturing guidelines influence specification sheets for hazardous material handling. The Dahej and Mundra industrial corridors are emerging as concentrated demand nodes for combination filling-capping systems.
Switzerland
High-value solvent and fine chemical producers in Basel-Land and Zurich cantons specify precision containment equipment for flammable liquid applications. Swissmedic pharmaceutical manufacturing standards and cantonal environmental enforcement shape procurement toward servo-driven accuracy platforms. The Basel chemical cluster drives premium-tier demand for integrated filler capper systems with recipe-driven changeover capabilities.
Pallet Drum Filler Capper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where ATEX certification capabilities and servo drive integration expertise determine market access. The vendor base separates into three strategic archetypes: German-engineered precision specialists, North American integrated packaging conglomerates, and Asia-Pacific scale fabricators. Competitive positioning hinges on M&A activity consolidating secondary packaging integration capabilities and strategic partnerships securing servo drive supply allocation.
Among German-engineered precision specialists, Feige GmbH and Krones AG occupy positions exemplifying high-accuracy flammable liquid handling and modular platform architectures respectively. PACK'R anchors the integrated cap sealing technology vector within the North American specialist tier. These three companies represent distinct competitive positioning strategies: heritage engineering dominance, beverage-to-chemical equipment extension, and vapor loss reduction specialization.
| Leading Market Players |
|---|
| Feige GmbH |
| Epic Packaging Systems |
| PACK'R |
| Krones AG |
| Accutek Packaging Equipment |
| Premier Tech Chronos |
| Filamatic, Inc. |
| Bosch Packaging Technology |
| Barry-Wehmiller Companies |
| Others |
Value Network & Pricing Analysis
Japanese and German servo drive manufacturers anchor upstream supply for precision motion components, concentrating margin capture in the ATEX-certified system integrator tier where certification timelines create pricing power. Equipment fabricators serving mid-tier chemical processors face compressed margins when nickel volatility spikes Grade 316L stainless steel input costs, forcing selective pass-through to buyers with long-term service contracts.
Pricing Analysis
Cost-plus contracts with nickel and rare-earth indexation dominate equipment procurement between German fabricators and North American petrochemical operators. Three-tier pricing structure across ATEX-certified premium, standard servo-driven, and pneumatic legacy systems differentiates based on certification grade and after-sales bundling intensity. Pricing pressure stems from stainless steel input volatility, with mid-tier processors exhibiting highest price sensitivity compared to Gulf Coast conglomerates prioritizing uptime guarantees over capital expenditure.
Supply Chain Analysis
German and Japanese export-control frameworks restrict high-precision servo drive and explosion-proof sensor flows to certified system integrators, fragmenting access for non-ATEX-compliant fabricators. Component sourcing concentrates in Germany, Japan, and South Korea, with raw material dependencies spanning nickel for Grade 316L stainless steel, neodymium for servo motors, and specialized ceramics for hazardous environment sensors. Single-source vulnerability runs through precision drive allocation, while distribution runs through OEM-direct channels for large chemical processors and regional distributor networks for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where ATEX certification timelines and servo commissioning expertise create switching costs that cement incumbent positions. The structural moat deepens as chemical processors internalize less packaging equipment expertise, forcing reliance on OEM field service relationships.
For Market Incumbents: Harden defensive positioning by deepening backward integration into servo drive allocation agreements with Japanese suppliers, insulating against lead time vulnerabilities. Expand captive service contract penetration among Texas and Louisiana petrochemical operators facing EPA risk management plan amendments. Prioritize certification investment for emerging explosive atmosphere sensor modalities before regulatory tightening accelerates. For New Entrants and Emerging Players: Mid-market toll processors in India's Dahej and Mundra industrial corridors represent the most penetrable entry point, where modular skid-mounted architectures enable rapid redeployment without deep certification heritage. China's provincial environmental inspections in Jiangsu chemical parks create displacement opportunities for energy-efficient servo alternatives among pneumatic legacy users. Pursue joint development agreements with established German component suppliers to bypass ATEX certification friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision engineering specialists holding dormant ATEX certification capabilities and underutilized servo integration expertise. Five-to-ten year viability hinges on regulatory enforcement intensity rather than pure capacity expansion, favoring targets with entrenched relationships among REACH-obligated European chemical manufacturers. Watch for EPA risk management plan amendment implementation velocity as inflection indicator for North American replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Supply | Secures allocation priority with Japanese manufacturers amid component scarcity. |
| ATEX Certification Expansion | Opens access to European REACH-obligated chemical processing procurement cycles. |
| Modular Platform Architecture Development | Enables rapid redeployment for India's toll processing contract manufacturing segment. |
| Integrated Service Contract Bundling | Captures recurring revenue from North American petrochemical uptime guarantees. |
| Coriolis Mass Flow Technology Migration | Addresses German and Swiss high-value solvent batch precision requirements. |
Research Methodology
Desk research of customs trade databases, SEC 10-K filings from packaging equipment conglomerates, and chemical industry association reports preceded structured interviews with plant engineers, maintenance directors at specialty chemical processors, OEM procurement teams, and aftermarket service heads. Primary fieldwork with stakeholders across Germany, the United States, China, and India combined with secondary validation from equipment certification registries and regional regulatory filings. Bottom-up unit economics triangulated against top-down capacity expansion announcements.
Assumptions held fixed include REACH and ATEX regulatory enforcement intensity, nickel price corridor stability, and servo drive supply allocation patterns, while regional chemical production growth rates and provincial environmental inspection severity were varied across scenarios. Segmentation dimensions modeled encompass automation intensity, hazardous material exposure tier, end-use vertical, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and project pipeline conversion rates, with inputs including chemical processing capacity utilization and pharmaceutical export growth trajectories.
Practitioners should monitor EPA risk management plan amendment implementation, MIIT equipment efficiency standard tightening, and nickel price volatility for early signals of forecast deviation. Material shifts in ATEX certification timeline compression or German-Japanese export control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Post Press Machine Market
Packaging Machinery
Volumetric Boom Filling Machine Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Filling Machinery Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Banding Machine Market
Packaging Machinery
Cosmetic Packaging Machinery Market
Packaging Machinery
Bubble Wrap Machine Market
Packaging Machinery
Asia-Pacific Pharmaceutical Packaging Machinery Market
Packaging Machinery
Injection Blow Molding Machine Market
Packaging Machinery
Liquid Filling Machines Market
Packaging Machinery
Tube Filling Machine Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Package Closing Machines Market
Packaging Machinery
Automatic Thermoforming Vacuum Machine Market