
 Tube Filling Machine Market | 2026-2036
Tube Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tube Filling Machine Market Outlook
Market Context
Aluminum-laminate composites is shifting from premium cosmetic tubes toward pharmaceutical barrier packaging as brands chase oxygen and moisture ingress protection. Norden Machinery leverages its Nordic engineering heritage to dominate high-speed aseptic lines for pharma injectables. Bosch Packaging sustains R&D intensity across servo-electric architectures that cut changeover times for multi-SKU contract manufacturers. GEA Group anchors its position through backward integration into dosing pump technology, capturing margin pools that pure-play machine builders cannot access.
Technical Definition and Segment Structure
A tube filling machine is an automated packaging system that doses viscous or semi-viscous products into collapsible tubes, then seals the tube tail through hot-air, ultrasonic, or crimping processes at speeds ranging from 30 to 400 tubes per minute depending on configuration. Its primary purpose is to deliver hermetic, contamination-free containment for pharmaceutical ointments, cosmetic creams, and food pastes while integrating inline coding and tamper-evident closure. Fully automatic electric systems lead unit shipments due to pharmaceutical demand for repeatable dosing accuracy and cleanroom compatibility, though semi-automatic pneumatic units retain share among artisan cosmetic producers and emerging-market chemical compounders where capital constraints limit upfront investment. Horizontal configurations are accelerating fastest in food and beverage, driven by larger-format tube demand for condiments and purees where gravity-assisted vertical filling creates air entrapment risks.
Regulatory Environment
FDA cGMP guidelines and EU GMP Annex 1 sterile manufacturing requirements shape machine design by mandating isolator integration, in-process weight verification, and electronic batch record connectivity. REACH and RoHS constraints from ECHA restrict lubricant and coating chemistries, pushing OEMs toward food-grade NSF H1 registered formulations and nickel-free wetted surfaces. Stakeholders must monitor how the EU AI Act and FDA's evolving guidance on artificial intelligence in manufacturing equipment will reshape validation protocols and software-as-a-service business models for predictive maintenance platforms.
Market Dynamics
Pharmaceutical serialization mandates are compressing equipment replacement cycles as manufacturers race to comply with track-and-trace regulations before statutory deadlines, forcing capital deployment toward integrated filling-coding systems.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization requirements for prescription medicines mandate inline printing and verification stations, pulling demand toward high-speed rotary fillers with integrated vision systems.
- Aluminum-laminate barrier migration:Oxygen-sensitive biologics and hyaluronic acid formulations require five-layer coextruded tubes, driving retrofit demand for hot-air sealing modules compatible with heat-resistant substrates.
- Contract packaging concentration:Multi-SKU pharma packers in Germany and Switzerland are consolidating production lines, favoring servo-electric machines with recipe-driven changeover protocols.
Market Restraints
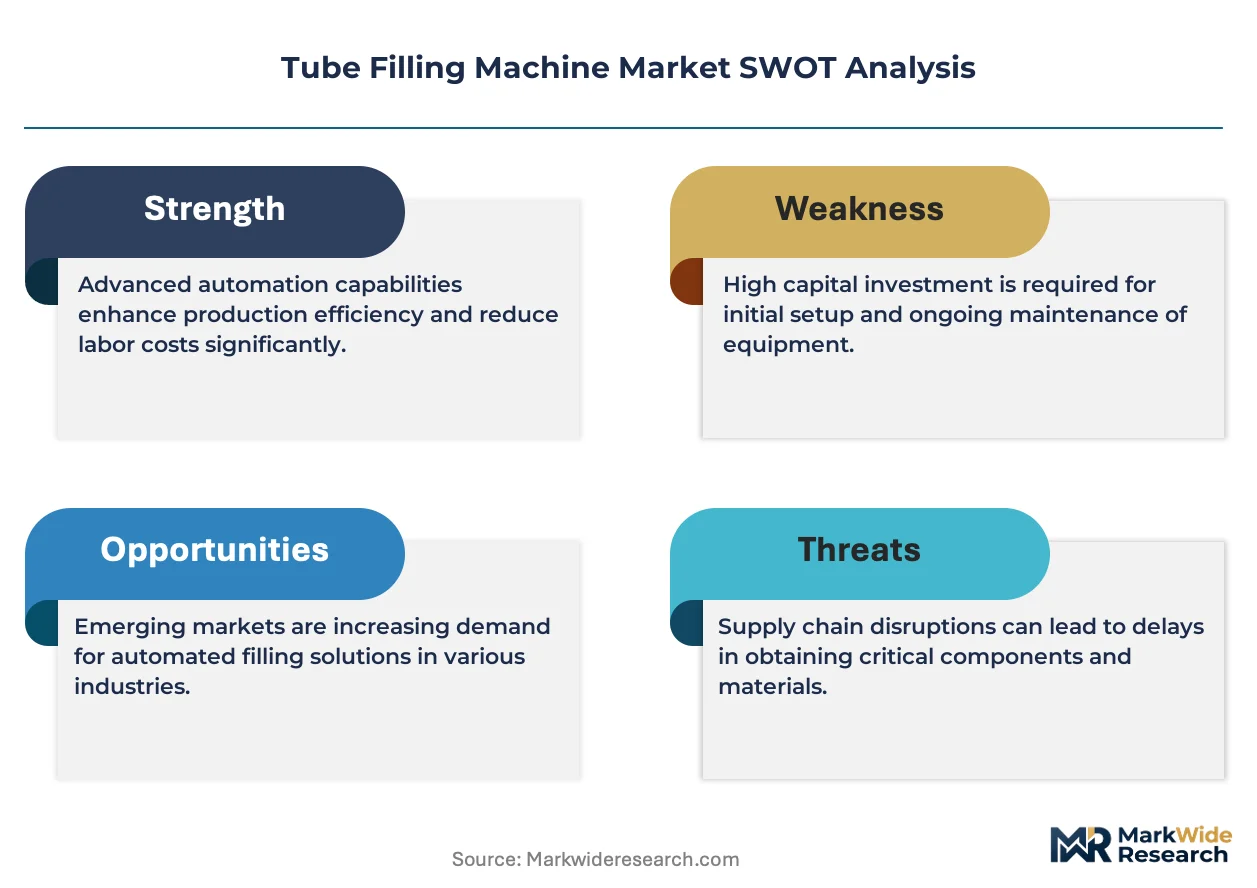
- Stainless steel input volatility:Grade 316L price swings squeeze OEM margins, forcing pass-through clauses that alienate price-sensitive emerging-market buyers.
- Precision component supply concentration:Swiss and German dosing pump specialists control high-accuracy piston technology, creating single-source vulnerability for aseptic line builders.
- Ultrasonic sealing limitation:Polyethylene tube stocks above 400 microns resist reliable weld formation, excluding the technology from food puree and industrial adhesive segments.
Strategic Opportunities
- India pharma manufacturing:CDSCO's phased serialization rollout creates first-mover advantage for suppliers offering validated turnkey lines with local service presence.
- Cell and gene therapy fill-finish:Personalized medicine batches as small as 500 units demand flexible aseptic isolators, opening premium niches beyond traditional high-volume cosmetics.
- EU AI Act compliance:Predictive maintenance platforms with embedded machine learning require revalidation frameworks, creating recurring revenue streams for software-enabled OEMs.
Industry Challenges
- Mechatronics talent scarcity:Servo programming and isolator robotics integration skills command premium wages in Stuttgart and Basel industrial clusters, constraining expansion timelines.
- Legacy pneumatic system integration:Semi-automatic lines in artisan cosmetic production lack Ethernet/IP connectivity, complicating electronic batch record implementation.
- Cleanroom certification timelines:EU GMP Annex 1 compliance validation for isolator-integrated fillers extends 18-24 months, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube Filling Machine Market |
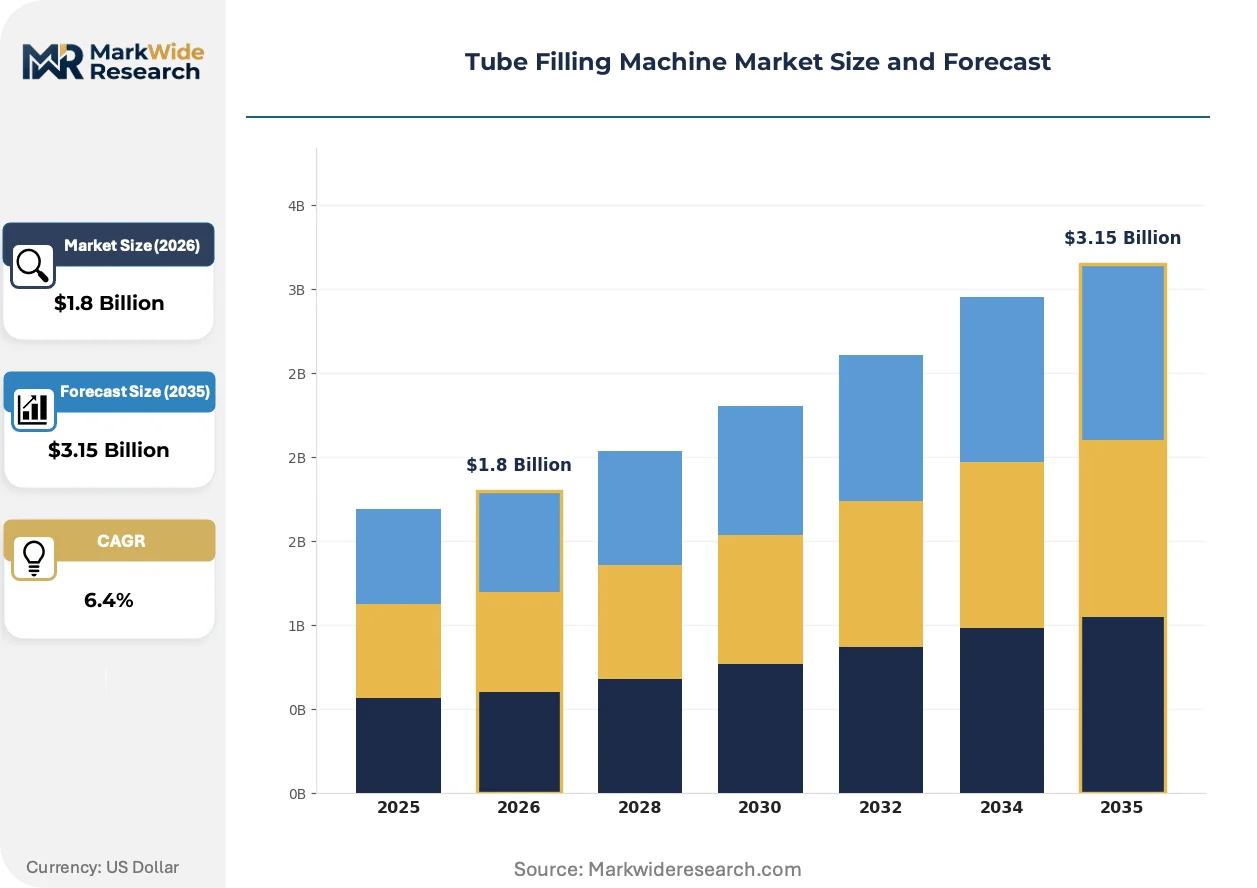
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical, Horizontal, Semi-Automatic, Fully Automatic Material: Plastic, Metal, Glass, Composite End User: Cosmetics, Pharmaceuticals, Food & Beverage, Chemicals Technology: Pneumatic, Electric, Mechanical, Hydraulic |
| Companies Covered | IMA Group, Norden Machinery, ProSys Fill, Bosch Packaging, GEA Group, Accutek Packaging Equipment Company, Axomatic, Romaco Group, Marchesini Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube Filling Machine Market Strategic Shifts
Servo-electric architectures are displacing pneumatic actuation across all throughput tiers, while regulatory pressure on data integrity and artificial intelligence validation is rewriting equipment specification criteria.
Pick-and-place robotic loading is modularizing traditional tube feeder designs, allowing pharmaceutical packers to reconfigure lines for aluminum, plastic, or laminate stocks without mechanical change parts. Mid-sized contract manufacturers in the Netherlands and Denmark are adopting these units fastest, compressing format conversion downtime from four hours to twenty minutes. The technology is modularizing what were once rigid dedicated lines into flexible multi-product assets.
REACH restrictions on perfluorinated lubricants are forcing OEMs to reformulate bearing greases and validate NSF H1 food-grade alternatives across entire machine portfolios. ECHA's 2023 PFAS restriction proposal has accelerated R&D timelines, with German and Italian builders now qualifying synthetic hydrocarbon substitutes. Aseptic pharma lines face the steepest compliance burden, as isolator environments prohibit lubricant migration risks.
Buyers are unbundling after-sales service from capital purchases, demanding subscription-based predictive maintenance with guaranteed uptime clauses rather than traditional time-and-materials contracts. Large pharmaceutical packers in Ireland and Singapore are leading this shift, pressuring machine builders to restructure revenue models. The transition is most visible in high-speed aseptic segments where unplanned downtime costs exceed ten thousand dollars per hour.
Tube Filling Machine Market Segmentation
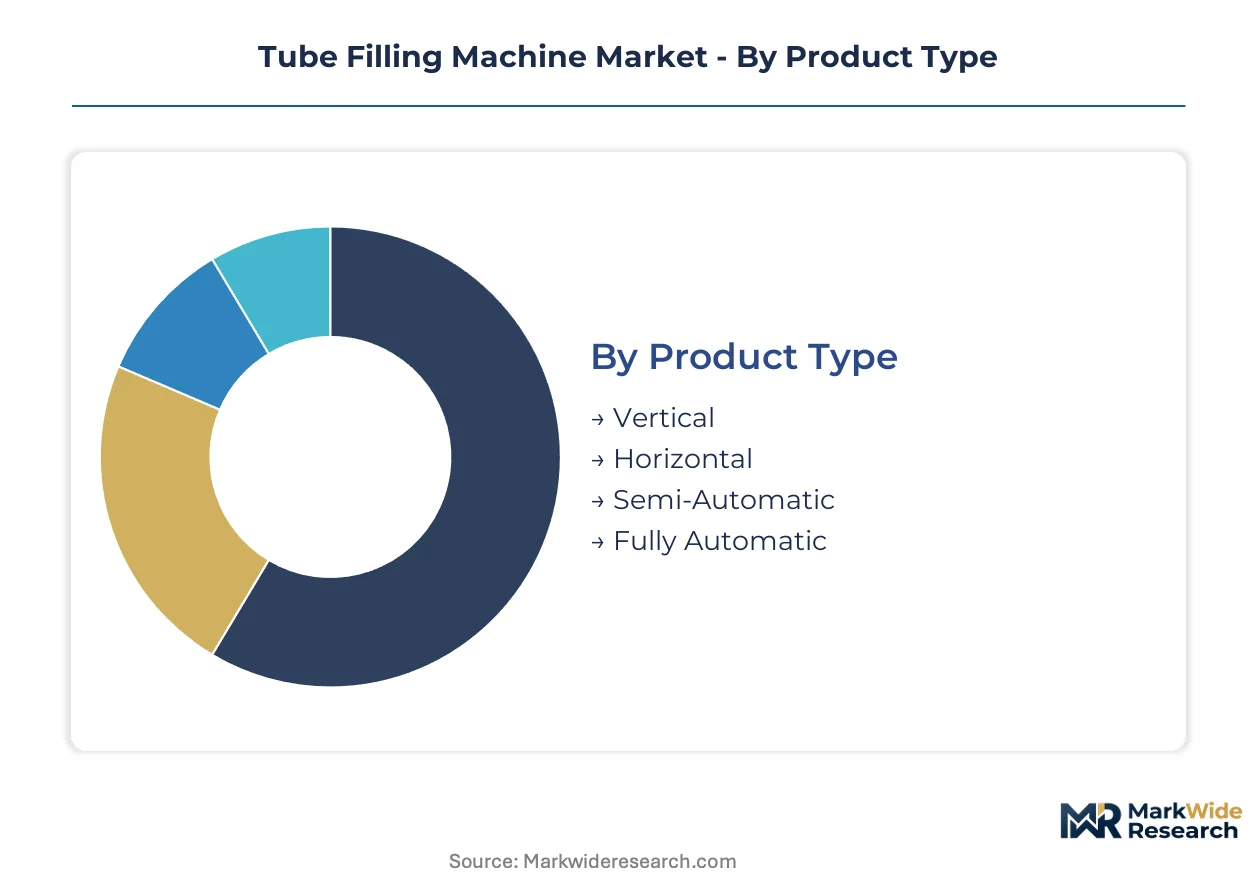
Tube filling machine procurement decisions hinge on cleanroom compatibility, dosing precision requirements, and format flexibility needs. Buyers weigh capital expenditure against regulatory validation timelines and SKU volatility in their production schedules.
Product Type:
Capital intensity and throughput requirements drive buyer selection between vertical, horizontal, and automation tiers.
- Vertical:Gravity-assisted filling architecture dominates pharmaceutical ointment production where contamination control takes priority over speed. German and Swiss contract packers specify these units for EU GMP Annex 1 compliance in sterility-critical applications.
- Horizontal:Servo-driven linear configurations handle larger-format tubes for food purees and condiments where air entrapment risks exclude vertical alternatives. Demand concentrates in Netherlands and Denmark for multi-product contract manufacturing lines.
- Semi-Automatic:Pneumatic actuation serves artisan cosmetic producers and emerging-market compounders facing capital constraints.
- Fully Automatic:Electric servo architectures deliver recipe-driven changeover for multi-SKU pharmaceutical operations.
Volume sits with Fully Automatic; growth tilts toward Horizontal.
Material:
Barrier performance specifications determine substrate selection for oxygen-sensitive and moisture-critical formulations.
- Plastic:Polyethylene and polypropylene stocks dominate mass-market cosmetics where cost efficiency outweighs barrier limitations. REACH compliance on polymer additives shapes supplier qualification in European manufacturing.
- Metal:Aluminum tubes retain pharmaceutical share for collapsible barrier properties in hyaluronic acid and biologic formulations. Swiss and German isolator-integrated lines specify metal-compatible hot-air sealing modules.
- Glass:Inert containment for high-purity chemical and specialty pharmaceutical applications.
- Composite:Five-layer coextruded aluminum-laminate structures serve oxygen-sensitive biologics requiring extended shelf stability.
Plastic captures installed base; Composite gains share fastest in pharma barrier migration.
End User:
Regulatory stringency and batch size variability create distinct equipment specification profiles across sectors.
- Cosmetics:SKU proliferation and seasonal demand volatility favor flexible servo-electric lines with rapid changeover capability. Italian and French contract packers drive specification for aesthetic finish quality in premium tube decoration.
- Pharmaceuticals:Serialization mandates under FDA DSCSA and EU Falsified Medicines Directive compress replacement cycles toward integrated filling-coding-vision systems. Aseptic isolator integration extends validation timelines 18-24 months.
- Food & Beverage:Large-format tube demand for condiments and purees accelerates horizontal configuration adoption.
- Chemicals:Corrosion-resistant wetted surfaces and explosion-proof ratings dominate specification for industrial adhesive and sealant applications.
Cosmetics holds volume leadership; Pharmaceuticals commands steepest expansion trajectory.
Technology:
Actuation architecture determines precision, energy consumption, and connectivity readiness for electronic batch records.
- Pneumatic:Compressed air systems retain position in price-sensitive emerging markets and legacy cosmetic installations lacking Ethernet/IP infrastructure for digital integration.
- Electric:Servo-electric architectures displace pneumatic alternatives across all throughput tiers for repeatable dosing accuracy and cleanroom compatibility. German OEMs anchor R&D intensity in multi-axis servo programming.
- Mechanical:Cam-driven systems persist in high-volume single-format applications where changeover flexibility carries less value.
- Hydraulic:High-force actuation for industrial chemical filling with viscous or abrasive product characteristics.
Electric dominates new investment; Pneumatic retains residual emerging-market share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's pharmaceutical special economic zones and Bavaria's precision-engineering clusters concentrate tube filling machine demand through tax-advantaged manufacturing incentives and anchor tenant effects.
Germany
Stuttgart's servo-electric engineering corridor supplies multi-SKU contract packers with recipe-driven changeover systems. EU GMP Annex 1 sterile manufacturing requirements mandate isolator integration for aseptic lines. Bosch Packaging anchors R&D intensity in Baden-Württemberg, capturing margin pools through captive dosing pump technology.
United States
FDA DSCSA serialization deadlines compress equipment replacement cycles toward integrated filling-coding-vision systems. The 2023 Drug Supply Chain Security Act enforcement triggers capital deployment in New Jersey and North Carolina pharma corridors. Irish-owned contract manufacturers in Puerto Rico specify high-speed rotary fillers with inline verification stations.
India
CDSCO's phased serialization rollout creates first-mover advantage for validated turnkey line suppliers. Maharashtra's pharma manufacturing belt in Thane and Pune drives demand for servo-electric architectures with local service presence. Gujarat's Dahej SEZ concentrates sterile injectable production, requiring aseptic isolator compatibility.
Switzerland
Swissmedic's stringent batch record requirements favor electronic connectivity in cleanroom equipment. Basel's biologics manufacturing cluster demands five-layer aluminum-laminate tube compatibility for oxygen-sensitive formulations. Norden Machinery leverages Nordic engineering heritage to dominate high-speed aseptic line specifications.
Netherlands
Horizontal configuration demand accelerates in Dutch food contract manufacturing for condiment and puree applications. Eindhoven's mechatronics ecosystem supplies pick-and-place robotic loading modules that compress format conversion downtime. Rotterdam's port logistics enable just-in-time stainless steel component supply for OEM assembly.
Tube Filling Machine Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical OEMs commanding premium positioning against price-sensitive food and cosmetic packers. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive component technology, pure-play precision engineering specialists, and regional fabricators serving emerging-market capital constraints. Consolidation pressure concentrates among mid-tier European builders facing stainless steel input volatility and precision component supply bottlenecks. Competitive moves center on backward integration into dosing pump technology and subscription-based predictive maintenance revenue restructuring.
Among diversified industrial conglomerates, GEA Group and Bosch Packaging exemplify the integrated-systems archetype through upstream control over critical subassembly technology. Norden Machinery occupies a specialist position representing Nordic precision-engineering heritage in high-speed aseptic applications. IMA Group and Marchesini Group sit within the Italian packaging machinery cluster that serves cosmetic and pharmaceutical contract manufacturers across Mediterranean and Middle Eastern markets.
| Leading Market Players |
|---|
| IMA Group |
| Norden Machinery |
| ProSys Fill |
| Bosch Packaging |
| GEA Group |
| Accutek Packaging Equipment Company |
| Axomatic |
| Romaco Group |
| Marchesini Group |
| Others |
Value Chain & Pricing Dynamics
Aseptic certification tiers bifurcate machine procurement between EU GMP Annex 1 compliant isolator-integrated lines and standard cosmetic-grade equipment, with this divergence manifesting in both capital outlay differentials and supply chain sourcing strategies that concentrate precision component procurement in German and Swiss engineering clusters while pushing commodity pneumatic systems toward Asian fabrication hubs.
Pricing Analysis
High-volume pharmaceutical serialization contracts command margins that commodity cosmetic installations cannot replicate, with servo-electric architectures priced at premiums reflecting FDA DSCSA compliance bundling. Three-tier pricing structure across premium, standard, and economy levels separates aseptic isolator lines from semi-automatic pneumatic units and refurbished legacy equipment. Cost compression in entry-level segments intensifies because stainless steel input volatility forces pass-through clauses that alienate price-sensitive emerging-market buyers. Contract packers in Germany and Switzerland exhibit lowest price sensitivity, while artisan cosmetic producers in Southern Europe and Southeast Asian compounders face acute capital constraints.
Supply Chain Analysis
EU GMP Annex 1 qualification requirements gate component supply to Swiss and German dosing pump specialists whose piston technology dominates aseptic line specifications. Machine fabrication draws from stainless steel mills in Germany and Italy, servo drives from Japanese and German motion control specialists, and isolator-grade sealing materials from Nordic polymer suppliers. Single-source vulnerability concentrates in high-accuracy piston pump technology where Swiss specialists control critical intellectual property. Distribution runs through OEM direct sales for pharmaceutical accounts and regional distributor networks serving emerging-market cosmetic producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo-electric actuation is displacing pneumatic systems across all throughput tiers, compressing replacement cycles for legacy installations and rewriting equipment specification criteria for multi-SKU contract manufacturers.
For Market Incumbents: Acquire captive dosing pump technology to defend margin pools that pure-play machine builders cannot access. Bosch Packaging and GEA Group exemplify this backward integration strategy. Consolidate mid-tier European builders facing stainless steel input volatility before precision component supply bottlenecks deepen. Threat substitution from subscription-based predictive maintenance platforms requires restructuring revenue models away from time-and-materials contracts toward guaranteed uptime clauses. For New Entrants and Emerging Players: Predictive maintenance software with embedded machine learning offers technology-first entry into pharmaceutical accounts where unplanned downtime costs exceed ten thousand dollars per hour. White-space targets include CDSCO-validated turnkey lines for India's phased serialization rollout and flexible aseptic isolators for cell and gene therapy fill-finish batches as small as five hundred units. Go-to-market leverage rests on local service presence in Maharashtra's Thane-Pune pharma belt rather than equipment-only sales. For Investors and Strategic Acquirers: Re-rating potential sits with software-enabled OEMs given EU AI Act compliance requirements for predictive maintenance platform revalidation. Long-term viability favors suppliers with recurring revenue streams from subscription-based service models over pure equipment vendors exposed to capital expenditure cyclicality. Acquisition target archetype: mid-cap specialists with isolator integration capabilities and existing pharmaceutical validation track records. Signal to watch: CDSCO enforcement acceleration triggering Indian pharma capital deployment toward validated lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dosing Pump Technology | Captures margin pools in aseptic pharmaceutical lines that pure-play builders cannot access. |
| Subscription-Based Predictive Maintenance Launch | Restructures revenue models toward recurring streams with guaranteed uptime clauses for Irish and Singaporean packers. |
| Aseptic Isolator Integration for Cell and Gene Therapy | Opens premium niches beyond high-volume cosmetics for personalized medicine batches under five hundred units. |
| Local Service Presence Establishment in India | Captures first-mover advantage during CDSCO's phased serialization rollout in Maharashtra's pharma belt. |
| NSF H1 Food-Grade Lubricant Reformulation | Ensures REACH compliance across entire machine portfolios as ECHA's PFAS restrictions tighten. |
Study Parameters
Multi-period observation of pharmaceutical serialization mandate timelines, servo-electric adoption rates, and isolator integration lead times anchored the trend analysis, supplemented by interviews with maintenance directors at German contract packers, plant engineers at Swiss biologics manufacturers, OEM procurement teams in Italy, and aftermarket service heads in India. Secondary validation drew from FDA DSCSA guidance documents, EU GMP Annex 1 sterile manufacturing requirements, ECHA REACH restriction proposals, and SEC filings of diversified industrial conglomerates. Bottom-up equipment shipment tracking triangulated against top-down pharmaceutical capital expenditure surveys.
Input-output matrices modeled tube filling machine demand across product type, material substrate, end-user industry, and actuation technology dimensions throughout the forecast period. CAGRs were derived from segmented growth rate analysis calibrated to regulatory deadline impacts and technology substitution curves. Industry-specific forecast inputs included CDSCO serialization phase timelines, EU AI Act validation protocol evolution, and stainless steel price elasticity coefficients for OEM margin modeling.
Several conditions sit outside the modeled scope, including unannounced regulatory deadline extensions, breakthrough ultrasonic sealing technologies for polyethylene stocks above four hundred microns, and geopolitical disruptions to Swiss-German precision component supply chains. Forecasts reflect documented assumptions about pharmaceutical compliance spending persistence and cosmetic capital constraint continuity. A model refresh is warranted upon material change in FDA DSCSA enforcement intensity or ECHA PFAS restriction finalization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Combination Filler Machine Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Wet Ink Coding Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Flow Pack Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Barcode Labeller Machine Market
Packaging Machinery
Global Pet Stretch Blow Molding Machines Market
Packaging Machinery
Stick Pack Packaging Machine Market
Packaging Machinery
Oral Dosage Powder Packaging Machines Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Tray Sealer Machines Market