
 Packet Optical Networking Market | 2026-2036
Packet Optical Networking Market Size, Share, and Industry Trends Forecast 2026-2036
Packet Optical Networking Market Analytics
Multi-source optical component procurement is consolidating around vertically integrated platform vendors with captive silicon and software stacks. Ciena Corporation leverages its WaveLogic coherent DSP portfolio to anchor high-margin submarine and terrestrial deployments. Huawei Technologies Co Ltd competes through end-to-end optical-electrical convergence spanning transport, access, and control plane layers. Nokia Corporation differentiates via its PSE-V family and Bell Labs R&D pipeline sustaining intercontinental bandwidth scaling.
Packet optical networking fuses photonic transport with MPLS-TP and Ethernet switching at line rates from 100G to 800G, enabling converged infrastructure that collapses separate IP and optical layers into unified programmable fabrics. Dense Wavelength Division Multiplexing dominates capital deployment for long-haul and metro core routes where fiber scarcity demands maximum spectral efficiency. Ethernet technology is displacing legacy TDM interfaces in data center interconnects, while Multi-Protocol Label Switching persists in carrier VPN and traffic engineering applications requiring deterministic path control.
FCC open internet and spectrum coordination rules shape US carrier transport investment timing, while EU CSRD and F-Gas Regulation mandate energy transparency and sustainable cooling in optical infrastructure procurement. ETSI and IEEE 802.3 standards bodies are accelerating 800ZR and beyond-coherent interoperability specifications. Stakeholders must monitor open line system maturity against proprietary integrated platforms as the central procurement trade-off.
Market Dynamics
Open optical line system standards from the OIF and TIP are collapsing the traditional vendor lock-in model that has structured carrier procurement for decades, forcing incumbents to unbundle hardware from software control planes.
Growth Catalysts
- AI-driven traffic loads:Cloud service providers in the United States are scaling packet-optical backbones to support machine learning workloads. Hyperscale data centers now require 800G coherent transport between facilities.
- EU CSRD mandates:The Corporate Sustainability Reporting Directive requires energy transparency in optical infrastructure procurement. German carriers including Deutsche Telekom are modernizing core networks ahead of compliance deadlines.
- 800ZR standardization:IEEE 802.3 specifications for beyond-coherent interoperability are enabling multi-vendor deployments. ETSI acceleration of these standards reduces integration friction for network operators.
Market Restraints
- Coherent DSP supply concentration:Advanced digital signal processors for 800G systems depend on a limited supplier base in Taiwan and the United States. Foundry capacity constraints extend lead times for critical components.
- F-Gas Regulation compliance costs:The EU mandate for sustainable cooling in optical infrastructure adds capital expenditure for thermally efficient chassis designs. German and French carriers face accelerated replacement cycles.
- Fiber scarcity in metro cores:Dense urban environments in Japan and South Korea lack available conduit for new cable deployment. Existing duct infrastructure forces spectral efficiency upgrades rather than fiber additions.
Strategic Opportunities
- Submarine cable upgrades:Trans-Pacific and trans-Atlantic routes require 400G to 800G coherent upgrades. Open cable consortiums are disaggregating terminal equipment from wet plant assets.
- India's BharatNet expansion:The country's rural broadband initiative creates demand for converged packet-optical access platforms. State-run BSNL and private operators are tendering for unified transport solutions.
- Photonic-electronic convergence:Silicon photonics integration with switch ASICs enables co-packaged optics in data centers. Cloud operators in the United States are piloting this architecture for power efficiency gains.
Industry Challenges
- Coherent optical engineering talent scarcity:DSP algorithm development and forward error correction expertise concentrates among specialists in Finland, Canada, and the United States. Carriers struggle to staff network planning functions.
- Multi-vendor integration complexity:Open line system deployments require verification across transponder, ROADM, and amplifier combinations. Interoperability testing extends deployment timelines for tier-two operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packet Optical Networking Market |
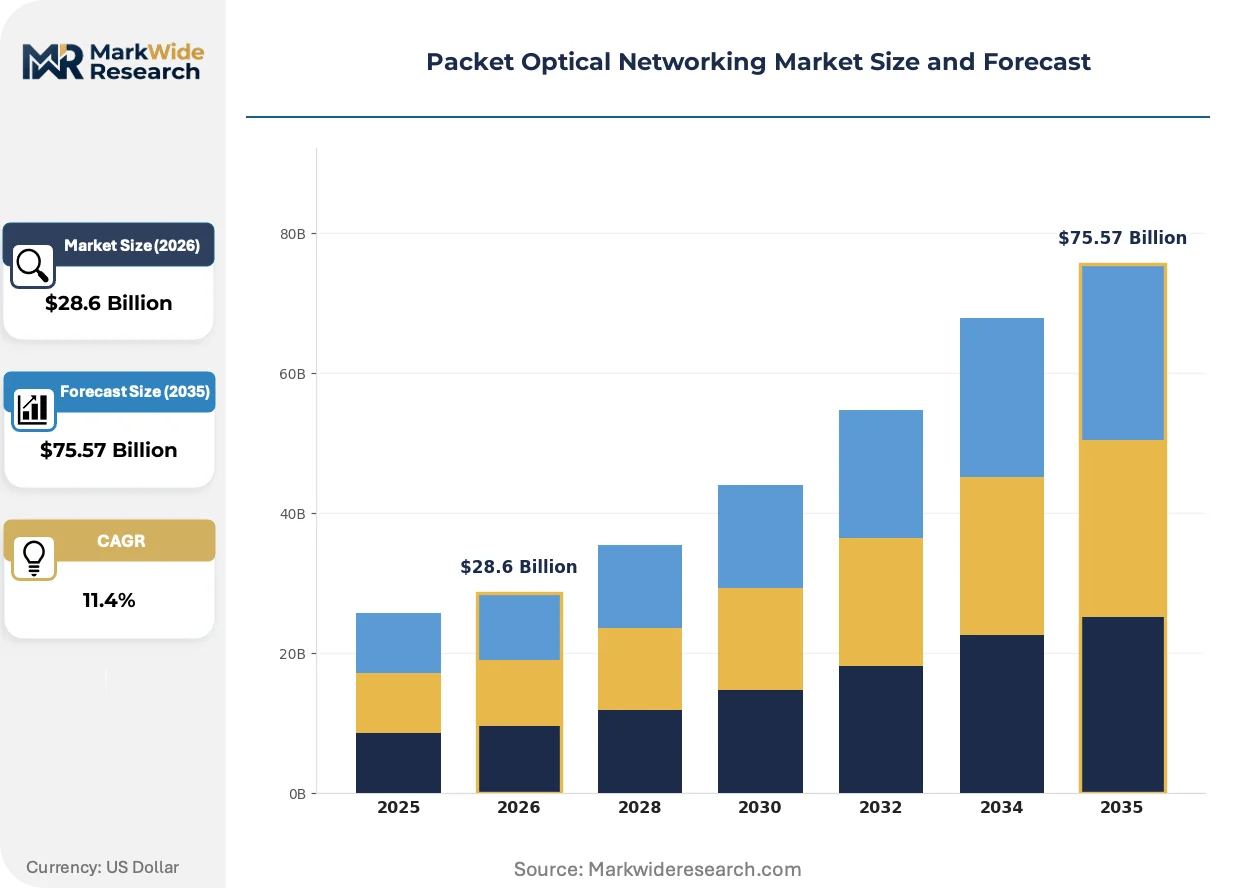
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Transport Network, Wavelength Division Multiplexing, Dense Wavelength Division Multiplexing, Packet-Optical Transport Technology: Ethernet, Multi-Protocol Label Switching, Optical Circuit Switching, Packet Switching End User: Telecommunications Providers, Data Centers, Enterprises, Cloud Service Providers Application: Bandwidth Management, Network Monitoring, Traffic Engineering, Virtualization |
| Companies Covered | Huawei Technologies Co Ltd, Ciena Corporation, Nokia Corporation, Cisco Systems Inc, ZTE Corporation, Fujitsu Limited, Juniper Networks Inc, Mitsubishi Electric Corporation, Ericsson AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packet Optical Networking Market Evolving Landscape
Packet optical networking is undergoing architectural transformation as programmable silicon, open disaggregation, and sustainability mandates rewrite procurement criteria across carrier and cloud segments.
Coherent pluggable optics operating at 400G and 800G is converging with switch-router platforms to collapse traditional transponder shelf architectures. Cloud operators in the United States are deploying ZR and ZR+ modules directly into switch faceplates. This convergence is compressing capital intensity per gigabit while eliminating separate optical transport layers.
The EU F-Gas Regulation and CSRD disclosure requirements are mandating refrigerant-free cooling and embodied carbon reporting for network equipment. Vendors must now certify thermal designs and supply chain emissions to qualify for German and French carrier tenders. Submarine and terrestrial system manufacturers are responding with liquid-cooled chassis and modular power architectures.
Hyperscale buyers are consolidating vendor relationships around vertically integrated platform suppliers with captive silicon and software stacks. Traditional best-of-breed procurement for optical transport is yielding to single-source accountability for performance guarantees. This concentration is most visible in North American cloud provider RFPs, where operational simplicity outweighs multi-vendor price competition.
Packet Optical Networking Market Segmentation
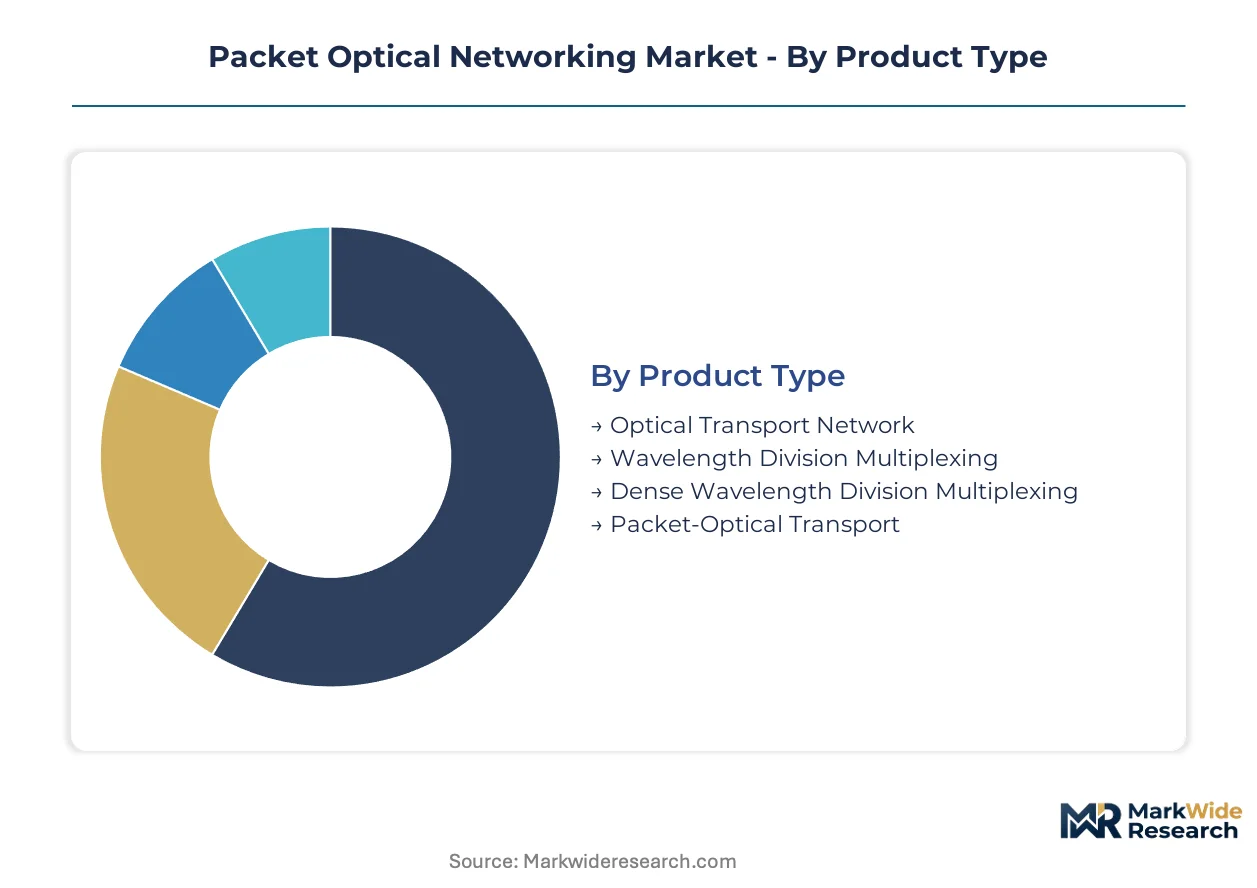
Packet optical networking procurement diverges sharply between volume-driven metro deployments and premium long-haul systems. Segmentation reveals where coherent DSP investments concentrate versus where commoditized pluggable optics displace traditional transponder shelves.
Product Type:
Volume deployments favor integrated platforms, while premium routes demand spectral efficiency maximization.
- Optical Transport Network:Legacy SDH/SONET-derived framing persists in carrier wholesale services requiring deterministic latency. Deutsche Telekom maintains OTN switching layers for enterprise SLA guarantees despite Ethernet encroachment.
- Wavelength Division Multiplexing:CWDM dominates access fiber relief and enterprise campus interconnects where cost-per-channel outweighs spectral density requirements. Regional carriers in Germany deploy these systems for last-mile fiber extension.
- Dense Wavelength Division Multiplexing:C-band and L-band coherent systems achieve 96+ channels per fiber pair. Submarine cable operators and tier-one carriers deploy these for transcontinental routes where fiber scarcity commands maximum spectral efficiency.
- Packet-Optical Transport:MPLS-TP and segment routing integration collapses IP and optical layers into unified fabrics. Cloud service providers in the United States specify these platforms for data center interconnects requiring sub-50ms protection switching.
Today's leader: Dense Wavelength Division Multiplexing. Tomorrow's challenger: Packet-Optical Transport.
Technology:
Carrier control plane requirements sustain MPLS relevance even as Ethernet dominates data center interconnect economics.
- Ethernet:400G and 800G ZR/ZR+ pluggable modules disaggregate optical transport from dedicated transponder hardware. Hyperscale operators deploy these directly into switch faceplates for power and space efficiency.
- Multi-Protocol Label Switching:Traffic engineering and VPN segregation capabilities preserve MPLS in carrier cores despite simpler Ethernet alternatives. Deterministic path control satisfies financial services latency requirements.
- Optical Circuit Switching:All-optical bypass eliminates electronic regeneration for express wavelengths. Submarine cable landing stations deploy these for power reduction on transoceanic routes.
- Packet Switching:Statistical multiplexing gains maximize utilization for bursty cloud traffic. Metro aggregation nodes employ these for oversubscribed access convergence.
Deployment concentration: Ethernet in cloud facilities, MPLS in carrier cores.
End User:
Procurement sophistication separates hyperscale self-builders from carrier managed service providers.
- Telecommunications Providers:Incumbent operators modernize multi-layer networks under regulatory pressure. Open line system adoption accelerates as OIF standards mature.
- Data Centers:Colocation facilities demand converged packet-optical platforms for cross-connect automation. Latency-sensitive financial trading venues specify deterministic transport.
- Enterprises:Large manufacturers and healthcare systems procure managed wavelength services rather than capital equipment. Private optical networks concentrate in campus environments with fiber ownership.
- Cloud Service Providers:AWS, Google Cloud, and Microsoft Azure drive 800G coherent demand through direct switch integration. These buyers specify thermal and power requirements that reshape vendor roadmaps.
Volume anchor: Telecommunications Providers. Margin concentration: Cloud Service Providers.
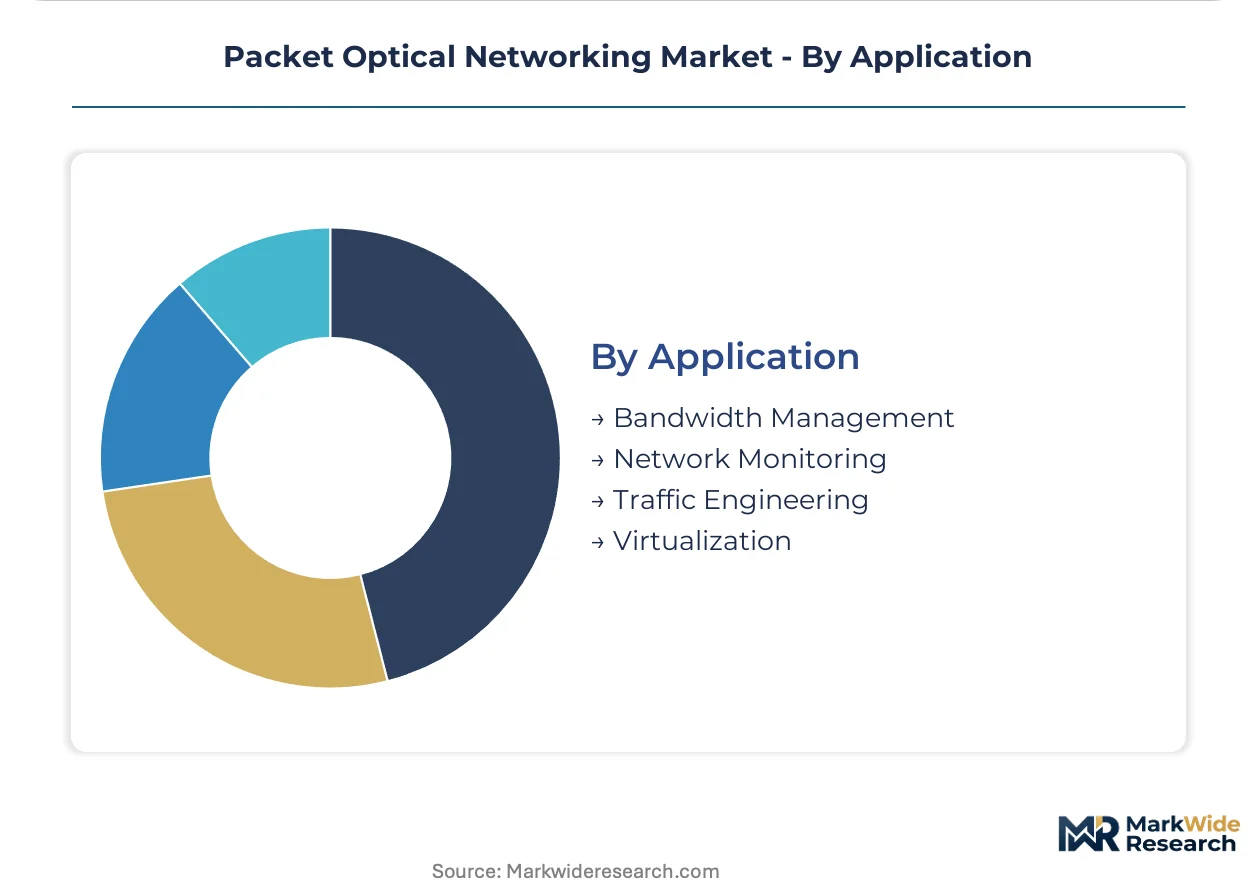
Application:
Operational complexity determines whether buyers prioritize automation or raw transport capacity.
- Bandwidth Management:Dynamic optical layer provisioning responds to traffic fluctuations without manual intervention. Software-defined control planes enable bandwidth-on-demand services.
- Network Monitoring:Coherent DSP telemetry provides per-wavelength optical signal-to-noise ratios without dedicated test equipment. This capability reduces truck rolls for fault isolation.
- Traffic Engineering:Explicit path computation optimizes latency and diversity for critical flows. Financial exchange connectivity and 5G fronthaul specify these capabilities.
- Virtualization:Network function virtualization disaggregates control plane software from transport hardware. Carriers evaluate cloud-native optical controllers against traditional embedded systems.
Current investment priority: Bandwidth Management. Emerging requirement: Virtualization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley hyperscale campuses anchor coherent optical demand through 800G switch integration and submarine cable terminal investments. Cloud operators in the United States specify thermal and power requirements that reshape vendor roadmaps across terrestrial and trans-Pacific routes.
United States
AWS, Google Cloud, and Microsoft Azure drive 800G coherent procurement through direct switch integration. FCC open internet and spectrum coordination rules shape carrier transport investment timing. Northern Virginia data center clusters concentrate ZR and ZR+ pluggable deployments for power efficiency gains.
Germany
Deutsche Telekom and regional carriers modernize core networks ahead of EU digital sovereignty targets. The EU F-Gas Regulation and CSRD mandate sustainable cooling and embodied carbon reporting in optical infrastructure procurement. Munich and Frankfurt data center hubs concentrate packet-optical transport platform deployments for enterprise SLA guarantees.
China
State-run operators expand converged packet-optical access platforms for rural broadband and 5G fronthaul. MIIT standards and dual carbon goals accelerate domestic coherent DSP development and silicon photonics integration. Beijing and Shanghai metro cores deploy high-density DWDM systems for fiber scarcity relief.
Japan
NTT and KDDI upgrade submarine cable landing stations with liquid-cooled chassis for trans-Pacific bandwidth scaling. METI energy efficiency guidelines drive thermally efficient chassis designs in optical infrastructure. Tokyo and Osaka metro areas face fiber scarcity forcing spectral efficiency upgrades over new fiber deployment.
India
BSNL and private operators tender for unified transport solutions under the BharatNet rural broadband initiative. TRAI spectrum and infrastructure sharing rules shape carrier procurement cycles for converged platforms. Bangalore and Hyderabad technology corridors concentrate data center interconnect demand from cloud service provider expansion.
Packet Optical Networking Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue silicon photonics integration and open line system disaggregation. The vendor base concentrates around vertically integrated platform suppliers with captive silicon and software stacks. Three archetypes dominate: coherent DSP specialists anchoring high-margin submarine deployments, end-to-end optical-electrical convergers spanning transport and access layers, and programmable silicon vendors collapsing IP and optical layers. Competitive moves center on strategic partnerships for multi-vendor interoperability testing and portfolio diversification into pluggable optics.
Within the vertically integrated tier, Huawei Technologies Co Ltd and Ciena Corporation exemplify divergent approaches to market positioning. Huawei Technologies Co Ltd occupies a position spanning transport, access, and control plane layers through end-to-end optical-electrical convergence. Ciena Corporation anchors high-margin submarine and terrestrial deployments through coherent DSP portfolio specialization. Nokia Corporation sits within the programmable silicon tier, differentiating via sustained intercontinental bandwidth scaling investments.
| Leading Market Players |
|---|
| Huawei Technologies Co Ltd |
| Ciena Corporation |
| Nokia Corporation |
| Cisco Systems Inc |
| ZTE Corporation |
| Fujitsu Limited |
| Juniper Networks Inc |
| Mitsubishi Electric Corporation |
| Ericsson AB |
| Others |
Value Network & Pricing Analysis
Coherent DSP algorithm specialists concentrated in Finland, Canada, and the United States command compensation premiums that widen pricing spreads between premium submarine systems and economy metro access platforms. Labor-cost differentials for forward error correction expertise and silicon photonics integration directly stratify vendor pricing tiers across carrier procurement cycles.
Pricing Analysis
Input-cost pass-through from Taiwan and United States foundry constraints tightens margins on 800G coherent DSP modules. Three-tier pricing structure across premium submarine, standard long-haul, and economy metro access levels separates Ciena and Huawei from commodity pluggable vendors. Price differentiation rests on captive silicon ownership and software control plane integration. Cost compression in economy metro tiers intensifies because ZR/ZR+ module commoditization eliminates separate transponder shelf architectures. Hyperscale cloud operators exhibit lowest price sensitivity; tier-two regional carriers face acute budget constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for 800G switch-integrated optics, while systems integrators serve carrier managed service procurement. Geographic supply concentration centers on Taiwan for advanced DSP foundry capacity, the United States for coherent algorithm development, and China for optical component assembly. Raw material dependencies include indium phosphide substrates, silicon photonics wafers, and rare-earth doped fiber amplifiers. Single-source vulnerability in Taiwan DSP foundries exposes lead time volatility for 800G module production. Distribution runs through vendor-direct relationships for cloud operators and tier-one carriers, with channel partners covering enterprise and mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation and CSRD disclosure mandates accelerate carrier replacement cycles and reshape vendor qualification criteria.
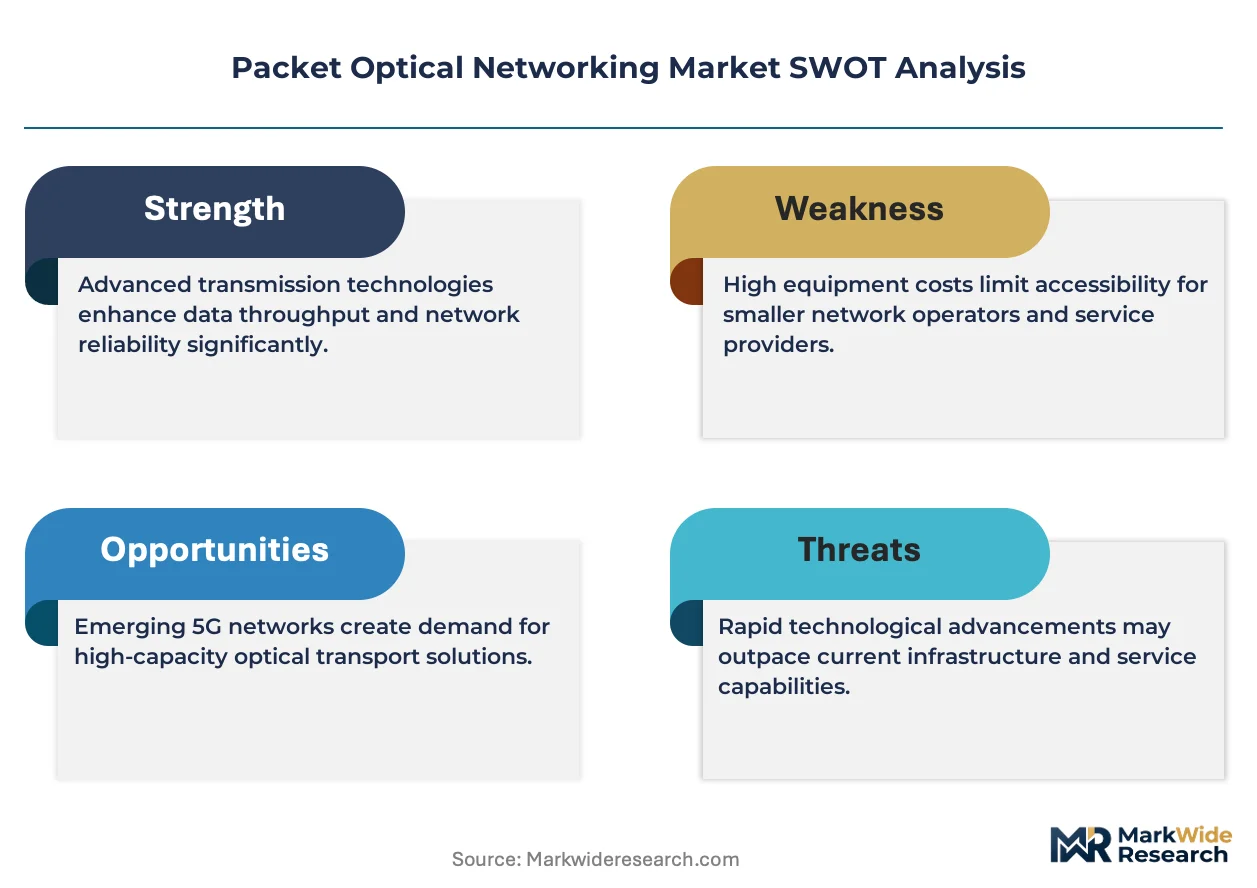
For Market Incumbents: Deepen captive silicon roadmaps to defend margin position against open line system disaggregation. Prioritize liquid-cooled chassis certification for German and French carrier tenders. Incumbent vendors face substitution threat from pluggable ZR/ZR+ modules collapsing traditional transponder architectures; vertical integration into coherent DSP design remains the critical defensive lever. For New Entrants and Emerging Players: The 40-60% price-point gap between premium submarine systems and economy metro access creates white-space opportunity for silicon photonics specialists. Target India's BharatNet rural broadband initiative for converged packet-optical access platform penetration. Pursue multi-vendor interoperability certification as primary go-to-market angle against vertically integrated incumbents. For Investors and Strategic Acquirers: Cloud service providers are the most active acquirer in this space through direct vertical integration into optical transport layers. Long-term viability favors coherent DSP specialists with submarine cable relationships and programmable silicon vendors collapsing IP-optical convergence. Watch open line system maturity against proprietary integrated platforms as inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Integration | Co-packaged optics in hyperscale data centers reduces power consumption per gigabit for AWS and Google Cloud deployments. |
| Open Line System Certification | OIF and TIP standard compliance enables multi-vendor procurement for Deutsche Telekom and regional carrier networks. |
| Liquid-Cooled Chassis Development | F-Gas Regulation compliance qualifies vendors for German and French sustainable infrastructure tenders. |
| 800ZR Module Production Scale-Up | IEEE 802.3 interoperability reduces integration friction for cloud operator switch-integrated deployments. |
| Submarine Cable Terminal Upgrade | Trans-Pacific route modernization demands 400G to 800G coherent upgrades from NTT and KDDI. |
Research Methodology
Bottom-up cloud operator and carrier procurement modeling reconciled against top-down coherent DSP and optical component supply tracking forms the analytical core. Primary interviews with network planning engineers, optical transport procurement leads, hyperscale infrastructure architects, and submarine cable system integrators combined with secondary validation. Secondary sources include FCC spectrum coordination filings, EU CSRD disclosure databases, ETSI standard development records, IEEE 802.3 working group documentation, and vendor hyperscaler capex disclosures. Triangulation across stakeholder inputs and published regulatory mandates ensures segment-level accuracy.
Input-output matrices map coherent DSP foundry capacity, pluggable optics module production, and carrier capital expenditure cycles against end-use demand from cloud data center interconnect and 5G transport buildouts. Segmentation dimensions modeled include product type, technology protocol, end-user category, and application function across the projection horizon. CAGRs derive from supply-side capacity expansion schedules and demand-side traffic growth assumptions. Industry-specific forecast inputs include AI-driven bandwidth scaling trajectories and EU digital sovereignty compliance deadlines.
Caveats apply where Taiwan foundry capacity constraints, EU F-Gas Regulation enforcement timing, or open line system interoperability delays could materially shift the outlook. Forecasts reflect base-case assumptions regarding standards maturation and carrier procurement cycle normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Information and Communication Technology
Enterprise Routers Market
Information and Communication Technology
Know Your Customer Software Market
Information and Communication Technology
Saudi Arabia Telecom Market
Information and Communication Technology
Articulated Robots for Injection Molding Machine Market
Information and Communication Technology
Landing Page Creation Software Market
Information and Communication Technology
Next Generation Network (NGN) Equipment Market
Information and Communication Technology
Data Integration Market
Information and Communication Technology
Architectural Rendering Software Market
Information and Communication Technology
Discount Management Software Market
Information and Communication Technology
Global IoT Routers Market
Information and Communication Technology
Global Business Card Software Market
Information and Communication Technology
Global Application Transformation Market
Information and Communication Technology
Smart Shelf Market
Information and Communication Technology
Financial Corporate Performance Management (FCPM) Software Market
Information and Communication Technology
Blockchain-As-A-Service (Baas) Market
Information and Communication Technology
Manufacturing Quoting and Estimating Software Market