
 Global Process Instrumentation Market | 2026-2036
Global Process Instrumentation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Process Instrumentation Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for European suppliers by mandating substance disclosure across sensor supply chains. Emerson Electric Co. leverages its Rosemount manufacturing footprint to sustain calibration service dominance across North American refineries. Siemens AG anchors its position through Sitrans product lines that specialize in electromagnetic flow measurement for water utilities. Endress+Hauser AG differentiates via Memosens digital sensor technology that controls premium positioning in hygienic process applications.
Process instrumentation encompasses devices that measure pressure, temperature, flow, and level variables with specified accuracy classes, converting physical parameters into standardized signals for industrial control systems. These instruments employ piezoelectric, thermocouple, Coriolis, or radar sensing principles to enable closed-loop process optimization across continuous and batch operations. Pressure transmitters occupy the largest product category due to universal deployment in hydrocarbon processing, while smart sensors represent the fastest-expanding technology segment as IO-Link and HART-IP protocols displace analog wiring. Flow meters concentrate margin pools in custody-transfer applications where metrological certification commands pricing premiums.
The EPA enforces emissions monitoring requirements under Clean Air Act provisions that mandate continuous parameter tracking at major industrial sources. EMA pharmaceutical manufacturing guidelines and FDA process analytical technology frameworks both drive validated instrument specifications in drug production environments. IEC 61508 functional safety standards shape product development priorities for safety instrumented systems. Stakeholders must weigh digital twin integration roadmaps against legacy 4-20 mA infrastructure replacement cycles when allocating capital across plant modernization programs.
Market Dynamics
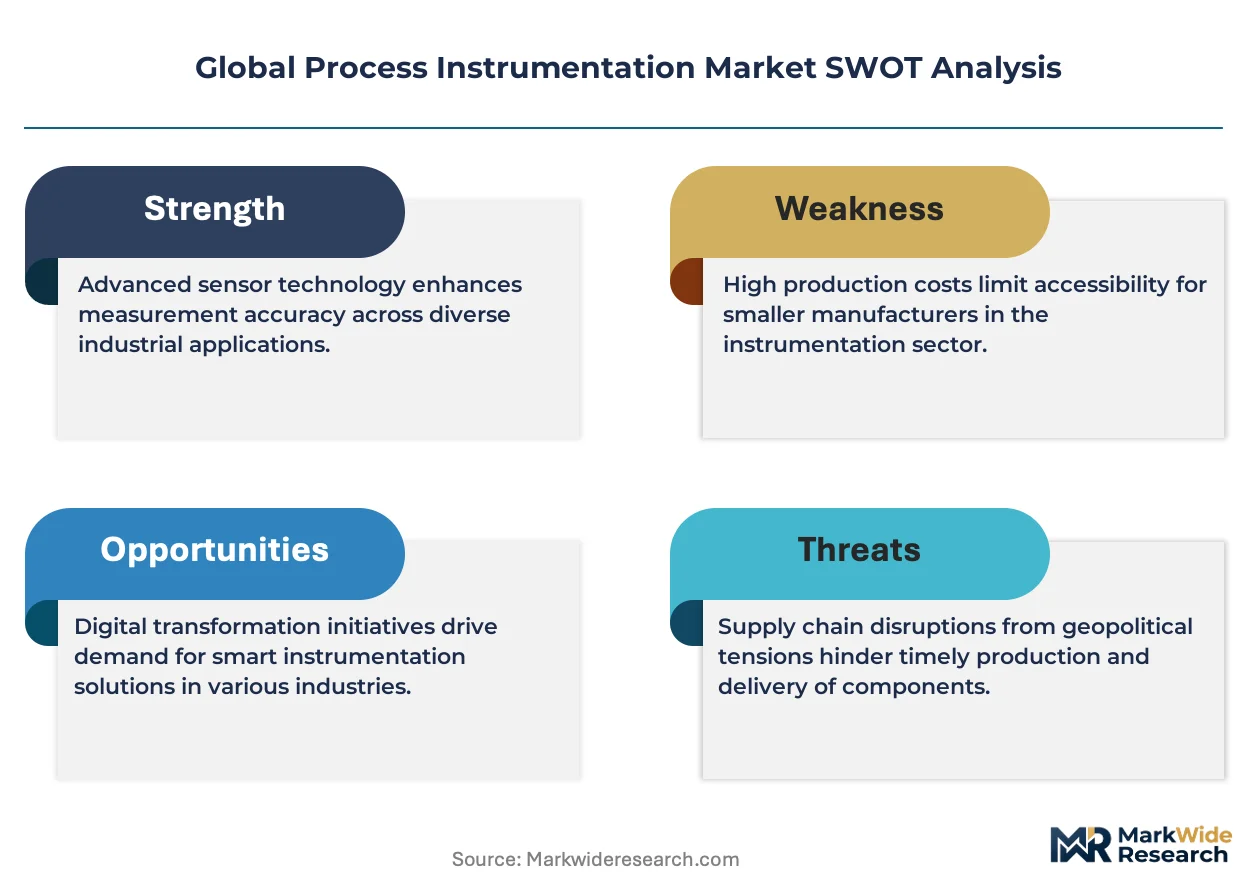
Digital protocol migration is compressing analog infrastructure replacement cycles across process industries, forcing simultaneous capital allocation toward IO-Link and HART-IP architectures while legacy 4-20 mA networks remain operational.
Growth Catalysts
- EU Green Deal emissions mandates:Chemical producers in Germany are deploying continuous monitoring architectures to satisfy real-time reporting requirements for Scope 1 and Scope 2 emissions.
- Shale modernization cycles:United States wellhead operators are replacing mechanical gauges with wireless pressure transmitters to enable remote monitoring of distributed assets.
- Pharmaceutical process analytical technology:FDA frameworks for real-time quality verification are driving validated instrument specifications in active pharmaceutical ingredient manufacturing.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium dependencies on Chinese processing infrastructure create vulnerability in Coriolis flow meter production.
- REACH substance disclosure burdens:ECHA compliance costs for sensor supply chain transparency disproportionately burden mid-tier European suppliers against Asian competitors.
- Silicon carbide wafer scarcity:Limited 150mm substrate availability constrains MEMS pressure sensor foundry capacity expansion.
Strategic Opportunities
- India water infrastructure buildout:Central Electricity Authority mandates for smart grid instrumentation extend to municipal water distribution monitoring in tier-2 cities.
- Hydrogen economy metrology gaps:Custody-transfer flow measurement for high-pressure hydrogen remains uncertified, creating first-mover advantage for ultrasonic technology developers.
- Digital twin integration:Convergence of physics-based simulation with live sensor feeds enables predictive maintenance contracts in refining operations.
Industry Challenges
- IEC 61508 functional safety certification:Safety instrumented system validation timelines extend 18-24 months, delaying product launches for safety-critical pressure transmitter lines.
- Fieldbus protocol fragmentation:Proliferation of competing industrial Ethernet standards forces redundant hardware development to maintain interoperability across customer installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Process Instrumentation Market |
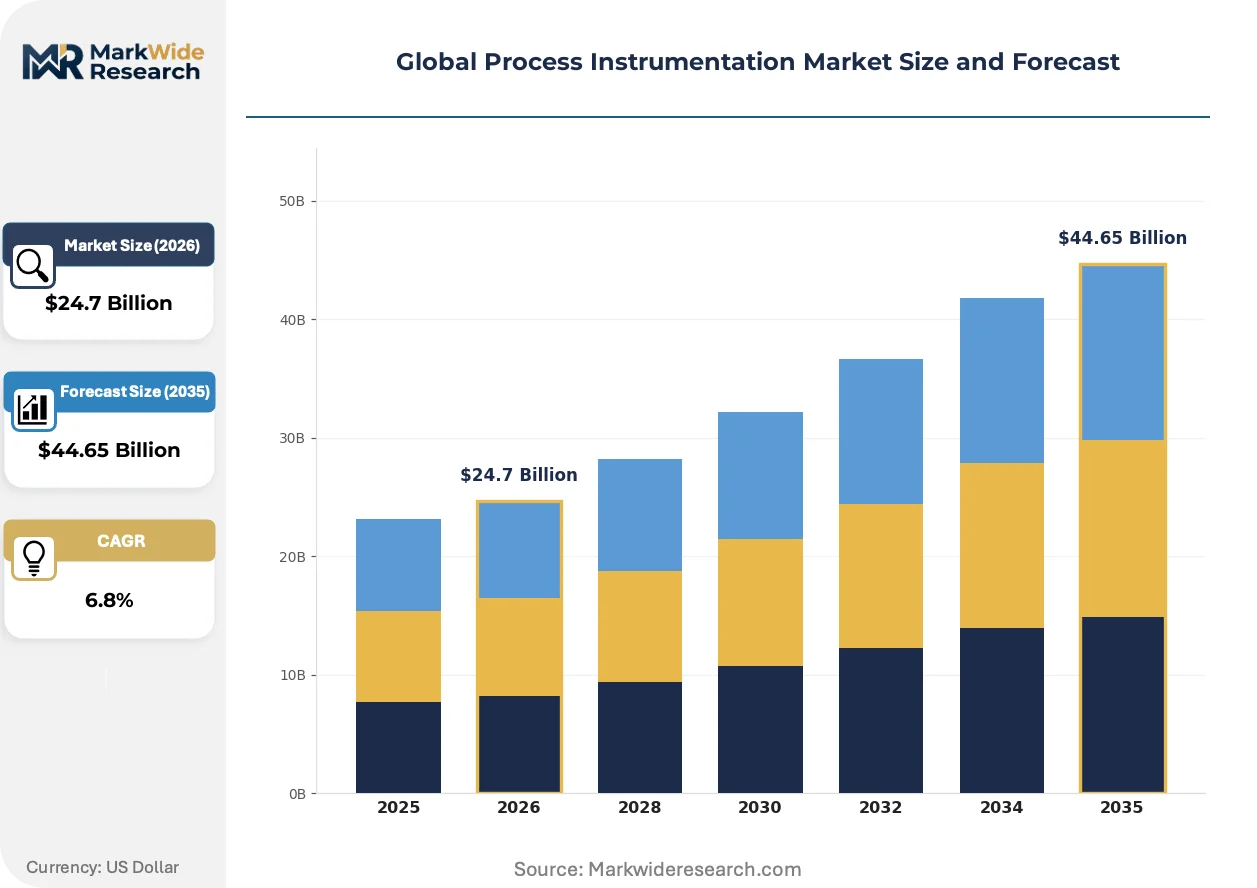
| Market Size in 2026 | $24.7 Billion |
| Market Size in 2035 | $44.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Transmitters, Temperature Sensors, Flow Meters, Level Sensors End User: Manufacturing, Oil & Gas, Water & Wastewater, Chemical Technology: Smart Sensors, Wireless Technology, Optical Measurement, Electromagnetic Application: Process Control, Quality Assurance, Environmental Monitoring, Safety Systems |
| Companies Covered | Emerson Electric Co., Siemens AG, Honeywell International Inc., ABB Ltd., Schneider Electric SE, Yokogawa Electric Corporation, Endress+Hauser AG, Rockwell Automation Inc., Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Process Instrumentation Market Strategic Shifts
Protocol standardization is eliminating analog wiring architectures across greenfield process installations, compressing commissioning timelines while demanding simultaneous cybersecurity hardening of edge devices.
MEMS-based pressure sensing is consolidating discrete mechanical transmitter architectures into monolithic silicon solutions. Hydrocarbon processors in the Permian Basin are adopting these devices for wellhead monitoring at three-year replacement cycles versus fifteen-year mechanical gauge lifespans. Component count reduction is consolidating supplier tiers and compressing calibration service margins.
EPA Clean Air Act continuous emissions monitoring requirements are mandating redundant parameter tracking at major industrial sources. Refinery operators must install duplicate analyzers for critical emissions points, doubling instrument density in atmospheric monitoring applications. Texas and Louisiana facilities are accelerating procurement to meet 2026 compliance deadlines.
Service contract unbundling is separating hardware procurement from calibration and validation obligations. Pharmaceutical manufacturers in Ireland and Singapore are tendering these functions separately, pressuring integrated vendors to price maintenance independently of initial instrument sales. This fragmentation favors specialized metrology service providers over full-line manufacturers.
Global Process Instrumentation Market Segmentation
Process instrumentation buyers segment procurement decisions around calibration protocols, digital integration requirements, and regulatory validation burdens. Suppliers must align product architectures with distinct technical specifications across pressure, flow, temperature, and level measurement domains.
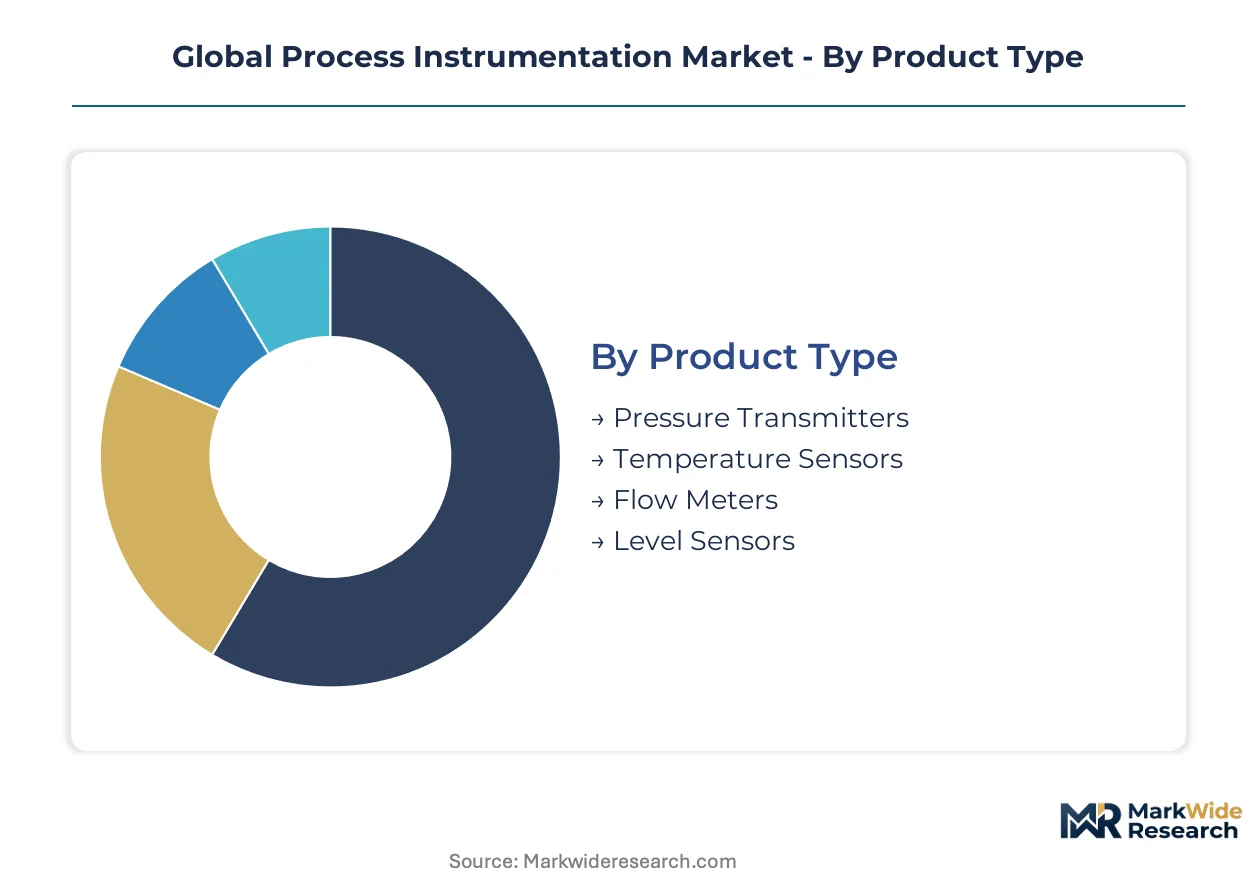
Product Type:
Buyers differentiate primarily by accuracy class requirements and replacement cycle economics rather than absolute unit cost.
- Pressure Transmitters:Piezoelectric and capacitive sensing elements convert physical pressure into standardized 4-20 mA or digital HART signals. Hydrocarbon processors in Texas and Louisiana deploy these universally across wellhead and refinery infrastructure to satisfy EPA Clean Air Act continuous monitoring mandates.
- Flow Meters:Coriolis, ultrasonic, and electromagnetic principles enable custody-transfer measurement with metrological certification. Chemical producers in Germany are expanding Coriolis deployments to track process mass balance for EU Green Deal emissions reporting obligations.
- Temperature Sensors:Thermocouple and RTD architectures provide precision thermal monitoring across reactor vessels and heat exchangers.
- Level Sensors:Radar and guided-wave technologies dominate bulk liquid storage applications in tank farms.
Pressure transmitters lead volumes today; flow meters are gaining share fastest through custody-transfer certification premiums.
End User:
Application environments dictate material specifications, hazardous area ratings, and validation documentation intensity.
- Oil & Gas:Wireless pressure transmitters and multiphase flow meters enable remote monitoring of distributed shale assets. Permian Basin operators are replacing mechanical gauges with MEMS-based devices at compressed three-year replacement cycles.
- Chemical:Electromagnetic flow meters and pH sensors track process chemistry with substance disclosure documentation for REACH compliance. German chemical clusters are deploying continuous emissions monitoring architectures to satisfy real-time Scope 1 and Scope 2 reporting requirements.
- Water & Wastewater:Ultrasonic level sensors and magnetic flow meters support municipal distribution network monitoring.
- Manufacturing:Smart sensors with IO-Link connectivity enable predictive maintenance in discrete automation environments.
Oil and gas dominates current procurement volumes; water infrastructure represents the steepest expansion trajectory through smart city instrumentation mandates.
Technology:
Digital protocol maturity separates greenfield specification winners from legacy analog replacement suppliers.
- Smart Sensors:Embedded microprocessors enable edge diagnostics, self-calibration, and HART-IP or IO-Link protocol integration. United States shale operators are modernizing wellhead monitoring infrastructure with these devices to enable remote asset visibility.
- Wireless Technology:ISA100 and WirelessHART architectures eliminate cabling costs in geographically dispersed installations. Offshore platforms and pipeline networks deploy battery-powered transmitters for non-critical measurement points.
- Electromagnetic:Faraday's law-based flow measurement dominates conductive liquid applications without moving parts.
- Optical Measurement:Laser and infrared spectroscopy enable non-contact composition analysis in pharmaceutical manufacturing.
Smart sensors command the largest installed base; wireless technology is climbing the fastest through distributed asset monitoring demand.
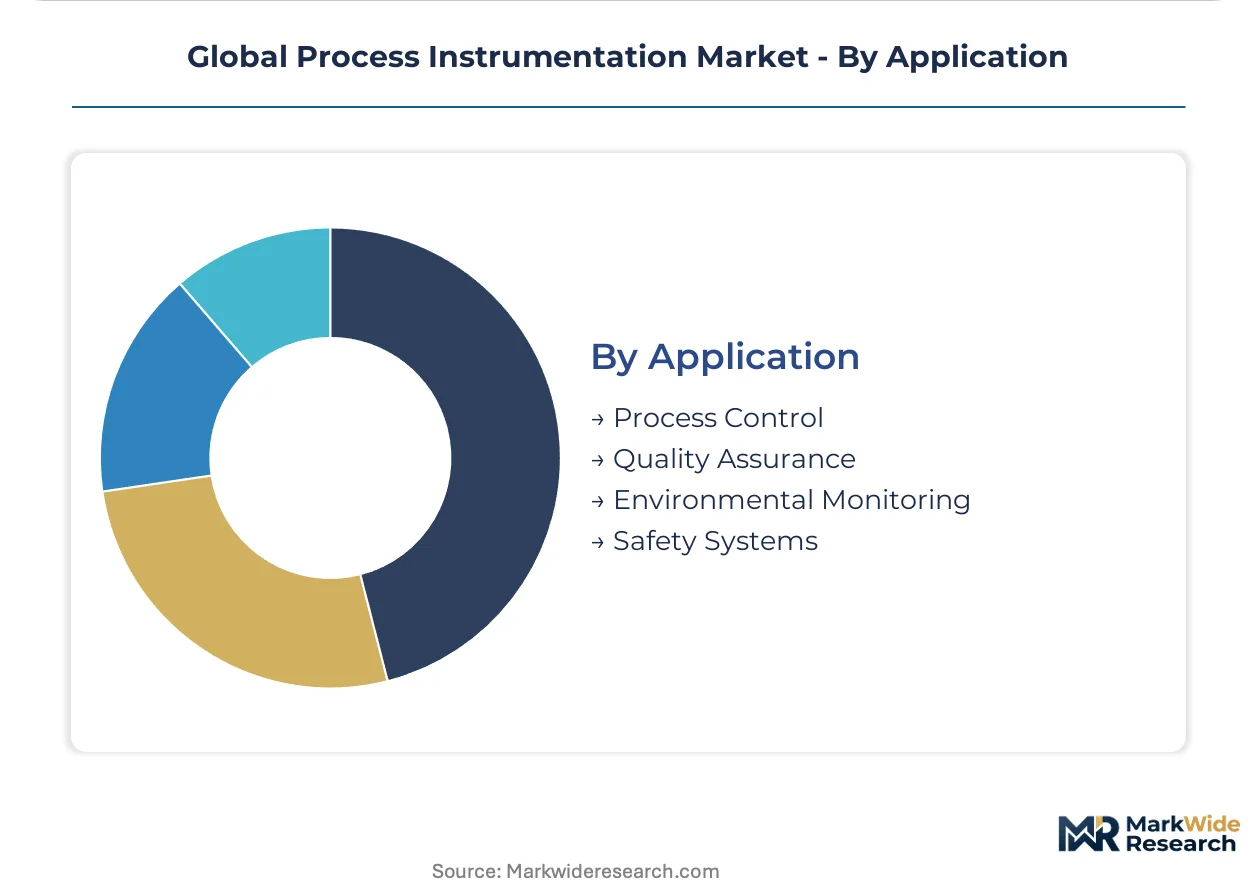
Application:
Functional safety integrity levels and validation documentation requirements stratify supplier qualification thresholds.
- Process Control:Closed-loop PID regulation demands measurement accuracy and signal reliability for continuous operations. Refinery distillation columns and chemical reactors depend on redundant transmitter architectures to maintain setpoint stability.
- Safety Systems:IEC 61508-certified instruments enable safety instrumented functions with defined failure probabilities. Offshore platforms and high-pressure hydrogen facilities require SIL-rated pressure transmitters with extended validation timelines.
- Environmental Monitoring:Continuous emissions monitoring systems track regulatory compliance parameters at stack and flare points.
- Quality Assurance:Validated analytical instruments support FDA process analytical technology frameworks in pharmaceutical manufacturing.
Process control anchors current revenue; safety systems are expanding most quickly through functional safety standard adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Instrumentation engineering talent concentrates in German industrial clusters, US Gulf Coast refining corridors, and Japanese precision manufacturing zones, anchoring regional competitive advantages in sensor design and calibration services.
United States
Shale operators in the Permian Basin and Eagle Ford formations are replacing mechanical gauges with wireless pressure transmitters at compressed three-year cycles. EPA Clean Air Act continuous emissions monitoring mandates drive redundant analyzer installations at Texas and Louisiana refineries. Houston anchors the largest concentration of instrumentation service providers supporting Gulf Coast petrochemical expansion.
Germany
Chemical producers in Ludwigshafen and Leverkusen are deploying continuous emissions monitoring architectures to satisfy EU Green Deal Scope 1 and Scope 2 reporting requirements. REACH substance disclosure obligations pivot procurement toward suppliers with transparent supply chain documentation. The Ruhr industrial corridor sustains dense clusters of flow meter calibration laboratories serving Benelux export markets.
China
State-owned refineries in Shandong and Liaoning provinces are modernizing distributed control systems with smart sensor architectures. The country's national environmental regulator enforces continuous emissions monitoring at major industrial sources under tightening air quality standards. Yangtze River Delta chemical parks concentrate domestic electromagnetic flow meter manufacturing capacity.
India
Municipal water authorities in tier-2 cities are expanding smart distribution network monitoring under Central Electricity Authority smart grid instrumentation mandates. The Bureau of Indian Standards certifies pressure transmitter accuracy classes for process industry procurement. Gujarat's chemical manufacturing clusters drive demand for hygienic sensor specifications in pharmaceutical ingredient production.
Japan
Precision equipment manufacturers in Nagoya and Osaka industrial zones supply MEMS pressure sensing elements to global automotive and industrial markets. METI industrial efficiency programs incentivize predictive maintenance sensor deployments in steel and chemical operations. Yokohama hosts specialized validation laboratories serving Asia-Pacific pharmaceutical manufacturing compliance requirements.
Global Process Instrumentation Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base stratifies into three distinct layers: full-line automation houses with integrated control portfolios, sensor-focused specialists with deep calibration service networks, and regional fabricators serving price-sensitive replacement markets. Consolidation pressure intensifies as digital protocol standardization raises R&D minimums. Strategic moves concentrate on M&A for wireless technology capabilities and backward integration into MEMS foundry operations.
Among diversified automation conglomerates, Emerson Electric Co., Siemens AG, and Honeywell International Inc. occupy positions representing distinct geographic anchoring and protocol ecosystem influence. Emerson exemplifies the North American service-integrated model through its Rosemount manufacturing footprint. Siemens represents European electromagnetic flow measurement specialization via Sitrans product architectures. Honeywell sits within the tier leveraging aerospace-derived sensing expertise for industrial process applications. These three anchor competitive dynamics without exhausting the specialist tier where Endress+Hauser AG and Yokogawa Electric Corporation concentrate domain expertise.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Siemens AG |
| Honeywell International Inc. |
| ABB Ltd. |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| Endress+Hauser AG |
| Rockwell Automation Inc. |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
Neodymium oxide price volatility cascades through Coriolis flow meter production costs, compressing margins for European sensor manufacturers while Asian competitors absorb shocks through integrated rare earth processing. This raw material exposure stratifies pricing power across three distinct service bundling tiers.
Pricing Analysis
Service unbundling separates hardware procurement from calibration and validation obligations across pharmaceutical and chemical buyer segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service intensity. Cost compression in mid-tier segments is intensifying because REACH compliance documentation burdens disproportionately burden European suppliers against Asian competitors. Small municipal water authorities exhibit highest price sensitivity; large hydrocarbon processors with custody-transfer metrology requirements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing infrastructure for neodymium and dysprosium magnet supply. Manufacturing capacity concentrates in Germany, China, and Japan for precision sensing elements and calibration equipment. Silicon carbide wafer scarcity and MEMS foundry bottlenecks create component dependencies that rest on limited 150mm substrate availability. Tariff exposure runs through transatlantic instrument shipments. Distribution runs through authorized distributor networks with regional calibration service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in smart sensor architectures where MEMS consolidation reduces bill-of-materials costs, while premium-tier positioning in safety instrumented systems captures functional safety certification premiums.
For Market Incumbents: Lock in calibration service dominance through captive validation laboratory networks in Houston, Ludwigshafen, and Yokohama industrial corridors. Backward integration into MEMS foundry operations secures silicon carbide wafer allocation against foundry capacity constraints. Wireless technology capabilities represent the priority capability gap requiring M&A response. For New Entrants and Emerging Players: Direct-to-utility digital sales channels bypass entrenched distributor relationships in Indian tier-2 municipal water markets. Hydrogen economy metrology gaps in high-pressure custody-transfer applications offer white-space entry with ultrasonic technology specialization. Pharmaceutical process analytical technology validation services present the most penetrable segment given unbundling trends. For Investors and Strategic Acquirers: Asymmetric upside sits with wireless sensor module specialists possessing ISA100 and WirelessHART protocol stacks. Long-term viability hinges on digital twin integration roadmaps converging physics-based simulation with live sensor feeds. Acquisition targets should demonstrate MEMS design capability paired with IEC 61508 functional safety certification track records. Watch hydrogen infrastructure deployment announcements as inflection signal for flow meter demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Backward Integration | Captive silicon carbide wafer supply secures pressure sensor capacity against substrate scarcity. |
| Wireless Protocol Stack Acquisition | ISA100 and WirelessHART capabilities enable distributed asset monitoring in shale and offshore applications. |
| Hydrogen Metrology Certification Investment | First-mover ultrasonic flow measurement for high-pressure custody-transfer captures uncertified market gap. |
| Digital Twin Platform Partnership | Physics-based simulation convergence with live sensor feeds enables predictive maintenance contracts in refining. |
| REACH Supply Chain Transparency Program | Substance disclosure documentation pivots procurement toward compliant European suppliers against Asian competitors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers, OEM procurement teams, aftermarket service heads, and calibration laboratory directors with secondary validation against SEC filings, customs trade data, IEC certification registries, and EPA emissions monitoring compliance records. Bottom-up sensor shipment data triangulated against top-down industrial capital expenditure surveys.
Segment-weighting approaches distributed revenue across pressure transmitter, flow meter, temperature sensor, and level sensor product categories, with further stratification by smart sensor, wireless, electromagnetic, and optical technology architectures. CAGRs derived from installation base growth, replacement cycle compression, and protocol migration adoption curves across the projection horizon. Hydrocarbon processing capital budgets, EU Green Deal implementation timelines, and pharmaceutical FDA submission pipelines informed industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for IO-Link and HART-IP protocol displacement would alter the outlook. Forecasts reflect assumptions regarding shale modernization cycles, REACH compliance cost trajectories, and rare earth supply stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
Communication Test and Measurement (Ctandm) Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
Network Diagnostic Tools Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Global Laser Measuring Instrument Market
Measuring Instruments
Global Container Weighing Systems Market
Measuring Instruments
Moisture Meter Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
Global Dissolved Oxygen Meters and Controllers Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
TDS Meter Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Base Station Analyzer Market
Measuring Instruments
Monitoring Tools Market
Measuring Instruments
Global Dimensional Metrology Software Market
Measuring Instruments
North America Scientific Instruments Market