
 Computer Software Market | 2026-2036
Computer Software Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Software Market Analysis
Proprietary on-premise codebases are recalibrating cost structures as open-source frameworks replace licensed middleware stacks. Microsoft leverages its Azure-integrated development ecosystem to anchor enterprise workloads across hybrid environments. Oracle sustains database licensing dominance through backward compatibility guarantees that lock institutional clients into multi-year renewals. SAP competes aggressively in ERP migration services, positioning its S/4HANA platform as the default upgrade path for aging ECC installations.
Computer software encompasses executable programs, operating systems, and development frameworks written in compiled or interpreted code, typically distributed via binary packages or containerized microservices with defined API specifications. Its primary commercial purpose is automating information processing, enabling real-time decision pipelines, and orchestrating hardware resources across distributed computing architectures. Application software captures the dominant margin pool as enterprises prioritize vertical-specific SaaS solutions over generic productivity suites. Cloud-based deployment is expanding fastest as latency-sensitive workloads shift toward edge-native architectures, while on-premise licensing retains structural importance in regulated sectors with data sovereignty requirements.
The US FDA governs software-as-medical-device classifications, forcing health-tech vendors to validate algorithmic outputs through formal quality management systems. The EU AI Act imposes risk-tiered conformity assessments on automated decision systems, restricting market access for non-compliant providers. ISO 27001 and SOC 2 frameworks shape procurement eligibility for enterprise buyers evaluating vendor security postures. Stakeholders must monitor regulatory divergence between Brussels and Washington, as conflicting compliance obligations will fragment product roadmaps and inflate certification costs for cross-border software distribution.
Market Dynamics
Cloud migration mandates under the EU AI Act and GDPR compliance requirements are accelerating enterprise replacement cycles, forcing vendors to re-architect delivery models around sovereign data residency and automated conformity assessment pipelines.
Growth Catalysts
- Healthcare digitization:Hospital systems are expanding procurement for patient data management platforms as HIPAA compliance deadlines tighten and FDA software-as-medical-device classifications expand.
- EU AI Act enforcement:Risk-tiered conformity assessments on automated decision systems are restricting market access for non-compliant providers, creating first-mover advantages for certified vendors.
- Federal modernization:United States agencies and Fortune 500 enterprises are replacing aging infrastructure, concentrating demand in Washington DC corridors and Texas data center clusters.
Market Restraints
- Specialized talent scarcity:DevOps engineers with FedRAMP certification command premium compensation, inflating implementation costs for government-facing vendors.
- Input cost volatility:GPU compute pricing fluctuates with Taiwan semiconductor foundry capacity constraints, destabilizing cloud provider margin structures.
- Regulatory fragmentation:Divergent compliance obligations between Brussels GDPR requirements and Washington HIPAA frameworks fragment product roadmaps and inflate certification costs.
Strategic Opportunities
- Edge-native architectures:Latency-sensitive workloads are shifting toward distributed processing nodes, opening white space in manufacturing automation and autonomous vehicle software stacks.
- Regulatory tailwind:ISO 27001 and SOC 2 frameworks are shaping procurement eligibility, creating competitive moats for vendors with pre-certified security postures.
- Legacy ERP displacement:Aging SAP ECC installations face mandatory end-of-life deadlines, positioning migration services as a high-margin recurring revenue channel.
Industry Challenges
- Integration complexity:Hybrid cloud deployments require seamless orchestration between on-premise mainframes and containerized microservices, demanding scarce mainframe-to-Kubernetes expertise.
- Compliance timeline compression:EU AI Act conformity assessments must complete before market entry, forcing vendors to front-load quality management system investments without guaranteed revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Software Market |
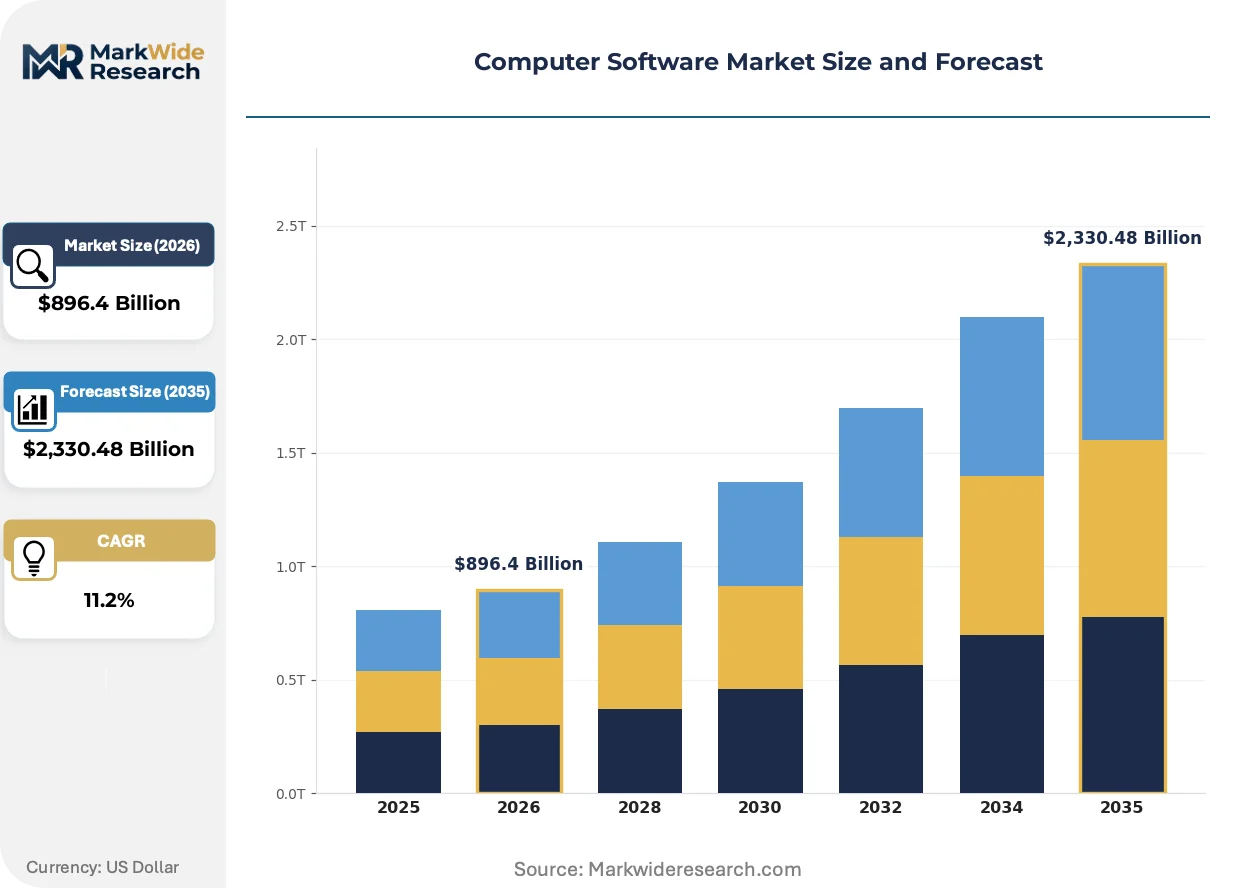
| Market Size in 2026 | $896.4 Billion |
| Market Size in 2035 | $2,330.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Application Software, System Software, Development Tools, Middleware Deployment: On-Premise, Cloud-Based, Hybrid, Remote Access End User: Enterprise, SMB, Government, Individual License Model: Perpetual License, Subscription, Freeware, Open Source |
| Companies Covered | Microsoft, Alphabet, Oracle, SAP, Palantir Technologies, Salesforce, IBM, ServiceNow, Adobe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Software Market Emerging Trajectories
Executable program distribution is fragmenting across containerized microservices and serverless functions, compressing traditional middleware licensing models while elevating API governance and observability tooling.
Edge computing infrastructure is decentralizing application delivery architectures by processing data closer to source devices rather than centralized hyperscale facilities. Automotive manufacturers and industrial automation vendors are deploying Kubernetes clusters to factory floors and vehicle onboard units at accelerating velocity. This topology is decentralizing cloud provider market power while creating new attack surfaces requiring zero-trust security frameworks.
The EU AI Act imposes mandatory conformity assessments on high-risk automated decision systems, forcing health-tech vendors to validate algorithmic outputs through formal quality management systems. Medical device software classifications now require documented training data provenance and human oversight protocols. European health systems are delaying procurement cycles until vendor certifications complete, compressing competitive windows for non-compliant providers.
Enterprise buyers are unbundling after-sales service contracts from perpetual license agreements, demanding consumption-based pricing tied to actual API call volumes or active user seats. Federal agencies and Fortune 500 procurement teams are replacing three-year enterprise agreements with annual renewals featuring built-in price renegotiation clauses. This pattern is most visible in United States government contracting, where FedRAMP authorization delays already extend sales cycles by twelve to eighteen months.
Computer Software Market Segmentation
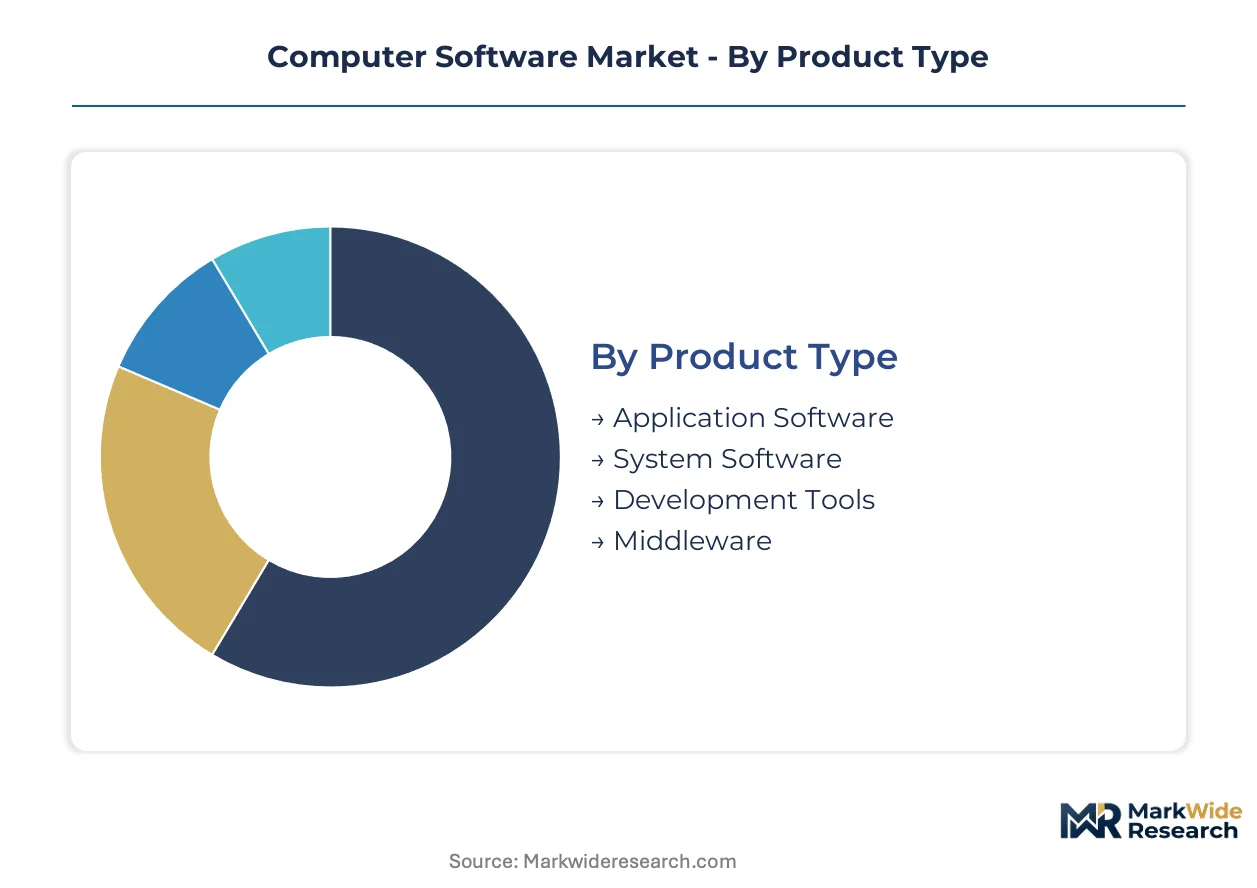
Software procurement decisions hinge on interoperability requirements, compliance postures, and total cost of ownership calculations across multi-year depreciation cycles. Vendors must architect pricing and delivery models that align with distinct buyer risk appetites and infrastructure maturity levels.
Product Type:
Enterprise buyers prioritize functional depth over integration breadth when allocating capital across software categories.
- Application Software:Vertical-specific SaaS platforms automate industry workflows through configurable modules. Hospital systems in the United States and manufacturing conglomerates in Germany are consolidating procurement around FDA-validated and ISO 27001-certified suites.
- System Software:Operating systems and utility programs manage hardware resource allocation and security policy enforcement. Federal agencies demand FedRAMP-authorized distributions, while European enterprises require GDPR-compliant telemetry configurations.
- Development Tools:Integrated environments and code repositories accelerate release pipelines for DevOps teams.
- Middleware:Message brokers and API gateways enable legacy-to-cloud connectivity.
Application software leads on scale; development tools lead on momentum.
Deployment:
Latency requirements and data sovereignty mandates are fragmenting infrastructure strategies across buyer segments.
- Cloud-Based:Hyperscale delivery eliminates capital expenditure for compute and storage infrastructure. United States Fortune 500 enterprises and United Kingdom financial services firms are migrating ERP workloads to meet GDPR and SOX audit requirements.
- Hybrid:Orchestrated environments span on-premise mainframes and containerized cloud instances. German automotive manufacturers and Japanese industrial automation vendors deploy Kubernetes clusters to factory floors while retaining sensitive design data locally.
- On-Premise:Perpetual licensing persists in regulated sectors with strict data residency rules.
- Remote Access:Virtual desktop infrastructure supports distributed workforces with centralized security policy enforcement.
Cloud-based deployment captures volume concentration; hybrid architectures are climbing the fastest.
End User:
Procurement sophistication and compliance stringency vary sharply across organizational scale and sector.
- Enterprise:Global conglomerates negotiate multi-year enterprise agreements with built-in price renegotiation clauses. United States federal agencies and German healthcare systems mandate FedRAMP and EU AI Act conformity assessments respectively.
- Government:Public sector buyers impose certification prerequisites that extend sales cycles. French hospital networks and Saudi healthcare authorities require documented algorithmic training data provenance for medical device software.
- SMB:Mid-market buyers favor consumption-based pricing tied to active user seats.
- Individual:Freelance developers and small studios drive demand for affordable IDE subscriptions.
Enterprise accounts dominate revenue concentration; government verticals are gaining share fastest.
License Model:
Pricing structure selection reflects buyer cash flow preferences and strategic vendor relationship positioning.
- Subscription:Recurring revenue models align vendor incentives with customer success outcomes. United States SaaS providers and European health-tech vendors are displacing perpetual licenses with annual renewals featuring usage-based tiers.
- Open Source:Community-developed frameworks reduce middleware licensing costs while elevating support contract value. German automotive suppliers and United States cloud-native startups contribute to and commercialize Kubernetes and TensorFlow ecosystems.
- Perpetual License:One-time purchases with maintenance add-ons persist in capital-intensive industries.
- Freeware:No-cost distribution builds user bases for premium feature upsells.
Subscription pricing leads on scale; open source licensing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley corridors anchor enterprise software procurement concentration as federal agencies and Fortune 500 enterprises accelerate legacy modernization cycles. Cloud migration mandates under the EU AI Act and GDPR compliance requirements are fragmenting vendor delivery models across sovereign data residency zones. Procurement gravity shifts toward jurisdictions with aligned regulatory frameworks and established certification infrastructure.
United States
Federal modernization programs and HIPAA compliance deadlines drive hospital system procurement for patient data management platforms. The FDA governs software-as-medical-device classifications through formal quality management system requirements. Washington DC corridors and Texas data center clusters concentrate demand as agencies replace aging infrastructure with FedRAMP-authorized distributions.
Germany
Automotive manufacturers and industrial automation vendors deploy Kubernetes clusters to factory floors for latency-sensitive manufacturing workloads. The EU AI Act imposes risk-tiered conformity assessments on automated decision systems entering European markets. Baden-Württemberg and Bavaria host dense concentrations of SAP ECC installations facing mandatory end-of-life migration deadlines.
United Kingdom
Financial services firms migrate ERP workloads to cloud environments to satisfy SOX audit requirements and operational resilience mandates. GDPR telemetry configurations shape enterprise procurement eligibility for system software vendors. London and Southeast England anchor SaaS provider headquarters serving European mid-market buyers with consumption-based pricing models.
India
Cloud-native startups and enterprise IT services firms commercialize open-source frameworks while contributing to Kubernetes and TensorFlow ecosystems. The country's national data protection authority is formulating cross-border data transfer requirements affecting software distribution models. Karnataka and Telangana host development centers supplying DevOps talent for global vendor implementation pipelines.
Japan
Industrial conglomerates demand hybrid orchestration between on-premise mainframes and containerized cloud instances for legacy system continuity. METI guidelines influence procurement standards for software security postures in critical infrastructure sectors. Tokyo and Osaka metropolitan areas concentrate enterprise buyers evaluating ISO 27001-certified vendor relationships.
Computer Software Market Vendor Landscape
Global majors compete with regional champions across certification depth and sovereign data residency capabilities. The vendor base stratifies into hyperscale cloud-integrated ecosystems, legacy database licensing incumbents, and vertical-specific SaaS specialists. Three archetypes dominate: platform orchestrators anchoring hybrid environments, compliance-forward health-tech vendors, and open-source commercialization engines. Competitive moves concentrate on FedRAMP authorization acquisition and EU AI Act pre-certification to compress rival sales cycles.
Within the platform orchestrator tier, Microsoft and Oracle exemplify divergent lock-in strategies—Azure-integrated development ecosystems versus backward compatibility guarantees that institutionalize multi-year renewals. SAP occupies a position as the default upgrade path for aging ECC installations, while Salesforce represents the consumption-based pricing archetype displacing perpetual licenses with annual renewals featuring usage-based tiers. Palantir Technologies anchors the government-facing specialist segment where FedRAMP certification creates competitive moats.
| Leading Market Players |
|---|
| Microsoft |
| Alphabet |
| Oracle |
| SAP |
| Palantir Technologies |
| Salesforce |
| IBM |
| ServiceNow |
| Adobe |
| Others |
Supply Flow & Price Mechanics
GPU compute pricing indices cascade through cloud provider margin structures into SaaS subscription tiers, compressing mid-market pricing while premium FedRAMP-certified offerings sustain rate premiums. This cost transmission forces vendors to re-architect delivery models around sovereign data residency zones.
Pricing Analysis
Input-cost pass-through from Taiwan semiconductor foundry capacity constraints cascades into cloud provider rate cards, compressing standard-tier SaaS margins while ISO 27001-certified and EU AI Act-compliant offerings maintain pricing power. Price differentiation hinges on certification grade and vertical integration depth. Pricing pressure stems from GPU compute volatility destabilizing consumption-based models. SMB buyers exhibit highest price sensitivity; federal agencies demonstrate lowest sensitivity due to mandated security requirements.
Supply Chain Analysis
Specialized compute hardware supply rests on Taiwan, South Korea, and United States foundry capacity, with NVIDIA GPU architectures and ARM-based processor designs anchoring downstream software performance tiers. Raw material dependencies span silicon wafers, advanced packaging substrates, and rare earth elements for memory modules. Single-source vulnerability concentrates in leading-edge semiconductor lithography. Distribution runs through hyperscale cloud marketplaces and direct enterprise sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities emerge from divergent compliance costs between Brussels GDPR enforcement and Washington FedRAMP authorization timelines, rewarding vendors with dual-certification infrastructure.
For Market Incumbents: Deploy backward integration into sovereign cloud infrastructure to defend against emerging compliance-forward specialists threatening federal and healthcare verticals. Lock institutional clients through multi-year Azure-integrated development ecosystem contracts while accelerating EU AI Act pre-certification investments to compress rival sales cycles. For New Entrants and Emerging Players: Mid-market German automotive suppliers represent the most penetrable buyer archetype, underserved by legacy SAP ECC migration services and seeking Kubernetes-native manufacturing automation. Target ISO 27001 certification as the primary go-to-market wedge, leveraging open-source commercialization to displace licensed middleware stacks. For Investors and Strategic Acquirers: Asymmetric upside sits with compliance-forward health-tech vendors possessing FDA software-as-medical-device validations and documented algorithmic training data provenance. Long-term viability favors acquisition targets with pre-built conformity assessment pipelines spanning Brussels and Washington regulatory frameworks. Watch EU AI Act enforcement velocity as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure-anchored ecosystems capture hybrid workload orchestration across federal and Fortune 500 accounts. |
| Regulatory Pre-Certification | EU AI Act conformity assessments create first-mover moats before mandated compliance deadlines restrict market access. |
| Backward Integration | Captive GPU allocation agreements with Taiwan foundries insulate margin structures from spot-market volatility. |
| Vertical SaaS Launch | FDA-validated patient data management platforms capture HIPAA-driven hospital system procurement cycles. |
| Geographic Expansion | German automotive manufacturing clusters offer Kubernetes deployment density for latency-sensitive industrial automation. |
Methodological Framework
Coverage spans United States, Germany, United Kingdom, India, and Japan, with primary inputs from each market combining structured interviews with CTOs, IT procurement officers, platform engineers, and channel partners alongside secondary validation. Sources include SEC filings, hyperscaler capex disclosures, App Annie usage data, and EU regulatory submission databases. Bottom-up deployment modeling triangulates against top-down enterprise IT spending benchmarks.
Granularity-level framing segments the market by deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern across the analysis window. CAGRs derive from regression analysis against historical replacement cycle data and regulatory mandate timelines. Forecast inputs incorporate FedRAMP authorization velocity, EU AI Act implementation schedules, and SAP ECC end-of-life migration deadlines.
Underlying measurement precision varies by segment; cloud-based deployment and enterprise end-user categories carry tighter precision than individual license models. Forecasts reflect documented assumptions about regulatory enforcement timelines and semiconductor supply normalization. GPU pricing volatility, FedRAMP backlog duration, and EU-US regulatory divergence warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Online Community Management Software Market
Software & Services
Advanced Mobile UX Design Services Market
Software & Services
Marketing Automation Software Market
Software & Services
Period-Tracking Software Market
Software & Services
Global Subscription Billing Software Market
Software & Services
Reporter Systems Market
Software & Services
Software Licensing Market
Software & Services
Telecom Billing Software Market
Software & Services
ELD Compliance Software Market
Software & Services
Global Photogrammetry Software Market
Software & Services
Truck Dispatch Software Market
Software & Services
Live Software Market
Software & Services
App Creation Software Market
Software & Services
Global Construction Management Software Market
Software & Services
Global Gym Software Market
Software & Services
Equipment Management Software Market