
 Mining Simulation Software Market | 2026-2036
Mining Simulation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Simulation Software Market Insights
Multi-source procurement of simulation modules is shifting toward integrated platform contracts as miners consolidate vendor relationships. Datamine leverages its geological modeling heritage to anchor underground optimization workflows. Maptek competes through specialized point-cloud integration for open-pit environments. Deswik dominates mine planning interoperability with third-party equipment data feeds.
Mining simulation software encompasses digital environments that replicate extraction processes, equipment behavior, and rock mechanics through physics-based engines operating at millisecond update intervals for operator training and design validation. Its primary commercial purpose centers on reducing unplanned downtime and catastrophic safety incidents before physical deployment. Cloud-based solutions now lead technology adoption as distributed mine sites require centralized model synchronization, while virtual reality integration represents the fastest-expanding segment as headset costs decline and immersion fidelity improves. Training simulators command the deepest margin pools due to recurring certification mandates and union-negotiated competency requirements.
OSHA workplace safety directives and Canada's MEE environmental assessment protocols shape North American procurement specifications for hazard replication fidelity. Australia's Work Health and Safety Act enforcement drives underground simulator mandates for longwall operations. Stakeholders must monitor how regulatory bodies harmonize digital twin evidence standards across permitting processes without fragmenting software certification requirements.
Market Dynamics
Underground coal operators in Australia are accelerating simulator deployments as Work Health and Safety Act enforcement tightens competency mandates for longwall operations. This regulatory pressure is compressing procurement cycles and forcing vendors to integrate certification tracking directly into training modules.
Growth Catalysts
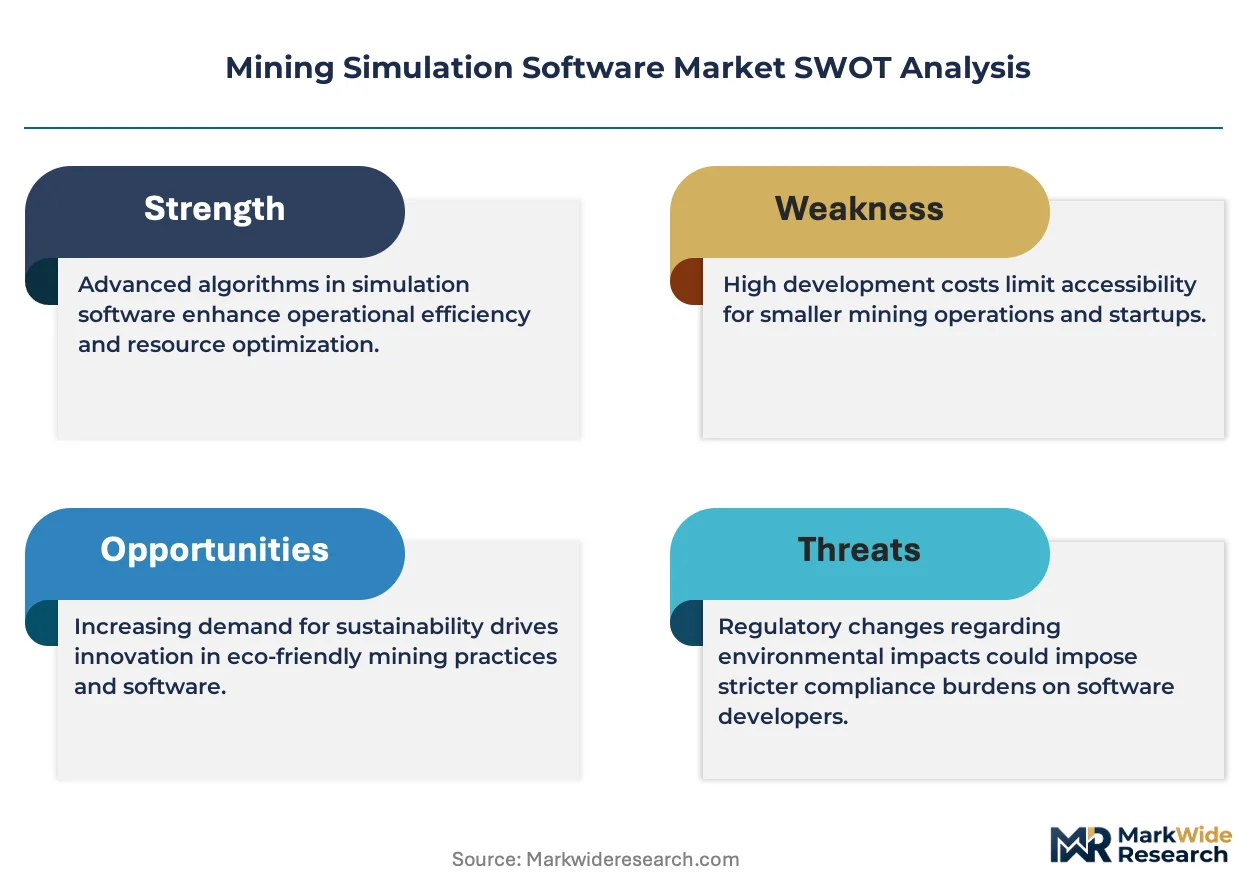
- OSHA workplace safety directives:US underground metal mines must demonstrate hazard replication fidelity in operator training programs, creating recurring software refresh cycles.
- Copper belt modernization:Chilean state-owned operators are expanding workforce readiness programs across Calama and Antofagasta mining clusters.
- Cloud synchronization:Distributed mine sites in Western Australia and Saskatchewan now require centralized model deployment for remote training coordination.
Market Restraints
- GPU supply concentration:Rendering hardware dependency on Taiwan-based semiconductor fabrication creates procurement bottlenecks for physics engine upgrades.
- Legacy system incompatibility:Existing SCADA and fleet management architectures resist real-time data feed integration with modern simulation platforms.
- Substitution by basic VR:Low-cost headset deployments without physics engines satisfy minimum compliance in jurisdictions with weaker enforcement standards.
Strategic Opportunities
- Canada's MEE digital twin mandate:Environmental permitting now requires predictive modeling evidence, opening new licensing revenue streams for geology-integrated platforms.
- VR-headset cost compression:Hardware price declines below $500 per unit are enabling mass deployment across surface operation training centers.
- Artificial intelligence convergence:Machine learning rock mechanics models are reducing calibration time for site-specific geotechnical simulations.
Industry Challenges
- Simulation engineer scarcity:The intersection of mining engineering and software development expertise remains critically under-supplied across Calgary, Brisbane, and Denver talent markets.
- Certification timeline fragmentation:Australia's RII09 training package and Canada's provincial mining safety regimes maintain incompatible competency evidence standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Simulation Software Market |
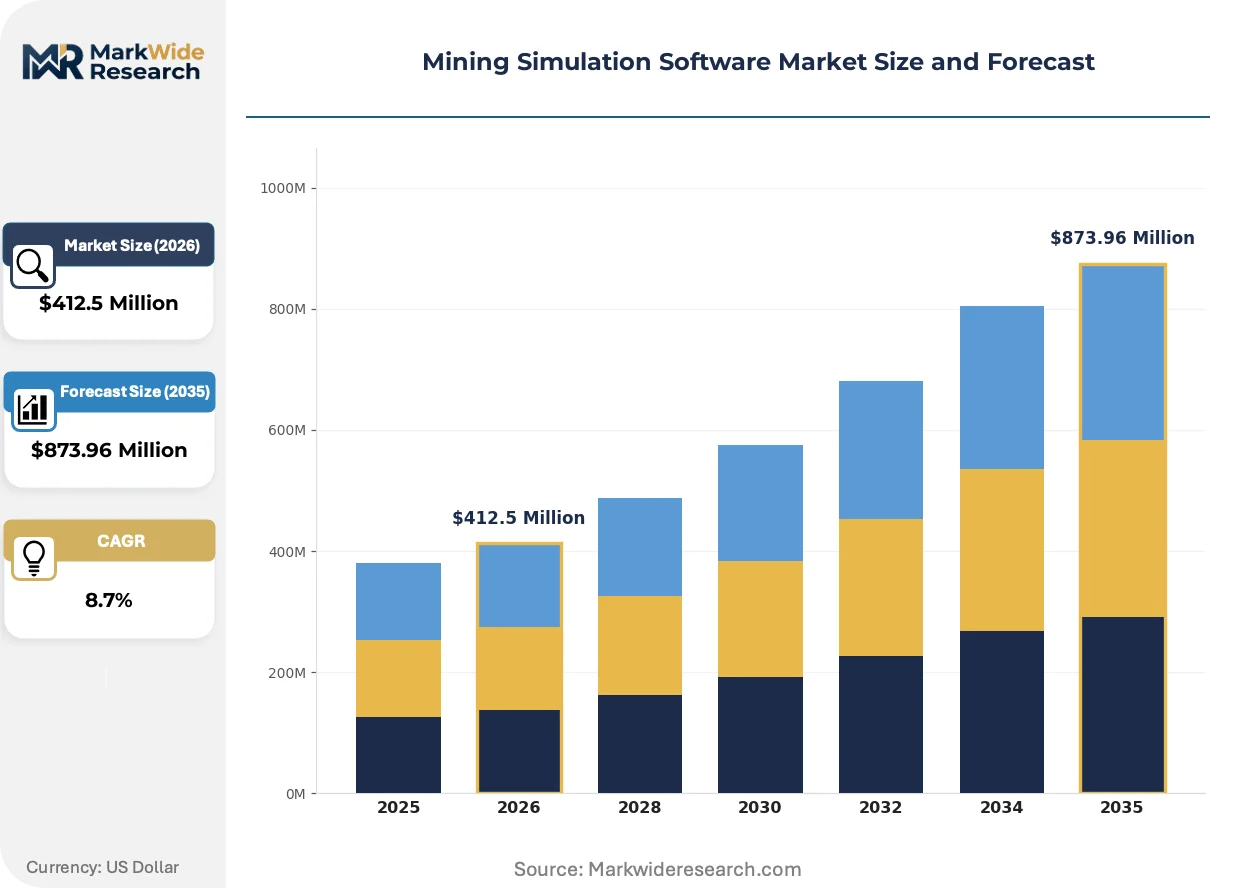
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Simulation Tools, Training Simulators, Predictive Analytics, Asset Management Application: Mineral Exploration, Project Planning, Safety Management, Operational Optimization End User: Mining Companies, Consultants, Regulatory Bodies, Academic Institutions Technology: Cloud-Based Solutions, On-Premises Software, Hybrid Models, Virtual Reality Integration |
| Companies Covered | Datamine, Micromine, Maptek, Rocscience, GEOVIA, Deswik, K-MINE, Promine, Seequent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Simulation Software Market Trends and Innovations
Physics engines operating at millisecond update intervals are displacing legacy frame-rate-dependent simulations. This architectural shift is compressing the gap between virtual training outcomes and actual equipment response patterns.
Real-time rock mechanics modeling is automating the calibration workflows that previously required manual geotechnical parameter entry. Underground coal operators in Queensland are adopting these self-tuning engines for longwall face stability predictions. The technology is automating the specialist labor bottleneck that constrained simulator deployment velocity across Australian basins.
Canada's MEE environmental assessment protocols now mandate predictive tailings behavior modeling for permit approval. This regulatory expansion is forcing simulation vendors to integrate hydrological and geochemical modules into traditional equipment training platforms. Copper-gold projects in British Columbia are experiencing the longest compliance preparation cycles as they adapt to these digital twin evidence requirements.
Consolidated platform contracts are displacing multi-source module procurement as miners reduce vendor management overhead. Chilean state-owned operators now specify single-source responsibility for training, planning, and environmental simulation workflows. This concentration is most visible in the Antofagasta region where procurement teams prioritize interoperability guarantees over specialized point solutions.
Mining Simulation Software Market Segmentation
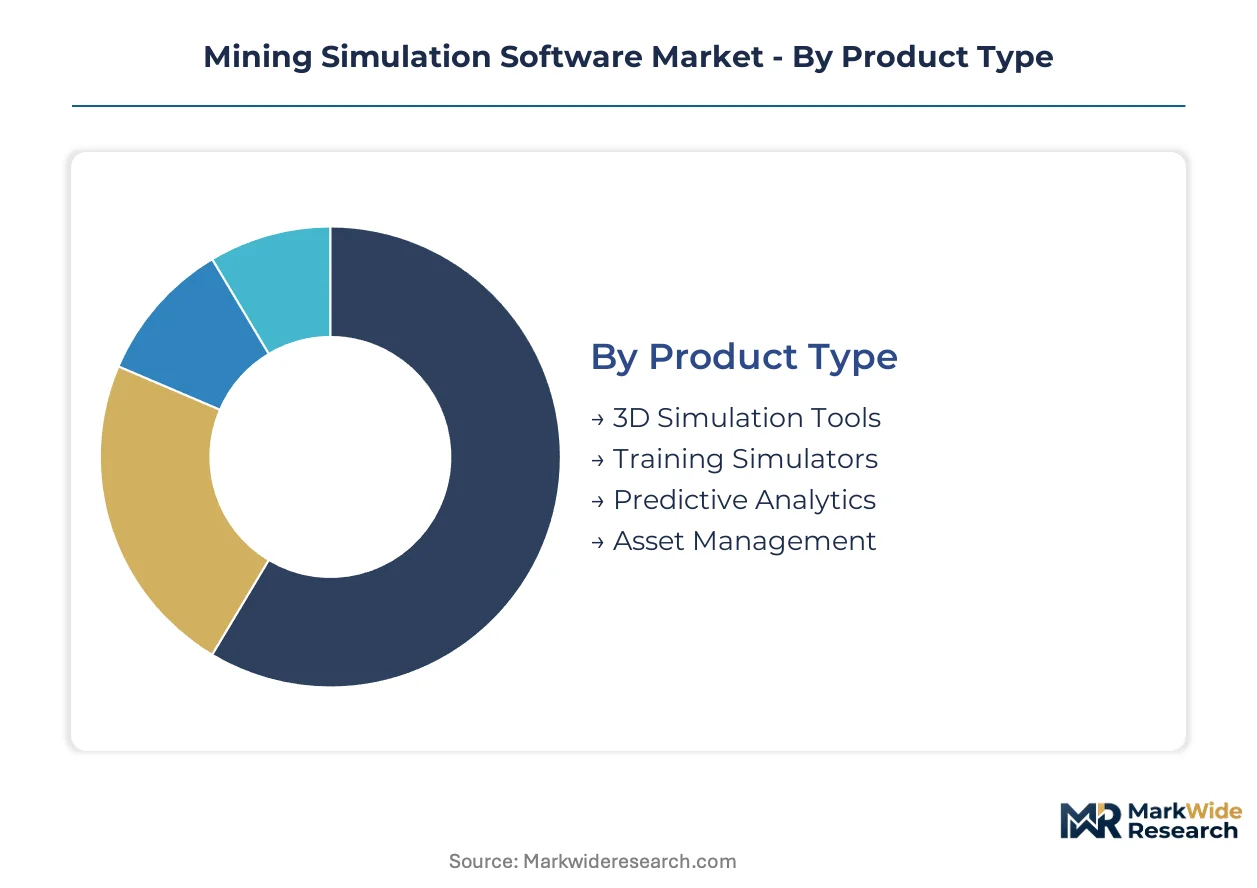
Mining simulation software procurement hinges on matching physics engine fidelity to specific operational risk profiles. Buyers prioritize certification compliance, integration depth, and workforce deployment scale when selecting across product categories.
Product Type:
Training simulators command premium budgets where union-mandated competency programs require recurring certification cycles.
- 3D Simulation Tools:Physics engines render geological formations and equipment kinematics at millisecond update intervals for design validation. Underground coal operators in Australia deploy these for longwall face stability modeling under Work Health and Safety Act enforcement.
- Training Simulators:Immersive cabins replicate operator controls with force-feedback hydraulics and motion platforms for skill certification. Chilean state-owned operators across Calama and Antofagasta clusters are modernizing workforce readiness programs with these systems.
- Predictive Analytics:Machine learning models forecast equipment failure and ore grade variability.
- Asset Management:Digital twins synchronize maintenance schedules with production planning.
Training Simulators lead on scale; Predictive Analytics leads on momentum.
Application:
Safety Management absorbs the deepest software budgets where regulatory mandates require hazard replication evidence.
- Safety Management:Virtual environments replicate methane outbursts, rock bursts, and equipment collision scenarios for procedural drilling. Canada's MEE digital twin mandate for environmental permitting is expanding predictive modeling requirements across British Columbia copper-gold projects.
- Operational Optimization:Real-time fleet dispatch algorithms integrate with geological block models for throughput maximization. Western Australian iron ore producers deploy these for remote coordination across Pilbara distributed sites.
- Mineral Exploration:Geophysical inversion and drillhole visualization reduce target delineation risk.
- Project Planning:Schedule-risk quantification links resource modeling to capital timing decisions.
Operational Optimization dominates current deployment volume; Safety Management is climbing the fastest on regulatory tailwinds.
End User:
Mining Companies consolidate vendor relationships to reduce integration complexity across planning and training workflows.
- Mining Companies:Integrated platform contracts span geology, mine planning, and operator training modules with single-source accountability. Chilean procurement teams in Antofagasta prioritize interoperability guarantees over specialized point solutions.
- Consultants:Multi-client license structures support due diligence and technical report preparation for capital markets.
- Regulatory Bodies:Digital twin evidence standards for permitting require vendor compliance certification.
- Academic Institutions:Curriculum-integrated simulators supply graduate mining engineers with equipment operation credentials.
Mining Companies anchor revenue concentration; Academic Institutions are gaining share fastest on workforce pipeline investments.
Technology:
Cloud deployment decisions balance data sovereignty requirements against distributed site synchronization needs.
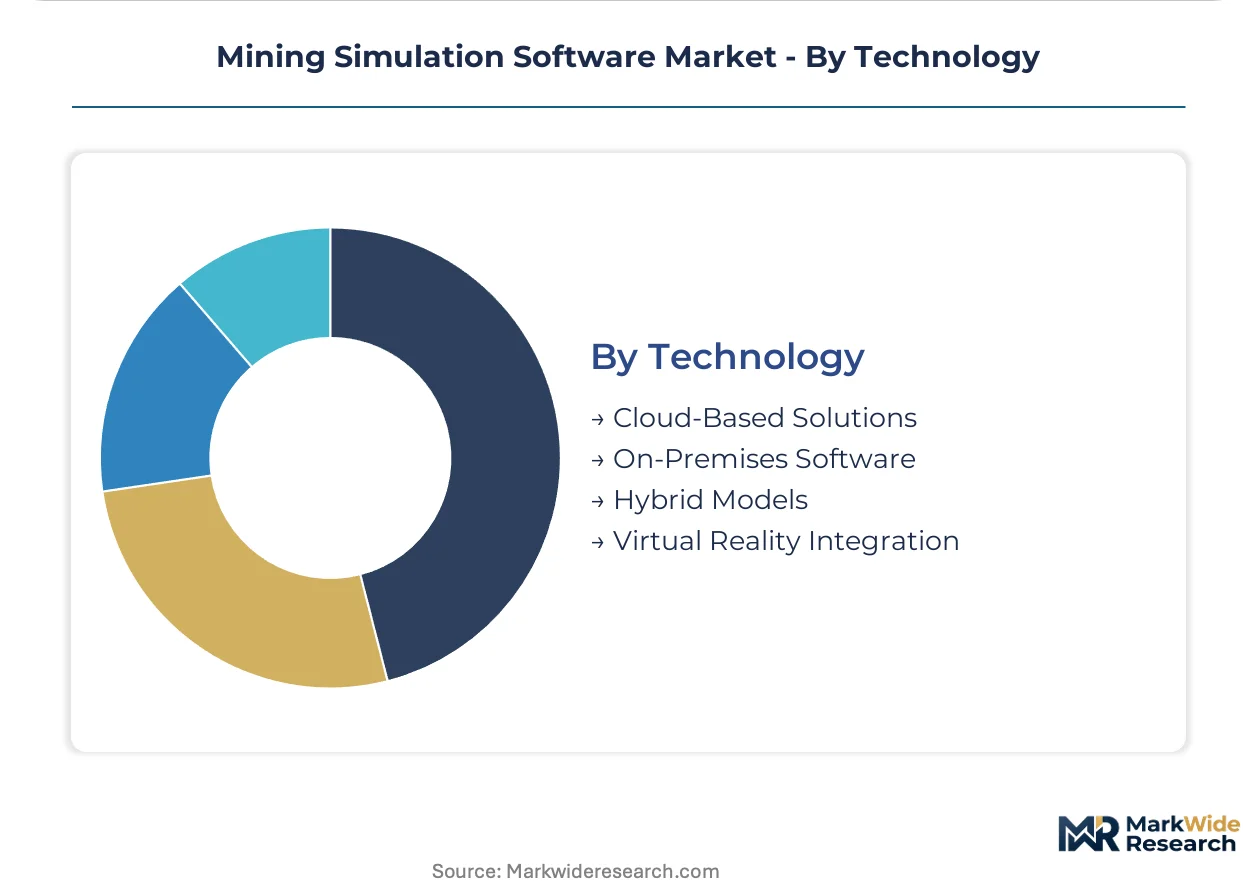
- Cloud-Based Solutions:Centralized model repositories enable real-time updates across remote training centers and operational sites. Saskatchewan potash producers and Western Australian gold operators deploy these for cross-site competency standardization.
- Virtual Reality Integration:Headset-based immersion reduces simulator cabin capital costs while maintaining procedural fidelity. Hardware price compression below $500 per unit is enabling mass deployment across surface operation training centers.
- On-Premises Software:Air-gapped installations satisfy cybersecurity protocols for critical infrastructure protection.
- Hybrid Models:Edge computing for real-time physics with cloud archival for longitudinal analytics.
Cloud-Based Solutions hold the largest installed base; Virtual Reality Integration shows the steepest expansion trajectory on hardware cost declines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting procurement budgets toward jurisdictions where compliance mandates accelerate simulator deployment. Australia's Work Health and Safety Act enforcement creates cost-of-compliance premiums that Chilean and Canadian operators exploit through faster certification cycles.
Australia
Queensland's Bowen Basin coal operators face compressed procurement timelines under tightened longwall competency mandates. The country's Work Health and Safety Act drives underground simulator deployment across New South Wales and Queensland. Perth-based training centers coordinate remote certification for Pilbara iron ore distributed sites.
Chile
State-owned Codelco and Antofagasta Minerals are modernizing workforce readiness programs across the Calama and Antofagasta copper clusters. The country's mining safety regulator enforces operator competency evidence standards that favor physics-engine fidelity. Procurement teams in the Atacama region now specify single-source platform contracts spanning training and planning modules.
Canada
British Columbia copper-gold projects experience extended compliance preparation cycles under the MEE digital twin mandate for environmental permitting. The Ministry of Environment and Energy requires predictive tailings behavior modeling. Vancouver-based engineering firms integrate hydrological modules into traditional equipment training platforms for permitting submissions.
United States
OSHA workplace safety directives force underground metal mines in Nevada and Arizona to demonstrate hazard replication fidelity in operator training programs. The federal regulator mandates recurring software refresh cycles for competency documentation. Denver-based mining consultancies anchor procurement coordination for Rocky Mountain operations.
South Africa
Platinum belt operators in Rustenburg and Limpopo deploy simulators for mechanized mining competency transfer under the country's Mine Health and Safety Act. The Department of Mineral Resources and Energy enforces certificate-of-competency requirements. Johannesburg-based training providers synchronize certification tracking with union-negotiated workforce development programs.
Mining Simulation Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native architectures and VR headset integration. The vendor base clusters around three capability bundles: geological modeling heritage, mine planning interoperability, and specialized point-cloud processing. Dominant competitive moves include consolidated platform contracting to reduce vendor management overhead and AI convergence partnerships to compress geotechnical calibration timelines.
Within the geological modeling tier, Datamine and Seequent occupy positions anchored by subsurface visualization heritage. Maptek exemplifies the specialized point-cloud integration archetype for open-pit environments. Deswik sits within the mine planning interoperability segment, anchoring third-party equipment data feed integration. These three vendors represent distinct strategic postures that miners evaluate against single-source accountability requirements.
| Leading Market Players |
|---|
| Datamine |
| Micromine |
| Maptek |
| Rocscience |
| GEOVIA |
| Deswik |
| K-MINE |
| Promine |
| Seequent |
| Others |
Pricing and Supply Chain Analysis
Chilean state-owned mining procurement teams concentrate buying power through consolidated platform contracts, anchoring pricing power in volume-scale negotiations rather than module-by-module sourcing. This buyer archetype concentration rewards vendors who bundle training, planning, and environmental simulation workflows under single-source accountability.
Pricing Analysis
Direct-to-mine-site licensing discounts dominate as procurement teams eliminate distributor margins for enterprise-scale deployments. Three-tier pricing structure across premium physics-engine fidelity, standard compliance-grade modules, and economy VR-headset-only configurations separates certification-mandated buyers from discretionary adopters. Cost compression in hardware tiers is intensifying because Taiwan-based GPU fabrication bottlenecks constrain rendering upgrade cycles. Academic institutions exhibit highest price sensitivity due to constrained capital budgets, while Australian underground coal operators under Work Health and Safety Act enforcement show lowest sensitivity given recurring certification mandates.
Supply Chain Analysis
GPU and motion-platform hardware supply rests on Taiwan-based semiconductor fabrication and German precision-engineering producers for force-feedback cabin components. Physics-engine software development draws from Canadian geotechnical modeling expertise and Australian mining engineering talent pools concentrated in Brisbane and Perth. Single-source vulnerability in GPU supply creates procurement bottlenecks for physics engine upgrades when fabrication capacity tightens. Distribution runs through direct vendor-to-mine-site relationships with engineering-procurement-construction contractors coordinating installation and calibration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mining simulation software functions as a stable compounder where regulatory-mandated training refresh cycles generate predictable recurring revenue independent of commodity price cycles.
For Market Incumbents: Extend platform interoperability guarantees to preempt challenger entry through certification-tracking integration that locks in multi-year training contracts. Threat substitution by low-cost VR headsets without physics engines pressures margin pools in weak-enforcement jurisdictions like select South American surface operations. Lever vertical integration into cloud infrastructure to capture recurring synchronization revenue from distributed Western Australian and Saskatchewan mine sites. For New Entrants and Emerging Players: Mid-tier consulting engineering firms serving British Columbia copper-gold projects represent an underserved buyer archetype requiring digital twin compliance modules without full enterprise platform investment. White-space concentration sits in environmental permitting simulation where Canada's MEE mandate has outpaced vendor hydrological module development. Go-to-market positioning as MEE-specialist compliance partners bypasses direct competition with established training simulator incumbents. For Investors and Strategic Acquirers: Industrial software conglomerates with mining verticals are the most active acquirer in this space, seeking geological modeling heritage to anchor underground optimization workflows. Long-term viability frames around decade-scale regulatory harmonization trends rather than technology displacement risk. Acquisition target archetypes include cloud-native VR specialists with millisecond physics engines and established certification authority relationships. Watch for OSHA enforcement expansion into surface metal mining as inflection indicator for training simulator demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Single-source accountability for training-planning-environmental workflows reduces Chilean procurement team vendor management overhead. |
| AI Convergence Partnership | Machine learning rock mechanics partnerships compress geotechnical calibration timelines for Australian longwall operators. |
| Geographic Expansion | Perth-based training center networks capture Western Australian Pilbara remote site synchronization demand. |
| Product Launch | Sub-$500 VR headset bundles open surface operation training center mass deployment across Canadian potash producers. |
| Strategic Partnership | Cloud infrastructure alliances enable centralized model repositories for Saskatchewan cross-site competency standardization. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mine planning engineers, training center operations managers, environmental compliance officers, and procurement leads at state-owned Chilean operators with secondary validation through SEC filings of listed mining technology vendors, Canadian MEE permit application databases, Australian RII09 training package documentation, and OSHA enforcement action records. Bottom-up deployment counts across Australian longwall operations and Chilean copper clusters triangulated against top-down vendor revenue attribution.
Historical reference periods anchored the forecast window to pre-pandemic certification mandate acceleration and post-2020 cloud migration adoption curves across the analysis window. Segmentation dimensions modeled include product type fidelity tiers, application risk profiles, end-user procurement scale, and deployment technology architecture. CAGRs derived from regression of certified simulator installations against regulatory enforcement intensity indices, with industry-specific inputs incorporating union-negotiated competency requirement cycles and GPU hardware cost compression trajectories.
Underlying measurement precision varies by segment; training simulator installation counts carry tighter precision than predictive analytics module adoption given opaque vendor bundling practices. Forecasts incorporate assumptions around regulatory harmonization timelines and semiconductor supply normalization that could revise trajectory if OSHA enforcement expands or Taiwan fabrication capacity constraints deepen. A small set of triggers—Canadian MEE digital twin mandate expansion, Australian Work Health and Safety Act surface mining extension, and Chilean state-owned operator procurement centralization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Workflow Automation and Optimization Software Market
Software & Services
Social Collaboration Software Market
Software & Services
Production Optimization Software Market
Software & Services
AI Sales Assistant Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
HVAC Solution Software Market
Software & Services
Global Recreation Management Software Market
Software & Services
Australia HR Payroll Software Market
Software & Services
Business Activity Monitoring Software (BAM) Market
Software & Services
Telecom Billing Software Market
Software & Services
Global Maintenance Management Software Market
Software & Services
Workstation Software Market
Software & Services
Server Software Market
Software & Services
Global Bill of Material Management Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Advanced Mobile UX Design Services Market