
 Digital Customer Onboarding Software Market | 2026-2036
Digital Customer Onboarding Software Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Customer Onboarding Software Market Insights
Subscription-based feature tiers is pivoting vendor economics away from perpetual licenses toward recurring revenue anchored by usage-based entitlements. WalkMe leverages deep product analytics to sustain enterprise retention across complex SaaS stacks. Appcues specializes in no-code onboarding flows that dominate mid-market SaaS adoption. Userpilot competes through in-app guidance tools that extend customer lifetime value for product-led growth companies.
Digital customer onboarding software encompasses cloud-native and on-premises platforms that automate identity verification, document collection, compliance screening, and user activation through configurable workflows and API orchestration. These systems integrate biometric authentication, optical character recognition, and real-time database checks to reduce abandonment rates and accelerate time-to-value for regulated and consumer-facing enterprises. Cloud-based deployment leads in new customer acquisition due to elastic scalability and reduced infrastructure overhead, while hybrid architectures capture margin pools from financial services clients with data residency requirements. API integration represents the fastest-growing connectivity layer as embedded finance and banking-as-a-service models proliferate across telecommunications and insurance verticals.
Financial regulators including the SEC, FINRA, and state-level banking supervisors enforce KYC and AML standards that shape product roadmaps and create barriers for non-compliant vendors. The EU's GDPR and forthcoming AI Act impose additional data governance and algorithmic transparency obligations on automated decisioning features. Stakeholders must monitor evolving patchworks of federal and state privacy legislation to determine whether to build compliant infrastructure natively or absorb certification costs through partnership strategies.
Market Dynamics
API-first onboarding infrastructure is consolidating vendor architectures around embedded finance partnerships, compressing deployment timelines from quarters to weeks for banking-as-a-service providers.
Growth Catalysts
- KYC/AML Mandates:The EU's AML6 Directive and GDPR enforcement are compelling financial institutions to replace manual verification with automated workflows, accelerating software procurement cycles.
- Biometric Authentication:Liveness detection and facial recognition technologies are reducing abandonment rates at document upload stages for retail banking applications.
- United States:Fintech startups and neobanks in California, New York, and Texas are driving concentrated demand for scalable, multi-tenant onboarding platforms.
Market Restraints
- Data Residency Requirements:Financial services clients in Germany and Switzerland demand hybrid cloud architectures, increasing infrastructure complexity and compliance certification costs.
- Optical Character Recognition Limitations:Low-quality document images and non-Latin scripts continue to generate false rejection rates that erode customer trust.
- Legacy Core Banking Integration:SOAP-based mainframe systems at incumbent institutions create middleware bottlenecks that delay real-time API orchestration deployments.
Strategic Opportunities
- Telecommunications Vertical:Mobile network operators in Brazil and Mexico are embedding financial services, creating demand for white-label onboarding modules.
- AI Act Compliance Tools:The EU's forthcoming algorithmic transparency requirements will create premium pricing tiers for explainable decisioning engines in automated screening.
- Real-Time Payments Convergence:Integration of instant payment rails with identity verification is opening new use cases for gig economy and marketplace lending platforms.
Industry Challenges
- Machine Learning Engineering Talent:Scarcity of practitioners with fraud detection model expertise is inflating compensation costs and extending hiring timelines.
- Cross-Border Certification Complexity:Vendors must maintain separate audit trails for SEC, FINRA, and state-level banking supervisors, fragmenting product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Customer Onboarding Software Market |
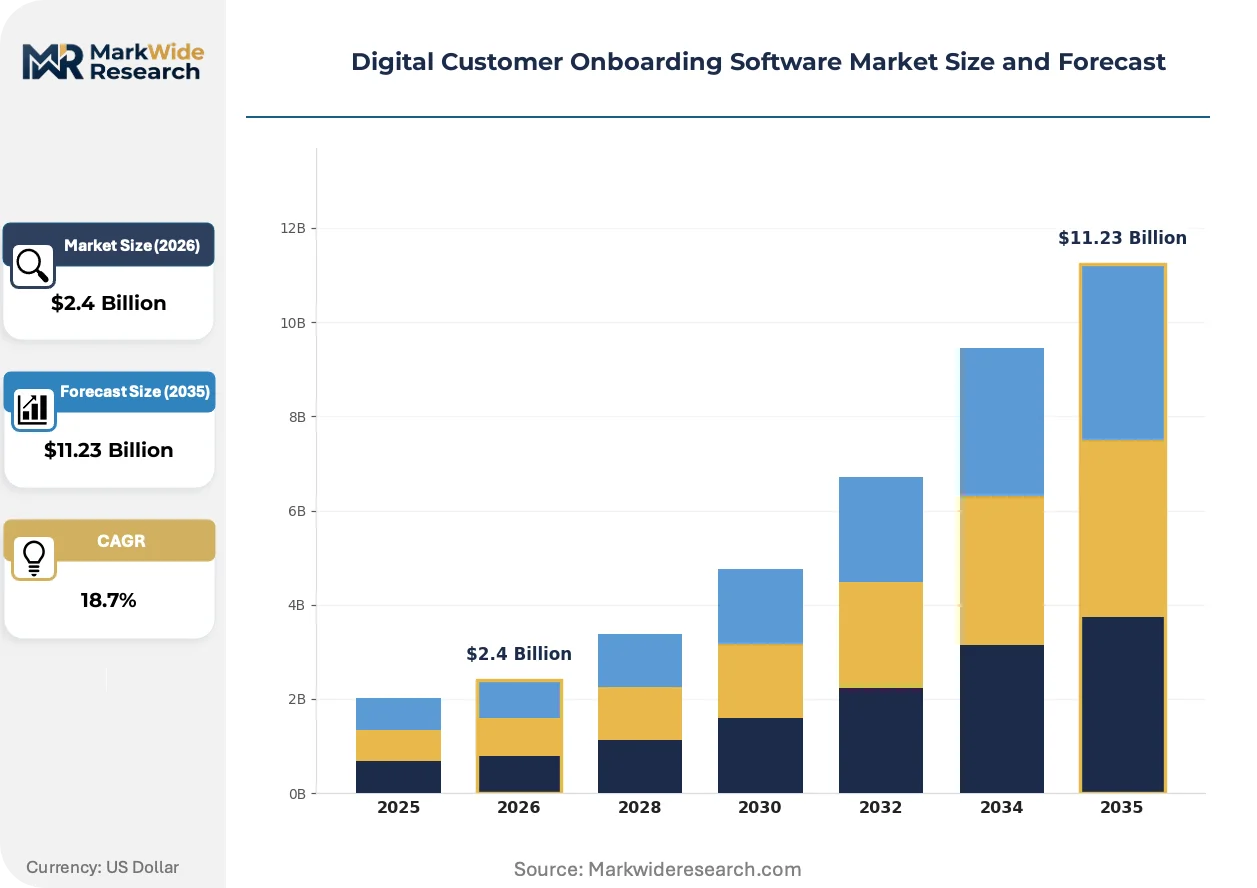
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $11.23 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Web-Based, Mobile Application, Cloud-Based, Desktop Software End User: Financial Services, E-Commerce, Telecommunications, Insurance Deployment: On-Premises, Hybrid, Public Cloud, Private Cloud Integration Level: API Integration, Single Sign-On, Third-Party Tools, Custom Integration |
| Companies Covered | Pendo, Chameleon, Guideflow, Rocketlane, WalkMe, Dock, Appcues, GUIDEcx, Userpilot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Customer Onboarding Software Market Trends and Innovations
Embedded finance partnerships are dissolving traditional boundaries between identity verification and transaction initiation, forcing vendors to rearchitect around real-time data orchestration rather than batch processing.
Passive biometric behavioral analysis is overtaking active document-centric verification as the primary fraud prevention layer. Challenger banks in the United Kingdom and Netherlands are deploying keystroke dynamics and device fingerprinting at account opening, reducing friction for legitimate users while elevating detection precision. This shift is compressing the addressable market for standalone document verification specialists.
The EU AI Act's risk classification framework is mandating human-in-the-loop overrides for automated rejection decisions in credit onboarding. Vendors serving European financial institutions must now engineer explainability dashboards and audit logging capabilities that satisfy both GDPR and algorithmic accountability requirements. This regulatory layering is favoring incumbent platforms with established compliance engineering teams over point-solution newcomers.
Product-led growth companies are unbundling onboarding from core banking contracts, purchasing standalone identity verification through developer marketplaces rather than enterprise procurement. This channel migration is visible most acutely among Series B fintechs in San Francisco and London, which prioritize API documentation quality and sandbox availability over traditional vendor relationship management.
Digital Customer Onboarding Software Market Segmentation
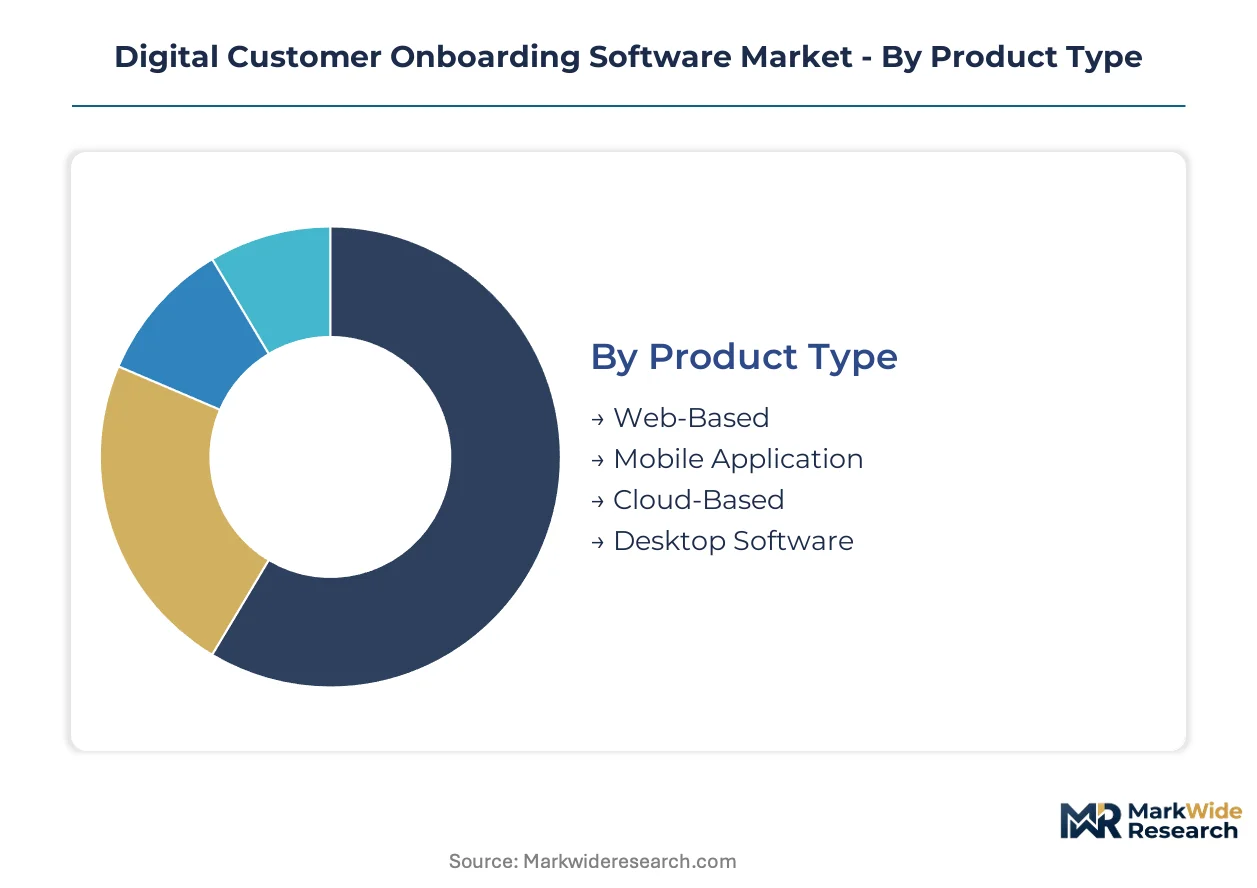
Segmentation in digital customer onboarding software reveals how vendor architectures align with client technical maturity and regulatory exposure. Deployment choices and integration depth separate commodity buyers from enterprises requiring embedded compliance infrastructure.
Product Type:
Integration depth varies sharply across product modalities, with cloud-native platforms embedding directly into banking-as-a-service stacks while desktop software persists in compliance-heavy back offices.
- Cloud-Based:Multi-tenant architectures with elastic compute provisioning serve fintech startups and neobanks requiring rapid scaling. Demand clusters among California and New York banking-as-a-service providers building embedded finance products.
- Mobile Application:Native iOS and Android SDKs with biometric capture and liveness detection dominate retail banking and telecommunications subscriber acquisition. Brazilian and Mexican mobile network operators drive concentrated procurement for white-label financial service launches.
- Web-Based:Browser-rendered onboarding flows with responsive design serve mid-market SaaS and e-commerce marketplaces.
- Desktop Software:Thick-client installations persist in German and Swiss private banking where data residency mandates prohibit cloud processing.
Volume placements concentrate in Cloud-Based platforms; the faster expansion belongs to Mobile Application as telecommunications verticals embed financial services.
End User:
Cost tier separation distinguishes regulated financial institutions paying premium for compliance certification from e-commerce operators prioritizing conversion velocity over audit depth.
- Financial Services:Banks, credit unions, and investment firms require KYC/AML workflows with biometric authentication and real-time sanctions screening. EU AML6 Directive enforcement accelerates replacement of manual verification at institutions across Germany, France, and Netherlands.
- E-Commerce:Marketplaces and direct-to-consumer brands prioritize friction reduction through social login and progressive profiling. Southeast Asian platforms favor lightweight identity verification to minimize checkout abandonment.
- Telecommunications:Mobile operators in Brazil, Mexico, and Nigeria embed financial services through SIM-linked identity verification.
- Insurance:Life and property carriers deploy document-centric onboarding with OCR and medical record integration for underwriting automation.
Revenue concentration sits with Financial Services; Insurance demonstrates the steepest expansion trajectory as automated underwriting penetrates personal lines.
Deployment:
Application criticality determines whether clients absorb operational overhead for control or delegate infrastructure to vendor-managed environments.
- Public Cloud:Shared infrastructure with SOC 2 and PCI DSS certification serves Series B fintechs and product-led growth companies. San Francisco and London startups prioritize API documentation and sandbox availability over customization.
- Hybrid:Split architectures with sensitive data on-premises and orchestration in cloud satisfy German and Swiss data residency requirements. FINRA and SEC audit trails mandate this configuration for US broker-dealers with European operations.
- Private Cloud:Dedicated single-tenant deployments serve government contractors and defense-adjacent financial institutions.
- On-Premises:Air-gapped installations persist in classified environments and certain central banking applications.
Customer acquisition favors Public Cloud; Hybrid deployments gain share fastest as cross-border financial services multiply.
Integration Level:
Customer type separates developer-led procurement through marketplaces from enterprise IT mandating single-vendor consolidation.
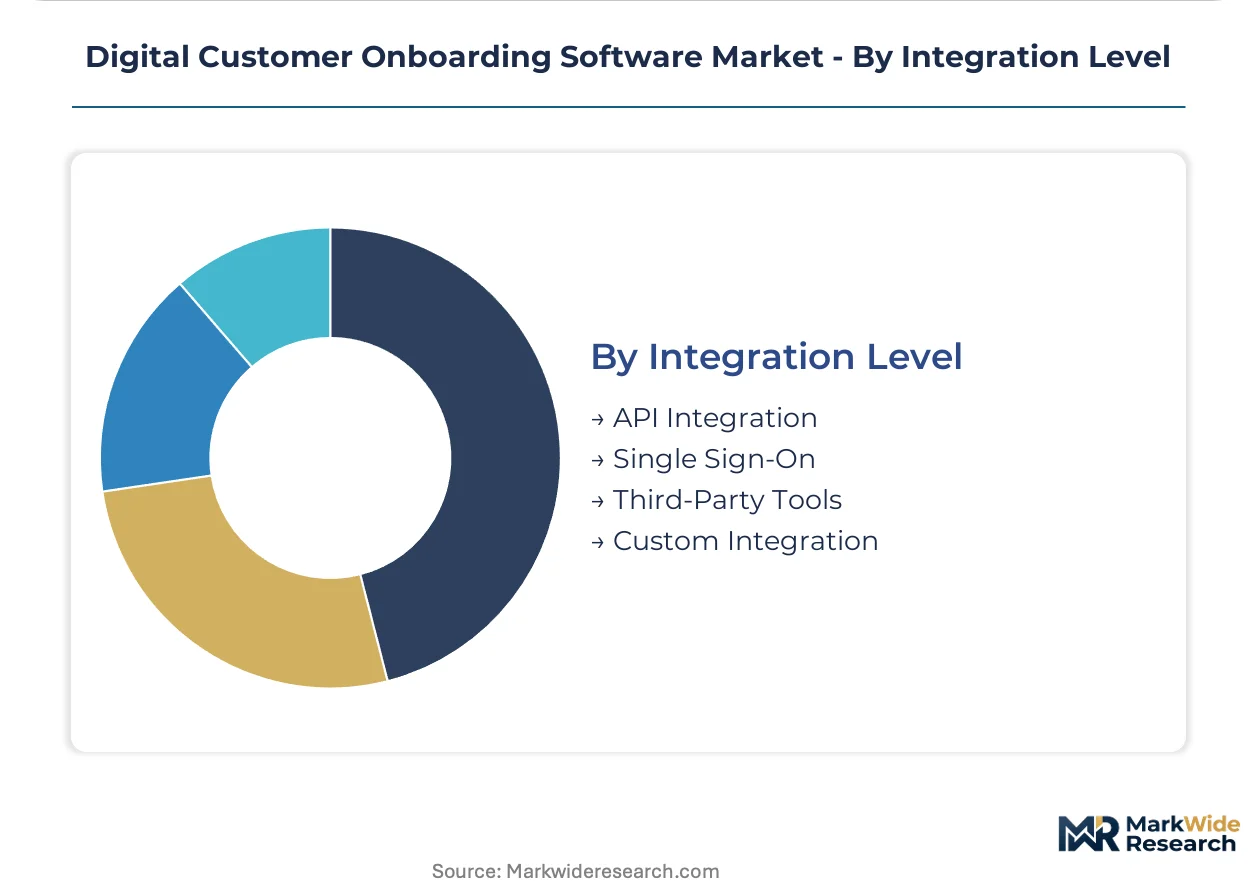
- API Integration:REST and GraphQL endpoints with webhook eventing enable embedded finance architectures. Banking-as-a-service providers in Texas and California compress deployment timelines through pre-built connectors to core banking systems.
- Single Sign-On:SAML and OIDC federation reduces credential friction for workforce and customer identity convergence.
- Third-Party Tools:Pre-packaged connectors to CRM, marketing automation, and customer data platforms serve mid-market SaaS stacks.
- Custom Integration:Bespoke middleware development addresses legacy SOAP-based mainframe systems at incumbent institutions.
Integration volume concentrates in API-first implementations; Custom Integration climbs fastest as legacy core banking modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors procurement intensity for API-first onboarding infrastructure, with venture-backed fintechs driving concentrated demand for scalable identity verification stacks.
United States
Texas and California banking-as-a-service providers compress deployment timelines through pre-built core banking connectors. SEC and FINRA audit requirements shape vendor certification roadmaps. New York metro fintechs prioritize sandbox availability over traditional procurement channels.
Germany
Private banking institutions in Frankfurt and Munich mandate hybrid cloud architectures to satisfy data residency requirements. BaFin enforcement of AML6 Directive accelerates replacement of manual verification workflows. Baden-Württemberg manufacturing banks embed onboarding into supply chain finance products.
United Kingdom
Challenger banks in London deploy passive biometric behavioral analysis at account opening. FCA consumer duty rules elevate explainability requirements for automated rejection decisions. Manchester and Leeds neobanks unbundle identity verification from legacy core contracts.
Brazil
Mobile network operators in São Paulo embed financial services through SIM-linked identity verification. Banco Central do Brasil instant payment rails converge with verification workflows for gig economy platforms. Rio de Janeiro fintechs white-label onboarding modules for telecommunications partnerships.
Netherlands
Amsterdam-based fintechs integrate EU AI Act compliance tools into automated screening engines. DNB supervision mandates human-in-the-loop overrides for credit onboarding decisions. Rotterdam insurance carriers deploy document-centric verification with medical record integration.
Digital Customer Onboarding Software Market Competitive Landscape
Capital-heavy platform vendors compete with asset-light workflow specialists for enterprise procurement budgets. The vendor base separates into three tiers: incumbent compliance suites, API-native challengers, and no-code workflow tools. Strategic consolidation centers on embedded finance partnerships and vertical-specific compliance certification.
Within the product analytics tier, WalkMe occupies a position exemplifying enterprise retention strategies across complex SaaS stacks. Appcues and Userpilot represent divergent archetypes—no-code flow dominance versus in-app guidance for product-led growth companies—illustrating how specialization fragments addressable market segments.
| Leading Market Players |
|---|
| Pendo |
| Chameleon |
| Guideflow |
| Rocketlane |
| WalkMe |
| Dock |
| Appcues |
| GUIDEcx |
| Userpilot |
| Others |
Pricing and Supply Chain Analysis
Banking-as-a-service providers in California and Texas concentrate procurement volume for API-first onboarding infrastructure, anchoring vendor pricing around subscription tiers scaled by verification throughput and compliance module depth.
Pricing Analysis
Value-based pricing anchored to customer acquisition cost reduction dominates enterprise procurement, with vendors charging premium rates for biometric liveness detection and real-time sanctions screening. Price differentiation separates certified AML6-compliant tiers from basic identity verification packages. Pricing pressure stems from open-source OCR libraries commoditizing document processing at the low end. Series B fintechs in San Francisco and London exhibit highest price sensitivity, while German private banking institutions absorb premium hybrid-deployment costs without negotiation.
Supply Chain Analysis
Refurbishment flows for on-premises biometric hardware extend equipment lifecycles at Swiss and German institutions resisting cloud migration. Component sourcing concentrates in Taiwan for facial recognition chipsets, Ireland for data center infrastructure, and India for OCR engineering talent. Supply chain risk rests on single-source dependencies for liveness detection algorithms held by Israeli and Chinese vendors. Distribution runs through direct enterprise sales teams for financial services clients and developer marketplaces for product-led growth companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around embedded finance partnerships, with API documentation quality and compliance certification speed forcing document-centric point solutions toward acquisition or exit.
For Market Incumbents: Deepen vertical integration into biometric hardware manufacturing to reduce dependency on Israeli liveness detection providers. Acquire no-code workflow specialists in the mid-market SaaS segment before challenger banks unbundle identity verification from core banking contracts. Prioritize EU AI Act explainability engineering to defend premium pricing against open-source alternatives. For New Entrants and Emerging Players: Developer marketplace distribution offers the fastest route to revenue for API-native onboarding tools targeting Series B fintechs. Telecommunications verticals in Brazil and Mexico present underpenetrated white-space for SIM-linked identity verification modules. Lead with sandbox availability and webhook documentation quality rather than traditional sales relationship investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor no-code onboarding workflow specialists with established mid-market SaaS customer bases in London and San Francisco. Long-term viability hinges on compliance engineering depth rather than feature velocity. Monitor Banco Central do Brasil instant payment rail integration requirements as an inflection signal for Latin American market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | Banking-as-a-service providers in Texas compress deployment timelines through pre-built core connectors. |
| EU AI Act Compliance Engineering | Explainability dashboards satisfy DNB supervision mandates for human-in-the-loop credit decisions in Amsterdam. |
| Biometric Hardware Backward Integration | In-house liveness detection chipsets reduce exposure to single-source Israeli algorithm providers. |
| Telecommunications Vertical Expansion | White-label SDKs for Brazilian mobile operators capture SIM-linked financial service launches. |
| Developer Marketplace Distribution | App store placement reaches product-led growth companies unbundling from enterprise procurement channels. |
Research Methodology
Independent corroboration across CTO interviews at California neobanks, compliance officer discussions at Frankfurt private banks, and platform engineer conversations at London fintechs underwrites the qualitative findings. Secondary validation drew from SEC filings, BaFin enforcement notices, Banco Central do Brasil regulatory circulars, and hyperscaler partnership announcements. Bottom-up deployment estimates triangulated against top-down financial services IT spending benchmarks.
Rate-of-change decomposition across the analysis window modeled cloud versus hybrid deployment shifts, API versus custom integration trajectories, and financial services versus telecommunications vertical penetration. Segmentation dimensions included deployment architecture, organization size tier, integration complexity level, and regional regulatory cluster. CAGR derivation incorporated vendor booking data, procurement cycle length observations, and replacement rate assumptions for manual verification workflows.
The model holds under sustained KYC/AML enforcement intensity; deviation in EU AI Act implementation timelines or GDPR penalty relaxation would shift vendor investment priorities. Practitioners should monitor Banco Central do Brasil instant payment convergence signals and FINRA audit trail requirement updates for early indicators of geographic expansion viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Plant Design Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
Global Architecture Design Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Expense Management Software Market
Software & Services
Global Virtual Desktop Market
Software & Services
Apache Spark Market
Software & Services
Automotive Hypervisor Market
Software & Services
Global Android Kiosk Software Market
Software & Services
Live Software Market
Software & Services
Time Series Databases Software Market
Software & Services
Output Management Software Market
Software & Services
Car-Hailing Software Market
Software & Services
North America Servicenow Store Apps Market
Software & Services
Global Campaign Management Software Market
Software & Services
Lease Accounting and Management Software Market