
 Confocal Displacement Sensor Market | 2026-2036
Confocal Displacement Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Confocal Displacement Sensor Market Outlook
The gap between sub-micron precision systems and general-purpose displacement tools is realigning procurement patterns across industrial automation. Keyence Corporation leverages its direct sales model to dominate high-end factory floor installations. Micro-Epsilon sustains technology leadership through in-house production of chromatic confocal optical probes. Panasonic Corporation anchors its position in automotive powertrain inspection through deep integration with Japanese OEMs.
Confocal displacement sensors employ chromatic aberration optics to map surface topography with axial resolution below one hundred nanometers, projecting a polychromatic light spot through an objective lens with calibrated color-to-height encoding. These systems serve primarily as inline metrology instruments for non-destructive thickness verification and dimensional tolerance checking in precision manufacturing. Laser confocal variants command the dominant share of current revenue as semiconductor fabs standardize on chromatic white-light configurations for wafer bow measurement. Fiber optic technology segments show the fastest expansion as machine builders embed miniature probe heads directly into robotic end-effectors for closed-loop process control.
Japan's METI enforces JIS standards for industrial measurement equipment that mandate traceable calibration protocols, pushing vendors to maintain certified service networks. The EU Machinery Directive and CE marking requirements shape product safety and electromagnetic compatibility specifications for systems deployed in European automotive lines. Stakeholders must monitor how China's GB standards evolution and MIIT smart manufacturing mandates redirect procurement specifications toward domestic sensor platforms.
Market Dynamics
Wafer-level packaging architectures in semiconductor fabrication are compressing tolerance bands below fifty nanometers, forcing displacement metrology vendors to recalibrate chromatic confocal probe designs for inline deployment. This precision escalation is redrawing competitive boundaries between fiber-integrated miniature heads and benchtop laboratory systems.
Growth Catalysts
- Semiconductor packaging densification:Three-dimensional integrated circuit stacking in East Asian fabrication corridors demands non-contact thickness verification at bond-line interfaces. Chromatic confocal probes now embed directly into die-attach equipment for real-time bow measurement.
- METI JIS calibration mandates:Japan's Ministry of Economy, Trade and Industry enforces traceable measurement protocols for industrial equipment, compelling sensor vendors to maintain certified service networks that lock in replacement part revenue streams.
- Fiber optic probe miniaturization:Machine builders in precision automotive powertrain inspection are embedding sub-millimeter diameter confocal heads into robotic end-effectors, enabling closed-loop dimensional correction during camshaft and transmission component machining.
Market Restraints
- Optical component supply concentration:High-dispersion objective lenses and specialized chromatic aberration optics rely on a concentrated supplier base in German and Japanese precision glass manufacturing, creating single-source vulnerability for probe head production.
- Capital intensity of calibration infrastructure:Establishing NIST-traceable or JIS-certified height standard laboratories requires seven-figure investments in interferometric reference systems and climate-controlled metrology environments, elevating barriers for regional service expansion.
- Laser triangulation substitution:Lower-cost red and blue laser displacement sensors capture share in general-purpose factory automation where sub-micron precision is unnecessary, compressing price floors for standard confocal configurations.
Strategic Opportunities
- Battery electrode inspection in electric vehicle manufacturing:Calendering and coating thickness control for lithium-ion cell production represents an underpenetrated application where chromatic confocal sensors can displace contact profilometers in electrode web processing lines.
- EU Machinery Directive safety integration:CE marking requirements for electromagnetic compatibility and functional safety in European automotive assembly create specification pull for certified sensor platforms that bundle displacement measurement with safety-rated I/O modules.
- Convergence with machine vision architectures:Integration of confocal height data with 2D camera inspection systems through common GigE Vision interfaces enables unified metrology workstations that reduce controller hardware count and simplify operator interfaces.
Industry Challenges
- Multi-physics simulation expertise scarcity:Designing chromatic confocal probes requires simultaneous optimization of optical ray tracing, thermal drift modeling, and mechanical vibration isolation, yet qualified optical-mechanical engineers remain concentrated in legacy microscopy and lithography equipment firms.
- Legacy PLC integration complexity:Semiconductor fabs and automotive lines operate established programmable logic controller architectures with proprietary fieldbus protocols, forcing sensor vendors to maintain extensive gateway and adapter portfolios that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Confocal Displacement Sensor Market |
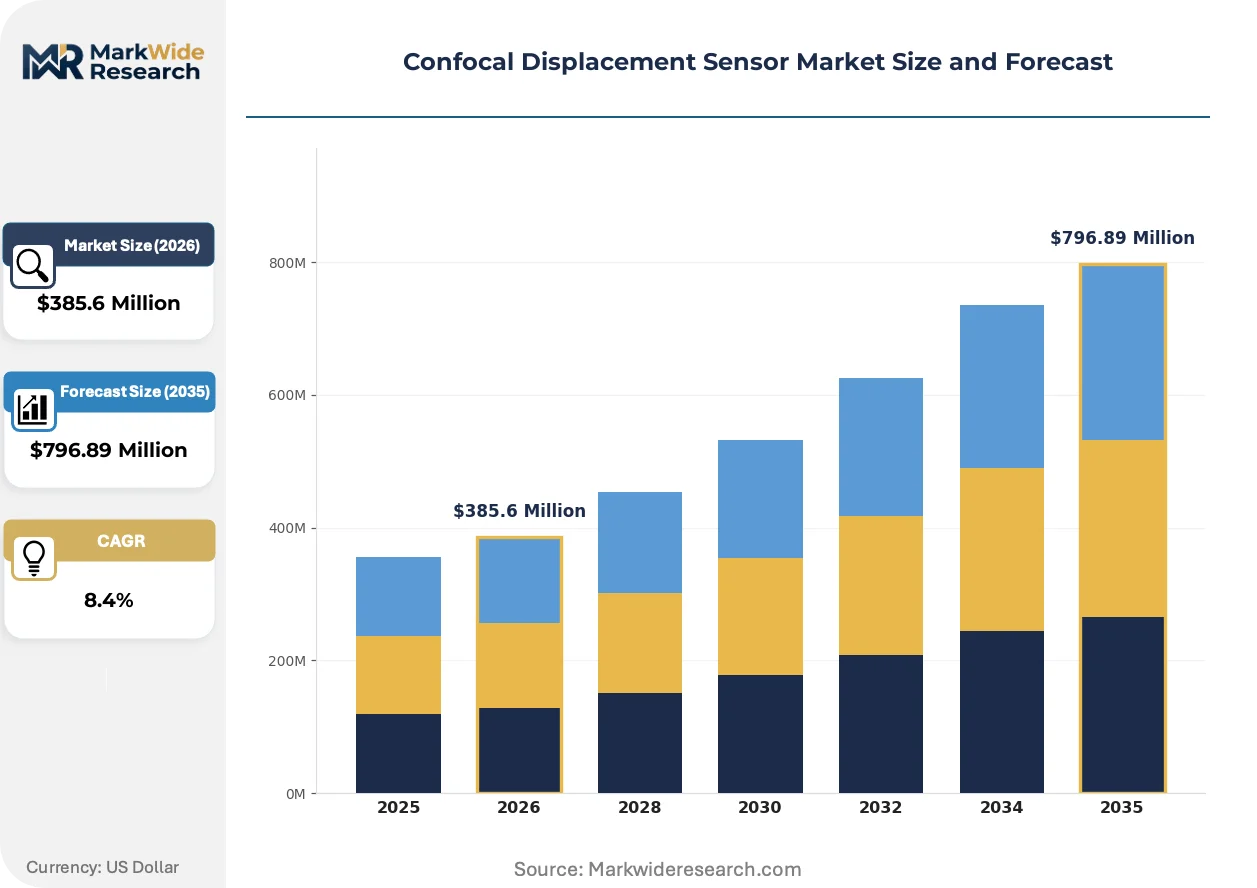
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $796.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Confocal, Optical, Non-Contact, 3D Technology: Fiber Optic, Digital Signal, Analog Signal, Photoelectric End User: Aerospace, Manufacturing, Automotive, Research Laboratories Application: Thickness Measurement, Surface Profiling, Dimensional Inspection, 3D Mapping |
| Companies Covered | Keyence Corporation, Micro-Epsilon, OMRON, Precitec, LMI Technologies, SICK AG, Acuity Laser, Panasonic Corporation, STIL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Confocal Displacement Sensor Market Strategic Shifts
Displacement metrology is migrating from quality laboratory benches toward production machinery cores, with sensor architectures compressing to fit robotic end-effector form factors while preserving nanometer-scale resolution.
Chromatic confocal fiber probes are expanding into semiconductor wafer handling equipment, projecting polychromatic light through flexible fiber bundles that isolate vibration-sensitive optics from motion platforms. Equipment builders at advanced packaging facilities in Taiwan and South Korea are specifying these probes for die-level thickness mapping during temporary bonding and debonding operations. The technology is compressing the traditional separation between metrology stations and process equipment, enabling closed-loop thickness correction without wafer transfer delays.
Japan's METI has tightened JIS B 7440 standards for optical displacement sensors, mandating documented calibration uncertainty budgets and environmental temperature compensation coefficients. Vendors must now submit third-party validation data for axial linearity and repeatability across specified operating ranges. Japanese automotive OEMs and their tier-one machine suppliers are prioritizing procurement specifications that reference these updated standards, filtering non-compliant platforms from qualified vendor lists.
Machine builders are unbundling sensor hardware from application software, selling probe heads and controllers separately from measurement algorithm licenses. This model displaces the traditional integrated-system sale in European and East Asian markets where end-users possess internal software development capabilities. German automotive component manufacturers and Chinese battery equipment builders increasingly specify bare confocal probes for integration into proprietary quality data infrastructures, compressing margins for turnkey solution providers while expanding addressable volume for component specialists.
Confocal Displacement Sensor Market Segmentation
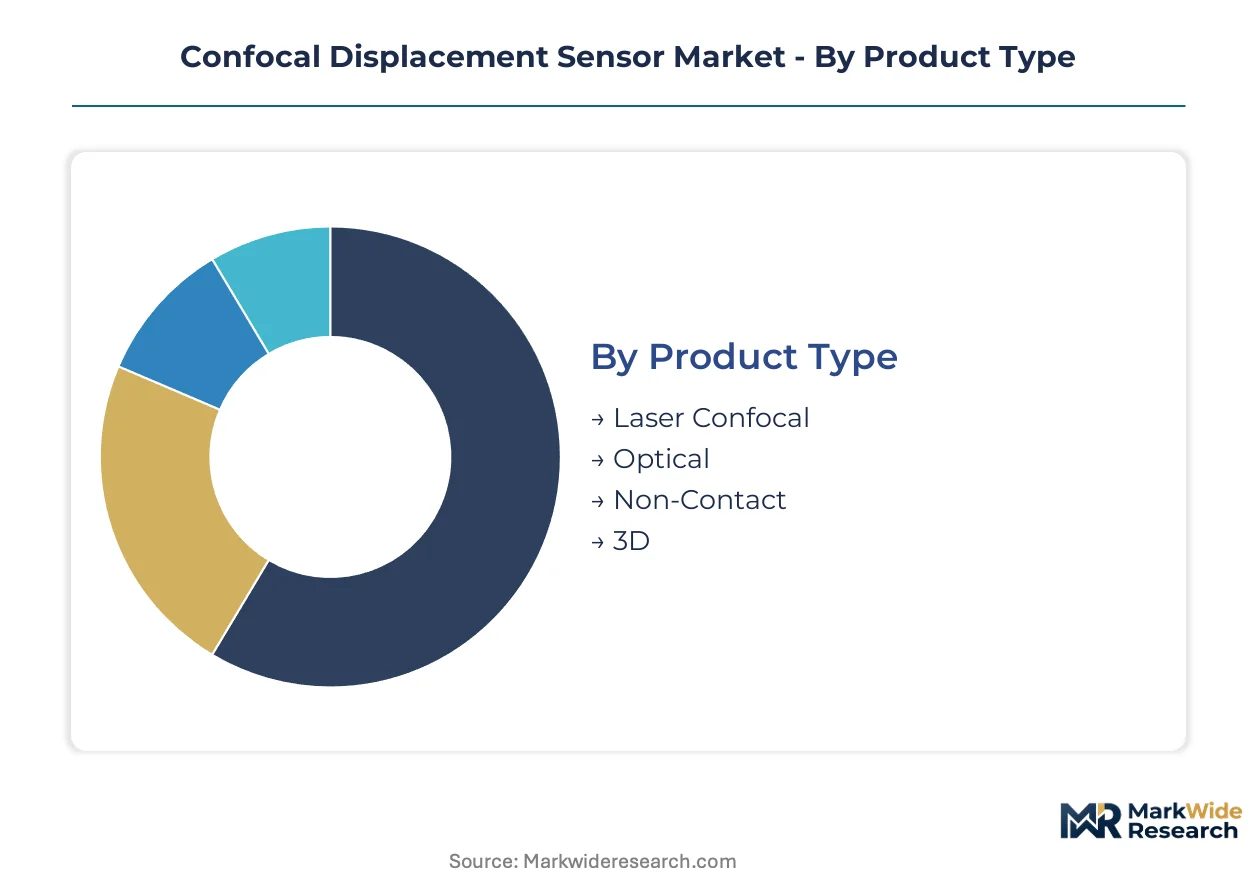
Confocal displacement sensors fragment across multiple technical dimensions that dictate procurement economics and deployment complexity. Product architecture, signal processing method, and end-use environment each impose distinct qualification requirements and service infrastructure demands.
Product Type:
Laser confocal configurations demand the steepest upfront capital commitment due to precision optical benches and interferometric calibration rigs.
- Laser Confocal:These systems project monochromatic laser light through high-numerical-aperture objectives to achieve sub-hundred-nanometer axial resolution. Semiconductor fabrication facilities in Taiwan and South Korea standardize on these platforms for wafer bow measurement during temporary bonding operations, driven by three-dimensional integrated circuit stacking requirements.
- Optical:White-light chromatic confocal variants disperse polychromatic illumination across calibrated spectral bands to encode height information. Automotive powertrain manufacturers in Germany embed these probes into camshaft machining lines for real-time dimensional correction, compelled by tighter tolerance bands on electrified drivetrain components.
- Non-Contact:General-purpose displacement sensors eliminate mechanical stylus wear in high-throughput factory automation. Electronics assembly lines in China's Yangtze River Delta deploy these for PCB warpage inspection.
- 3D:Multi-point confocal arrays capture complete surface topography in single acquisition cycles. Battery electrode calendering operations in electric vehicle manufacturing corridors utilize these for coating thickness mapping.
Laser confocal systems absorb the bulk of installed capacity; 3D multi-point configurations are expanding most quickly.
Technology:
Signal processing architecture determines integration complexity and electromagnetic immunity in industrial environments.
- Fiber Optic:Flexible probe heads isolate vibration-sensitive optics from motion platforms through coherent fiber bundles. Machine builders in precision automotive lines specify these for robotic end-effector integration, enabling closed-loop process control without optical bench recalibration.
- Digital Signal:DSP-based demodulation enables direct GigE Vision interface compatibility with machine vision architectures. European automotive assembly plants favor these for unified metrology workstations that consolidate controller hardware.
- Analog Signal:Voltage-output configurations interface with legacy programmable logic controller architectures prevalent in established semiconductor fabs. These require proprietary gateway adapters that fragment vendor engineering resources.
- Photoelectric:Direct photodiode arrays simplify electronics for cost-sensitive displacement applications. General manufacturing automation in Southeast Asia adopts these where sub-micron precision is unnecessary.
Digital signal processing commands the highest average selling prices; fiber optic probe heads are climbing the fastest.
End User:
Industry-specific qualification protocols and calibration traceability requirements shape vendor selection criteria.
- Aerospace:Turbine blade inspection and airframe assembly verification demand NIST-traceable uncertainty budgets. US and European OEMs mandate documented environmental temperature compensation coefficients.
- Manufacturing:Precision machining and electronics assembly lines prioritize throughput and operator interface simplicity. China's MIIT smart manufacturing directives redirect procurement toward domestic-qualified platforms.
- Automotive:Powertrain component inspection and battery electrode processing require safety-rated I/O modules for CE marking compliance. Japanese OEMs filter procurement through METI JIS B 7440 certified vendor lists.
- Research Laboratories:Materials science and metrology institutes seek configurable software environments and raw data access. These buyers increasingly specify bare probes for proprietary algorithm development.
Automotive end-use absorbs the bulk of current procurement volume; research laboratory demand is gaining share fastest.
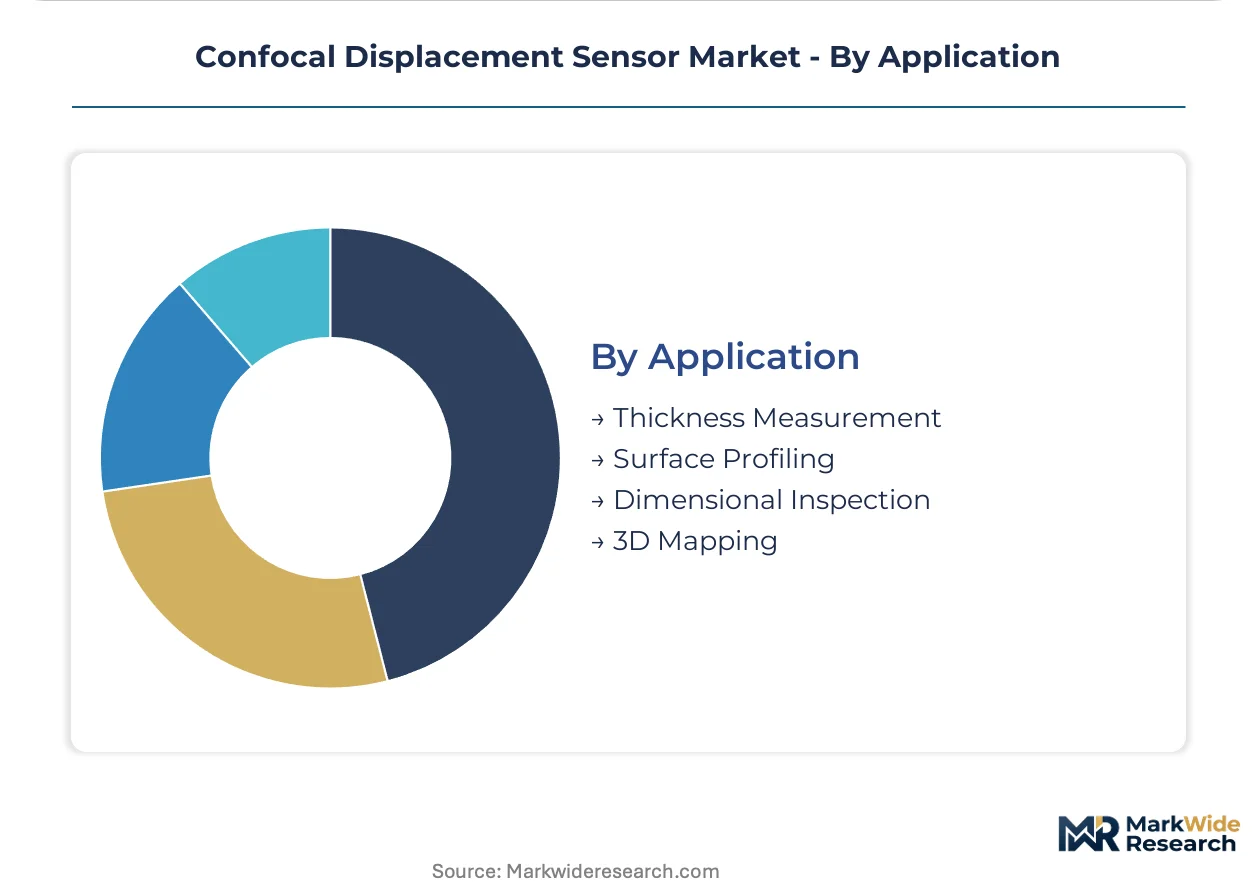
Application:
Measurement task geometry and throughput requirements determine probe head specifications and controller architecture.
- Thickness Measurement:Bond-line verification in wafer-level packaging and electrode coating control dominate this segment. Inline deployment without wafer transfer delays drives adoption of fiber-integrated miniature heads.
- Surface Profiling:Roughness and texture characterization for precision bearings and optical components requires high lateral sampling density. German automotive component manufacturers specify these for camshaft lobe finish verification.
- Dimensional Inspection:Geometric tolerance checking in machined components tolerates lower axial resolution for higher measurement speed. General factory automation in Southeast Asia favors these for cost-sensitive deployment.
- 3D Mapping:Complete topography capture for reverse engineering and defect documentation demands multi-point or scanning architectures. Battery manufacturing lines utilize these for electrode web uniformity verification.
Thickness measurement holds the largest installed base; 3D mapping applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta manufacturing corridor dominates confocal displacement sensor deployment, with Shanghai and Suzhou hosting the densest concentration of semiconductor packaging lines demanding nanometer-scale metrology.
China
Wafer-level packaging facilities in Jiangsu and Zhejiang provinces drive fiber-optic probe adoption for inline thickness verification. MIIT smart manufacturing mandates redirect procurement specifications toward domestic-qualified sensor platforms. Equipment builders in Suzhou Industrial Park embed miniature confocal heads directly into die-attach machinery for real-time bow measurement.
Japan
Automotive powertrain manufacturers in Aichi Prefecture specify chromatic confocal systems for camshaft dimensional correction during electrified drivetrain production. METI enforces JIS B 7440 calibration standards that mandate traceable uncertainty budgets and temperature compensation documentation. Nagoya-based machine suppliers filter procurement through certified vendor lists, locking in replacement part revenue for compliant vendors.
South Korea
Three-dimensional integrated circuit stacking at Samsung and SK Hynix facilities in Gyeonggi Province compresses tolerance bands below fifty nanometers. The national semiconductor regulator enforces measurement traceability protocols for advanced packaging equipment. Pangyo Techno Valley hosts the primary concentration of probe integration specialists serving memory fab lines.
Germany
Automotive component manufacturers in Baden-Württemberg embed white-light chromatic probes into camshaft machining lines for surface finish verification. CE marking requirements under the EU Machinery Directive mandate electromagnetic compatibility and functional safety integration. Stuttgart's precision engineering cluster demands bundled sensor platforms with safety-rated I/O modules.
United States
Aerospace OEMs in Washington State and California mandate NIST-traceable uncertainty budgets for turbine blade inspection systems. FAA airworthiness directives shape metrology equipment qualification protocols for defense subcontractors. Seattle-Tacoma manufacturing corridors concentrate demand for environmental temperature compensation in large-structure assembly verification.
Confocal Displacement Sensor Market Competitive Environment
Premium-margin players sit above commodity-margin players across calibration certification tiers, with JIS-certified and NIST-traceable service networks commanding pricing multiples over uncertified alternatives. The vendor base stratifies between integrated turnkey solution providers and bare probe component specialists. Three archetypes dominate: direct-sales industrial automation conglomerates, precision optics specialists with in-house probe manufacturing, and machine vision integrators bundling displacement data with 2D camera systems. Geographic expansion through certified service laboratories and technology licensing for fiber-optic miniaturization represent the dominant competitive moves.
Within the precision optics tier, Micro-Epsilon and STIL exemplify European specialists with captive probe manufacturing capabilities. Keyence Corporation anchors the direct-sales archetype through high-end factory floor installations. Panasonic Corporation occupies a position bridging automotive OEM integration with Japanese regulatory compliance. These three firms represent distinct strategic postures: component specialization, distribution control, and vertical industry anchoring respectively.
| Leading Market Players |
|---|
| Keyence Corporation |
| Micro-Epsilon |
| OMRON |
| Precitec |
| LMI Technologies |
| SICK AG |
| Acuity Laser |
| Panasonic Corporation |
| STIL |
| Others |
Value Chain & Pricing Dynamics
High-dispersion objective lenses manufactured in Schott's German facilities and specialized chromatic aberration optics from Japanese precision glass makers cascade through probe head assembly costs into three-tier pricing structures across premium, standard, and economy levels. JIS-certified calibration service networks in Nagoya and Stuttgart command pricing multiples over uncertified alternatives, while fiber-integrated miniature heads for robotic end-effectors extract premiums from automotive powertrain manufacturers in Baden-Württemberg.
Pricing Analysis
Yield-guarantee pricing anchors sensor procurement decisions in semiconductor packaging lines, where inline bow measurement failures trigger wafer scrap costs dwarfing hardware premiums. Price differentiation separates JIS B 7440-certified platforms with documented uncertainty budgets from uncertified alternatives, while volume scale discounts compress margins for standard confocal configurations. Cost compression in general-purpose factory automation intensifies as laser triangulation sensors displace chromatic confocal systems where sub-micron precision is unnecessary. Electronics assembly buyers in China's Yangtze River Delta exhibit highest price sensitivity; aerospace OEMs in Washington State demonstrate lowest sensitivity due to NIST-traceability mandates.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Nagoya, and Shanghai operate hub-and-spoke patterns to serve precision manufacturing clusters within forty-eight-hour windows. Probe head production draws from concentrated German and Japanese precision glass manufacturing for high-dispersion objectives, with fiber bundle drawing concentrated in South Korean and Chinese facilities. Single-source vulnerability for chromatic aberration optics creates supply chain risk given limited qualified suppliers for calibrated color-to-height encoding lenses. Distribution runs through direct-sales industrial automation channels for high-end installations, with bare probe component specialists serving machine builders through distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into captive probe manufacturing to escape optical component supply concentration and capture calibration service revenue.
For Market Incumbents: Lock in replacement part revenue streams by expanding JIS-certified service laboratories in Aichi Prefecture and Gyeonggi Province. Deepen captive supply of chromatic confocal optical probes to insulate margins from German and Japanese precision glass supplier pricing power. Laser triangulation substitution in general-purpose automation represents the primary threat to standard configuration price floors. For New Entrants and Emerging Players: Enter via battery electrode inspection for electric vehicle manufacturing, where chromatic confocal sensors remain underpenetrated against contact profilometers in calendering lines. Target Chinese domestic-qualified platform procurement under MIIT smart manufacturing mandates as the most penetrable geography. License fiber-optic miniaturization technology from European precision optics specialists rather than building optical-mechanical engineering capabilities from scratch. For Investors and Strategic Acquirers: Distressed-cycle entries favor bare probe component specialists with GigE Vision interface capabilities in German precision engineering clusters. Long-term viability hinges on unbundling trends where machine builders specify probe hardware separately from measurement algorithm licenses. Watch for inflection when Chinese battery equipment builders accelerate domestic sensor platform qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Service Laboratory Expansion | JIS B 7440 compliance in Nagoya locks in Japanese automotive OEM procurement. |
| Fiber-Optic Miniaturization Licensing | Technology transfer to Chinese machine builders accelerates domestic platform adoption. |
| Battery Electrode Inspection Entry | Displacement of contact profilometers in calendering lines opens volume expansion. |
| GigE Vision Interface Integration | Unified metrology workstations reduce controller hardware count in European automotive assembly. |
| Backward Integration into Probe Manufacturing | In-house production of chromatic confocal optical probes insulates supply risk from German glass suppliers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this confocal displacement sensor market analysis. Primary interviews with precision optics procurement managers at semiconductor packaging facilities, metrology equipment sales directors, automotive powertrain quality engineers, and fiber-optic probe integration specialists validated demand assumptions. METI JIS standard documentation, EU Machinery Directive CE marking databases, and China MIIT smart manufacturing policy circulars provided regulatory calibration requirements. Bottom-up probe shipment estimates triangulated against top-down semiconductor capital expenditure patterns and automotive powertrain inspection equipment budgets.
Segment-level granularity modeled product architecture across laser confocal, white-light chromatic, and fiber-optic probe configurations; signal processing method through analog, digital, and photoelectric demodulation; and end-use environment spanning semiconductor fabrication, automotive powertrain, and battery electrode processing. Technology diffusion curves for fiber-integrated miniature heads and multi-point 3D arrays informed expansion rates across the analysis window. CAGRs derived from equipment investment cycles in East Asian wafer-level packaging facilities and European automotive electrification programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt shifts in semiconductor capital expenditure cycles or Chinese domestic sensor platform procurement mandates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Magnetoresistance Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
North America Proximity Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Europe Vibration Sensors Market