
 Organic Feed Market | 2026-2036
Organic Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Feed Market Analysis
The capital-intensity gap between integrated millers and regional blenders is collapsing as equipment costs fall and organic grain sourcing networks mature. Modesto Milling Inc leverages its California grain belt proximity to anchor West Coast supply chains. Aller Aqua Group competes through aquaculture-specific formulation expertise across Northern European markets. K-Much Industry Co. Ltd dominates Asian aquaculture feed channels with plant-based ingredient specialization.
Organic feed comprises formulated rations manufactured without synthetic pesticides, genetically modified organisms, or growth-promoting antibiotics, typically containing minimum organic ingredient thresholds ranging from 95% to 100% depending on certification grade. Its primary commercial purpose centers on enabling livestock producers to meet organic certification standards while maintaining nutritional parity with conventional rations. Pellet formats command premium positioning due to reduced waste and automated handling compatibility across large-scale poultry operations. Plant-based ingredient sourcing draws the fastest capacity expansion as soybean and pea protein concentrates displace fishmeal in aquaculture and poultry formulations.
The USDA National Organic Program governs feed composition and labeling within the United States, while the EU Organic Regulation 2018/848 standardizes input requirements across member states. Both frameworks directly constrain ingredient procurement and elevate compliance costs for non-certified suppliers. Stakeholders must monitor evolving certification reciprocity agreements between major producing regions to anticipate sourcing disruption risks.
Market Dynamics
The USDA National Organic Program's tightened feed certification requirements are compressing the supplier base while EU Green Deal agricultural targets redirect procurement toward certified organic inputs, creating a bifurcation between integrated millers and regional blenders.
Growth Catalysts
- EU Green Deal agricultural targets:The EU Green Deal mandates sustainable livestock input sourcing across member states, redirecting procurement volumes toward certified organic feed channels and reshaping supplier relationships in Northern European markets.
- Poultry sector procurement expansion:United States poultry farmers are scaling organic feed volumes to meet tightening USDA National Organic Program standards, driving demand concentration among vertically integrated operations seeking certification compliance.
- Pea protein concentrate technology:Advances in plant-based protein extraction are enabling fishmeal substitution in aquaculture formulations, opening formulation flexibility for feed manufacturers serving Asian and European aquaculture channels.
Market Restraints
- Organic grain input cost volatility:Weather-dependent organic soybean and corn harvests in the United States and Brazil create margin compression for non-integrated blenders lacking captive grain sourcing.
- Certification reciprocity friction:Divergent organic standards between the USDA National Organic Program and EU Organic Regulation 2018/848 generate compliance duplication costs for exporters serving transatlantic markets.
- Conventional feed price arbitrage:Persistent price gaps between organic and conventional rations limit conversion rates among cost-sensitive livestock operations in price-competitive protein markets.
Strategic Opportunities
- Underpenetrated Brazilian organic livestock sector:Brazil's expanding organic beef and dairy production lacks domestic organic feed capacity, creating import substitution potential for suppliers with South American grain sourcing networks.
- Pellet format automation compatibility:Large-scale poultry operations in the United States are retrofitting handling systems for pellet formats, rewarding suppliers with extrusion capabilities and automated delivery infrastructure.
- EU Organic Regulation 2018/848 enforcement expansion:Stricter input verification requirements across EU member states are disqualifying non-compliant suppliers, opening market share for certified operators with established audit trails.
Industry Challenges
- Organic certification timeline compression:The three-year land conversion requirement for organic grain sourcing under USDA National Organic Program standards constrains rapid capacity expansion for new market entrants.
- Formulation talent scarcity:Specialized expertise in organic amino acid balancing and plant-based ingredient optimization remains concentrated among legacy operators, limiting new competitor technical capabilities.
- Supply chain traceability system integration:Retrofitting legacy batch tracking systems to meet EU Organic Regulation 2018/848 and USDA audit requirements demands capital investment and operational reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Feed Market |
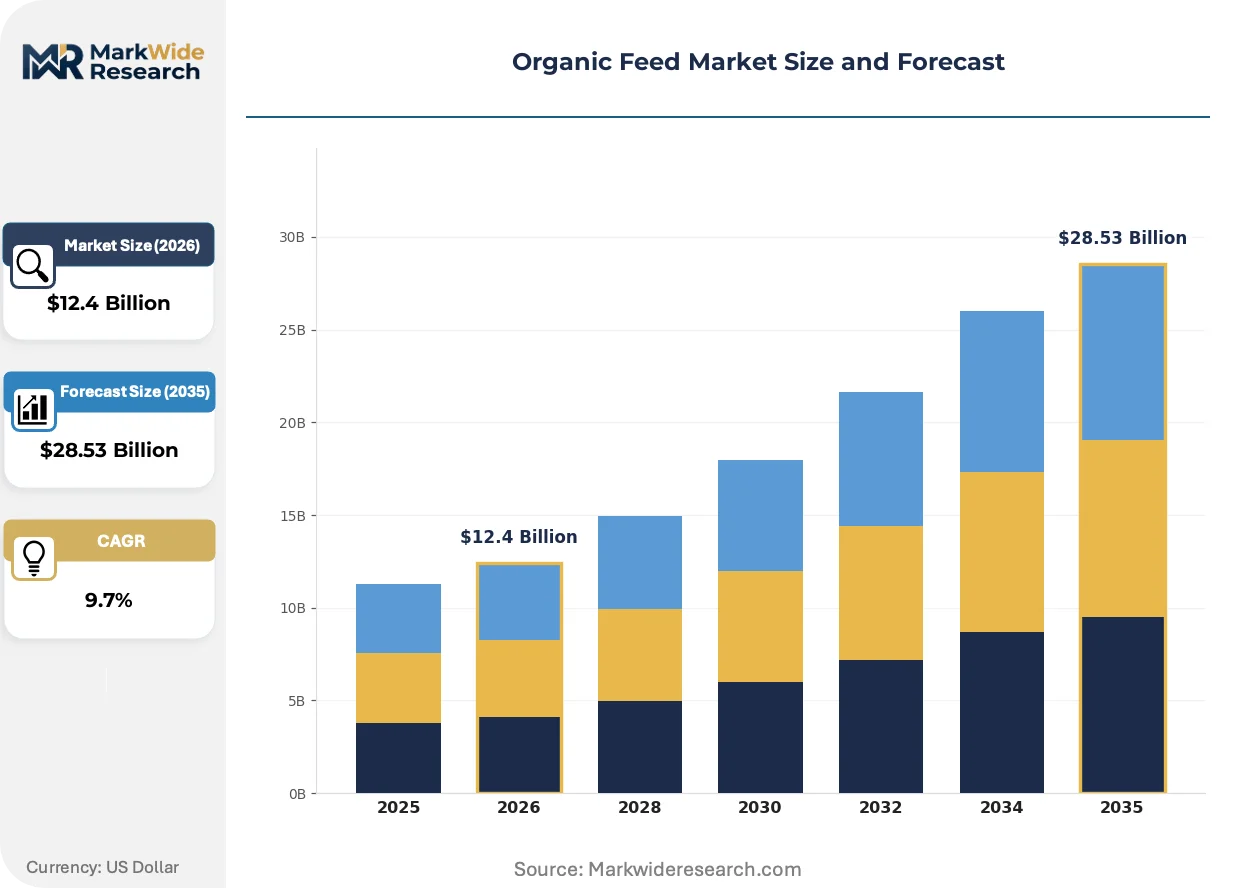
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Mash, Crumbles, Extruded Ingredient Source: Plant-Based, Animal By-Products, Minerals, Vitamins End User: Poultry Farmers, Livestock Producers, Aquaculture, Pet Owners Distribution Channel: Online Retail, Agricultural Stores, Wholesale Distributors, Farm Supply Stores |
| Companies Covered | Aller Aqua Group, BW Feeds, Country Junction Feeds, Hi Peak Feeds, K-Much Industry Co. Ltd, Modesto Milling Inc, Ranch-Way Feeds, Yorktown Organics LLC, The Organic Feed Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Feed Market Emerging Trajectories
Formulation science and certification technology are converging to reshape competitive advantage in organic feed manufacturing, with automation and traceability systems becoming as critical as ingredient sourcing networks.
Precision fermentation-derived proteins are supplanting fishmeal and soybean meal in premium aquaculture and poultry formulations. Nordic and Southeast Asian aquaculture operators are adopting these inputs at pilot scale to meet marine ingredient reduction targets. This technology is supplanting traditional protein procurement patterns by enabling geographic decoupling from agricultural commodity cycles.
EU Organic Regulation 2018/848 mandates electronic traceability systems for all organic feed inputs across member states by 2026. The regulation forces millers to implement batch-level digital tracking from grain elevator to finished product. Small and mid-sized regional blenders in Germany and France are consolidating or partnering with technology providers to achieve compliance cost efficiency.
Livestock producers are consolidating procurement relationships around full-service feed partners capable of certification documentation, nutritional consulting, and automated delivery. This pattern displaces transactional commodity purchasing in the United States and Netherlands, where large poultry and dairy operations prioritize supply security over spot-price optimization. The shift is most visible among vertically integrated egg and broiler producers seeking streamlined audit compliance.
Organic Feed Market Segmentation
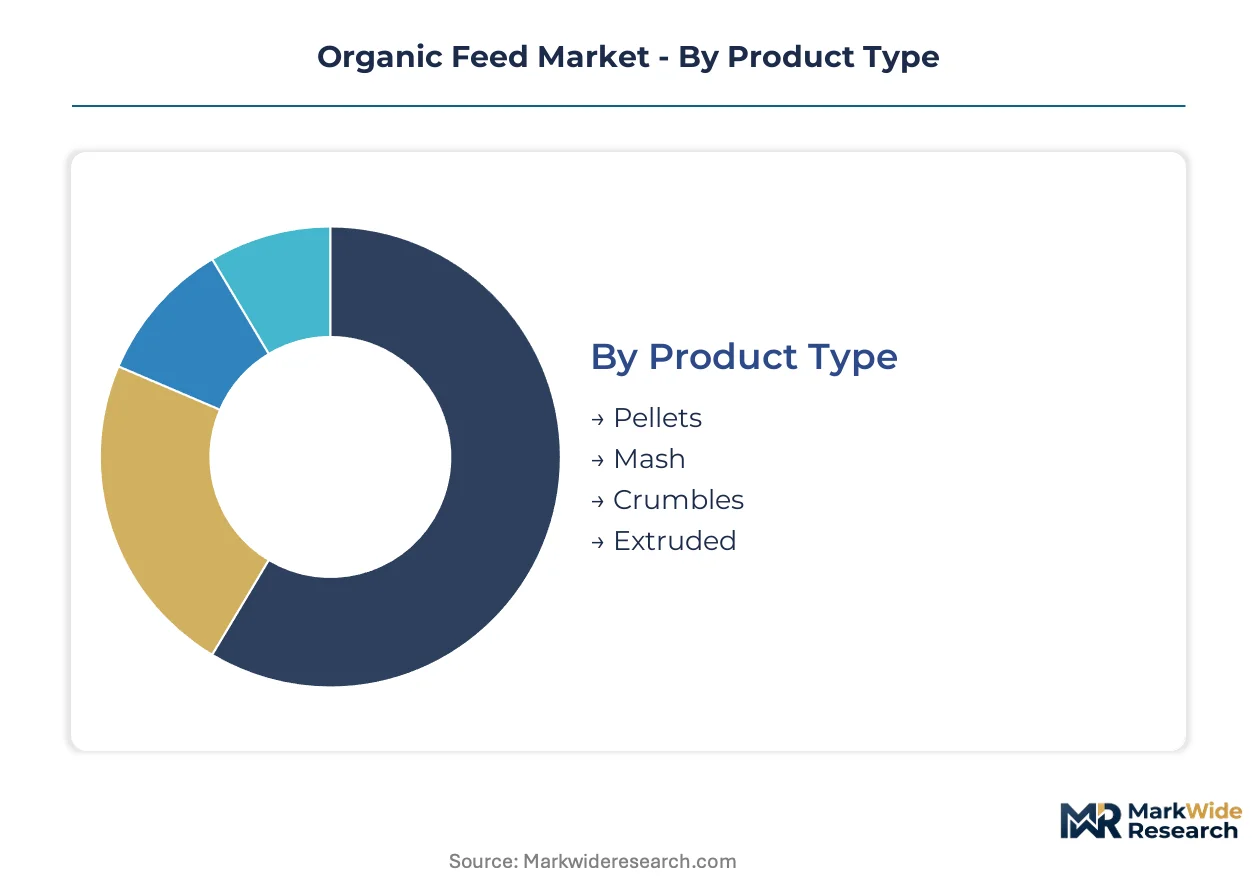
Organic feed segmentation reveals how formulation formats, ingredient sourcing strategies, and procurement channels align with distinct certification requirements and handling infrastructure across livestock sectors. Understanding these divisions exposes where capital deployment and compliance investment concentrate.
Product Type:
Pellet and crumble formats dominate domestic procurement in the United States and Germany, while mash retains export-led demand across Southeast Asian aquaculture channels.
- Pellets:Compressed cylindrical formulations manufactured through high-temperature extrusion achieve density uniformity and reduced dust loss. United States poultry integrators retrofit automated handling systems for pellet compatibility, driving procurement concentration among operations exceeding 500,000 bird capacity.
- Mash:Unprocessed ground meal blends preserve raw ingredient integrity for species requiring lower processing intensity. Vietnamese and Indonesian shrimp farms source mash formats for pond-side manual distribution, constrained by limited extrusion infrastructure in Mekong Delta supply zones.
- Crumbles:Pellet fragments sized for starter-phase poultry and young ruminants bridge mash digestibility with pellet handling efficiency.
- Extruded:High-pressure thermal processing gelatinizes starches and eliminates pathogens, serving premium pet food and specialty aquaculture channels.
Pellets command the established base. The steepest expansion runs through extruded formats.
Ingredient Source:
Cost tier differentiation separates commodity-scale plant proteins from premium mineral and vitamin premixes serving certified organic compliance.
- Plant-Based:Soybean meal, pea protein concentrates, and corn gluten meal constitute the primary nitrogen source for poultry and swine rations. EU Green Deal agricultural targets accelerate substitution of fishmeal with plant proteins in Danish and Dutch aquaculture operations.
- Animal By-Products:Processed fishmeal, blood meal, and feather meal deliver amino acid profiles unattainable from plant sources alone. Norwegian salmon farmers balance marine ingredient reduction mandates against growth performance requirements through precision inclusion rates.
- Minerals:Chelated trace elements from approved geological deposits replace synthetic mineral supplements prohibited under USDA National Organic Program standards.
- Vitamins:Natural-source fat-soluble and water-soluble compounds derived from fermentation or plant extraction satisfy certification thresholds.
Plant-based sourcing anchors volume leadership. The fastest value growth concentrates in mineral premixes.
End User:
Customer type fragmentation separates vertically integrated commodity producers from fragmented specialty operators with diverging certification timelines.
- Poultry Farmers:United States broiler and layer operations drive the largest procurement volumes, with USDA National Organic Program compliance forcing three-year conversion timelines that lock in supplier relationships.
- Livestock Producers:Organic dairy and beef operations in France and Germany require ruminant-specific formulations with bypass protein protection and mineral balancing for forage-based systems.
- Aquaculture:Salmon, shrimp, and tilapia producers in Norway, Vietnam, and Ecuador face marine ingredient reduction targets that reshape protein procurement.
- Pet Owners:Premium companion animal channels in Japan and South Korea absorb small-batch certified organic production at price multiples exceeding livestock applications.
Poultry farmers represent the volume core. Aquaculture claims the steepest expansion trajectory.
Distribution Channel:
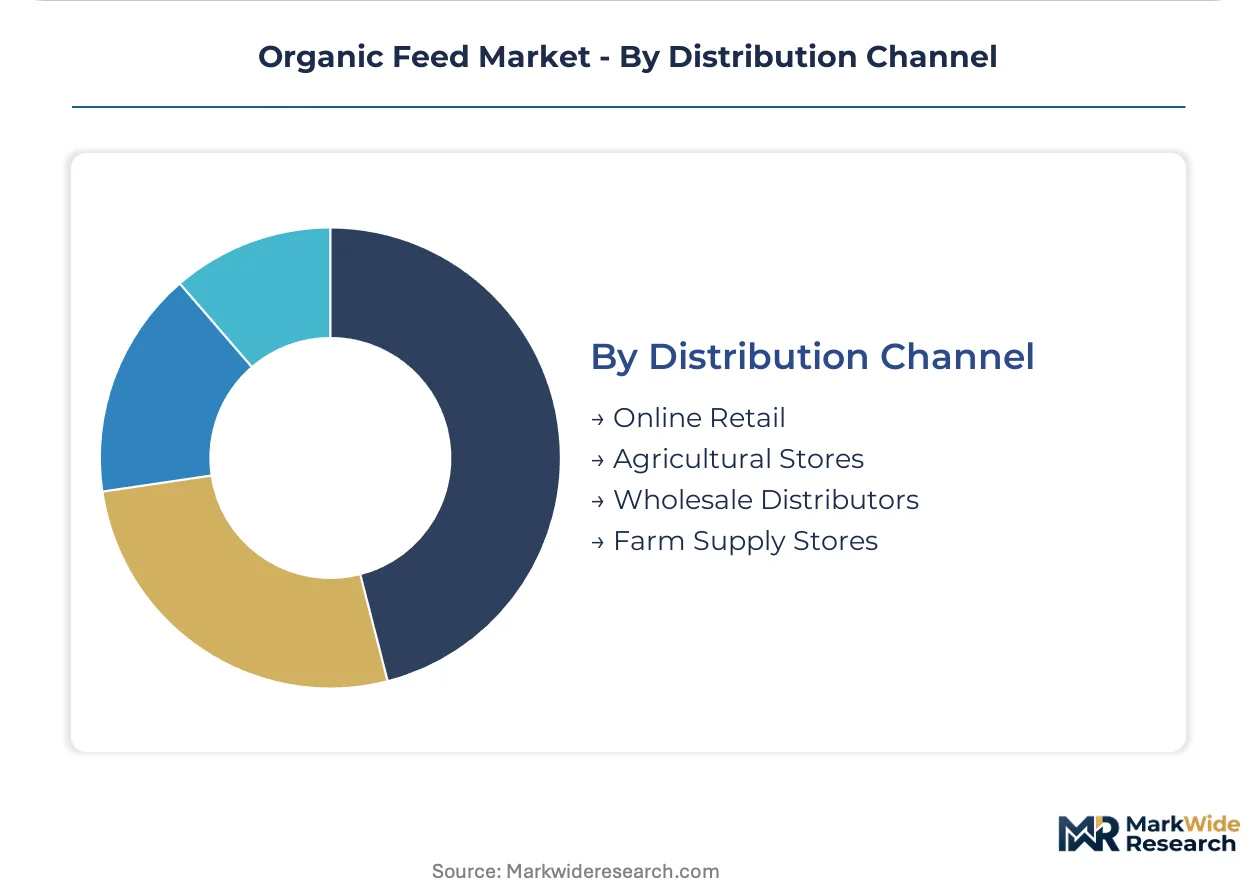
Supply concentration patterns favor wholesale distributors with grain elevator integration, while online retail fragments around specialty and small-lot procurement.
- Wholesale Distributors:Integrated grain handlers with certified organic storage capacity dominate volume flows to United States and Brazilian livestock operations.
- Agricultural Stores:Regional cooperatives in Iowa, Minnesota, and Wisconsin serve mid-scale dairy producers with formulation consulting and delivery logistics.
- Farm Supply Stores:Independent retailers concentrate in Corn Belt counties with dense organic grain production, offering localized technical support.
- Online Retail:Direct-to-producer platforms capture pet food and specialty aquaculture segments requiring small-batch customization and documentation.
Wholesale distributors control the established base. Online retail channels gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers absorb price premiums with minimal elasticity as certification compliance locks in supplier relationships, while Brazilian and Southeast Asian operations remain highly price-sensitive and slow to convert from conventional rations.
United States
Poultry integrators and organic dairy cooperatives drive procurement volumes as the USDA National Organic Program enforces three-year land conversion requirements for grain sourcing. The Corn Belt corridor through Iowa, Minnesota, and Wisconsin concentrates feed milling capacity and organic grain elevator infrastructure. Vertically integrated operations exceeding 500,000 bird capacity dominate volume flows, locking in multi-year supplier contracts.
Germany
Organic dairy and beef producers in Lower Saxony and Bavaria require ruminant-specific formulations with bypass protein protection. The EU Organic Regulation 2018/848 mandates electronic traceability systems by 2026, forcing millers to implement batch-level digital tracking. The Münsterland region anchors Northern European supply chains with dense organic grain production and cooperative milling infrastructure.
Brazil
Expanding organic beef and dairy production in São Paulo and Minas Gerais states lacks domestic organic feed capacity, creating import substitution pressure. The national agricultural regulator enforces organic certification standards that lag EU and US stringency, slowing domestic miller investment. Southern grain belt regions concentrate conventional feed capacity that requires costly conversion for organic compliance.
Vietnam
Shrimp and tilapia producers in the Mekong Delta source mash formats for pond-side manual distribution, constrained by limited extrusion infrastructure. Marine ingredient reduction targets reshape protein procurement toward plant-based concentrates. Can Tho and An Giang provinces anchor aquaculture feed demand, though organic certification penetration remains minimal outside export-oriented operations.
Norway
Salmon farmers balance marine ingredient reduction mandates against growth performance requirements through precision inclusion rates. The national food safety authority enforces strict input verification that aligns with EU Organic Regulation standards. The Bergen-Stavenger corridor concentrates aquaculture feed formulation expertise and precision fermentation protein adoption.
Organic Feed Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with formulation specialists commanding premium positioning while scale-driven millers compete on grain procurement efficiency. The supplier base separates into integrated operators with captive organic grain sourcing and regional blenders dependent on spot markets. Three archetypes dominate: aquaculture formulation specialists, poultry-centric integrated millers, and plant-based protein innovators. Competitive moves concentrate on backward integration into organic grain sourcing and extrusion capacity expansion for pellet format automation compatibility.
Among North American integrated millers, Modesto Milling Inc and Ranch-Way Feeds occupy positions anchored by grain belt proximity and regional distribution density. K-Much Industry Co. Ltd represents the Asian aquaculture specialization archetype, while Aller Aqua Group exemplifies European formulation expertise serving marine ingredient reduction mandates. These three companies illustrate how geographic clustering and species-specific knowledge create defensible positioning against commodity-scale competitors.
| Leading Market Players |
|---|
| Aller Aqua Group |
| BW Feeds |
| Country Junction Feeds |
| Hi Peak Feeds |
| K-Much Industry Co. Ltd |
| Modesto Milling Inc |
| Ranch-Way Feeds |
| Yorktown Organics LLC |
| The Organic Feed Company |
| Others |
Supply Flow & Price Mechanics
Pea protein concentrate substitution for fishmeal is redrawing procurement geography from marine-dependent Norway toward plant-protein processing clusters in Denmark and the Netherlands while compressing formulation cost structures for aquaculture feed manufacturers. This input shift simultaneously weakens traditional fishmeal suppliers' pricing power and elevates grain belt proximity as a cost determinant for competitive positioning.
Pricing Analysis
After-sales revenue from nutritional consulting and certification documentation drives lifetime value more than commodity feed margins. Three-tier pricing structure across premium, standard, and economy levels separates fully certified organic rations from transitional-grade blends and conventional alternatives. Price differentiation hinges on USDA National Organic Program certification tier and volume scale commitments. Pricing pressure stems from organic grain input cost volatility as weather-dependent harvests in the United States and Brazil squeeze non-integrated blenders. Small-scale poultry farmers in Southeast Asia exhibit highest price sensitivity, while United States integrators absorbing certification lock-in costs show minimal elasticity.
Supply Chain Analysis
Strategic stockpile preferences dominate organic feed supply chains as the three-year land conversion requirement under USDA National Organic Program standards prevents rapid input sourcing adjustments. Geographic supply concentration centers on the United States Corn Belt, Brazil's southern grain belt, and Northern European cooperative milling clusters in Germany and Denmark. Raw material dependencies rest on organic soybean and corn harvests, pea protein concentrates, and precision fermentation-derived proteins. Single-source vulnerability runs through certified organic grain elevator infrastructure where limited storage capacity creates bottleneck risk. Distribution runs through wholesale distributors with integrated grain handling and certified storage capabilities serving large-scale livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated poultry operations exceeding 500,000 bird capacity, forcing suppliers to absorb documentation burdens and accept multi-year contract terms that lock in procurement relationships.
For Market Incumbents: Secure captive organic grain sourcing through long-term land lease arrangements or cooperative partnerships in Iowa and Minnesota to defend against margin compression from spot market volatility. Expand extrusion capacity for pellet format compatibility as United States poultry integrators retrofit automated handling systems, creating technical barriers for regional blenders lacking capital investment capability. For New Entrants and Emerging Players: EU Organic Regulation 2018/848 fast-track certification pathways offer entry acceleration for millers willing to invest in batch-level digital tracking systems ahead of the 2026 enforcement deadline. Target underpenetrated Brazilian organic beef and dairy operations in São Paulo state lacking domestic feed capacity, leveraging South American grain sourcing networks to displace import-dependent supply chains. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed regional blenders in Germany and France facing EU traceability compliance cost pressures that favor consolidation. Five-to-ten year viability favors operators with backward integration into organic grain sourcing and established audit trail infrastructure. Monitor USDA-EU certification reciprocity negotiations as the inflection signal for transatlantic sourcing disruption risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Grain Sourcing | Captive supply of certified corn and soybeans insulates margins from spot market volatility in Brazil and the United States. |
| Extrusion Capacity Expansion for Pellet Formats | Automated handling compatibility secures procurement contracts with large-scale United States poultry integrators retrofitting feed systems. |
| EU Traceability System Implementation | Batch-level digital tracking compliance opens market share as EU Organic Regulation 2018/848 disqualifies non-compliant regional blenders. |
| Precision Fermentation Protein Partnerships | Technology licensing agreements with Nordic suppliers enable fishmeal substitution for aquaculture customers facing marine ingredient reduction mandates. |
| Brazilian Market Entry Through Distribution Alliances | Local partnerships with agricultural cooperatives in São Paulo bypass import substitution barriers for organic beef and dairy feed demand. |
Methodological Framework
The analysis maps poultry feed formulations, aquaculture rations, ruminant blends, and pet food applications, each validated through procurement directors at integrated livestock operations, feed mill technical managers, organic certification auditors, and grain elevator operators. Primary interviews across these stakeholder categories combined with secondary validation from USDA National Organic Program filings, EU Organic Regulation 2018/848 implementation guidance, customs trade data for organic grain flows, and SEC 10-K disclosures from publicly traded agribusiness operators. Bottom-up volume estimates from individual facility capacity and top-down market sizing from agricultural input expenditure data were triangulated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product format, ingredient source, end-user species, and distribution channel complexity alongside regional regulatory cluster variations. CAGRs were derived from fitted growth curves incorporating organic livestock herd expansion rates, certification conversion timelines, and substitution elasticities between organic and conventional rations. Industry-specific forecast inputs included three-year land conversion lags for organic grain supply and marine ingredient reduction mandate compliance trajectories.
The analysis sits within stated boundaries; outcomes outside sustained organic certification premium retention and stable grain belt harvest conditions would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and procurement relationship lock-in durability. Revision becomes warranted when EU-US certification reciprocity negotiations or climate-induced organic grain yield volatility cross threshold levels that disrupt established supply chain economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Asia-Pacific Rapeseed Oil Market
Agriculture and Agri Products
Palm Kernel Expeller Market
Agriculture and Agri Products
United Kingdom Commercial Greenhouse Market
Agriculture and Agri Products
South America Compound Feed Market
Agriculture and Agri Products
Germany Compound Feed Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Cassava Starch Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Boswellia Market
Agriculture and Agri Products
Asia Pacific Animal Feed Market
Agriculture and Agri Products
Asia-Pacific Poultry Meat Market
Agriculture and Agri Products
Animal Feed Ingredients Market
Agriculture and Agri Products
United Kingdom Poultry Meat Market
Agriculture and Agri Products
Organic Cassava Flour Market
Agriculture and Agri Products
Oman Agriculture Market