
 Germany Digital Twin Market | 2026-2036
Germany Digital Twin Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Twin Market Insights
Germany is narrowing its industrial software gap through targeted digital twin investments across automotive and precision engineering clusters. Siemens AG leverages deep manufacturing heritage to dominate factory-floor simulation deployments. Bosch sustains R&D intensity in IoT-enabled twin architectures for predictive maintenance. Dassault Systèmes anchors its position through product lifecycle management integration with virtual prototyping capabilities.
A digital twin constitutes a virtual representation of a physical asset, system, or process that ingests real-time sensor data and applies computational models to simulate behavior, predict performance, and optimize operations without disrupting live production environments. Software platforms command the largest revenue share as enterprises prioritize cloud-based simulation environments over on-premise hardware. Manufacturing applications lead adoption volumes, while healthcare represents the fastest-expanding segment as German hospitals deploy patient-specific organ twins for surgical planning. Enterprise end users absorb the majority of platform spending, though SMEs are gaining access through subscription-based service models.
Germany's Federal Ministry for Economic Affairs and Climate Action oversees Industry 4.0 standardization through DIN and VDI guidelines, while the EU AI Act imposes risk-classification requirements on autonomous decision-making within twin systems. KBA compliance mandates for automotive digital twins are tightening traceability standards across supplier networks. Stakeholders must monitor how BSI cybersecurity certifications evolve for cross-border data flows between German industrial assets and cloud-hosted simulation engines.
Market Dynamics
Germany's digital twin market is being restructured by the collision between Industry 4.0 standardization mandates and the EU AI Act's risk-classification requirements for autonomous simulation systems.
Growth Catalysts
- Industry 4.0 Framework:DIN and VDI guidelines mandate interoperable digital twin architectures across manufacturing supply chains, compelling Bavarian and Baden-Württemberg automotive clusters to accelerate platform deployment.
- Automotive Production Line Optimization:Precision engineering manufacturers in Stuttgart and Munich are deploying sensor-integrated twins for real-time quality control and predictive maintenance workflows.
- Cloud-Based Simulation Migration:Enterprise manufacturers are prioritizing SaaS delivery models over on-premise hardware, expanding access to computational fluid dynamics and finite element analysis tools.
Market Restraints
- Capital Intensity of Sensor Infrastructure:Retrofitting legacy production equipment with IoT sensor arrays requires substantial upfront investment, particularly for mid-tier suppliers in Saxony and Lower Saxony.
- Cross-Border Data Flow Friction:BSI cybersecurity certification requirements for cloud-hosted simulation engines create compliance complexity when German industrial assets interface with non-EU hosting providers.
- Interoperability Limitations:Proprietary data formats from dominant industrial software vendors inhibit seamless twin integration across heterogeneous supplier networks.
Strategic Opportunities
- Healthcare Organ Twin Deployment:German university hospitals in Berlin and Heidelberg are pioneering patient-specific cardiac and hepatic twins for pre-surgical planning, representing the fastest-expanding application segment.
- SME Subscription Access:Tiered SaaS pricing models are democratizing twin technology for precision tooling shops in North Rhine-Westphalia previously excluded from enterprise licensing schemes.
- EU Green Deal Alignment:Carbon footprint monitoring requirements under the EU Green Deal are driving demand for energy consumption twins in heavy manufacturing processes.
Industry Challenges
- Mechatronics Talent Scarcity:German technical universities produce insufficient graduates combining mechanical engineering, data science, and industrial IT competencies to meet platform deployment timelines.
- Legacy System Integration Complexity:Brownfield manufacturing facilities operate decades-old SCADA and MES architectures that resist API-based connectivity with modern twin platforms.
- KBA Traceability Certification:Automotive suppliers face extended approval cycles for digital twin documentation meeting the Federal Motor Transport Authority's tightening supplier network accountability standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Twin Market |
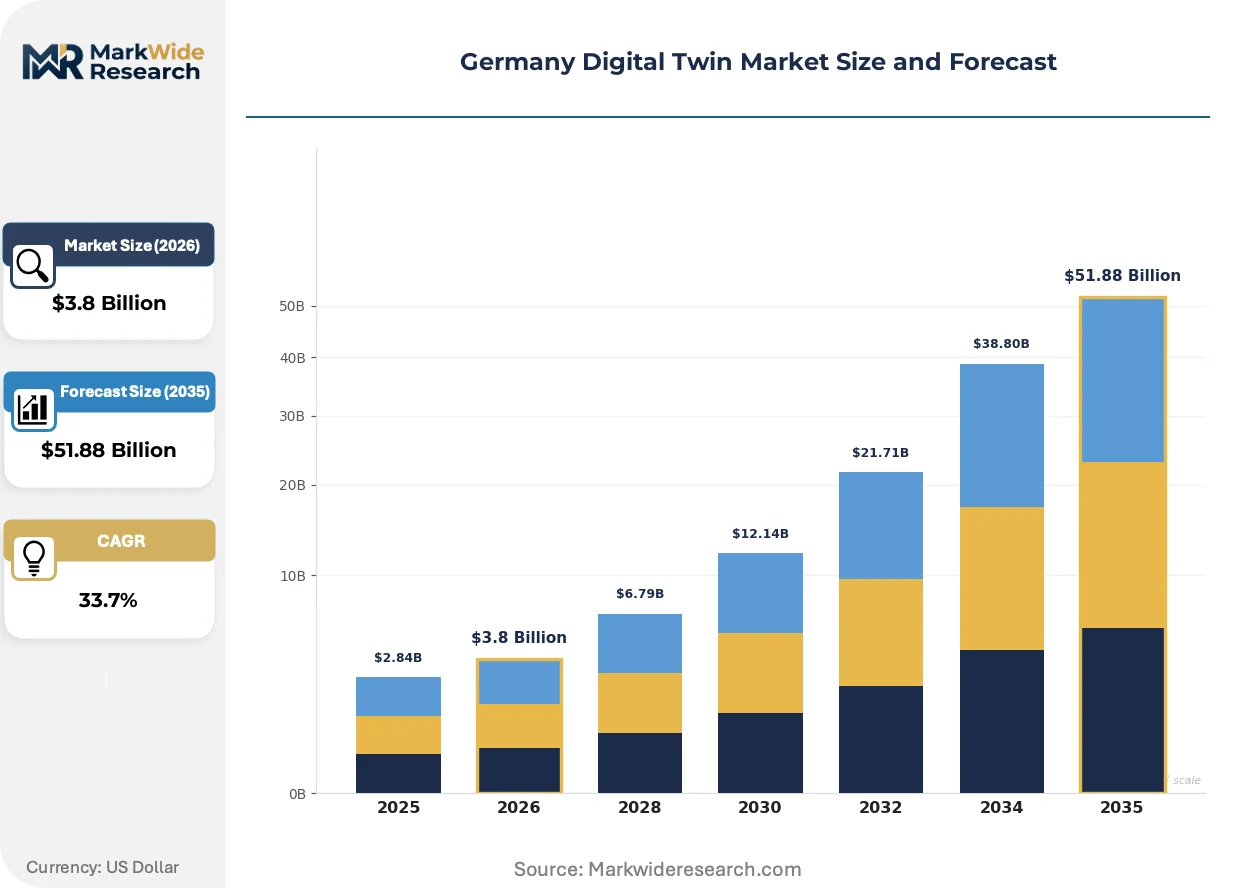
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 33.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Hardware, Services, Platforms Application: Manufacturing, Healthcare, Automotive, Smart Cities End User: Enterprises, Government, SMEs, Research Institutions Technology: IoT, AI, Machine Learning, Big Data |
| Companies Covered | ANSYS Inc., Bosch, Siemens AG, ABB Group, Schneider Electric, Dassault Systèmes, PTC Inc., Autodesk, SAP SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Twin Market Trends and Innovations
Computational architectures and compliance frameworks are actively restructuring how German industrial enterprises deploy virtual simulation environments. Three distinct vectors are compressing deployment cycles and redefining competitive positioning.
Edge computing is migrating from centralized cloud processing to distributed node architectures within factory floor environments. Automotive manufacturers in Wolfsburg and Ingolstadt are deploying GPU-enabled edge devices for millisecond-latency simulation feedback. This topology is migrating from batch-processing analytics to real-time closed-loop control systems that adjust cutting parameters and thermal treatments without human intervention.
The EU AI Act's risk-based classification system is imposing documentation and human-oversight requirements on autonomous decision-making within twin platforms. High-risk applications in medical device manufacturing and autonomous vehicle validation now require algorithmic transparency and bias auditing protocols. German industrial software vendors are responding by embedding explainable AI modules and audit trail logging into simulation engines before the Act's enforcement deadlines.
Hospital procurement departments are consolidating vendor relationships around integrated digital twin suites rather than point solutions for imaging, surgical planning, and post-operative monitoring. Academic medical centers in Hamburg and Cologne are negotiating enterprise licenses spanning radiology, cardiology, and oncology departments. This concentration is most visible in university hospital networks where procurement authority has centralized under chief digital officers with cross-departmental budget control.
Germany Digital Twin Market Segmentation
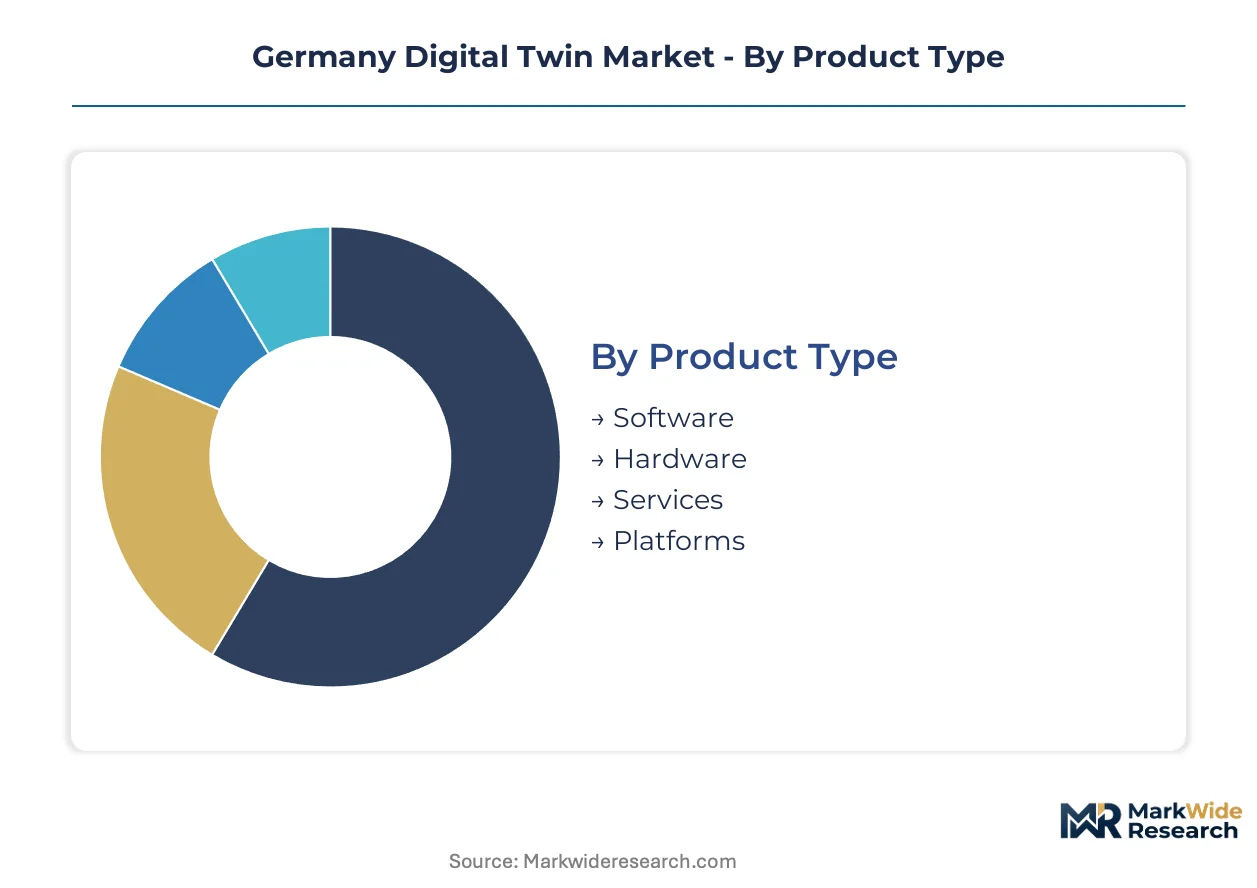
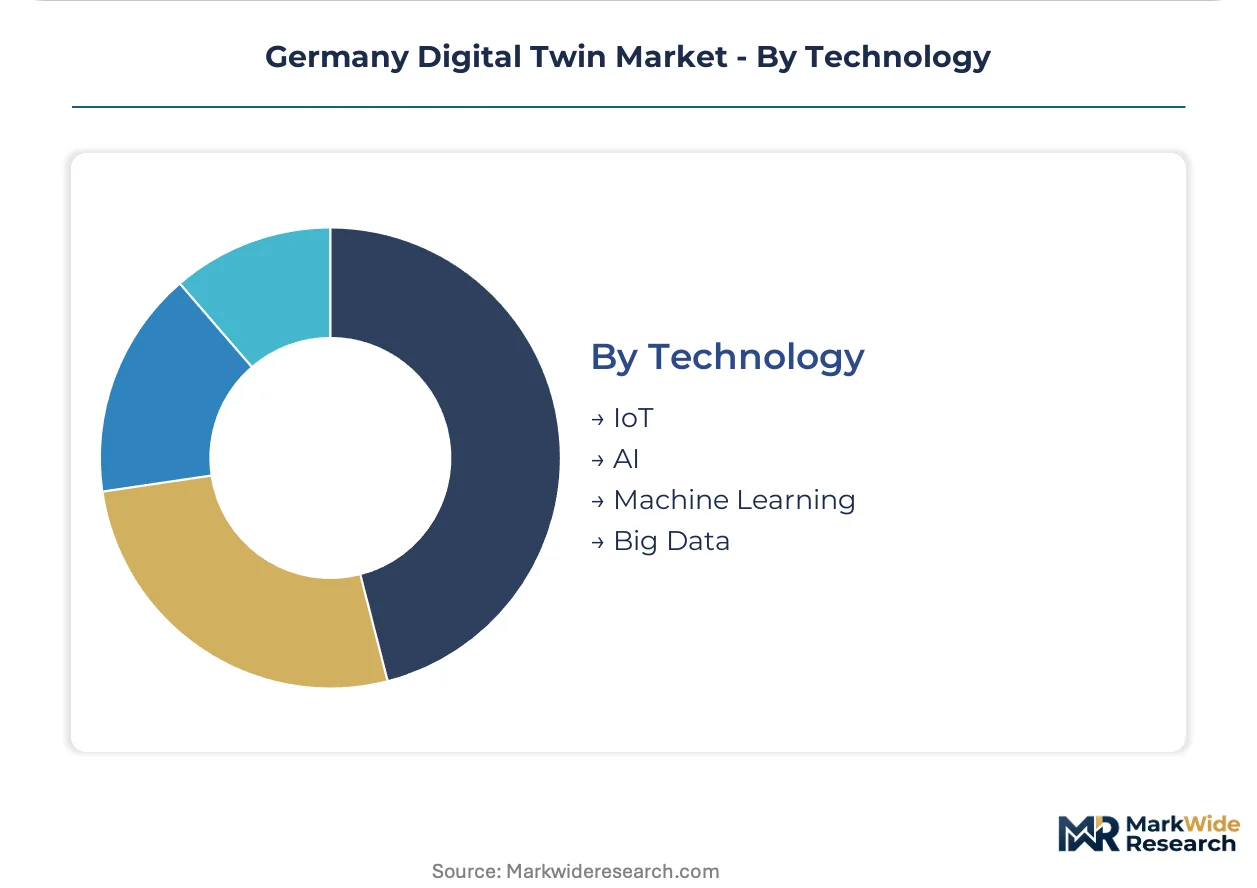
Germany's digital twin market fragments across four distinct dimensions that determine procurement patterns and deployment complexity. Product type and application segment splits reveal where platform investments concentrate versus where specialized solutions gain traction. End user and technology categories expose capability gaps between large manufacturers and mid-tier suppliers.
Product Type:
Cost tier differentiation separates capital-intensive on-premise deployments from subscription-accessible cloud alternatives.
- Software:Cloud-native simulation engines dominate enterprise budgets, with computational fluid dynamics and finite element analysis tools migrating to SaaS delivery. Bavarian automotive clusters in Munich and Ingolstadt prioritize these platforms for real-time production line optimization.
- Platforms:Integrated environments combining data ingestion, modeling, and visualization capabilities command premium licensing. Baden-Württemberg precision engineering manufacturers deploy these for supplier network coordination.
- Hardware:GPU-enabled edge devices and industrial sensor arrays form the physical layer.
- Services:Implementation consulting and managed twin operations support brownfield integration.
Software commands the established base. The steepest expansion runs through Platforms.
Application:
End-use concentration maps directly onto Germany's industrial geography and regulatory priorities.
- Manufacturing:Factory-floor twins integrate SCADA and MES architectures for predictive maintenance workflows. DIN and VDI standardization mandates under Industry 4.0 compel interoperable deployments across supplier networks in Saxony and Lower Saxony.
- Healthcare:Patient-specific organ twins for cardiac and hepatic surgical planning are expanding most quickly. University hospitals in Berlin and Heidelberg drive procurement, with EU AI Act risk-classification requirements shaping vendor selection.
- Automotive:KBA traceability mandates tighten documentation standards for supplier network accountability.
- Smart Cities:Urban infrastructure twins monitor energy distribution and traffic flows.
Manufacturing absorbs the majority of current spending. Healthcare claims the fastest-climbing trajectory.
End User:
Customer type determines platform complexity, with capability requirements scaling inversely with organizational size.
- Enterprises:Large manufacturers operate dedicated digital twin centers of excellence with cross-functional teams combining mechanical engineering, data science, and industrial IT competencies. Wolfsburg and Stuttgart automotive headquarters deploy these for global production coordination.
- SMEs:Tiered SaaS pricing democratizes access for North Rhine-Westphalia precision tooling shops previously excluded from enterprise licensing schemes.
- Government:Federal and state agencies fund standardization research and public infrastructure pilots.
- Research Institutions:Fraunhofer and Max Planck institutes advance foundational simulation algorithms.
Enterprises dominate platform revenue. SME adoption is gaining share fastest.
Technology:
Technical maturity separates proven connectivity layers from emerging autonomous capabilities.
- IoT:Sensor networks and edge connectivity form the data foundation. Retrofitting legacy equipment in brownfield facilities remains capital-intensive for mid-tier suppliers.
- AI:Autonomous decision-making within twin platforms triggers EU AI Act documentation and human-oversight requirements. German vendors embed explainable AI modules and audit trail logging to meet enforcement deadlines.
- Machine Learning:Predictive models refine simulation accuracy from operational data.
- Big Data:Distributed storage and processing architectures handle high-velocity industrial telemetry.
IoT anchors current deployments. AI capabilities are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters consume digital twin platforms differently than automotive-heavy Bavaria and precision-engineering Baden-Württemberg, where factory-floor simulation dominates, versus healthcare-focused Berlin and Hamburg prioritizing patient-specific organ modeling.
Bavaria
Munich and Ingolstadt automotive headquarters drive demand for real-time production line optimization and supplier network coordination. DIN standardization mandates under Industry 4.0 compel interoperable twin architectures across manufacturing supply chains. BMW and Audi operations deploy sensor-integrated twins for predictive maintenance and quality control workflows.
Baden-Württemberg
Stuttgart precision engineering manufacturers prioritize virtual prototyping and product lifecycle management integration. VDI guidelines enforce simulation platform compliance across heterogeneous supplier networks. Bosch maintains R&D intensity in IoT-enabled twin architectures for industrial predictive maintenance applications.
North Rhine-Westphalia
Tiered SaaS pricing models are democratizing twin access for mid-tier precision tooling shops previously excluded from enterprise licensing. The EU AI Act's risk-classification requirements shape vendor selection for autonomous manufacturing systems. Düsseldorf and Cologne industrial zones deploy energy consumption twins aligned with EU Green Deal carbon monitoring mandates.
Berlin-Brandenburg
University hospitals in Berlin pioneer patient-specific cardiac and hepatic twins for pre-surgical planning, representing the fastest-expanding application segment. EU AI Act documentation and human-oversight requirements apply to high-risk medical device simulation. Charité and Max Delbrück Center anchor healthcare twin procurement with cross-departmental enterprise licensing.
Lower Saxony
Capital intensity of IoT sensor retrofitting slows twin adoption among mid-tier suppliers in Wolfsburg-adjacent automotive networks. KBA traceability mandates tighten documentation standards for supplier network accountability. Volkswagen headquarters operations deploy global production coordination twins with dedicated centers of excellence.
Germany Digital Twin Market Competitive Landscape
Capability concentration sits with industrial software heritage players; scale advantage sits with diversified technology conglomerates. The vendor base organizes around three strategic archetypes: manufacturing-native platform builders, cloud-native simulation specialists, and diversified industrial conglomerates with captive twin capabilities. Competitive dynamics center on strategic partnerships for brownfield integration and portfolio diversification into healthcare and smart city verticals.
Within the manufacturing-native tier, Siemens AG and Bosch exemplify industrial heritage players leveraging deep factory-floor expertise. Dassault Systèmes occupies a position bridging product lifecycle management with virtual prototyping capabilities. These three anchors represent distinct competitive vectors: Siemens dominates German automotive cluster deployments, Bosch sustains R&D intensity in IoT-enabled architectures, and Dassault Systèmes anchors aerospace and precision engineering segments through PLM integration.
| Leading Market Players |
|---|
| ANSYS Inc. |
| Bosch |
| Siemens AG |
| ABB Group |
| Schneider Electric |
| Dassault Systèmes |
| PTC Inc. |
| Autodesk |
| SAP SE |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Alpine Corridor freight network carries industrial sensor arrays and GPU-enabled edge devices from Rotterdam through the Ruhr Valley to Bavarian automotive plants, with container rate volatility compressing margins for mid-tier platform vendors while amplifying price differentiation between cloud-native SaaS tiers and on-premise perpetual licenses.
Pricing Analysis
Price spreads between Munich-based enterprise deployments and North Rhine-Westphalia SME subscriptions reflect divergent service bundling intensity. Three-tier pricing structure across premium, standard, and economy levels separates dedicated implementation consulting from self-service portal access. Pricing pressure stems from hyperscaler cloud infrastructure commoditizing computational fluid dynamics engines. SMEs exhibit highest price sensitivity, while Wolfsburg automotive headquarters absorb premium licensing with minimal procurement friction.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts for industrial IoT sensor arrays, straining component vendors in Taiwan, South Korea, and Germany itself. GPU chipsets, fiber-optic temperature sensors, and edge computing nodes draw from concentrated semiconductor foundries. Single-source vulnerability in advanced GPU supply creates exposure for real-time simulation platforms. Distribution runs through authorized system integrators with DIN-certified implementation credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Charité and Max Delbrück Center procurement committees in Berlin-Brandenburg, with hospital network consolidation forcing vendors into enterprise-wide licensing negotiations rather than departmental point solutions.
For Market Incumbents:Pre-empt SaaS-native challengers by embedding EU AI Act compliance modules ahead of enforcement deadlines. Acquire edge computing hardware specialists to close brownfield integration capability gaps. Lock in Bavarian automotive clusters through multi-year managed twin operations contracts with KBA documentation guarantees.
For New Entrants and Emerging Players:Lower Saxony mid-tier automotive suppliers present underpenetrated demand for subscription-based predictive maintenance twins without upfront sensor capital expenditure. Target precision tooling shops in Saxony with API-first platforms bypassing legacy SCADA replacement. Partner with Fraunhofer institutes for co-branded implementation credibility.
For Investors and Strategic Acquirers:Carve-out targets emerge from diversified industrial conglomerates with captive digital twin divisions lacking standalone scale. Five-to-ten year viability hinges on healthcare segment diversification beyond manufacturing cyclicality. Watch for EU AI Act high-risk classification enforcement as inflection trigger for compliance-focused vendor consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Siemens AG and Bosch embed EU AI Act audit trails to preempt regulatory displacement. |
| Acquisition of Specialist Firm | Edge computing hardware targets close latency gaps for Wolfsburg real-time control systems. |
| Strategic Partnership | Fraunhofer alliances validate implementation credentials for North Rhine-Westphalia SME penetration. |
| Product Launch | Patient-specific organ twin suites capture Charité procurement consolidation momentum. |
| Geographic Expansion | Baden-Württemberg precision engineering clusters extend VDI-compliant supplier network coordination. |
Research Methodology
A spread of perspectives from automotive platform engineers, hospital chief digital officers, Fraunhofer research directors, and industrial IoT procurement managers converged on the working assumptions for this analysis. Primary fieldwork combined with secondary validation against DIN standardization documents, KBA regulatory filings, EU AI Act implementation guidance, and hyperscaler cloud infrastructure disclosures. Bottom-up deployment counts across Bavarian and Baden-Württemberg manufacturing facilities triangulated against top-down platform revenue estimates.
Demand-supply balance modeling calibrated adoption curves against sensor infrastructure installation capacity and mechatronics graduate pipeline constraints. Segmentation dimensions spanned product type, application vertical, end-user scale, and technology maturity across the projection horizon. CAGRs derived from logistic diffusion curves fitted to historical Industry 4.0 technology adoption patterns. Forecast inputs incorporated DIN guideline revision schedules and EU AI Act enforcement timeline uncertainty.
Practitioners should monitor KBA traceability mandate tightening and BSI cybersecurity certification evolution for early signals of vendor compliance burden shifts. Forecasts embed assumptions regarding cloud migration velocity and healthcare procurement centralization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
In-App Purchase Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Digital User Experience Solutions Market
Digital Solutions
North America Managed Mobility Service Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Supply Side Platform (SSP) Market
Digital Solutions
Contactless Ticketing Ics Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
Next Generation OSS and BSS Market
Digital Solutions
Digital Marketing Software Market
Digital Solutions
UK High Performance Computing Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
Global Cloud OSS BSS Market
Digital Solutions
Cloud E-Signature Tools Market