
 Global Thermochromic Materials Market | 2026-2036
Global Thermochromic Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermochromic Materials Market Outlook
Microencapsulation of leuco dye systems is rewriting how thermochromic functionality embeds into thin-film substrates without compromising durability. Chromatic Technologies Inc. leverages proprietary encapsulation patents to anchor North American supply for beverage labeling and pharmaceutical cold-chain indicators. LCR Hallcrest sustains decades of liquid crystal expertise to dominate temperature-mapping applications in industrial process control. OliKrom specializes in reversible pigment systems that compete on response-speed specifications for aerospace and defense coatings.
Thermochromic materials reversibly change optical properties when heated or cooled, typically operating within a narrow temperature bandwidth of minus fifteen to plus sixty-five degrees Celsius through molecular rearrangement of liquid crystals, spirolactone dyes, or polymer-bound chromic compounds. Their primary commercial purpose spans overt and covert authentication, thermal warning indicators, and aesthetic surface effects across consumer and industrial goods. Liquid crystal formulations occupy the premium tier where precision temperature indication commands higher margins, while polymer-based systems represent the fastest-growing category as injection-moldable masterbatches penetrate automotive interior trim and consumer electronics housings. Pigment powders in powder and granule forms retain mature demand from textiles and printing inks, though margin pools are shifting toward paste formulations for direct coating deposition.
EPA oversees volatile organic compound limits that constrain solvent-based thermochromic ink formulations in the United States, while REACH registration requirements in Europe impose toxicity documentation burdens on imported dye intermediates. Japan's METI enforces chemical substance reporting under CSCL that affects cross-border pigment shipments. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as fluorinated encapsulants face phasedown pressure that could force reformulation of microencapsulated dye systems across multiple jurisdictions.
Market Dynamics
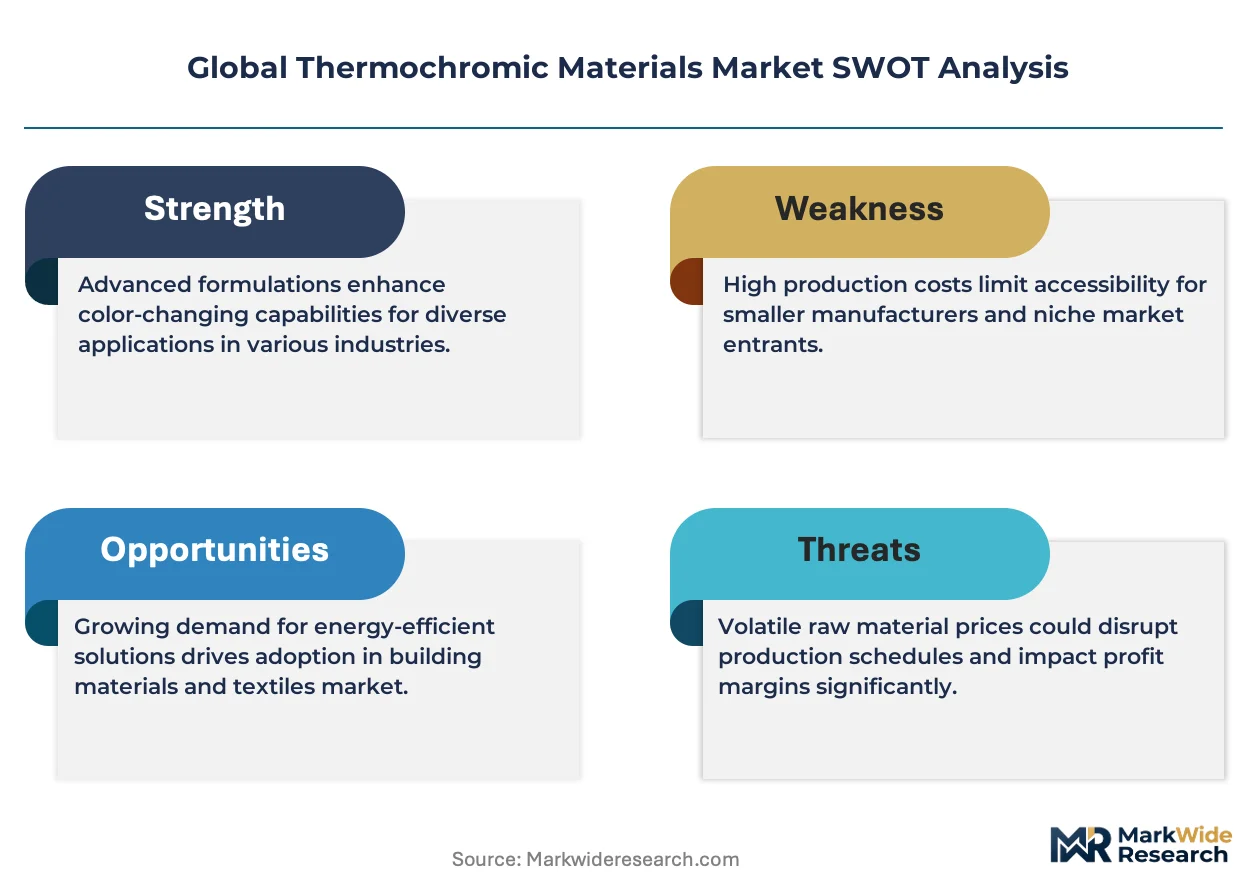
REACH registration requirements and EU Green Deal chemical disclosure mandates are forcing reformulation of microencapsulated dye systems, compressing margins for imported intermediates while creating first-mover advantage for domestic European compounders with established toxicity documentation.
Growth Catalysts
- Smart packaging integration:Food and pharmaceutical cold-chain indicators now embed reversible thermochromic films directly into primary packaging substrates, eliminating separate temperature logger hardware.
- REACH compliance as competitive moat:European compounders with pre-registered dye intermediates capture share from Asian exporters facing documentation backlogs at ECHA.
- Automotive interior trim specification:German and Japanese OEMs mandate temperature-responsive surface finishes for premium electric vehicle cabins, pulling injection-moldable masterbatch volumes.
Market Restraints
- Fluorinated encapsulant phase-down:Per- and polyfluoroalkyl substance restrictions across multiple jurisdictions threaten durability of existing microencapsulated leuco dye systems.
- Liquid crystal feedstock concentration:Cholesteric ester precursors for precision temperature-mapping applications source primarily from Japanese specialty chemical houses, creating single-geography supply risk.
- Organic photonic substitute emergence:Electrochromic and mechanochromic alternatives in aerospace authentication applications compete on reversibility cycle counts.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO cold-chain compliance requirements for temperature-sensitive biologics create untapped demand for reversible indicator integration.
- EU F-Gas Regulation alignment:Refrigeration equipment manufacturers seeking climate-friendly coolant systems value thermochromic leak-detection coatings as maintenance-free alternatives to electronic sensors.
- Textile-to-electronics convergence:Wearable device manufacturers combine thermochromic fibers with flexible printed circuit substrates for skin-temperature-responsive user interfaces.
Industry Challenges
- Microencapsulation process engineering talent:Thin-film coating specialists with simultaneous expertise in polymer science and continuous-flow manufacturing command premium compensation in Germany and Japan.
- Cross-jurisdiction substance notification:METI chemical substance reporting under Japan's CSCL runs on incompatible timelines with REACH dossier updates, forcing dual-track regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermochromic Materials Market |
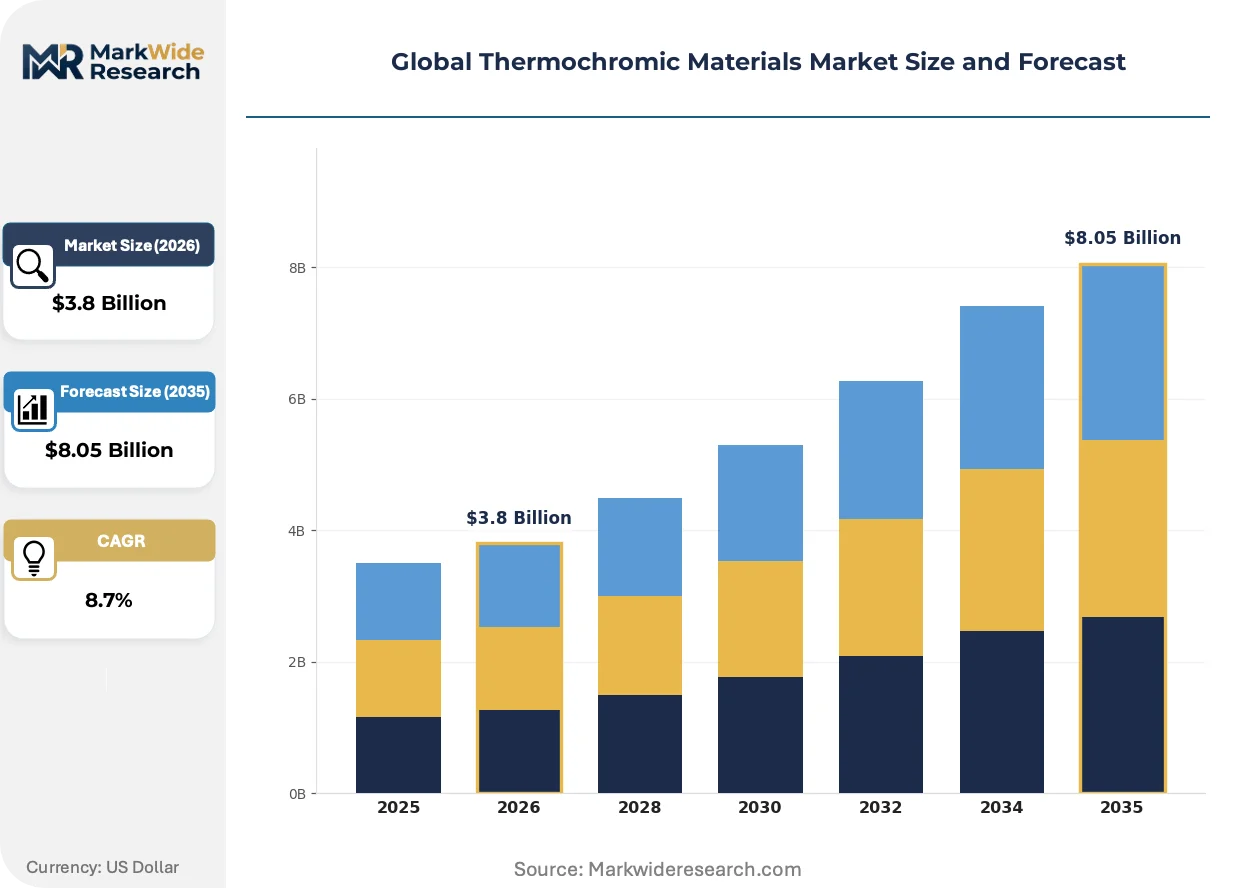
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Crystals, Polymers, Dyes, Pigments Application: Textiles, Coatings, Inks, Cosmetics End User: Automotive, Consumer Electronics, Packaging, Healthcare Form: Powder, Granule, Liquid, Paste |
| Companies Covered | Chromatic Technologies Inc. (CTI), LCR Hallcrest, OliKrom, Matsui International Company, New Prismatic Enterprise, Smarol Industry, GEMINNOV, Hali Industrial, RPM International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermochromic Materials Market Strategic Shifts
Digital simulation of color-transition kinetics is compressing R&D cycles for new thermochromic formulations, while sustainability pressures accelerate waterborne coating development and bio-based chromophore exploration.
Spirolactone dye-polymer conjugate systems is virtualizing traditional powder-blending approaches by enabling direct solution-processing into thin films without solvent-based ink intermediates. Automotive Tier-1 suppliers in Stuttgart and Nagoya adopt these conjugates for in-mold decoration of climate-control bezels and charging port surrounds. The technology is virtualizing established supply relationships between pigment houses and ink formulators by allowing OEMs to source functionalized polymers directly.
ECHA's tightening restrictions on microplastic release from coatings capture thermochromic masterbatches in scope, requiring reformulation of polymer-bound systems for textile and packaging applications. Industrial laundries and municipal wastewater utilities in the Netherlands and Denmark drive enforcement through purchasing specifications. Textile finishers serving Scandinavian outdoor apparel brands respond fastest, shifting toward covalently-bound chromophore systems that resist mechanical shedding.
Brand-owner sustainability scorecards now weight chemical transparency above unit cost in thermochromic procurement decisions. Beverage and pharmaceutical packaging buyers in Germany and California disfavor suppliers without full REACH-SVHC and California Proposition 65 disclosure. This preference compresses spot-market volumes for undocumented Asian pigment powders while expanding contract relationships with vertically integrated European compounders.
Global Thermochromic Materials Market Segmentation
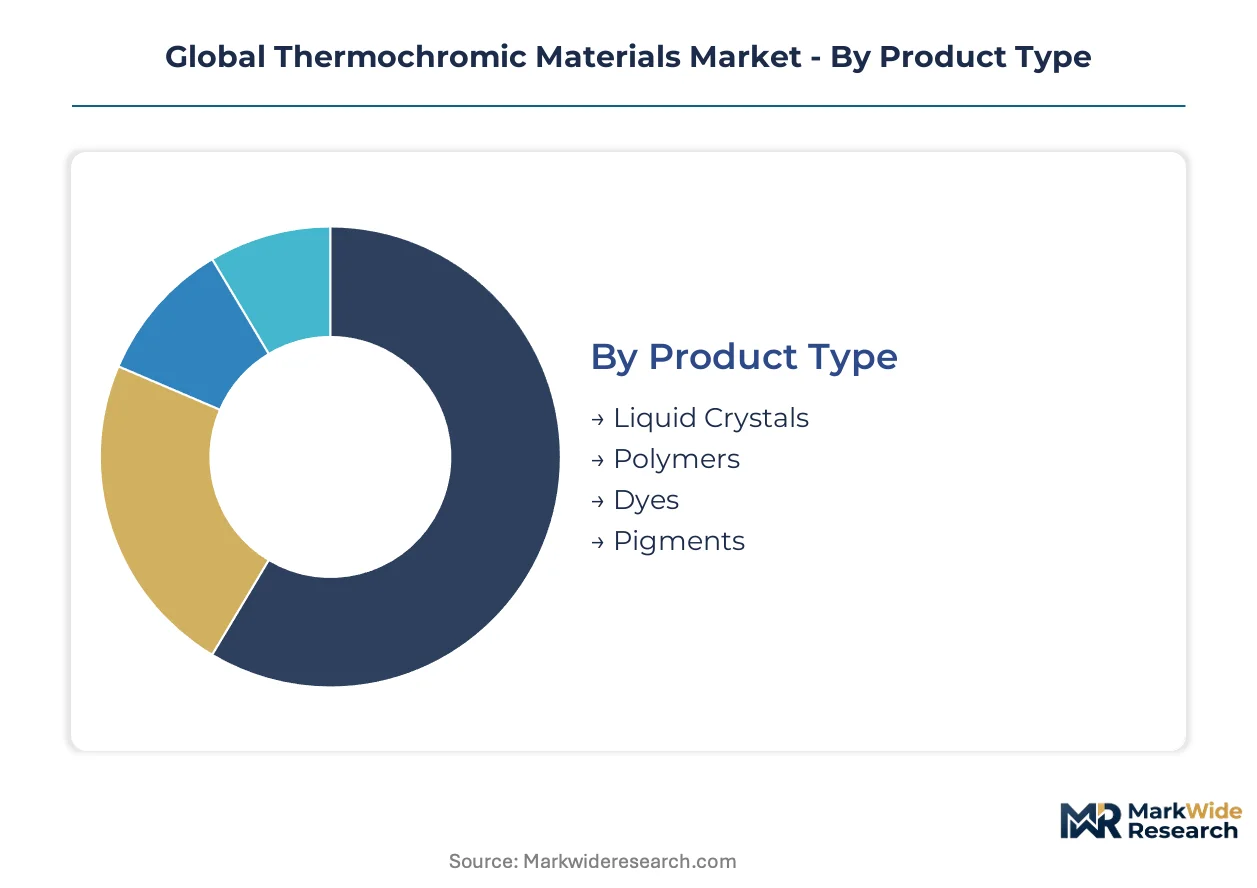
Thermochromic materials fragment across four intersecting dimensions that determine formulation complexity and commercial velocity. Product chemistry governs performance specifications while form factor dictates manufacturing integration paths.
Product Type:
Reversible thermochromic systems exhibit starkly different development cycles—liquid crystal formulations demand multi-year R&D for precision calibration, while polymer-bound systems compress time-to-market through masterbatch standardization.
- Liquid Crystals:Cholesteric ester-based formulations deliver narrow-band temperature indication with sub-degree accuracy for medical and industrial process control. German automotive OEMs and Japanese electronics manufacturers specify these for premium cabin interfaces and battery thermal mapping where precision commands price premiums.
- Polymers:Injection-moldable thermoplastic concentrates enable direct integration into automotive interior trim and consumer electronics housings without secondary coating operations. Stuttgart and Nagoya-based Tier-1 suppliers drive specification pull for climate-control bezels and charging port surrounds in electric vehicle programs.
- Dyes:Leuco dye systems encapsulated in melamine-formaldehyde shells provide irreversible or reversible color change for cold-chain indicators and authentication labels.
- Pigments:Powder and granule forms serve mature textile printing and decorative coating applications with established supply chains.
Pigments anchor the volume base while polymers gain share at the steepest rate.
Application:
Cost stratification separates commodity surface decoration from functional thermal indication where failure carries liability exposure.
- Textiles:Fiber-integration and finishing processes embed thermochromic functionality into athletic apparel and outdoor gear for aesthetic and thermoregulatory signaling. Scandinavian outdoor brands and Netherlands-based industrial laundries enforce ECHA microplastic restrictions that favor covalently-bound chromophore systems over mechanical coatings.
- Coatings:Direct deposition onto metal, plastic, and glass substrates serves automotive trim, appliance panels, and architectural surfaces. Waterborne formulations displace solvent-based systems under EPA VOC limits and EU Green Deal mandates.
- Inks:Screen and inkjet-compatible formulations enable variable-data printing of temperature indicators on flexible packaging.
- Cosmetics:Color-changing lip and eye products leverage thermochromic response to skin temperature for novelty positioning.
Coatings capture the premium margin tier while textiles expand most quickly under sustainability-driven material substitution.
End User:
Customer procurement sophistication varies sharply—automotive and healthcare buyers impose qualification protocols that exclude spot-market suppliers, while packaging purchasers weight chemical transparency above unit cost.
- Automotive:German and Japanese OEMs mandate temperature-responsive surface finishes for premium electric vehicle cabins, with specification control residing in Stuttgart and Nagoya engineering centers. REACH-registered compounders with full toxicity documentation capture contract volumes from undocumented Asian competitors.
- Consumer Electronics:Wearable device manufacturers combine thermochromic fibers with flexible printed circuit substrates for skin-temperature-responsive user interfaces.
- Packaging:Food and pharmaceutical cold-chain indicators embed reversible thermochromic films directly into primary substrates, eliminating separate temperature logger hardware under FDA and EMA distribution requirements.
- Healthcare:Clinical temperature monitoring and patient compliance applications demand biocompatible formulations with documented safety profiles.
Packaging supplies the broadest addressable base while automotive concentrates value through specification control.
Form:
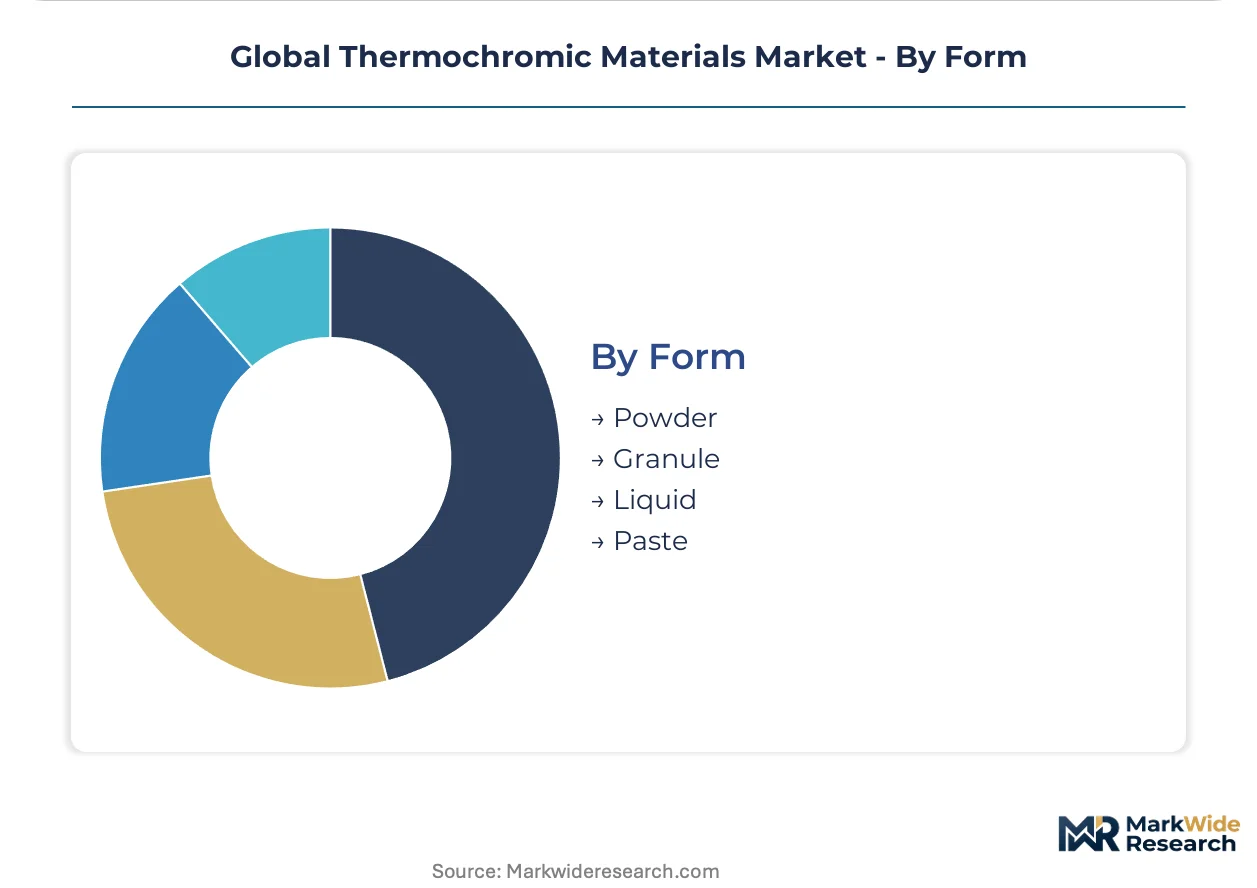
Physical state determines supply chain touchpoints—powder and granule forms flow through pigment houses and distributors, while pastes and liquids enable direct OEM relationships that bypass traditional ink formulators.
- Powder:Dry pigment concentrates serve textile printing and powder coating operations with established logistics infrastructure.
- Granule:Compounded thermoplastic masterbatches feed injection molding and extrusion equipment for automotive and electronics housings.
- Liquid:Solution-processable dye-polymer conjugates enable thin-film deposition without solvent-based intermediates, allowing direct OEM sourcing from polymer houses.
- Paste:High-solids formulations for screen printing and direct coating applications bridge pigment supply and finished goods manufacturing.
Powder and granule forms dominate current shipment volumes while liquid formulations climb fastest as spirolactone conjugates displace traditional ink supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Japanese electronics manufacturers concentrate premium-tier procurement, while packaging buyers in the United States and India drive volume expansion through cold-chain compliance mandates.
Germany
Stuttgart-based Tier-1 suppliers specify injection-moldable thermochromic masterbatches for electric vehicle cabin trim. REACH registration requirements at ECHA compounders with pre-registered dye intermediates capture share from Asian exporters facing documentation backlogs. Bavarian automotive engineering clusters mandate temperature-responsive surface finishes for premium EV programs.
Japan
Nagoya-based automotive suppliers integrate thermochromic polymers into climate-control bezels and charging port surrounds. METI enforces chemical substance reporting under CSCL that affects cross-border pigment shipments. Cholesteric ester precursors for liquid crystal formulations concentrate in Japanese specialty chemical houses, creating precision-temperature mapping supply advantages.
United States
California beverage and pharmaceutical packaging buyers weight chemical transparency above unit cost in procurement decisions. EPA volatile organic compound limits constrain solvent-based thermochromic ink formulations nationwide. Midwest industrial process control manufacturers source liquid crystal temperature-mapping systems for precision manufacturing applications.
India
CDSCO cold-chain compliance requirements for temperature-sensitive biologics create demand for reversible indicator integration in pharmaceutical export packaging. Domestic textile finishers serving European outdoor apparel brands respond to ECHA microplastic restrictions with covalently-bound chromophore systems. Gujarat-based pharmaceutical packaging clusters embed thermochromic films directly into primary substrates.
Netherlands
Industrial laundries and municipal wastewater utilities drive enforcement of ECHA microplastic release restrictions through purchasing specifications. Rotterdam-based packaging converters serve Scandinavian outdoor apparel brands with reformulated polymer-bound systems. Dutch textile finishers lead European adoption of covalently-bound chromophore systems that resist mechanical shedding.
Global Thermochromic Materials Market Competitive Environment
Channel-controlling players compete with product-specialist players across formulation complexity tiers. The vendor base organizes around microencapsulation expertise, liquid crystal precision calibration, and polymer masterbatch standardization. Three archetypes dominate: encapsulation patent holders, cholesteric ester specialists, and injection-moldable concentrate compounders. Competitive moves concentrate on REACH registration completion, fluorinated encapsulant reformulation, and direct OEM relationships that bypass traditional ink formulators.
Within the encapsulation-specialist tier, Chromatic Technologies Inc. and LCR Hallcrest occupy positions anchored by proprietary process knowledge. French specialist OliKrom exemplifies the reversible pigment systems archetype competing on response-speed specifications. These three entities represent distinct competitive vectors—North American beverage labeling supply, decades-long liquid crystal expertise, and aerospace-defense coating applications—illustrating how geographic clustering around regulatory compliance and end-use concentration shapes strategic positioning.
| Leading Market Players |
|---|
| Chromatic Technologies Inc. (CTI) |
| LCR Hallcrest |
| OliKrom |
| Matsui International Company |
| New Prismatic Enterprise |
| Smarol Industry |
| GEMINNOV |
| Hali Industrial |
| RPM International Inc. |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's automotive engineering cluster anchors European thermoplastic masterbatch capacity, concentrating formulation expertise that translates into pricing power over downstream Tier-1 suppliers. REACH-registered compounders with pre-registered dye intermediates command premium positioning against Asian exporters facing ECHA documentation backlogs, compressing spot-market volumes for undocumented pigment powders.
Pricing Analysis
Cost-plus contracts with cholesteric ester precursor indexation dominate liquid crystal procurement, insulating Japanese specialty chemical houses from raw material volatility. Three-tier pricing structure across precision-calibrated, standard-grade, and commodity pigment tiers separates automotive OEM specifications from textile printing applications. Pricing pressure stems from fluorinated encapsulant phase-down mandates forcing reformulation investment. Packaging buyers in Germany and California exhibit highest price sensitivity as chemical transparency scorecards disfavor undocumented suppliers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Nagoya-based automotive suppliers sustain working capital for Japanese masterbatch compounders. Manufacturing concentrates in Germany, Japan, and the United States, with cholesteric ester precursors drawing from Japanese specialty chemical houses and leuco dye systems resting on North American encapsulation patents. Single-geography feedstock concentration for precision liquid crystals creates structural vulnerability. Distribution runs through pigment houses and distributors for powder forms, while liquid formulations enable direct OEM relationships bypassing traditional ink formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where REACH registration requirements create regulatory entrenchment that locks out undocumented competitors and sustains incumbent pricing power.
For Market Incumbents: Build regulatory documentation moats by accelerating REACH-SVHC dossier completion ahead of ECHA disclosure tightening. Secure backward integration into cholesteric ester precursor supply through long-term offtake agreements with Japanese specialty chemical houses, mitigating single-source vulnerability that threatens precision temperature-mapping applications. For New Entrants and Emerging Players: Pursue Indian pharmaceutical export packaging as the most penetrable white-space target, where CDSCO cold-chain compliance requirements for temperature-sensitive biologics outpace domestic supplier capacity. Target covalently-bound chromophore systems for Scandinavian outdoor apparel brands responding to ECHA microplastic restrictions, leveraging sustainability-driven material substitution as entry wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among encapsulation patent holders serving beverage and pharmaceutical cold-chain indicator contracts. Long-term viability over the projection horizon favors vertically integrated compounders with simultaneous microencapsulation expertise and REACH registration completion. Monitor fluorinated encapsulant reformulation success as inflection indicator for durability-competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Completion | ECHA pre-registration creates competitive moat against Asian exporters facing documentation backlogs. |
| Fluorinated Encapsulant Reformulation | Per- and polyfluoroalkyl substance phase-down compliance sustains microencapsulated dye system durability. |
| Direct OEM Relationship Development | Liquid formulation supply bypasses traditional ink formulators, capturing margin from spirolactone conjugate adoption. |
| Cholesteric Ester Supply Security | Long-term offtake agreements with Japanese specialty chemical houses mitigate precision liquid crystal feedstock risk. |
| Covalently-Bound Chromophore Transition | ECHA microplastic restrictions in Netherlands and Denmark drive textile finisher purchasing specification shifts. |
Study Parameters
A spread of perspectives from thermochromic formulation chemists, automotive Tier-1 procurement directors, pharmaceutical packaging compliance officers, and textile finishing plant managers converged on the working assumptions. Primary interview insights combined with secondary validation from ECHA registration databases, EPA VOC compliance filings, METI chemical substance reporting records, and customs trade data. Bottom-up segment sizing and top-down market triangulation cross-checked volume estimates across the analysis window.
Demand-supply balance dynamics anchored the forecast framework, with segmentation across liquid crystal, polymer, dye, and pigment chemistries intersecting with automotive, packaging, textile, and electronics end-uses. Modeled dimensions included reversible versus irreversible transition behavior, form factor integration paths, and regional regulatory cluster adoption patterns. CAGRs derived from installed base growth, content-per-unit expansion, and replacement cycle analysis. Forecast inputs incorporated electric vehicle cabin specification trajectories and pharmaceutical cold-chain compliance mandate expansion.
Sensitivities concentrate around fluorinated encapsulant regulatory phase-down timelines, cholesteric ester precursor supply disruption, and organic photonic substitute reversibility cycle improvements. Forecasts reflect documented assumptions on REACH registration completion rates and OEM specification adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dyes and Pigments
Plastic Color Concentrates Market
Dyes and Pigments
Inorganic Color Pigments Market
Dyes and Pigments
Acid Dyes Market
Dyes and Pigments
Chemochromic Material Market
Dyes and Pigments
Plastic Pigments Market
Dyes and Pigments
Riboflavin Pigment Market
Dyes and Pigments
Phycoerythrin Market
Dyes and Pigments
Phthalocyanine Blue Market
Dyes and Pigments
High Performance Pigments Market
Dyes and Pigments
Cadmium Pigments Market
Dyes and Pigments
France Aluminium Pigments Market
Dyes and Pigments
Polymer Colorant Market
Dyes and Pigments
Carmoisine Market
Dyes and Pigments
Reactive Dyes Market
Dyes and Pigments
Lithol Rubine BK Market
Dyes and Pigments
Aluminum Pigments Market