
 Global Email Management Software Market | 2026-2036
Global Email Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Email Management Software Market Foresight
Mid-market enterprises is rotating toward integrated email platforms that bundle security, archiving, and analytics. Microsoft Corporation leverages its Office 365 ecosystem to anchor enterprise deployments across North America and Europe. Google LLC competes through Gmail Workspace integrations that emphasize collaboration and AI-assisted drafting. Zoho Corporation Pvt. Ltd. specializes in cost-optimized suites tailored to price-sensitive buyers in emerging economies.
Email management software encompasses systems that route, secure, archive, and analyze electronic mail across organizational networks, typically integrating SMTP/IMAP protocols with encryption standards such as TLS 1.3 and API-based automation hooks. These platforms serve commercial and industrial users by ensuring message deliverability, regulatory retention, and threat filtering at enterprise scale. Cloud-Based deployment leads volume growth as IT departments abandon on-premises server maintenance, while Email Archiving and Data Loss Prevention solution types capture concentrated margin pools from regulated industries. Compliance Management applications expand fastest in Banking & Finance and Legal Services as audit-ready retention becomes non-negotiable.
The EU AI Act, GDPR, and ISO 27001 standards collectively mandate audit trails, automated data classification, and cross-border transfer safeguards that elevate software procurement criteria. The US Securities and Exchange Commission and HIPAA impose parallel retention and access-control obligations on financial and healthcare entities. Stakeholders must monitor how converging AI governance and data-localization rules reshape vendor certification requirements and deployment architectures.
Market Dynamics
Cloud migration pressure from mid-market enterprises is compressing deployment timelines and forcing vendors to bundle security, archiving, and analytics into unified platforms rather than standalone modules.
Growth Catalysts
- EU AI Act compliance mandates:Automated data classification and audit trail requirements are pulling regulated industries toward certified email management platforms with built-in governance tooling.
- Banking & Finance retention rules:SEC and HIPAA parallel obligations are making non-negotiable audit-ready archiving solutions a baseline procurement criterion across financial and healthcare entities.
- India's legacy infrastructure modernization:Organizations in Mumbai, Bangalore, and Delhi are abandoning on-premises Exchange servers for cloud-native alternatives with API-based automation hooks.
Market Restraints
- TLS 1.3 encryption implementation costs:Small and mid-sized enterprises face elevated capex for certificate management and protocol migration across distributed email gateways.
- GDPR cross-border transfer complexity:Data localization requirements in Germany, France, and Ireland are fragmenting vendor deployment architectures and lengthening sales cycles.
- On-premises server stranded assets:IT departments with sunk costs in legacy hardware resist full cloud migration, creating hybrid environment management friction.
Strategic Opportunities
- AI-assisted drafting convergence:Natural language processing integration with SMTP routing protocols is opening premium pricing tiers for productivity-focused enterprise segments.
- Legal Services compliance automation:ISO 27001-aligned retention policies are creating dedicated solution categories for law firms managing client confidentiality and discovery readiness.
- Direct API marketplace distribution:Vendor bypass of traditional systems integrators through self-service developer portals is capturing price-sensitive buyers in emerging economies.
Industry Challenges
- IMAP-to-cloud protocol integration complexity:Engineering teams struggle to maintain message threading integrity during heterogeneous environment migrations.
- Multi-jurisdiction certification timelines:Simultaneous GDPR, HIPAA, and SEC compliance validation extends product release cycles by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Email Management Software Market |
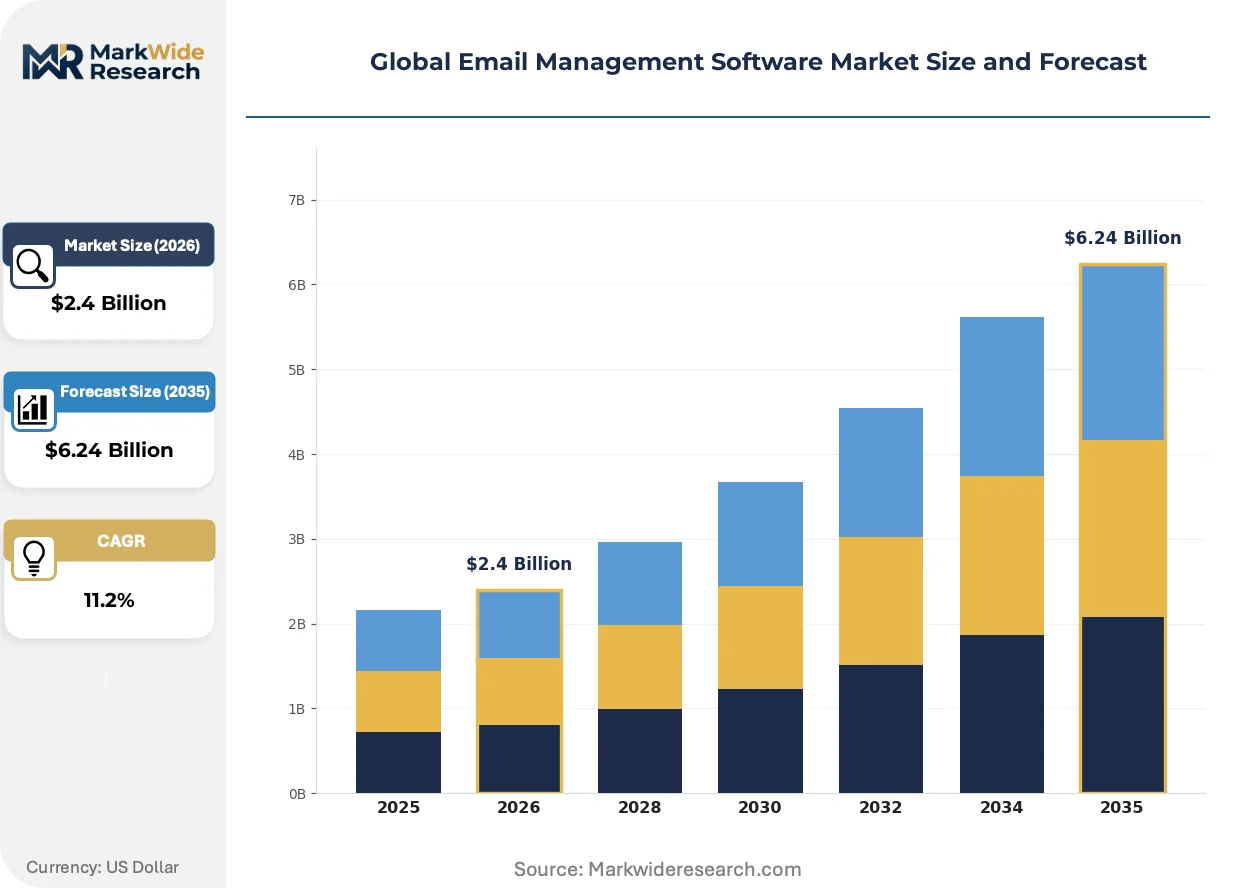
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Managed Services Solution Type: Spam Filtering, Email Archiving, Encryption, Data Loss Prevention, Email Analytics Application: Customer Support, Marketing Automation, Internal Communication, Compliance Management, Sales Enablement End User Industry: IT & Telecom, Banking & Finance, Education, Government Agencies, Legal Services |
| Companies Covered | Google LLC, Microsoft Corporation, IBM Corporation, Cisco Systems Inc., Oracle Corporation, Salesforce.com Inc., Zoho Corporation Pvt. Ltd., HubSpot Inc., Proofpoint Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Email Management Software Market Shifts & Advancements
Generative AI integration is rewriting feature roadmaps across vendor portfolios, with automated content generation and threat detection now table stakes rather than premium add-ons.
Machine learning-powered anomaly detection is bifurcating the threat filtering market. Mid-market enterprises in the United States and Germany are adopting these engines at accelerated pace. This capability is compressing margins for signature-based security vendors while elevating platform stickiness for integrated suite providers.
The EU AI Act's risk-based classification system is mandating algorithmic transparency in automated email sorting and response generation. Vendors must now document training data provenance and decision logic for high-risk deployments. Banking & Finance entities in Frankfurt and Paris are demanding pre-certified compliance modules before procurement approval.
Subscription unbundling is fragmenting buyer commitment patterns. Enterprise procurement teams in India and the United States are decomposing monolithic suites into component services sourced from multiple vendors. This pattern is most visible in technology and professional services verticals where IT departments prioritize best-of-breed API interoperability over single-vendor consolidation.
Global Email Management Software Market Segmentation
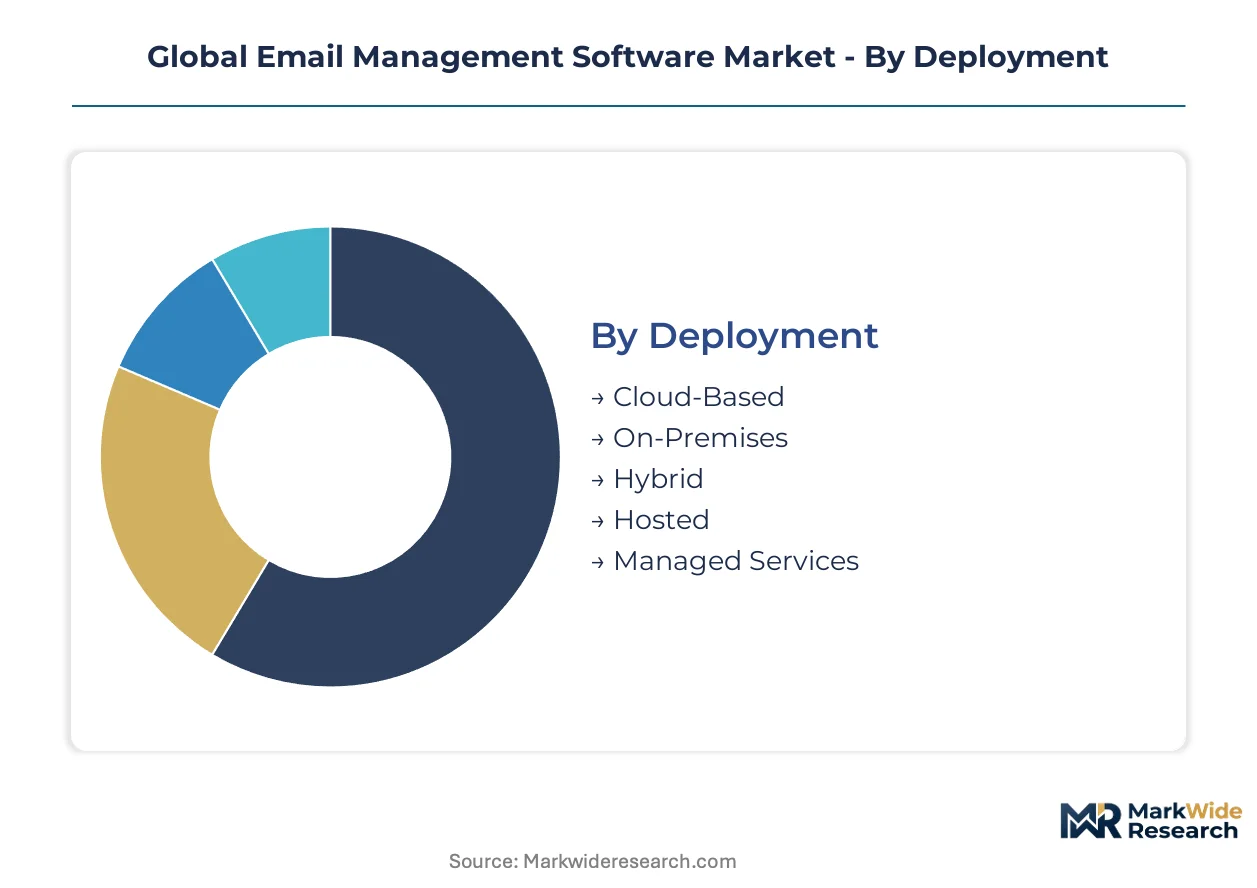
Email management software procurement patterns diverge sharply across deployment models, solution architectures, and regulatory exposure levels. Understanding these fault lines reveals where vendors capture premium pricing versus where commoditization pressures dominate contract negotiations.
Deployment:
Margin pools concentrate in hybrid and managed services arrangements where complexity premiums offset cloud infrastructure commoditization.
- Cloud-Based:Multi-tenant architectures with TLS 1.3 encryption and API automation hooks serve mid-market enterprises abandoning server maintenance. Demand concentrates in Mumbai, Bangalore, and Delhi as Indian organizations modernize legacy Exchange infrastructure under compressed timelines.
- On-Premises:Dedicated hardware deployments with full data sovereignty remain sticky in German banking and French government sectors where GDPR localization mandates override cloud economics. Sunk costs in existing infrastructure create migration friction that vendors exploit through hybrid transition services.
- Hybrid:Split architectures routing sensitive traffic on-premises while leveraging cloud analytics for non-critical workflows.
- Hosted:Single-tenant managed infrastructure for regulated entities requiring dedicated environments without capital ownership.
- Managed Services:Fully outsourced email operations including security monitoring, archiving, and compliance reporting.
Cloud-Based holds installed capacity. Hybrid is rotating up the share rankings.
Solution Type:
Application depth determines pricing power, with archiving and data loss prevention commanding sustained premiums against commoditized spam filtering.
- Email Archiving:Immutable retention systems with WORM storage and e-discovery indexing satisfy SEC, HIPAA, and EU AI Act audit trail mandates. Banking & Finance entities in Frankfurt and Paris require pre-certified compliance modules before procurement approval.
- Data Loss Prevention:Content inspection engines with automated classification and policy enforcement protect against exfiltration. Legal Services firms in London and New York deploy these solutions for client confidentiality and discovery readiness.
- Spam Filtering:Signature and heuristic-based threat detection facing margin compression from integrated suite competition.
- Encryption:End-to-end and gateway-level cryptographic protection for regulated data categories.
- Email Analytics:Sentiment analysis and communication pattern extraction for workforce optimization.
Email Archiving anchors revenue stability. Data Loss Prevention is climbing the fastest as compliance automation becomes non-negotiable.
Application:
Workflow integration intensity separates replacement markets from greenfield expansion opportunities.
- Compliance Management:Automated retention scheduling, legal hold processing, and regulatory reporting for audit-ready operations. Banking & Finance and Legal Services verticals drive concentrated demand as GDPR and SEC obligations harden.
- Marketing Automation:Campaign orchestration, A/B testing, and deliverability optimization for customer acquisition teams. Technology and professional services verticals in the United States and Germany decompose monolithic suites into best-of-breed API components.
- Customer Support:Ticket routing, knowledge base integration, and SLA tracking for service operations.
- Internal Communication:Enterprise social networking and departmental distribution list management.
- Sales Enablement:CRM synchronization, template libraries, and activity tracking for revenue teams.
Compliance Management dominates contract values. Marketing Automation is gaining share fastest through API unbundling.
End User Industry:
Regulatory exposure and digital maturity create divergent willingness-to-pay curves across vertical procurement teams.
- Banking & Finance:Multi-jurisdiction compliance requirements spanning SEC, HIPAA, GDPR, and EU AI Act standards. Frankfurt and Paris entities mandate algorithmic transparency documentation for high-risk automated sorting deployments.
- Legal Services:Client confidentiality protection and discovery readiness with ISO 27001-aligned retention policies. Law firms in London and New York create dedicated solution categories for matter-specific email governance.
- IT & Telecom:High-volume infrastructure with API-first automation requirements.
- Education:Cost-optimized deployments with FERPA compliance for student data protection.
- Government Agencies:Classified and unclassified network separation with domestic data residency mandates.
Banking & Finance maintains premium pricing power. Legal Services is expanding most quickly through compliance automation specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic fiber optic cable systems landing at Virginia Beach and Bude-Cornwall underwrite North American and European dominance in cloud software infrastructure. These digital arteries enable sub-50 millisecond latency for email platform synchronization across organizational networks. Data center concentration in Northern Virginia, Frankfurt, and Mumbai shapes vendor deployment architectures and compliance localization strategies.
United States
Mid-market enterprises in Chicago, Austin, and Denver are compressing Exchange migration timelines from 18 months to under six. The SEC mandates immutable audit trails for broker-dealer communications under Rule 17a-4. Northern Virginia's data center corridor hosts the densest concentration of cloud email infrastructure globally.
Germany
Frankfurt banking consortia demand pre-certified EU AI Act compliance modules before procurement approval. The BSI (Federal Office for Information Security) enforces TLS 1.3 minimum standards for federal contractor email systems. Bavarian automotive suppliers in Munich and Ingolstadt are mandating German-sovereign data residency for supplier communications.
India
Organizations in Mumbai, Bangalore, and Delhi are abandoning on-premises Exchange servers for API-native alternatives. The Digital Personal Data Protection Act 2023 imposes cross-border transfer restrictions mirroring GDPR complexity. Hyderabad's IT corridor is emerging as a secondary hub for cloud email migration services.
United Kingdom
Legal Services firms in London and Manchester are creating dedicated procurement categories for ISO 27001-aligned email governance. The UK GDPR retains EU-equivalent data protection standards post-Brexit. Edinburgh's financial services cluster is driving demand for hybrid archiving solutions.
France
Paris-based Banking & Finance entities require algorithmic transparency documentation for automated email sorting under EU AI Act high-risk classifications. The CNIL enforces strict data localization for sensitive administrative communications. Lyon's healthcare technology sector is expanding HIPAA-equivalent email retention deployments.
Global Email Management Software Market Competitive Landscape
Listed leaders compete with private specialists across platform integration depth, creating a tiered structure where scale advantages clash with vertical focus. The vendor base separates into three strategic archetypes: ecosystem-anchored suites, cost-optimized regional specialists, and security-centric point solutions. Consolidation pressure intensifies as mid-market procurement teams favor unified platforms over fragmented toolchains. Dominant competitive moves include API marketplace distribution bypassing systems integrators, and compliance pre-certification to accelerate regulated industry sales cycles.
Within the ecosystem-anchored tier, Microsoft Corporation and Google LLC exemplify platform consolidation strategies, leveraging Office 365 and Workspace integrations to capture enterprise deployments across North America and Europe. Zoho Corporation Pvt. Ltd. occupies a distinct position among cost-optimized specialists, targeting price-sensitive buyers in emerging economies through self-service developer portals and modular subscription unbundling.
| Leading Market Players |
|---|
| Google LLC |
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems Inc. |
| Oracle Corporation |
| Salesforce.com Inc. |
| Zoho Corporation Pvt. Ltd. |
| HubSpot Inc. |
| Proofpoint Inc. |
| Others |
Supply & Pricing Matrix
ISO 27001 certification gates both vendor qualification and price tiering in enterprise procurement cycles, forcing suppliers to absorb audit costs while capturing compliance premiums from regulated buyers. Banking & Finance entities in Frankfurt and Paris mandate pre-certified modules before contract approval, creating a bifurcated market where certified vendors command sustained pricing power against uncertified competitors.
Pricing Analysis
Volume-discount tiering structures separate enterprise deployments from mid-market subscriptions, with Banking & Finance and Legal Services showing lowest price sensitivity due to non-negotiable compliance requirements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and API automation depth as primary differentiation drivers. Pricing pressure stems from subscription unbundling in India and the United States, where procurement teams decompose monolithic suites into component services. Technology and professional services verticals exhibit highest price sensitivity, prioritizing best-of-breed API interoperability over single-vendor consolidation.
Supply Chain Analysis
United States and Germany anchor cloud infrastructure provisioning for enterprise email platforms, with Northern Virginia and Frankfurt data center corridors hosting dense concentrations of multi-tenant architectures. India emerges as a secondary hub for migration services and API-native development talent pools. The supply chain draws from TLS 1.3 certificate authorities, WORM storage hardware vendors, and NLP training data providers as critical inputs. Single-source vulnerability concentrates in hyperscaler cloud dependencies, with regulatory fragmentation across GDPR, SEC, and EU AI Act standards lengthening certification timelines. Distribution runs through direct API marketplace channels and systems integrator partnerships serving regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around API interoperability standards, as mid-market procurement teams abandon monolithic suites for composable service architectures. Microsoft Corporation and Google LLC ecosystem dominance creates interoperability moats that reshape competitive entry calculus.
For Market Incumbents: Shield installed base stickiness through vertical integration into archiving hardware and managed compliance services. Microsoft Corporation leverages Office 365 ecosystem density to deepen switching costs. Google LLC counters through Workspace AI-assisted drafting convergence. Certification investment in EU AI Act pre-validation accelerates regulated industry sales cycles against emerging API-native competitors. For New Entrants and Emerging Players: ISO 27001 fast-track certification unlocks Legal Services white-space in London and New York, where dedicated email governance procurement categories remain underpenetrated. India's legacy Exchange modernization presents greenfield API-native deployment opportunities in Mumbai, Bangalore, and Delhi. Self-service developer portals bypass systems integrator margin extraction for price-sensitive emerging economy buyers. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward compliance-automation specialists with pre-certified algorithmic transparency documentation. Long-term viability centers on vendors bridging on-premises stranded assets with cloud-native migration services. Watch for consolidation signals when hybrid deployment complexity premiums compress below managed services operating margins.| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Pre-Certification | EU AI Act algorithmic transparency documentation accelerates Banking & Finance procurement approval in Frankfurt and Paris. |
| API Marketplace Distribution | Direct developer portals bypass systems integrator channels for price-sensitive mid-market buyers in India. |
| Hybrid Transition Services | On-premises to cloud migration offerings monetize stranded Exchange assets in German banking and French government sectors. |
| AI-Assisted Drafting Integration | NLP-powered productivity features capture premium pricing tiers in United States technology and professional services verticals. |
| Vertical Archiving Specialization | WORM storage and e-discovery indexing address SEC Rule 17a-4 mandates for United States broker-dealer communications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, and EU regulatory databases. Interviews with CTOs, IT procurement officers, platform engineers, and channel partners across Banking & Finance, Legal Services, and Technology verticals inform demand-side validation. Bottom-up deployment volume estimates triangulate against top-down market sizing from vendor revenue disclosures and trade association aggregates.
Segmentation dimensions modeled span deployment architecture, organization size, vertical regulatory exposure, integration complexity, and regional adoption pattern across the analysis window. CAGRs derive from fitted growth curves applied to verified installed base transitions, with cloud migration velocity and compliance mandate enforcement timelines as primary forecast inputs.
Underlying assumptions cover sustained EU AI Act implementation timelines and TLS 1.3 protocol adoption rates, with deviation risk concentrated in data localization enforcement variability across Germany, France, and India. Recalibration cycles align with material shifts in cross-border transfer rulings and hyperscaler infrastructure expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Core Banking Software Market
Software & Services
Global OKR Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Digital Sculpture Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
Italy HR Payroll Software Market
Software & Services
Global Process Mining Software Market
Software & Services
OCR Scanning Software Market
Software & Services
Europe Enterprise Resource Planning (ERP) Software Market
Software & Services
Global Pension Administration Software Market
Software & Services
Online Project Management Software Market
Software & Services
Reporter Systems Market
Software & Services
Global MSP Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
United States IT Services Market