
 Global Refrigerator Water Filters Market | 2026-2036
Global Refrigerator Water Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refrigerator Water Filters Market Outlook
Commercial kitchen operators are rotating toward higher-capacity inline filtration systems as restaurants expand beverage programs and ice production. Samsung leverages its smart appliance ecosystem to embed filter monitoring directly into refrigerator interfaces, sustaining recurring replacement revenue. Whirlpool anchors its position through captive distribution via branded replacement programs that control the aftermarket channel. GE competes on certification breadth, dominating NSF/ANSI 401 and 53 protocol coverage for emerging contaminant removal.
Refrigerator water filters are replaceable cartridges designed to reduce chlorine, sediment, volatile organic compounds, and specific heavy metals from dispensed water and ice, typically employing activated carbon block media with nominal micron ratings between 0.5 and 5 microns to meet potable water safety thresholds. Carbon filters command the largest volume share due to cost efficiency and compatibility with mainstream refrigerator architectures, while reverse osmosis configurations capture premium margin pools in built-in installations where total dissolved solids reduction is specified. External installation types lead unit shipments by accommodating retrofit demand across aging refrigerator bases, though built-in segments concentrate value through OEM attachment rates on new appliance sales.
NSF International standards, EPA guidelines under the Safe Drinking Water Act, and EU Drinking Water Directive frameworks collectively shape product certification requirements and cross-border market access conditions for filter manufacturers. The FDA's oversight of food contact surfaces and materials influences carbon media binder chemistries and housing resin selections for units serving commercial food preparation environments. Stakeholders must monitor evolving contaminant priority lists and state-level notification requirements as regulatory bodies expand testing protocols beyond traditional chlorine and lead parameters.
Market Dynamics
Smart refrigerator ecosystems are compressing replacement cycles by embedding real-time filter monitoring and automated replenishment triggers into appliance software, locking households into proprietary cartridge formats and recurring revenue streams.
Growth Catalysts
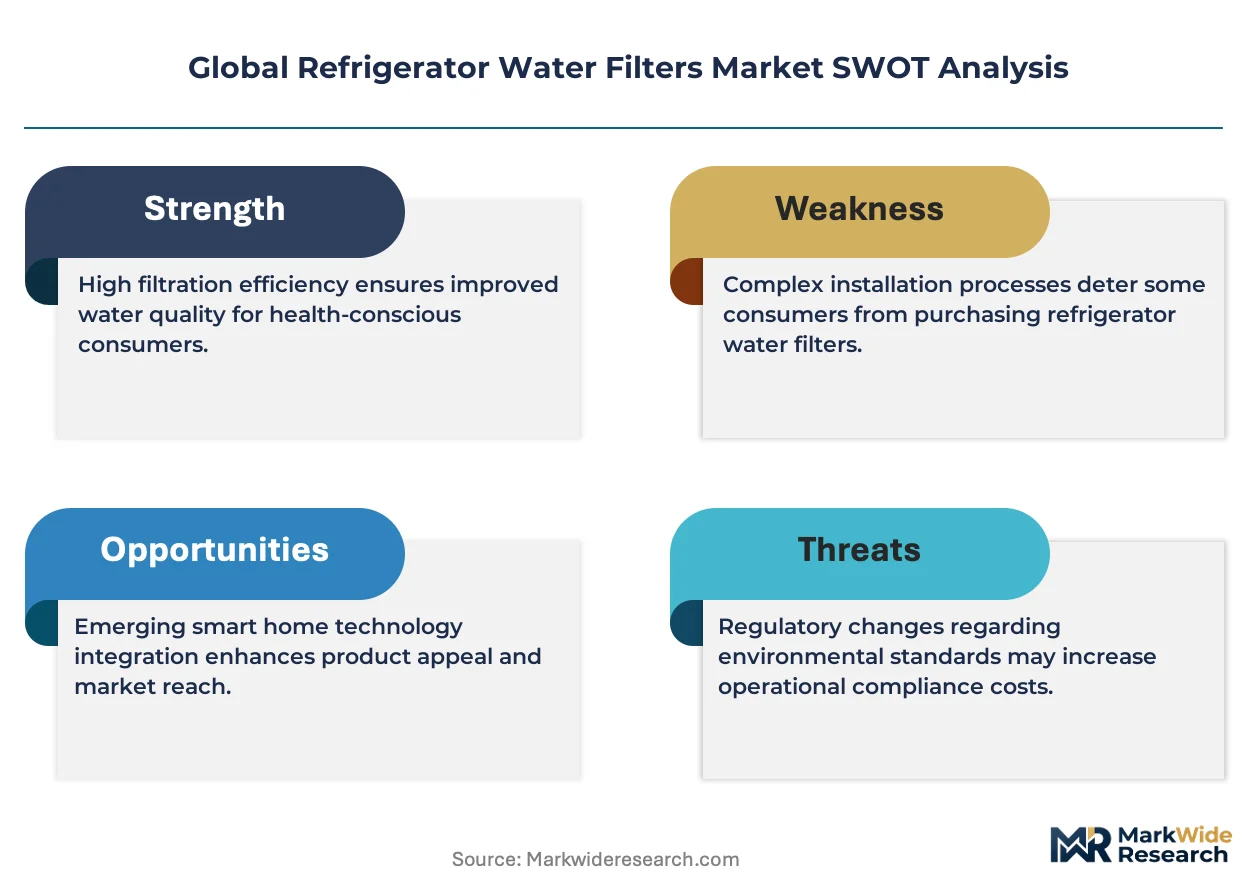
- EPA Safe Drinking Water Act amendments:Stricter contaminant monitoring protocols are elevating NSF/ANSI certification requirements, forcing filter upgrades and expanding addressable demand for performance-rated cartridges.
- Smart appliance connectivity:WiFi-enabled refrigerators are integrating filter status dashboards and subscription auto-replenishment, reducing purchase friction and locking in replacement revenue.
- Commercial beverage program expansion:Restaurant and hospitality operators are specifying higher-capacity inline filtration for ice production and dispensed drinks, driving volume in external installation formats.
Market Restraints
- Activated carbon cost volatility:Coconut shell carbon feedstock prices fluctuate with agricultural yields and shipping rates, compressing margins on economy-tier cartridges.
- OEM captive distribution:Samsung, Whirlpool, and GE control proprietary cartridge architectures, blocking third-party aftermarket access through interface authentication chips.
- Reverse osmosis technical ceiling:RO membranes require minimum water pressure and drainage infrastructure unavailable in most retrofit installations, limiting penetration to built-in premium segments.
Strategic Opportunities
- India residential underpenetration:Refrigerator ownership is accelerating in tier-2 and tier-3 cities without mature water infrastructure, creating first-mover potential for filtration-integrated appliances.
- EU Green Deal circularity mandates:The Ecodesign for Sustainable Products Regulation is pressuring manufacturers toward recyclable cartridge housings and take-back programs, rewarding redesign investment.
- Direct-to-consumer channel emergence:Subscription platforms are bypassing big-box retail, capturing customer data and enabling predictive replenishment algorithms.
Industry Challenges
- NSF/ANSI certification timeline compression:Expanding contaminant priority lists require continuous protocol updates, stretching R&D validation cycles and delaying product launches.
- Legacy refrigerator base incompatibility:Aging installed units lack standardized filter interfaces, fragmenting aftermarket SKU requirements and complicating inventory planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refrigerator Water Filters Market |
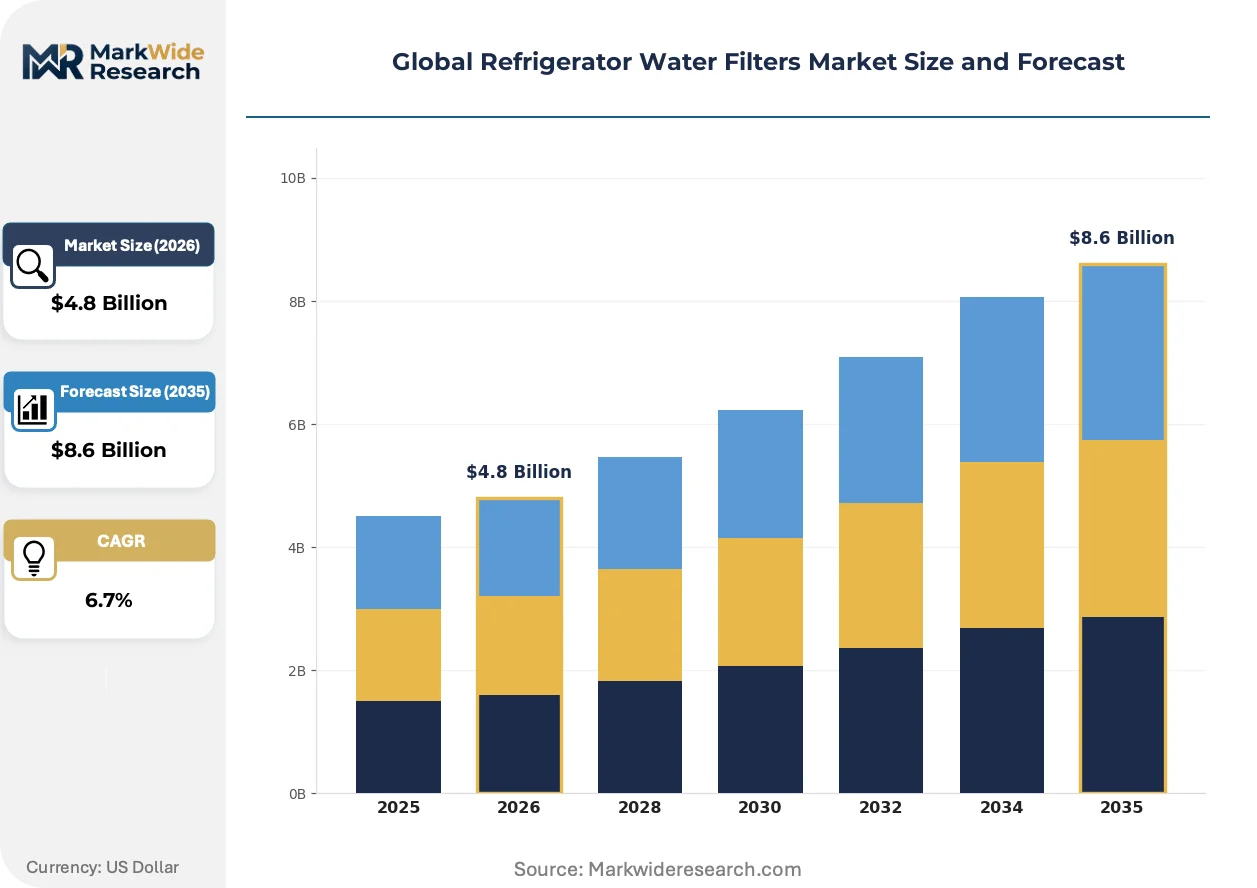
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Filters, Reverse Osmosis, Sediment Filters, Inline Filters End User: Households, Restaurants, Cafes, Commercial Kitchens Installation Type: Built-in, External, Portable, Undersink Distribution Channel: Online Retail, Specialty Stores, Wholesale Distributors, Supermarkets |
| Companies Covered | LG Electronics, Samsung, Whirlpool, Electrolux, Bosch, GE, Kenmore, Waterdrop, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refrigerator Water Filters Market Strategic Shifts
Filtration technology is converging with IoT infrastructure and circular economy mandates, reshaping how cartridges are designed, sold, and recovered. Three developments are redefining competitive positioning.
Electroadsorption media using carbon nanotube arrays is displacing conventional activated carbon blocks in premium built-in installations, capturing heavy metals and microplastics below 0.1 microns. Luxury kitchen designers in Germany and the United Arab Emirates are specifying these configurations for total dissolved solids reduction. The technology is displacing incumbent carbon block suppliers in high-margin custom appliance programs.
The EU Drinking Water Directive's revised parametric values for emerging contaminants are mandating broader filtration protocol coverage across member states. Manufacturers serving the Netherlands and Denmark must now validate removal rates for pharmaceutical residues and endocrine disruptors. Carbon block formulations with enhanced catalytic surfaces are capturing compliance-driven specification shifts in these markets.
Households are compressing replacement intervals from manufacturer-recommended six-month cycles to quarterly changes driven by water quality anxiety and smart refrigerator alert frequency. Subscription platforms in the United States are capitalizing on this behavioral shift with predictive shipping algorithms tied to usage sensors. The pattern is most pronounced in regions with documented lead service line infrastructure.
Global Refrigerator Water Filters Market Segmentation
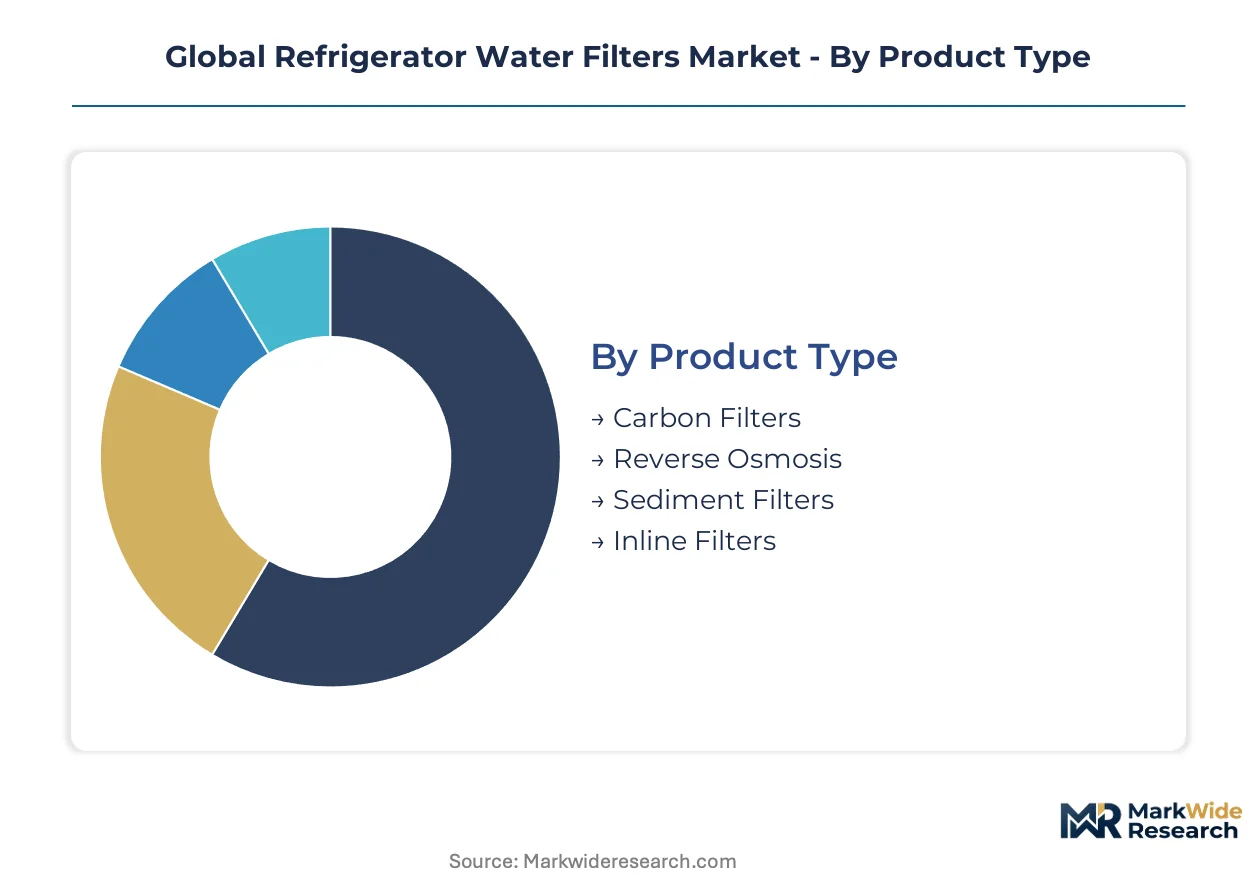
Filter manufacturers navigate divergent technical requirements across residential retrofit demand and OEM-integrated new appliance sales. Segmentation reveals where margin pools concentrate versus where volume shipments accumulate.
Product Type:
Carbon block formulations dominate domestic production in the United States and Germany, while reverse osmosis membranes flow primarily from South Korean and Japanese suppliers serving export markets.
- Carbon Filters:Activated carbon block media with 0.5-5 micron nominal ratings reduce chlorine, sediment, and volatile organic compounds. Demand concentrates in United States households replacing cartridges on shortened quarterly cycles driven by water quality anxiety and smart refrigerator alert frequency.
- Reverse Osmosis:Thin-film composite membranes requiring minimum water pressure and drainage infrastructure achieve total dissolved solids reduction below 10 ppm. Germany and United Arab Emirates luxury kitchen designers specify these for built-in premium installations where municipal water hardness exceeds 300 mg/L.
- Sediment Filters:Polypropylene depth filters with 5-50 micron ratings protect downstream carbon blocks from premature fouling.
- Inline Filters:Quick-connect cartridges install externally between water supply and refrigerator inlet, accommodating aging refrigerator bases lacking OEM filter housings.
Carbon filters command the established base. The steepest expansion runs through reverse osmosis configurations in premium built-in segments.
End User:
Cost tiers separate replacement-driven household demand from specification-heavy commercial procurement with divergent certification requirements.
- Households:Residential buyers prioritize NSF/ANSI 53 and 401 certification for lead and emerging contaminant removal, with subscription auto-replenishment reducing purchase friction.
- Restaurants:Full-service operators specify higher-capacity inline filtration for ice production and beverage programs, with FDA food contact surface compliance mandatory for carbon media binder chemistries.
- Cafes:Coffee-focused establishments demand chlorine reduction below 0.5 ppm to protect espresso machine boilers from corrosion.
- Commercial Kitchens:Institutional foodservice operators in the United States face EPA Safe Drinking Water Act amendment compliance for lead service line notification requirements.
Household replacement volume anchors revenue stability. Cafe and restaurant specifications are gaining share fastest as beverage program sophistication expands.
Installation Type:
Volume concentrates in external formats accommodating retrofit demand, while margin pools attach to OEM-integrated built-in configurations on new appliance sales.
- Built-in:OEM-integrated housings with proprietary authentication chips lock replacement revenue to manufacturer cartridge formats, prevalent in WiFi-enabled smart refrigerator ecosystems.
- External:Quick-connect inline units bypass proprietary interfaces, serving India's tier-2 and tier-3 cities where refrigerator ownership accelerates without mature water infrastructure.
- Portable:Countertop dispensers with integrated filtration target rental households and temporary installations lacking plumbing modifications.
- Undersink:Dedicated filtration systems with separate faucets bypass refrigerator dispensers entirely, competing for the same water quality budget in kitchen renovations.
External installations capture volume leadership. Built-in segments concentrate value through captive aftermarket control.
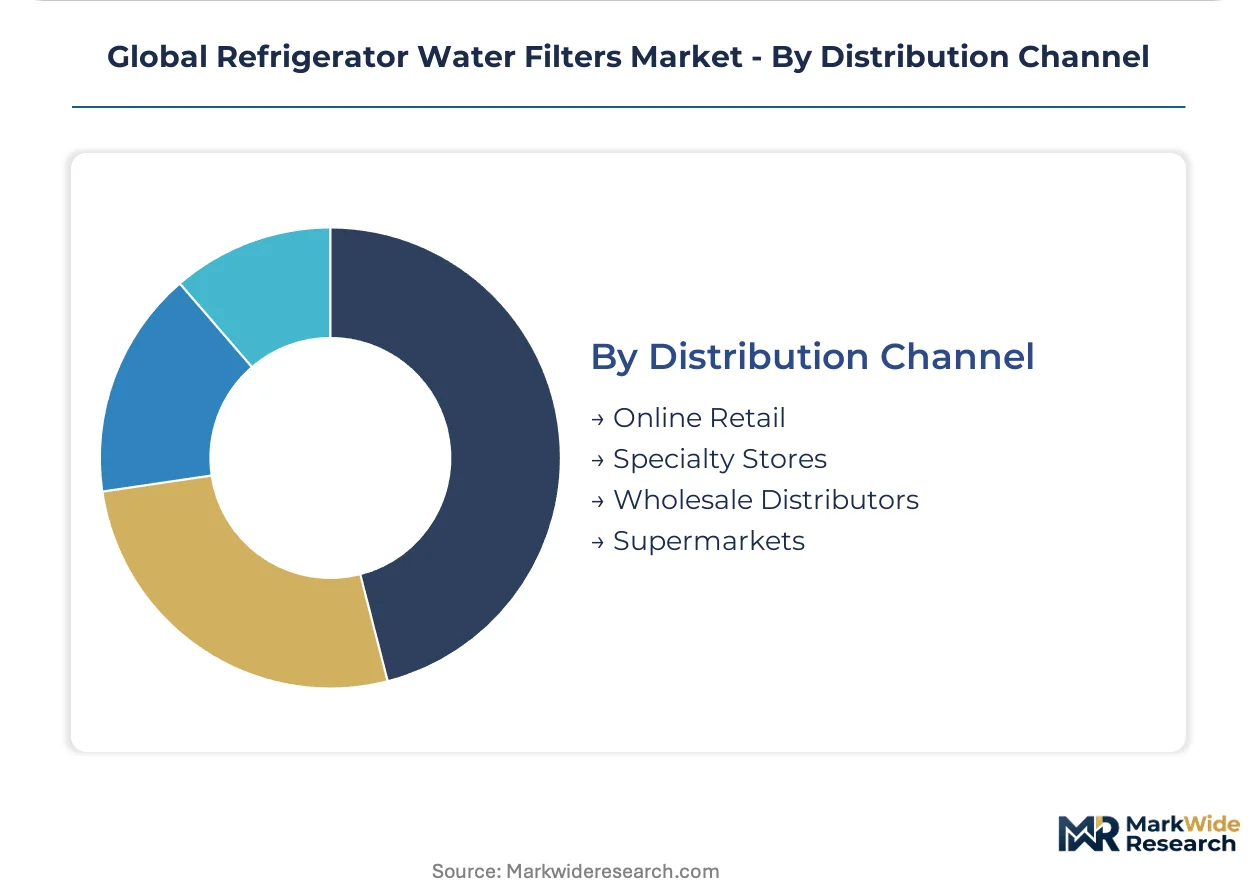
Distribution Channel:
Customer data capture and predictive replenishment algorithms are shifting procurement from big-box retail toward direct-to-consumer platforms.
- Online Retail:Subscription platforms bypass traditional retail, enabling predictive shipping tied to usage sensors and smart refrigerator API integration.
- Specialty Stores:Kitchen design showrooms in Germany and the Netherlands specify electroadsorption media for emerging contaminant compliance under EU Drinking Water Directive revisions.
- Wholesale Distributors:Commercial foodservice supply chains aggregate restaurant and cafe procurement with volume pricing for higher-capacity inline systems.
- Supermarkets:Mass retail carries economy-tier carbon cartridges with compressed margins, vulnerable to coconut shell feedstock price volatility.
Supermarkets and wholesale distributors retain the established base. Online retail channels are climbing the fastest as subscription models lock in recurring replacement revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export carbon block cartridges to United States distributors serving retrofit demand, while South Korean suppliers ship reverse osmosis membranes to Germany and the United Arab Emirates for premium built-in installations.
United States
Household replacement cycles compress to quarterly intervals driven by smart refrigerator alert systems and subscription auto-replenishment platforms. The EPA's Safe Drinking Water Act amendments mandate lead service line notification requirements that elevate NSF/ANSI 53 certification standards. Michigan and Ohio industrial clusters concentrate filter packaging operations serving the Great Lakes region's aging water infrastructure concerns.
Germany
Luxury kitchen designers specify electroadsorption media for total dissolved solids reduction in high-end residential renovations. The EU Drinking Water Directive's revised parametric values for pharmaceutical residues and endocrine disruptors force protocol expansions. Bavaria's appliance manufacturing corridor integrates filtration modules into premium refrigerator platforms exported throughout the European Union.
China
Domestic refrigerator ownership accelerates in tier-2 and tier-3 cities without mature municipal water treatment infrastructure. The country's national standards body aligns filtration performance benchmarks with international potable water safety thresholds. Yangtze River Delta manufacturing hubs produce activated carbon blocks for export to North American and European aftermarket channels.
India
External inline filter installations dominate as refrigerator penetration expands ahead of water infrastructure development in secondary cities. The Bureau of Indian Standards mandates food contact surface compliance for carbon media binder chemistries in commercial food preparation environments. Maharashtra and Gujarat industrial zones assemble quick-connect filtration units for domestic distribution and regional export.
United Arab Emirates
Luxury residential developments specify reverse osmosis configurations where municipal water hardness exceeds 300 mg/L. The Ministry of Health and Prevention oversees food contact material approvals for filtration systems serving hospitality and foodservice sectors. Dubai's high-end kitchen design showrooms drive specification of electroadsorption media in custom appliance programs.
Global Refrigerator Water Filters Market Competitive Environment
Player mix skews toward diversified appliance conglomerates controlling proprietary cartridge architectures through authentication chips and captive aftermarket channels. The vendor base concentrates around three strategic archetypes: smart ecosystem integrators leveraging refrigerator connectivity for recurring replacement revenue, certification-focused specialists dominating NSF/ANSI protocol breadth, and private-label assemblers serving price-sensitive retrofit demand. Dominant competitive moves include backward integration into carbon media production and strategic partnerships with water quality sensor manufacturers.
Within the diversified conglomerate tier, Samsung and LG Electronics anchor positions through smart appliance ecosystems that embed filter monitoring into refrigerator interfaces. Whirlpool occupies a position exemplifying captive distribution control via branded replacement programs. GE represents the certification-specialist archetype with emphasis on contaminant removal protocol coverage.
| Leading Market Players |
|---|
| LG Electronics |
| Samsung |
| Whirlpool |
| Electrolux |
| Bosch |
| GE |
| Kenmore |
| Waterdrop |
| 3M |
| Others |
Value Chain & Pricing Dynamics
NSF/ANSI certification regimes gate both supplier qualification and price differentiation simultaneously, forcing carbon block manufacturers to absorb validation costs while OEMs extract premium through proprietary authentication architectures. Coconut shell carbon feedstock volatility and smart refrigerator ecosystem lock-in create divergent margin pressures across aftermarket and captive channels.
Pricing Analysis
Next-generation electroadsorption media commands substantial premiums over activated carbon blocks, while legacy sediment filters face commoditization. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 401-certified cartridges from basic chlorine reduction units. Pricing pressure stems from coconut shell carbon agricultural yield fluctuations compressing margins on economy-tier products. Household subscription buyers show lowest price sensitivity, while India's tier-2 retrofit purchasers drive volume at compressed price points.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for carbon block manufacturers sourcing coconut shell media from Southeast Asian agricultural processors. Production gravity centers on China's Yangtze River Delta for activated carbon blocks, South Korea for reverse osmosis membranes, and Germany for electroadsorption nanotube arrays. Raw material dependencies include coconut shell carbon, polypropylene depth media, and thin-film composite membrane chemistries. Single-source vulnerability concentrates in South Korean RO membrane supply. Distribution runs through OEM captive channels, big-box retail, and emerging direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart refrigerator ecosystems are redefining this market as a platform-economics inflection, with proprietary authentication chips and API-integrated replenishment creating winner-take-most dynamics that marginalize unconnected aftermarket suppliers.
For Market Incumbents: Secure backward integration into carbon media production to insulate margin from coconut shell feedstock volatility. Lock in certification breadth across emerging contaminant protocols before NSF/ANSI timeline compression delays competitor launches. Defend against third-party cartridge encroachment by deepening smart appliance API integration and subscription platform ownership. For New Entrants and Emerging Players: Lead with external inline filtration targeting India's tier-2 and tier-3 cities where refrigerator ownership accelerates ahead of water infrastructure maturity. Bypass OEM authentication barriers by serving aging refrigerator bases lacking proprietary filter housings. Establish direct-to-consumer subscription channels with predictive algorithms tied to usage sensors rather than competing through retail shelf presence. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified appliance conglomerates seeking to monetize captive aftermarket filtration units as standalone recurring revenue platforms. Long-term viability hinges on subscription retention rates and smart ecosystem interoperability rather than one-time cartridge sales. Monitor EU Green Deal circularity mandate compliance costs as an inflection signal for manufacturing asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Media Production | Coconut shell carbon sourcing control insulates margin from agricultural yield volatility. |
| Smart Refrigerator API Integration | Filter status dashboards lock households into proprietary cartridge replenishment ecosystems. |
| EU Circularity Compliance Investment | Recyclable cartridge housings and take-back programs satisfy Ecodesign for Sustainable Products Regulation mandates. |
| Direct-to-Consumer Subscription Launch | Predictive shipping algorithms capture customer data and bypass big-box retail margin compression. |
| NSF/ANSI 401 Certification Expansion | Pharmaceutical residue and endocrine disruptor removal validation opens Netherlands and Denmark specification opportunities. |
Study Parameters
Desk research of regulatory filings, trade customs databases, and appliance OEM technical documentation preceded structured interviews with refrigerator platform engineers, aftermarket filter procurement managers, carbon media production specialists, and commercial foodservice equipment distributors. Primary fieldwork captured smart ecosystem integration roadmaps and certification validation timelines. Secondary sources included EPA Safe Drinking Water Act amendment dockets, NSF International protocol revision notices, and EU Drinking Water Directive implementation guidance. Bottom-up unit shipment modeling triangulated against top-down value estimates derived from OEM replacement program disclosures.
Variance decomposition across technology generation, installation type, and end-use segment shaped the analytical framework over the projection horizon. Modeled dimensions spanned carbon block versus reverse osmosis versus electroadsorption media, built-in versus external versus portable installation, and household versus commercial kitchen end-use. CAGRs derived from replacement cycle compression rates, smart refrigerator penetration curves, and regional water infrastructure development trajectories. Forecast inputs incorporated coconut shell carbon price indices and NSF/ANSI certification pipeline visibility.
The analysis sits within stated boundaries; outcomes outside sustained smart appliance connectivity adoption or accelerated EU regulatory timeline implementation would require recalibration. Forecasts reflect assumptions regarding OEM authentication chip proliferation and subscription platform customer acquisition economics. Coconut shell agricultural yield disruption, port congestion recurrence, or state-level lead service line notification requirement expansion could materially revise trajectory. Recalibration cycles align with material shifts in smart refrigerator shipment data and NSF protocol revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Faucets Market
Household Items
Tablet Tissue Paper Market
Household Items
Bristle Brush Market
Household Items
Memory Foam Market
Household Items
Shoe Dryer Market
Household Items
Gas Hobs Market
Household Items
Portable Humidifiers Market
Household Items
Smart Air Purifier Market
Household Items
Smart Spin Mop Market
Household Items
Ultrasonic Diffusers Market
Household Items
MENA POU Water Purifiers Market
Household Items
Flushable Wipes Market
Household Items
Dry Cleaning and Laundry Market
Household Items
India POU Water Purifiers Market
Household Items
Global Electronic Bidet Seats Market
Household Items
Netherlands Cookware Market