
 Efflorescence Remover Market | 2026-2036
Efflorescence Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Efflorescence Remover Market Analytics
Concentrated refill-and-dilution kits paired with applicator accessories is expanding buyer choice in the efflorescence remover category. Foundation Armor leverages its specialty masonry coatings heritage to anchor premium positioning in direct-to-contractor channels. Rust-Oleum competes through mass retail scale and brand recognition among residential renovators. Southeast Softwash differentiates with dedicated soft-wash equipment bundles that integrate chemical delivery systems for commercial cleaning operators.
Efflorescence removers are surface treatment formulations designed to dissolve and lift soluble salt deposits from concrete, brick, stone, and masonry substrates through acidic, alkaline, or chelating action, typically requiring controlled dwell times and neutralization protocols to prevent substrate damage. Chemical solutions dominate current volume due to established efficacy against heavy carbonate and sulfate deposits, though biodegradable options are gaining structural share as environmental compliance tightens across European and North American construction markets. Masonry restoration commands the highest margin pool within applications, driven by heritage building conservation standards and specialized contractor procurement, while spray products lead distribution growth through e-commerce platforms serving DIY and light commercial segments.
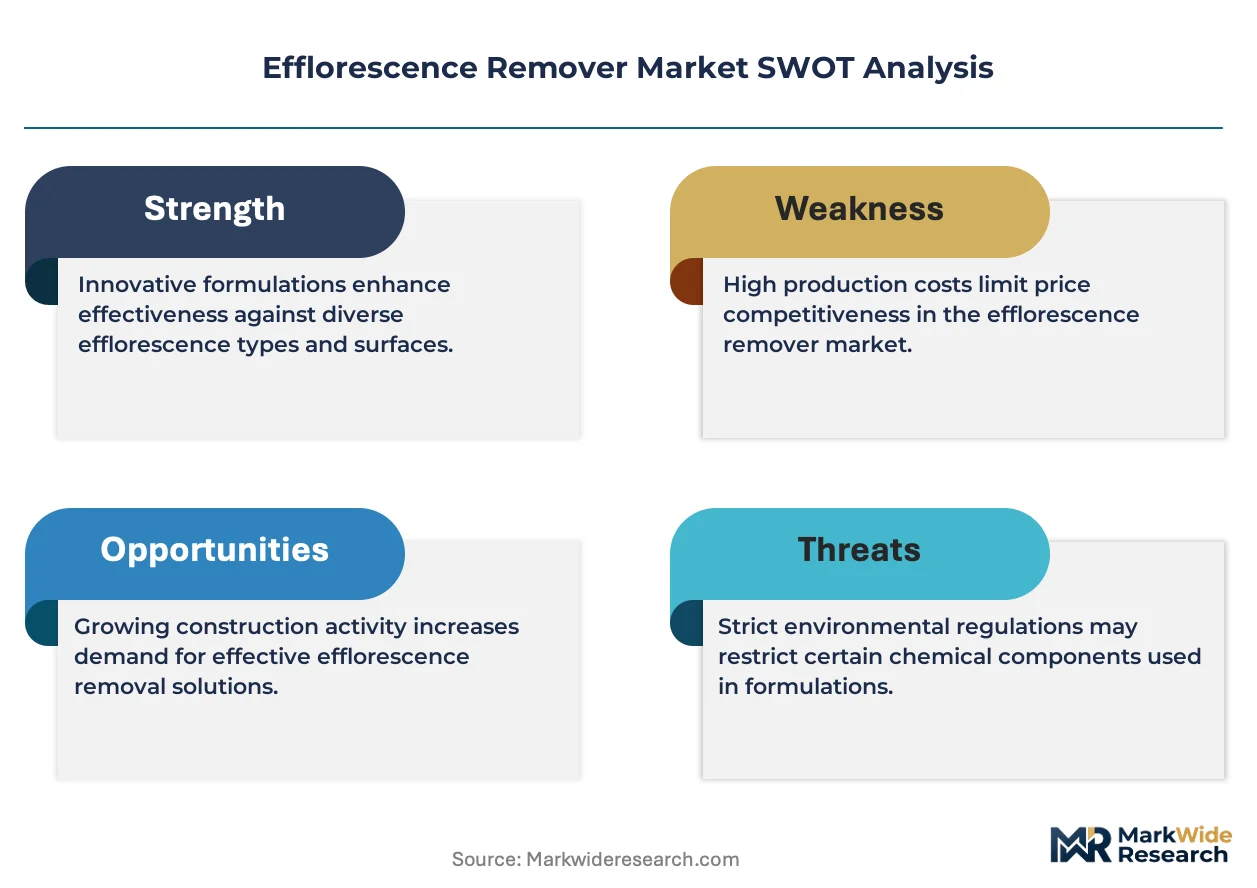
EPA VOC regulations and REACH substance restrictions are reshaping formulation portfolios, pushing manufacturers toward water-based and non-toxic alternatives that maintain stripping performance without restricted acids or solvents. OSHA workplace exposure standards further constrain industrial application methods, favoring gel formulations that reduce airborne chemical release during vertical surface treatment. Stakeholders must monitor evolving state-level green procurement mandates and building certification schemes that increasingly specify low-impact cleaning protocols for commercial and public structures.
Market Dynamics
REACH substance restrictions and OSHA workplace exposure standards are forcing manufacturers to abandon legacy acid-based formulations in favor of water-based and gel alternatives that reduce airborne chemical release during masonry restoration work.
Growth Catalysts
- Heritage Building Conservation Mandates:Germany's federal monument protection programs require specialized efflorescence treatment for historic masonry structures, creating sustained demand for premium restoration-grade formulations.
- EPA VOC Compliance Deadlines:Tightening volatile organic compound limits in architectural coatings and maintenance chemicals are accelerating replacement cycles for legacy solvent-based removers across US commercial property portfolios.
- Soft-Wash Equipment Bundling:Integration of chemical delivery systems with low-pressure washing rigs is expanding addressable market for commercial exterior cleaning contractors managing large-scale facade maintenance contracts.
Market Restraints
- Phosphoric Acid Supply Concentration:Dependence on Chinese and Moroccan phosphate rock processing creates input cost volatility and supply security concerns for acid-based formulation producers.
- Biodegradable Efficacy Gap:Current enzymatic and surfactant-based alternatives demonstrate reduced performance against heavy sulfate deposits, limiting substitution rates in industrial restoration applications.
- REACH Registration Burden:The European Chemicals Agency's substance evaluation and authorization requirements impose multi-year compliance timelines and testing costs that disadvantage smaller formulation specialists.
Strategic Opportunities
- Refill-and-Dilution Concentrates:Concentrated chemical kits paired with calibrated applicators reduce shipping costs and plastic waste, aligning with green procurement mandates in municipal and institutional building maintenance.
- Photovoltaic Substrate Cleaning:Efflorescence accumulation on solar panel mounting frames and concrete ballast systems represents an emerging application as utility-scale solar installations age across Spain and Italy.
- E-Commerce Contractor Supply:Direct-to-professional digital channels bypass traditional distribution markups and enable subscription replenishment models for recurring maintenance contractors.
Industry Challenges
- Skilled Restoration Technician Shortage:Specialized masonry conservation expertise required for substrate-safe efflorescence removal is concentrating among aging contractor networks in Western Europe.
- Certification Timeline Compression:Accelerating green building certification schemes demand rapid reformulation validation against multiple eco-label standards simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Efflorescence Remover Market |
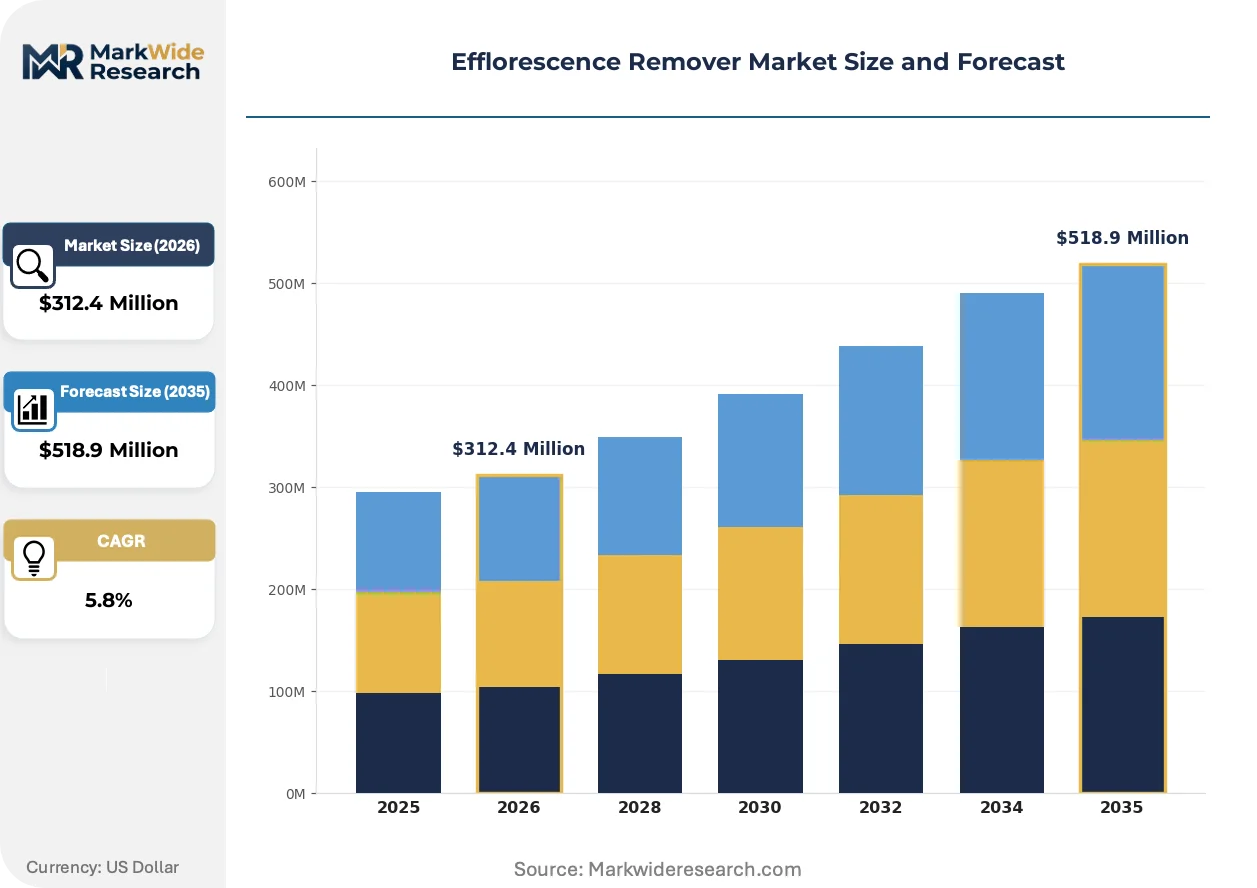
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemical Solutions, Biodegradable Options, Gel Formulations, Spray Products Application: Residential Use, Commercial Buildings, Industrial Facilities, Masonry Restoration Formulation: Acidic Formulations, Alkaline Formulations, Water-Based Solutions, Non-Toxic Options Distribution Channel: Retail Stores, Online Marketplaces, Direct Sales, Wholesale Distributors |
| Companies Covered | RadonSeal, Foundation Armor, Rust-Oleum, City Clean Inc., Omni, Chemique, PROTECTiT, Southeast Softwash, Aqua Mix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Efflorescence Remover Market Evolving Landscape
Formulation chemistry and application methodology are converging around reduced environmental impact without sacrificing stripping performance against carbonate and sulfate salt deposits.
Chelating agent technology is decentralizing efflorescence treatment from industrial contractors to facility maintenance staff. Ethylenediaminetetraacetic acid and gluconate-based formulations enable controlled dwell times without aggressive neutralization protocols. Property management teams in Germany and the Netherlands are adopting these systems for in-house facade maintenance, compressing reliance on specialized restoration firms for routine salt deposit removal.
REACH Annex XVII restrictions on hydrochloric acid concentrations in consumer products are mandating reformulation across European supply chains. Industrial-grade removers face parallel scrutiny under the EU's Classification, Labelling and Packaging Regulation. Manufacturers serving German heritage conservation programs are pivoting toward buffered organic acid blends that maintain efficacy while satisfying substance authorization requirements.
Certification-driven procurement is restructuring buyer decision criteria for commercial cleaning contracts. LEED and BREEAM building standards increasingly specify low-impact cleaning protocols for exterior maintenance. Facility managers in UK commercial property portfolios are prioritizing products carrying EU Ecolabel or Nordic Swan certification, displacing price-based selection in premium building segments.
Efflorescence Remover Market Segmentation
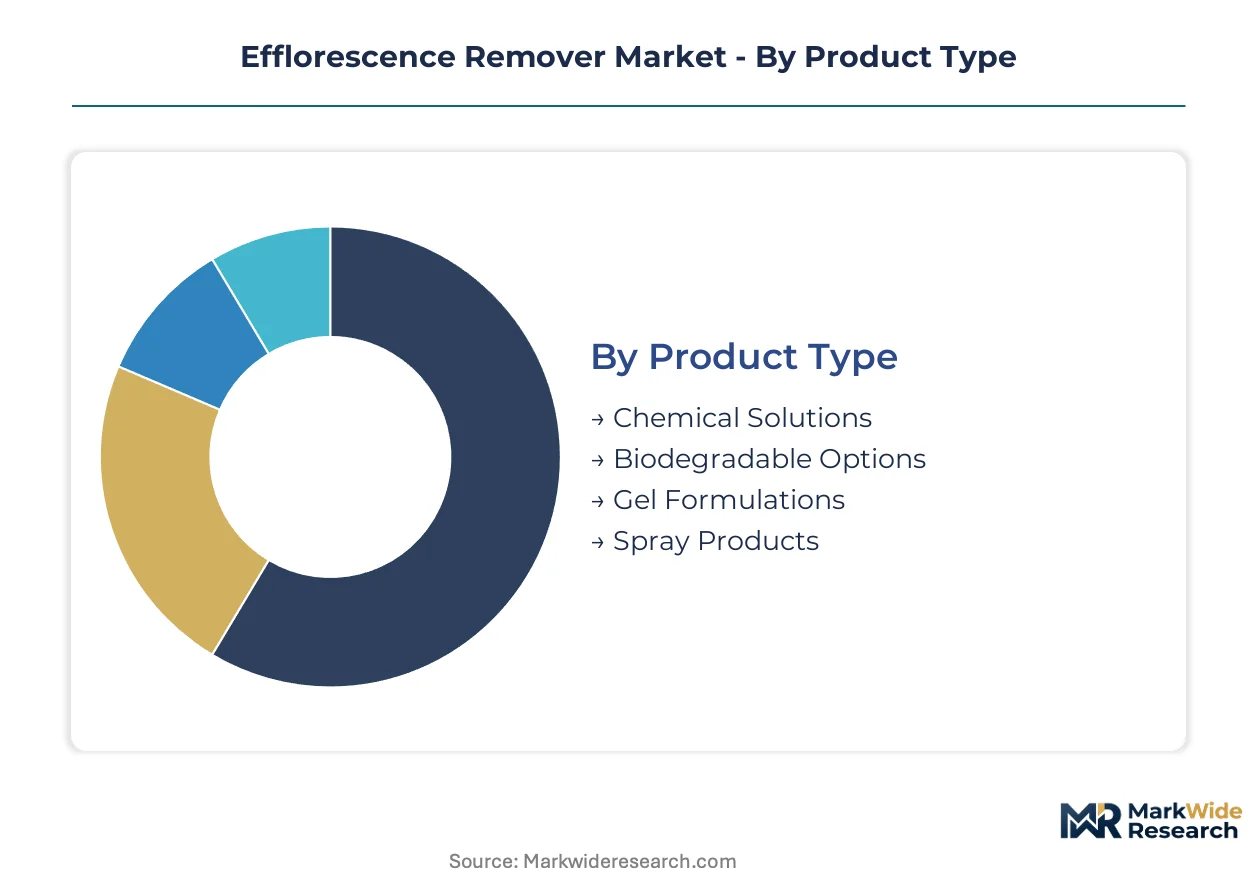
Efflorescence remover segmentation reveals distinct upgrade cycles across formulation chemistry, application intensity, and procurement channels. Understanding these segment boundaries exposes where substitution pressures and margin compression concentrate most acutely.
Product Type:
Replacement cycles accelerate where REACH substance restrictions and OSHA exposure standards force abandonment of legacy acid systems.
- Chemical Solutions:Acidic and chelating formulations containing phosphoric, hydrochloric, or sulfamic acid deliver aggressive stripping against heavy carbonate and sulfate deposits. Demand concentrates in German heritage masonry restoration programs where substrate compatibility testing justifies premium pricing for industrial-grade performance.
- Biodegradable Options:Enzymatic and surfactant-based formulations utilize microbial action and plant-derived chelators to dissolve salt deposits without hazardous neutralization protocols. Uptake climbs fastest in Dutch and UK commercial property portfolios where BREEAM and LEED certification mandates specify low-impact cleaning protocols for facade maintenance contracts.
- Gel Formulations:Thixotropic systems cling to vertical masonry surfaces, extending dwell time while reducing airborne chemical release per OSHA workplace exposure guidelines.
- Spray Products:Pre-mixed aqueous solutions in trigger or aerosol delivery target DIY residential renovators and light commercial touch-up work through hardware retail and e-commerce channels.
Chemical solutions sit at the top of the volume ranking, with biodegradable options climbing the fastest.
Application:
Cost tier differentiation separates routine maintenance budgets from capital-intensive conservation programs.
- Residential Use:Homeowners tackle efflorescence on concrete driveways, basement walls, and brick patios using consumer-grade acidic or water-based removers. Procurement concentrates through home improvement retailers in suburban US markets where moisture intrusion drives seasonal purchase patterns.
- Commercial Buildings:Property management teams maintain office facades, parking structures, and retail exteriors through contracted cleaning services or in-house facilities staff. German commercial portfolios lead premium formulation uptake due to stringent facade maintenance ordinances in Munich and Hamburg.
- Industrial Facilities:Manufacturing plants and warehouses require heavy-duty chemical solutions for concrete flooring and structural masonry exposed to process moisture and chemical splash.
- Masonry Restoration:Specialized contractors restore historic monuments, churches, and civic structures under heritage conservation mandates. This segment commands the highest margin pool due to substrate-sensitive application protocols and conservation officer oversight requirements.
Masonry restoration captures the highest margin tier, while commercial buildings represent the steepest expansion trajectory.
Formulation:
Volume concentration follows established supply chains for mineral acid feedstocks, though regulatory pressure redistributes share toward aqueous systems.
- Acidic Formulations:Mineral and organic acid blends penetrate masonry pores to dissolve calcium carbonate and magnesium sulfate deposits through proton-exchange reactions. Supply security concerns mount for phosphoric acid derivatives given Chinese and Moroccan phosphate rock processing concentration.
- Alkaline Formulations:Caustic-based systems saponify organic contaminants while attacking certain salt deposits, finding niche application in pre-cleaning protocols before acidic efflorescence treatment.
- Water-Based Solutions:Buffered aqueous systems with reduced VOC content satisfy EPA architectural coatings regulations and REACH authorization timelines. Dutch facility managers prioritize these formulations for in-house maintenance teams lacking specialized chemical handling certification.
- Non-Toxic Options:Citric acid, gluconate, and bio-surfactant formulations eliminate hazard classification for shipping and storage, reducing insurance and compliance burdens for municipal procurement.
Acidic formulations retain volume leadership, with water-based solutions gaining share fastest amid regulatory compliance deadlines.
Distribution Channel:
Customer type and purchase frequency determine channel economics, with digital platforms compressing traditional wholesale markups.
- Retail Stores:Home centers and hardware chains stock consumer-grade spray and liquid formulations for immediate DIY purchase. This channel dominates residential volume in US and Australian suburban markets.
- Online Marketplaces:Amazon, specialized construction supply platforms, and manufacturer-direct sites enable subscription replenishment for recurring commercial contractors. German restoration specialists increasingly procure certified formulations through digital channels to bypass distributor stock limitations.
- Direct Sales:Manufacturer representatives serve large commercial property portfolios and heritage conservation agencies with technical specification support and batch certification documentation.
- Wholesale Distributors:Regional construction supply houses inventory industrial-grade chemical solutions for contractor pickup, though share erodes as direct digital procurement expands.
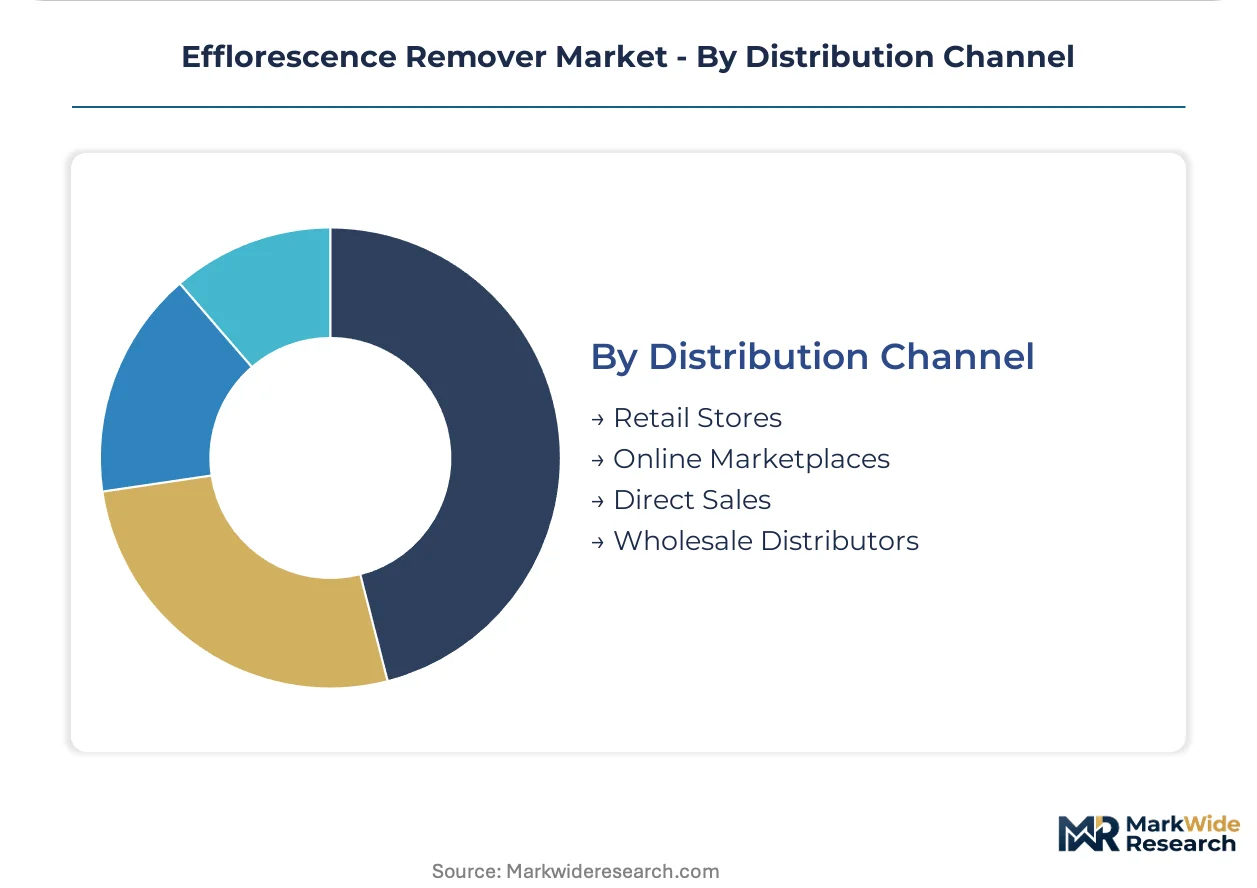
Retail stores anchor current volume, with online marketplaces expanding most quickly through contractor subscription models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Efflorescence remover formulation originated in post-war European masonry conservation laboratories, with industrial-scale production scaling first through German chemical clusters serving heritage restoration programs. Geographic demand patterns now track regulatory stringency and building stock age across mature construction markets.
Germany
Federal monument protection programs mandate specialized efflorescence treatment for historic masonry structures, sustaining premium formulation demand. REACH Annex XVII restrictions on hydrochloric acid concentrations force manufacturers toward buffered organic acid blends. Munich and Hamburg commercial property portfolios drive concentrated uptake of certified restoration-grade products through direct technical procurement channels.
United States
Commercial property maintenance budgets expand as aging concrete infrastructure requires systematic salt deposit management. EPA VOC compliance deadlines for architectural coatings accelerate replacement cycles for legacy solvent-based removers. Suburban DIY markets concentrate through home improvement retail chains in moisture-prone southeastern and midwestern states.
Netherlands
BREEAM certification mandates in commercial building portfolios prioritize low-impact cleaning protocols for facade maintenance contracts. Facility managers adopt water-based formulations for in-house teams lacking specialized chemical handling certification. Rotterdam and Amsterdam heritage districts generate sustained demand for substrate-sensitive restoration applications.
United Kingdom
LEED and BREEAM procurement specifications displace price-based selection in premium London commercial property segments. Conservation officer oversight requirements for historic monuments sustain specialized contractor networks. Manchester and Birmingham industrial heritage sites drive periodic heavy-duty treatment cycles for structural masonry exposed to process moisture.
Italy
Utility-scale solar installations across Spain and Italy create emerging demand for efflorescence removal from panel mounting frames and concrete ballast systems. Aging photovoltaic infrastructure requires maintenance chemical protocols not originally specified in installation contracts. Rome and Florence heritage conservation programs sustain artisan-scale restoration formulation demand.
Efflorescence Remover Market Competitive Landscape
The competitive structure tilts toward specialty chemical formulators with heritage masonry expertise. Market concentration remains moderate, with regional formulation specialists coexisting alongside diversified coatings conglomerates. Two strategic archetypes dominate: conservation-grade specialists serving heritage procurement channels, and mass-market suppliers leveraging retail distribution scale. Competitive moves center on formulation reformulation for regulatory compliance and direct-to-contractor digital channel expansion.
Among conservation-grade specialists, Foundation Armor anchors premium positioning through direct-to-contractor technical channels, while Rust-Oleum exemplifies mass-market scale through brand recognition in residential renovation segments. Southeast Softwash occupies a distinct position integrating chemical delivery systems with soft-wash equipment bundles for commercial exterior cleaning operators. These three represent the primary competitive vectors: heritage technical specialization, retail brand leverage, and equipment-chemical bundling.
| Leading Market Players |
|---|
| RadonSeal |
| Foundation Armor |
| Rust-Oleum |
| City Clean Inc. |
| Omni |
| Chemique |
| PROTECTiT |
| Southeast Softwash |
| Aqua Mix |
| Others |
Value Network & Pricing Analysis
Phosphate rock benchmark volatility from Moroccan and Chinese processing clusters cascades through acid-based formulation tiers into premium-mid-economy pricing differentiation across German heritage restoration and US commercial property maintenance channels.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and application intensity. Heritage conservation programs in Germany absorb premium pricing for REACH-compliant buffered organic acid blends, while US residential renovators gravitate toward economy-tier spray products through mass retail. Price differentiation stems from formulation chemistry complexity and regulatory compliance burden rather than brand premium alone. Cost compression in standard-tier chemical solutions is intensifying as phosphoric acid feedstock volatility squeezes mid-market producers.
Supply Chain Analysis
Freight cost escalation on bulk liquid chemical shipments from German and Dutch manufacturing hubs to UK and Italian distribution points compresses margins for low-volume specialty formulators. Raw material sourcing draws from Chinese phosphate rock processing, Moroccan acid production, and domestic European surfactant synthesis. Single-source vulnerability concentrates in phosphoric acid derivatives where Chinese export licensing creates intermittent supply constraints. Distribution runs through regional construction supply houses for contractor pickup, though direct digital procurement erodes wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The efflorescence remover market functions as a stable compounder anchored by regulatory-mandated formulation replacement cycles across European heritage conservation and North American commercial property portfolios.
For Market Incumbents: Hedge phosphoric acid supply exposure through backward integration into alternative chelating agent R&D or long-term offtake agreements with Moroccan phosphate processors. Defend premium positioning in German heritage channels by accelerating EU Ecolabel certification timelines ahead of REACH Annex XVII expansion. Channel control through direct-to-contractor digital platforms reduces distributor dependency.
For New Entrants and Emerging Players: Enter via photovoltaic substrate cleaning applications in Spain and Italy where utility-scale solar aging creates unmet maintenance chemical demand without entrenched incumbent relationships. Target soft-wash equipment bundling partnerships with commercial exterior cleaning operators seeking integrated chemical delivery systems. White-space exists in refill-and-dilution concentrate formats for municipal green procurement mandates.
For Investors and Strategic Acquirers: Asymmetric upside sits with conservation-grade specialists possessing validated REACH authorization dossiers and established heritage procurement relationships. Long-term viability hinges on regulatory compliance capability rather than manufacturing scale alone. Acquisition candidates should demonstrate formulated product portfolios with multi-jurisdiction substance registrations. Monitor EPA VOC rulemaking expansion into additional architectural coating categories as inflection signal for accelerated replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Reformulation | Buffered organic acid blends satisfy ECHA authorization timelines while preserving substrate compatibility for heritage contractors. |
| Direct-to-Contractor Digital Channel Expansion | Manufacturer-direct procurement bypasses wholesale markups and enables subscription replenishment for recurring maintenance contractors. |
| Soft-Wash Equipment Bundling | Integrated chemical delivery systems with low-pressure washing rigs capture commercial exterior cleaning contract value. |
| Refill-and-Dilution Concentrate Development | Concentrated kits reduce shipping costs and plastic waste, aligning with BREEAM procurement specifications. |
| Photovoltaic Substrate Cleaning Application | Concrete ballast and mounting frame maintenance creates incremental demand from aging utility-scale solar installations. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with specialty chemical plant managers, heritage conservation procurement officers, commercial property facility directors, and soft-wash equipment distributors with secondary validation against ECHA substance registration databases, EPA VOC regulatory filings, and construction chemical trade association reports. Bottom-up volume estimates from formulation chemistry segments were triangulated against top-down demand projections from regional building stock maintenance expenditure data.
Segment-weighting approaches applied differential growth assumptions across formulation chemistry, application intensity, and distribution channel dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical replacement cycles against regulatory compliance deadline schedules. Industry-specific inputs included REACH authorization timeline probabilities and heritage building conservation program budget allocations.
Inputs from ECHA registration databases and EPA regulatory dockets were available through the study window; gaps in proprietary formulation performance testing data introduce uncertainty bands around biodegradable efficacy projections. Forecasts reflect assumptions about regulatory enforcement intensity and substitution technology maturation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Industrial Cleaning Chemicals Market
Cleaning Chemicals
Industrial Cleaners Market
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Water-Saving Cleaning Chemical Systems for Professional Use Market
Cleaning Chemicals
Cleaning Fluids Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Europe Industrial and Institutional Cleaning Chemicals Market
Cleaning Chemicals
Bio-Enzymatic Odor Control Chemicals for Restrooms and Waste Areas Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Instrument Cleaners and Detergents Market
Cleaning Chemicals
High-Performance Descaling and Deliming Chemicals for HoReCa Equipment Market
Cleaning Chemicals
Mask Reticle Cleaning Agent Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Limestone Cleaner Market
Cleaning Chemicals
Acid Coil Cleaner Market