
 Asia-Pacific Stand-Up Paddleboard Market | 2026-2036
Asia-Pacific Stand-Up Paddleboard Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Stand-Up Paddleboard Market Outlook
REACH compliance is rebalancing material sourcing costs for epoxy and fiberglass suppliers entering European-export channels. Red Paddle Co. leverages inflatable technology leadership to dominate rental-service procurement across Southeast Asian resorts. Starboard anchors its position through sustainable manufacturing investments that align with Australia's marine conservation mandates. Naish International specializes in high-performance hard boards for competitive segments across Japan and South Korea.
A stand-up paddleboard is a buoyant watercraft propelled by a single-bladed paddle, typically constructed from epoxy resin over fiberglass, inflatable PVC drop-stitch, or carbon fiber composites, with lengths ranging from 2.7 to 4.3 meters and volume capacities of 150–300 liters for load-bearing stability. The primary commercial purpose spans leisure recreation, fitness training, and competitive racing across coastal and inland waterways. Inflatable boards command the largest volume share due to portability advantages for rental services and airline travel, while hard boards retain premium positioning in competition and touring applications where rigidity translates to speed performance. Yoga and fitness applications represent an emerging demand cluster as waterfront studios in Indonesia and Vietnam integrate paddleboard classes into wellness programming.
Australia's ACCC product safety standards and China's SAMR quality certification requirements shape market access protocols for imported boards, with dual compliance becoming a baseline cost for regional distributors. Japan's consumer safety regulations under METI jurisdiction extend to paddle and leash attachment standards, adding testing layers for new entrants. Stakeholders must monitor evolving marine park access restrictions and plastic-content regulations as coastal governance tightens across the region's high-traffic waterways.
Market Dynamics
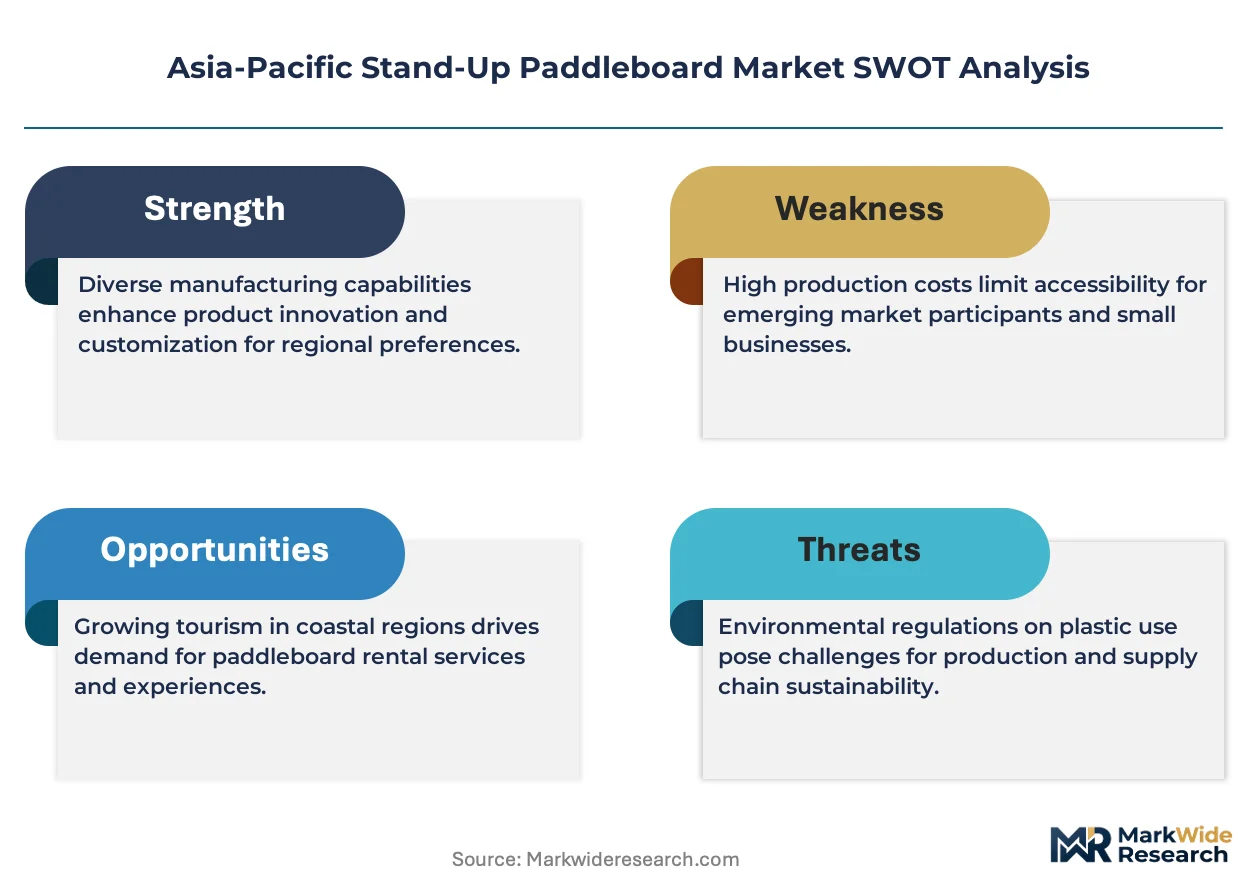
Coastal tourism infrastructure expansion across Southeast Asia is compressing equipment replacement cycles and reshaping procurement relationships between resort operators and board manufacturers. Thailand's marine national park licensing reforms and Australia's marine conservation zoning create divergent compliance pathways that segment the supplier base by certification capability.
Growth Catalysts
- Eco-tourism infrastructure:Resort operators in Phuket and Bali are converting beachfront inventory to paddleboard rental fleets, creating sustained equipment demand with 18-24 month refresh cycles.
- China's GB standards:Mandatory watercraft safety certification under SAMR jurisdiction is professionalizing manufacturing quality and filtering informal suppliers from export channels.
- Carbon fiber drop-stitch:Advanced inflatable construction is narrowing the rigidity gap with hard boards, expanding competitive racing adoption in Japan and South Korea.
Market Restraints
- Epoxy resin cost volatility:Hard board manufacturers face input price pressure from petrochemical supply fluctuations, compressing margins on premium touring models.
- Single-region supply concentration:Drop-stitch PVC fabric production clusters in China's Pearl River Delta, creating vulnerability to regional logistics disruptions.
- Leash attachment point failures:Inadequate reinforcement standards in budget inflatable boards generate liability exposure and reputational risk for rental operators.
Strategic Opportunities
- Vietnam's central coast:Da Nang-Hoi An tourism corridor remains underpenetrated for branded equipment distribution, offering first-mover positioning ahead of infrastructure completion.
- Yoga studio integration:Waterfront wellness programming in Indonesia is creating equipment-as-a-service demand with specialized deck pad and stability specifications.
- Australia's marine park access permits:Conservation-compliant manufacturing credentials are becoming a procurement filter for national park concessionaires, rewarding sustainable material investments.
Industry Challenges
- Shaper technician scarcity:Hard board production requires skilled laminators with epoxy-fiberglass expertise, a talent pool concentrated in Australia's Gold Coast and Japan's Shizuoka Prefecture.
- Dual certification timelines:Manufacturers targeting both Australia's ACCC product safety standards and China's SAMR quality requirements face 8-14 month testing sequences before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Stand-Up Paddleboard Market |
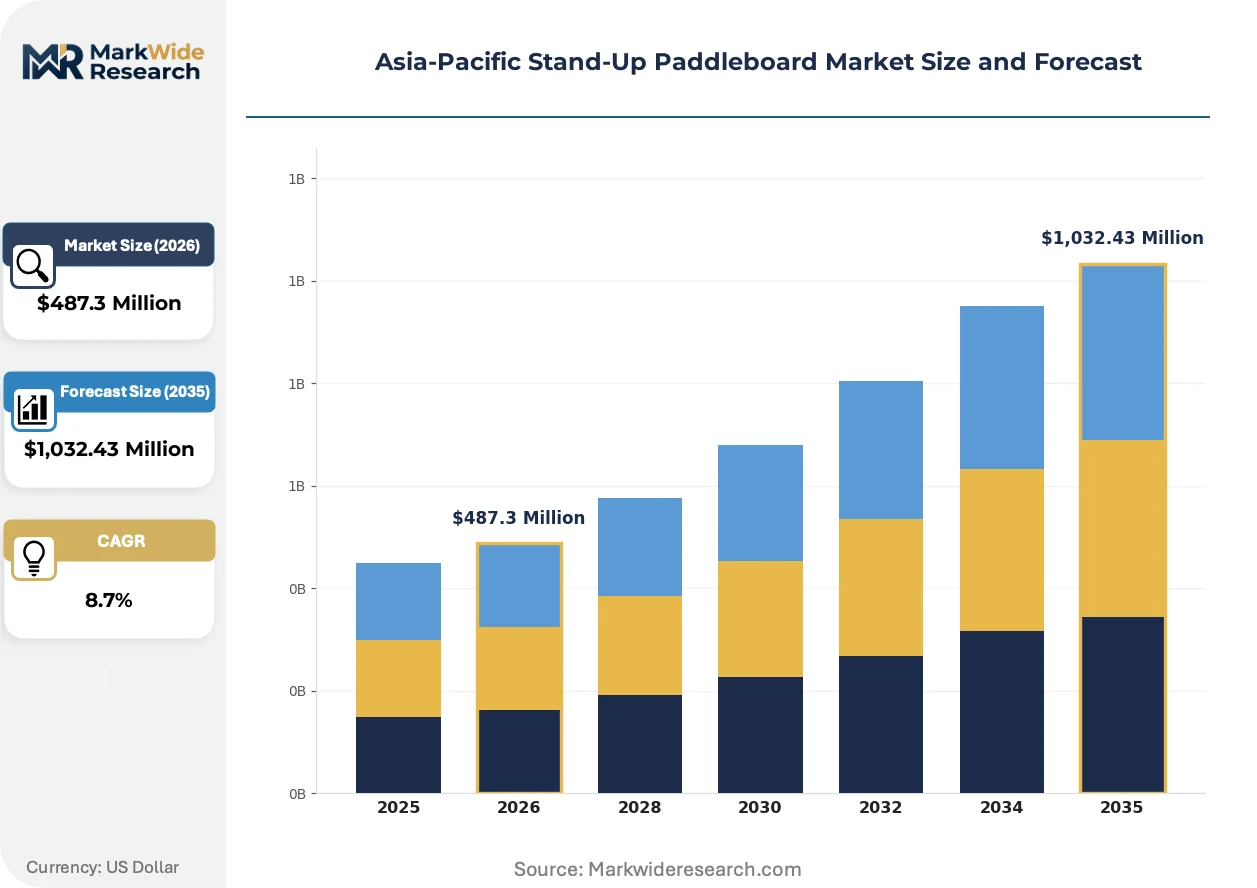
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable, Hard Board, Racing, All-Around End User: Recreational, Professional, Rental Services, Fitness Material: Plastic, Fiberglass, Epoxy, Wood Application: Leisure, Competition, Touring, Yoga |
| Companies Covered | Red Paddle Co., Tahe Outdoors, Naish International, Starboard, SUP ATX, Aqua Marina, Huarui Plastics, Lightboardcorp, SurfTech, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Stand-Up Paddleboard Market Strategic Shifts
Material science convergence and regulatory fragmentation are simultaneously elevating performance specifications and compliance complexity across the Asia-Pacific supply base. Three developments are restructuring competitive positioning.
Heat-welded seam technology is unifying inflatable board construction by eliminating glue-based assembly points that degrade in tropical UV exposure. Resort procurement teams in Thailand and Malaysia are specifying welded construction for fleet durability, compressing supplier differentiation around seam integrity rather than brand heritage. This technology is unifying quality expectations across price tiers, forcing mid-market manufacturers to upgrade production lines or exit the rental channel.
Australia's marine conservation mandates are tightening plastic-content thresholds for equipment used in protected waterways. The industrial consequence is a material substitution wave toward bio-based epoxy resins and recycled core foams. Hard board manufacturers serving Australia's national park concessionaires are reformulating layup schedules to meet these specifications, while inflatable suppliers face greater technical barriers in replacing PVC drop-stitch with thermoplastic alternatives.
Rental operators are consolidating procurement through direct manufacturer relationships, bypassing traditional surf shop distribution. Boutique resorts in Indonesia and Vietnam are negotiating volume commitments with board makers for seasonal fleet refresh, replacing transactional wholesale purchasing. This pattern is most visible in Bali's Canggu-Seminyak corridor, where hospitality groups are establishing preferred supplier status with inflatable specialists for standardized equipment across multiple properties.
Asia-Pacific Stand-Up Paddleboard Market Segmentation
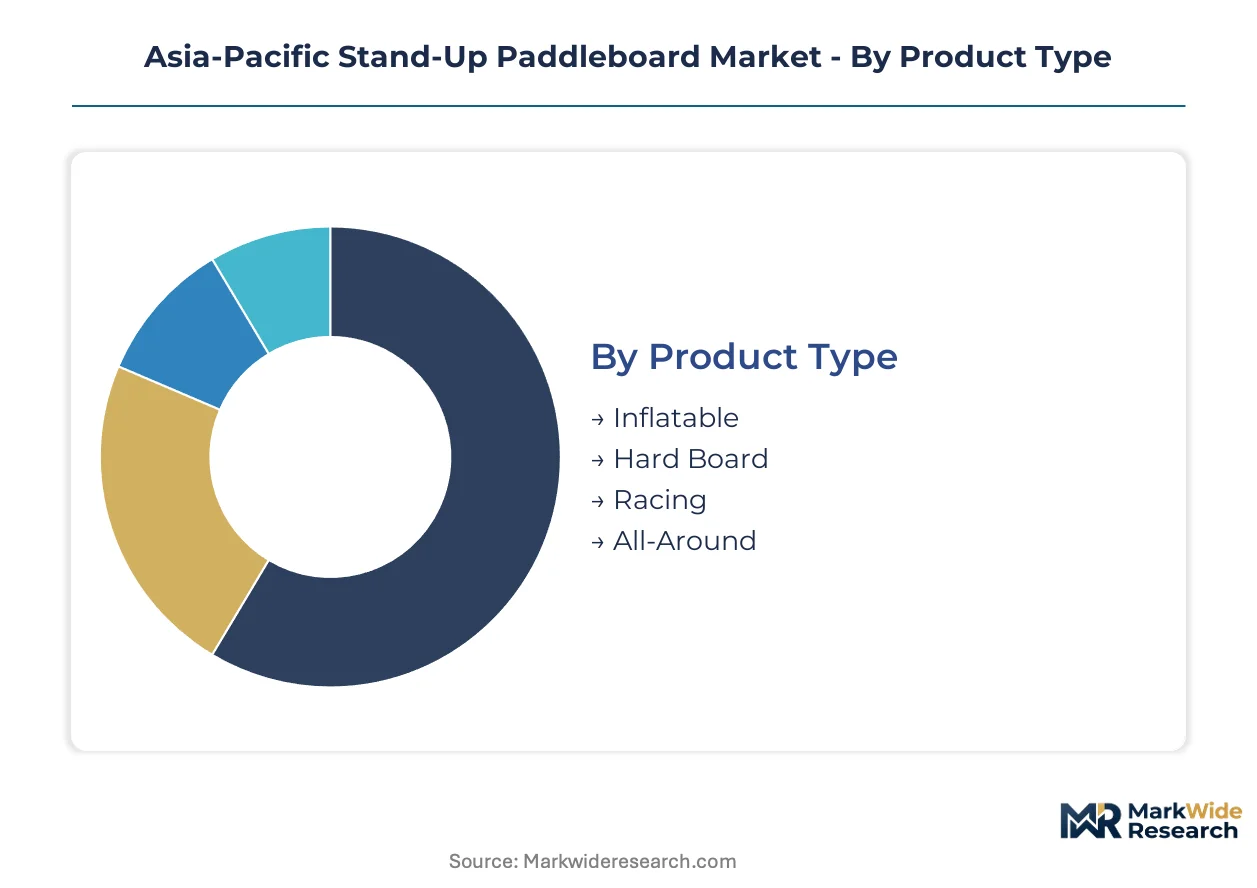
Material specifications and construction methods segment the Asia-Pacific stand-up paddleboard market into distinct procurement tiers. Resort operators, competitive athletes, and recreational users each prioritize different performance characteristics that reshape manufacturing priorities across the region.
Product Type:
Construction technology determines portability, rigidity, and price positioning across the regional supply base.
- Inflatable:Drop-stitch PVC construction with heat-welded seams dominates rental fleet procurement in Thailand's Phuket and Indonesia's Bali corridors. Portability advantages compress logistics costs for airline travelers and resort operators with seasonal storage constraints.
- Hard Board:Epoxy-fiberglass composite layups deliver superior rigidity for speed-focused applications. Australia's Gold Coast surf schools and Japan's competitive racing circuits sustain demand despite higher price points and transport complexity.
- Racing:Narrow profiles with displacement hulls optimize glide efficiency over distance. Carbon fiber construction penetrates South Korea's competitive circuit and Japan's domestic marathon events where federation specifications mandate minimum board dimensions.
- All-Around:Hybrid geometries balance stability with moderate glide performance for novice users. Vietnam's emerging Da Nang-Hoi An tourism corridor shows concentrated uptake as first-time rental demand expands.
Inflatable leads on scale; racing leads on momentum.
End User:
Procurement volume and replacement cycles diverge sharply across customer categories.
- Recreational:Individual ownership concentrates in Australia's coastal suburbs and Japan's lake districts. Weekend usage patterns drive demand for durable mid-range constructions with versatile performance envelopes.
- Professional:Athletes and instructors require equipment meeting federation specifications for competition eligibility. Sponsorship relationships with manufacturers like Starboard and Naish International lock in brand loyalty across Japan and South Korea.
- Rental Services:Hospitality operators in Phuket and Bali negotiate fleet pricing with 18-24 month refresh cycles. Standardized equipment reduces maintenance training costs and simplifies damage liability protocols.
- Fitness:Waterfront yoga studios in Indonesia and Vietnam integrate paddleboard classes into wellness programming. Specialized deck pads and enhanced stability specifications create equipment-as-a-service demand distinct from recreational procurement.
Rental services lead on scale; fitness leads on momentum.
Material:
Raw material selection shapes compliance pathways and cost structures for manufacturers targeting export channels.
- Plastic:Budget PVC constructions serve Southeast Asian price-sensitive segments. Australia's ACCC product safety standards and China's SAMR certification requirements filter informal suppliers from formal distribution.
- Fiberglass:Epoxy resin layups over fiberglass cloth remain the standard for hard board production. Shaper technician scarcity in Australia's Gold Coast and Japan's Shizuoka Prefecture constrains output expansion.
- Epoxy:Bio-based formulations respond to Australia's marine conservation mandates tightening plastic-content thresholds in protected waterways. Reformulation costs compress margins for manufacturers serving national park concessionaires.
- Wood:Veneer-over-foam constructions appeal to premium aesthetic positioning in Japan's domestic market. Limited production scale restricts geographic penetration beyond artisanal manufacturing clusters.
Fiberglass leads on scale; epoxy leads on momentum.
Application:
Usage context determines performance specifications and distribution channel selection.
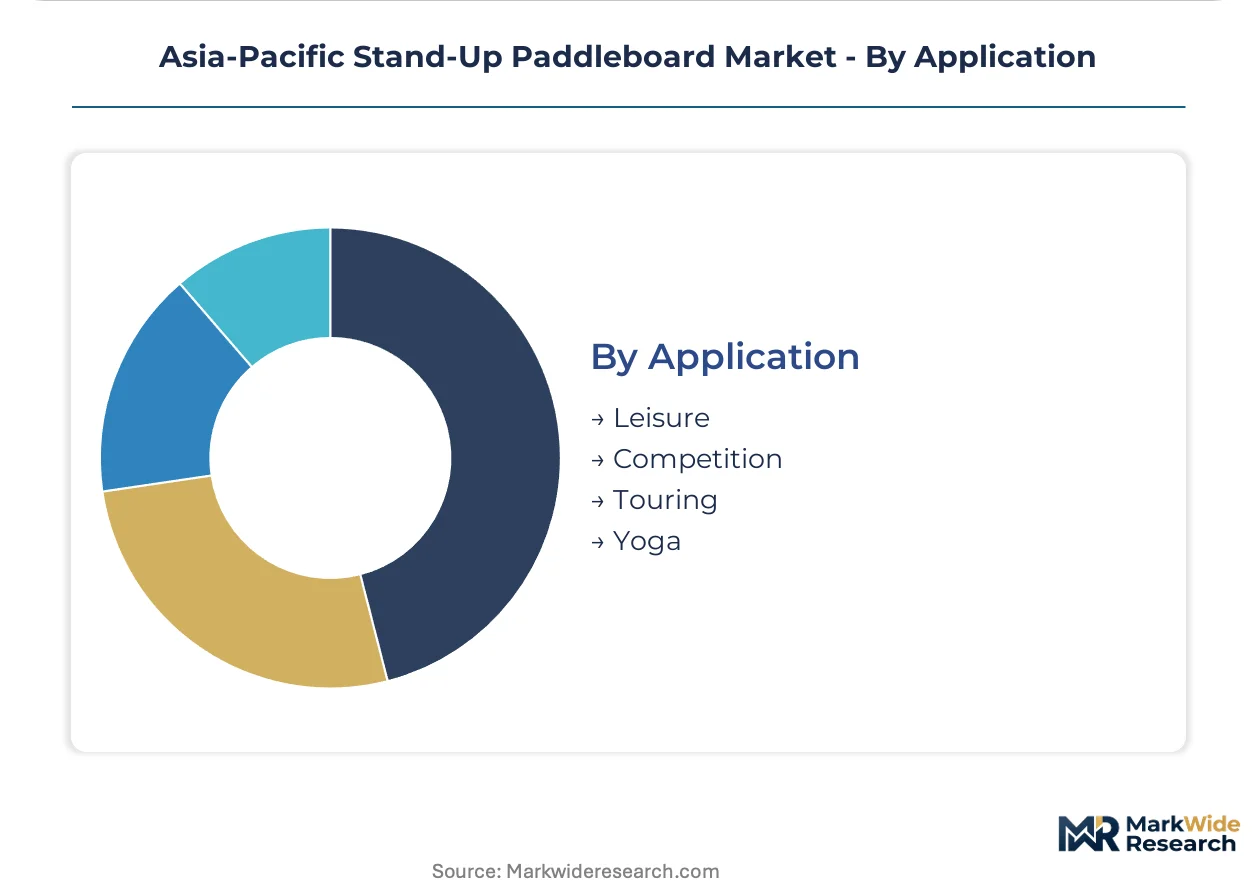
- Leisure:Casual flatwater paddling dominates volume across Southeast Asian resort destinations. Equipment prioritizes stability and durability over speed metrics.
- Competition:Federation-sanctioned events in Japan and South Korea enforce strict board dimension and construction standards. Carbon fiber penetration is climbing the fastest as performance thresholds escalate.
- Touring:Multi-day expedition use demands load-bearing capacity and tracking efficiency. Australia's Tasmanian coastline and New Zealand's fjord systems sustain niche demand for specialized displacement hulls.
- Yoga:Specialized deck pads and enhanced width specifications accommodate static balance requirements. Indonesia's Canggu-Seminyak corridor shows concentrated studio integration with equipment-as-a-service procurement models.
Leisure leads on scale; yoga leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stand-up paddleboarding originated in Hawaii during the 1940s before spreading to coastal Australia and Japan by the early 2000s. The Asia-Pacific region now hosts distinct national markets shaped by local tourism infrastructure, safety regulations, and manufacturing capabilities.
Australia
Gold Coast surf schools and Tasmanian expedition operators drive equipment demand across recreational and touring segments. The Australian Competition and Consumer Commission enforces product safety standards for leash attachment points and load-bearing capacity. Sydney's Northern Beaches cluster hosts specialized laminators serving premium hard board production for competitive racing circuits.
China
Drop-stitch PVC fabric production concentrates in the Pearl River Delta, supplying inflatable board manufacturers across Southeast Asian resort markets. The State Administration for Market Regulation mandates GB standards certification for watercraft safety, filtering informal suppliers from export channels. Zhuhai and Shenzhen house integrated production facilities serving both domestic fitness studios and international rental operators.
Thailand
Phuket's marine national park licensing reforms are compressing equipment replacement cycles for coastal tourism operators. The Department of National Parks enforces conservation zoning that restricts motorized craft, channeling visitor traffic toward paddleboard-accessible waterways. Krabi and Koh Samui resort corridors negotiate direct procurement relationships with inflatable specialists for standardized fleet deployment.
Japan
Lake districts in Nagano and competitive racing circuits in Shizuoka Prefecture sustain dual demand for recreational and high-performance equipment. The Ministry of Economy, Trade and Industry oversees consumer safety regulations extending to paddle and leash attachment standards. Tokyo Bay waterfront studios are integrating paddleboard yoga classes into corporate wellness programming.
Indonesia
Bali's Canggu-Seminyak hospitality corridor is consolidating procurement through direct manufacturer relationships for seasonal fleet refresh. The Ministry of Tourism coordinates marine park access permits that favor conservation-compliant equipment in protected zones. Lombok and the Gili Islands show concentrated rental operator expansion ahead of infrastructure completion.
Asia-Pacific Stand-Up Paddleboard Market Competitive Environment
The competitive structure tilts toward technology-differentiated specialists rather than scale-driven consolidators. Inflatable construction expertise and sustainable material credentials define tier placement across resort procurement channels. Three archetypes dominate: heat-welded seam specialists serving tropical rental markets, carbon fiber racing board fabricators, and bio-resin formulators meeting Australia's marine conservation mandates. Strategic moves center on direct hospitality partnerships and certification stacking for multi-jurisdiction compliance.
Among UK-based inflatable specialists, Red Paddle Co. occupies a position exemplifying heat-welded construction leadership for Southeast Asian resort procurement. Naish International and Starboard represent the performance-tier and sustainability-tier vectors respectively, with the former anchoring competitive racing positioning across Japan and South Korea, and the latter exemplifying conservation-compliant manufacturing credentials for Australia's national park concessionaires.
| Leading Market Players |
|---|
| Red Paddle Co. |
| Tahe Outdoors |
| Naish International |
| Starboard |
| SUP ATX |
| Aqua Marina |
| Huarui Plastics |
| Lightboardcorp |
| SurfTech |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin spot price volatility cascades through Asia-Pacific paddleboard manufacturing, compressing margins on premium hard boards while inflating procurement premiums for certified drop-stitch PVC in rental fleet contracts. China's SAMR certification requirements and Australia's ACCC safety standards create compliance-cost tiers that segment supplier pricing power by export-channel access.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and volume scale. Premium tiers command positioning through Australia's marine conservation compliance and Japan's METI safety endorsements, while economy segments serve Thailand's unlicensed beach vendors. Cost compression in mid-range inflatable construction is intensifying because heat-welded seam technology has unified quality expectations. Rental operators in Bali and Phuket exhibit lowest price sensitivity due to fleet-standardization imperatives, whereas individual recreational buyers in Vietnam's emerging corridors drive hardest bargain hunting.
Supply Chain Analysis
Certification gating through China's GB standards and Australia's ACCC protocols filters informal suppliers from formal distribution channels. Drop-stitch PVC fabric production clusters in China's Pearl River Delta, with epoxy resin formulation concentrated in Japan's Shizuoka Prefecture and fiberglass layup anchored in Australia's Gold Coast. Raw material flows draw from petrochemical feedstocks, carbon fiber imports, and bio-based resin experiments. Single-source vulnerability runs through China's Pearl River Delta fabric mills. Distribution feeds from manufacturer-direct relationships with hospitality groups, bypassing traditional surf shop wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific stand-up paddleboard demand compounds steadily through coastal tourism infrastructure expansion across Thailand, Indonesia, and Vietnam. Resort operator procurement standardization creates predictable replacement-cycle revenue for qualified suppliers.
For Market Incumbents: Anchor market position through heat-welded seam technology leadership and SAMR-ACCC dual certification stacking. Threats from carbon fiber drop-stitch disruptors in Japan's racing segment demand R&D investment in rigidity-performance parity. Backward integration into drop-stitch fabric production in Zhuhai-Shenzhen corridor secures supply continuity against Pearl River Delta logistics disruptions. For New Entrants and Emerging Players: Capture Vietnam's Da Nang-Hoi An tourism corridor ahead of branded equipment distribution saturation. Fitness-as-a-service procurement through waterfront yoga studios in Indonesia offers penetrable white-space with specialized deck pad specifications. Go-to-market through direct hospitality procurement relationships bypasses entrenched surf shop channel control. For Investors and Strategic Acquirers: Asymmetric upside sits with heat-welded inflatable specialists serving tropical rental markets with 18-24 month refresh cycles. Long-term viability rests on conservation-compliance credentialing as Australia's marine park access permits tighten. Acquisition target archetype: mid-cap manufacturers with SAMR certification and established resort operator relationships. Signal to watch: marine park concessionaire procurement filters shifting to bio-resin compliance mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Welded Seam Technology Adoption | Eliminates glue degradation in tropical UV exposure, unifying quality expectations across Thailand's rental fleets. |
| Bio-Based Epoxy Resin Reformulation | Meets Australia's marine conservation plastic-content thresholds for national park concessionaires. |
| Direct Hospitality Procurement Relationships | Bypasses surf shop distribution, securing seasonal fleet refresh contracts across Bali's Canggu-Seminyak corridor. |
| Dual Certification Investment (SAMR-ACCC) | Unlocks export-channel access to China's domestic fitness studios and Australia's premium recreational segments. |
| Carbon Fiber Drop-Stitch Development | Narrows rigidity gap with hard boards, expanding competitive racing adoption in Japan and South Korea. |
Study Parameters
Coverage spans Australia, China, Thailand, Japan, and Indonesia, with primary inputs from each market's stakeholder base. The analysis combines primary interviews with resort procurement managers, inflatable board manufacturing technicians, marine park licensing officers, and epoxy resin procurement leads with secondary validation from customs trade data, SAMR certification registries, ACCC product safety filings, and coastal tourism infrastructure investment disclosures. Bottom-up equipment shipment tallies triangulate against top-down tourism expenditure models.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon. Segmentation dimensions modeled include construction technology, end-user category, raw material composition, and application context, with regional regulatory cluster as an industry-specific overlay. CAGRs derive from equipment replacement-cycle analysis and tourism infrastructure pipeline assessment. Forecast inputs incorporate marine park access permit expansion timelines and heat-welded seam technology adoption curves.
Underlying measurement precision varies by segment; rental fleet procurement data carries tighter precision than individual recreational ownership estimates. Forecasts reflect assumptions about tourism infrastructure completion schedules and certification requirement stability. A model refresh is warranted upon material change in Australia's marine conservation mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Spain Horse Riding Equipment Market
Sports Equipment
Football Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
Bicycle Tire Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Ladderball Market
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Running Gear Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Surfboard Market
Sports Equipment
Global Basketball Shoes Market