
 Peppermint Extract Market | 2026-2036
Peppermint Extract Market Size, Share, and Industry Trends Forecast 2026-2036
Peppermint Extract Market Insights
Supercritical CO2 extraction is reshaping how peppermint oil is isolated from Mentha piperita biomass, replacing steam distillation in premium applications. Givaudan leverages vertical integration from raw botanical sourcing to finished flavor formulations. Symrise AG anchors European supply through specialized extraction facilities in Germany. Young Living Essential Oils LLC dominates direct-to-consumer channels with controlled farm-to-bottle traceability.
Peppermint extract denotes a concentrated preparation derived from Mentha piperita leaves, typically containing 50-80% menthol by volume depending on extraction method, and serves primarily as a flavoring, fragrance, and therapeutic active across food, cosmetic, and pharmaceutical systems. Essential oil commands the highest value per kilogram among product type segments, while flavoring agent generates the largest absolute volume throughput. Pharmaceutical applications are expanding fastest due to menthol's established efficacy in gastrointestinal and respiratory formulations.
FDA food additive regulations and EFSA botanical safety assessments govern permissible concentrations in ingestible and topical products, with REACH compliance mandatory for European cosmetic and fragrance applications. USDA organic certification and ISO 9001 quality management standards increasingly determine market access for premium extract suppliers. Stakeholders must monitor evolving novel food designation debates in Europe and North America that could reclassify concentrated botanical extracts across regulatory categories.
Market Dynamics
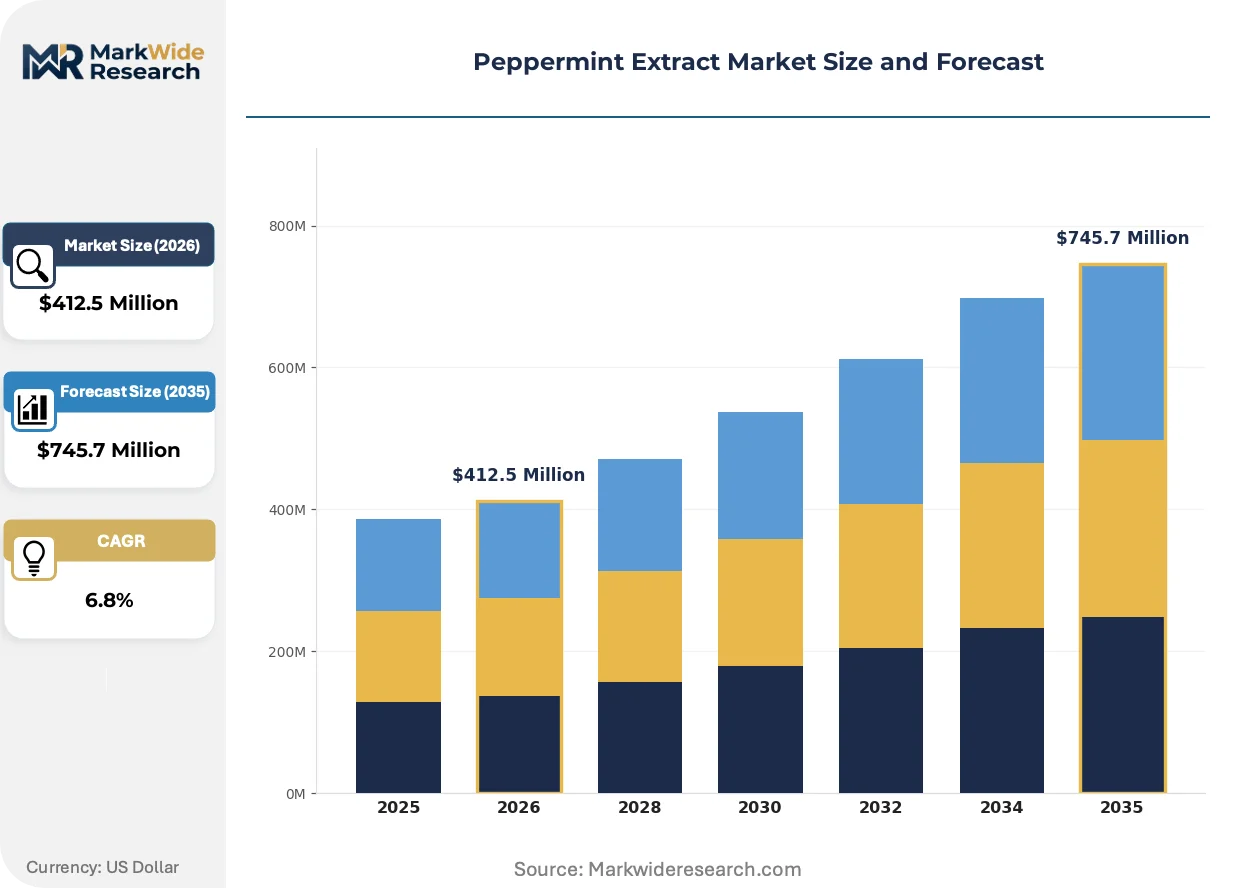
Supercritical CO2 extraction technology is compressing the cost premium over steam distillation while FDA and EFSA tighten purity thresholds for botanical extracts used in ingestible products.
Growth Catalysts
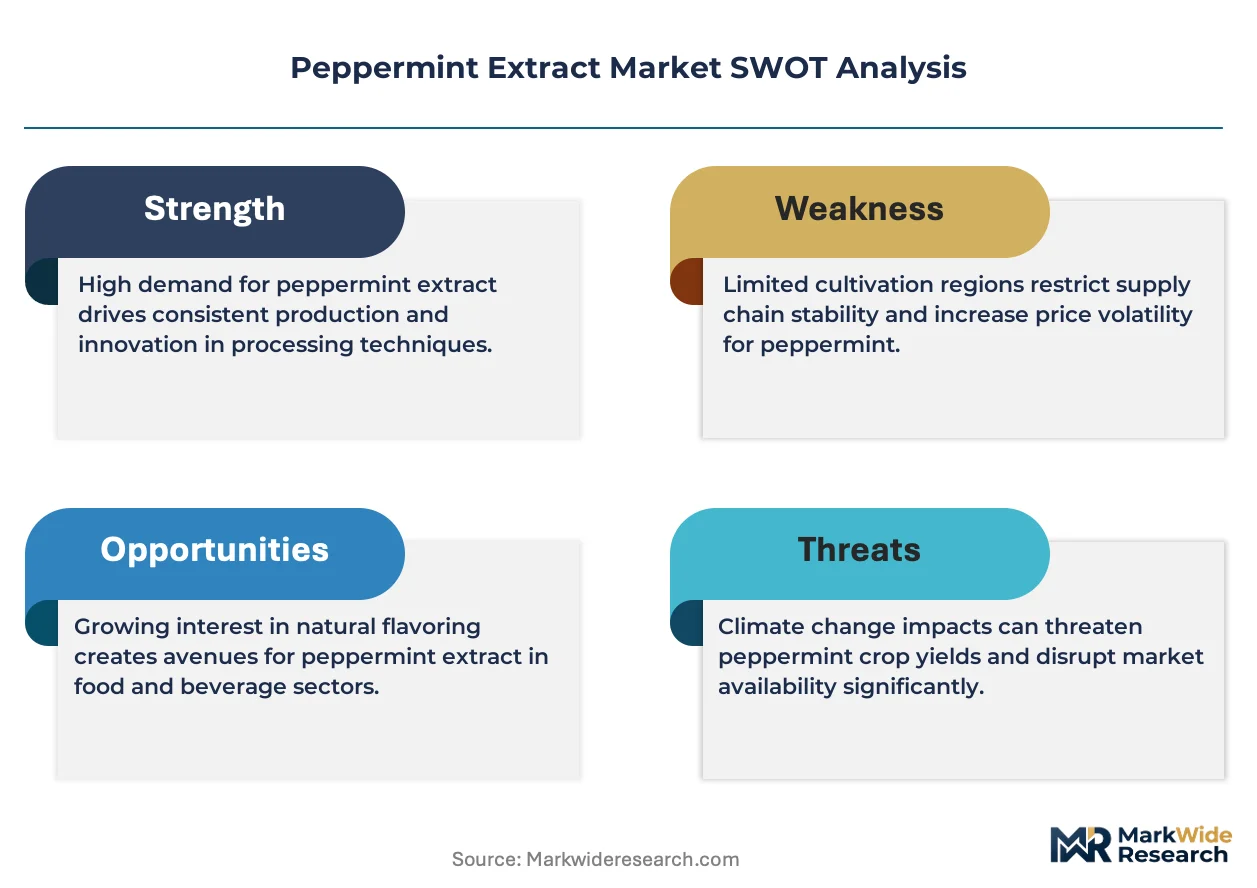
- Natural flavoring mandates:Beverage manufacturers in Germany are reformulating with peppermint extract to replace synthetic menthol under EFSA clean-label guidance.
- Pharmaceutical efficacy validation:Menthol's gastrointestinal and respiratory therapeutic applications are expanding formulation demand across CDSCO-regulated facilities in India.
- Extraction technology maturation:Supercritical CO2 systems are achieving yield parity with steam distillation at commercial scale in United States processing plants.
Market Restraints
- Raw biomass cost volatility:Mentha piperita leaf prices fluctuate with climate variability in Pacific Northwest growing regions.
- Regulatory friction:REACH compliance costs for European cosmetic applications disproportionately burden small-batch extract producers.
- Substitution pressure:Synthetic menthol from petrochemical feedstocks undercuts natural extract pricing in fragrance applications.
Strategic Opportunities
- Underpenetrated therapeutic segments:Topical analgesic formulations in Japan offer expansion potential beyond traditional food and fragrance uses.
- Regulatory tailwind:USDA organic certification is unlocking premium pricing tiers in direct-to-consumer channels.
- Channel innovation:Farm-to-bottle traceability platforms are capturing value from transparency-seeking buyers in wellness segments.
Industry Challenges
- Specialized extraction talent scarcity:Supercritical CO2 system operation requires chemical engineering expertise that outpaces vocational training output.
- Certification timeline compression:ISO 9001 and organic dual-certification cycles extend 14-18 months, delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peppermint Extract Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $745.7 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavoring Agent, Essential Oil, Herbal Extract, Food Supplement Application: Beverages, Confectionery, Personal Care, Pharmaceuticals Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales End User: Food Manufacturers, Cosmetics Companies, Pharmacies, Wellness Centers |
| Companies Covered | Synthite Industries Ltd., Aromaaz International, Mondelez, Givaudan, Biolandes, doTERRA, The Lebermuth Company, Symrise AG, Young Living Essential Oils LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peppermint Extract Market Trends and Innovations
Digital process control and spectroscopic quality verification are converging with regulatory data requirements to reshape how peppermint extract producers demonstrate compliance and consistency.
Supercritical CO2 extraction with inline near-infrared spectroscopy is digitizing real-time menthol concentration monitoring during processing. Pharmaceutical manufacturers in Germany are adopting these systems fastest, requiring batch records that satisfy EMA documentation standards. This integration is digitizing quality assurance workflows while compressing release cycle times from days to hours.
EFSA novel food designation debates are reclassifying concentrated botanical extracts across regulatory categories in Europe. The industrial consequence is reformulation pressure on legacy products that predate 2018 guidance. Ingestible applications face the steepest compliance burden, with manufacturers submitting safety dossiers for extracts previously treated as traditional food ingredients.
Direct procurement from controlled-origin farms is displacing spot-market leaf purchasing among premium extract buyers. Flavor houses in the United States are establishing captive Mentha piperita cultivation to secure supply chains against climate volatility. This behavioral shift concentrates most visibly in therapeutic-grade segments where traceability commands price premiums.
Peppermint Extract Market Segmentation
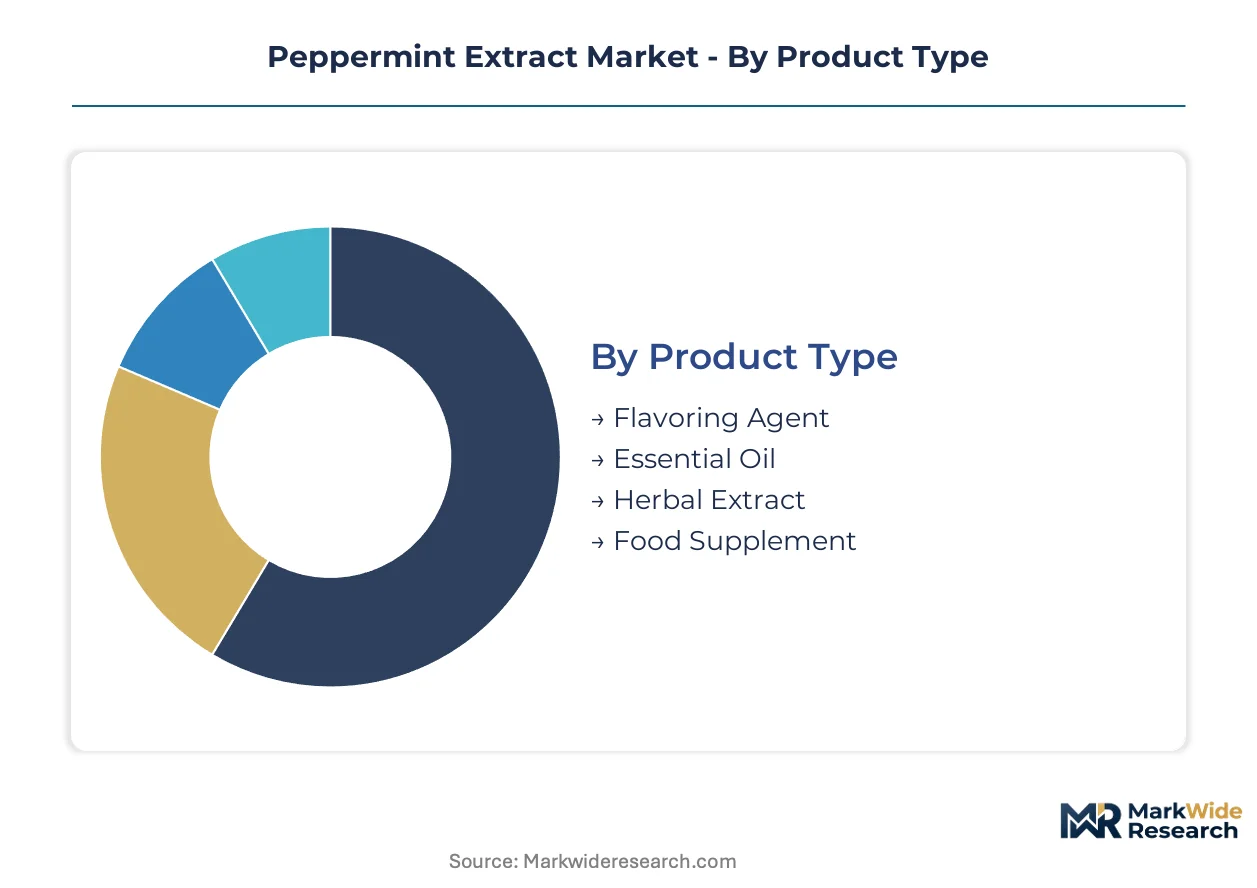
Peppermint extract segmentation reveals how extraction grade determines application suitability and margin capture. Technical specifications vary sharply between flavor-grade and therapeutic-grade products, creating distinct procurement behaviors across buyer categories.
Product Type:
Cycle times compress from months for essential oil spot contracts to years for supplement regulatory approvals, reshaping working capital requirements across the product matrix.
- Essential Oil:Concentrated volatile oil containing 50-80% menthol by volume, isolated through steam distillation or supercritical CO2 extraction. Demand concentrates in Germany's pharmaceutical compounding facilities where EMA documentation standards require batch-level terpene profiling. Purity thresholds for therapeutic applications command price premiums over fragrance-grade material.
- Flavoring Agent:Standardized menthol solutions diluted for food-safe concentrations, typically 2-10% active content. United States beverage manufacturers are expanding procurement volumes under FDA clean-label reformulation mandates. Reformulation timelines for legacy synthetic menthol products extend 18-24 months, locking in near-term demand.
- Herbal Extract:Water-ethanol preparations retaining broader phytochemical profiles beyond isolated menthol. Wellness channels in India favor these preparations for Ayurvedic formulation compatibility.
- Food Supplement:Capsule and tablet formats requiring novel food or dietary ingredient status depending on jurisdiction. CDSCO-regulated facilities in India are scaling encapsulation capacity for export markets.
Essential oil dominates installed base. Food supplement is where expansion concentrates.
Application:
Margin structures diverge sharply between commodity flavoring contracts and pharmaceutical formulation partnerships, with the latter requiring dedicated quality management systems.
- Pharmaceuticals:Respiratory and gastrointestinal formulations leveraging menthol's established therapeutic mechanisms. Germany's EMA-compliant manufacturing facilities are validating supercritical CO2 extracts for API-grade applications. Regulatory dossier requirements for novel therapeutic indications extend development cycles.
- Confectionery:Hard candy and chewing gum applications demanding heat-stable flavor release profiles. United States contract manufacturers are consolidating procurement through flavor house intermediaries to manage volatility in leaf supply.
- Beverages:Functional and flavored drink categories with rapid flavor trend turnover. Clean-label positioning in Germany is accelerating natural extract substitution for synthetic menthol.
- Personal Care:Topical cooling and fragrance applications across skincare and oral hygiene. Synthetic menthol from petrochemical feedstocks maintains cost advantage in mass-market fragrance segments.
Confectionery anchors volume throughput. Pharmaceuticals is climbing the fastest on value per kilogram.
Distribution Channel:
Channel selection correlates directly with batch size requirements and traceability documentation needs, fragmenting procurement patterns across buyer types.
- Direct Sales:Long-term supply agreements with captive cultivation and dedicated extraction capacity. United States flavor houses are deepening backward integration into Mentha piperita farming to secure therapeutic-grade supply chains.
- Specialty Stores:Small-batch therapeutic and aromatherapy segments with premium positioning. Wellness centers in Germany favor these channels for organic-certified product access.
- Online Retail:Direct-to-consumer formats with farm-to-bottle traceability platforms. Young Living's controlled-origin model exemplifies this channel's transparency premium capture.
- Supermarkets:Mass-market food-grade extracts with standardized specifications and price-competitive positioning. Shelf space allocation favors established brands with ISO 9001 certification.
Direct sales lock in the largest contract values. Online retail is gaining share fastest through transparency differentiation.
End User:
End-user technical sophistication determines specification stringency, from pharmaceutical-grade HPLC verification to basic organoleptic approval.
- Food Manufacturers:Beverage and confectionery processors with formulation stability requirements and high-volume procurement. Germany's reformulation mandates under EFSA guidance are accelerating natural extract adoption timelines.
- Cosmetics Companies:Personal care formulators balancing natural positioning with cost targets. REACH compliance costs for European cosmetic applications favor larger batch procurement to amortize testing overhead.
- Pharmacies:Compounding and OTC preparation facilities with therapeutic-grade material requirements. CDSCO-regulated facilities in India are expanding menthol-based respiratory formulation capacity.
- Wellness Centers:Holistic health providers with organic certification and traceability priorities. USDA organic certification unlocks premium pricing tiers in this segment.
Food manufacturers represent the largest absolute demand base. Wellness centers are expanding most quickly on per-customer value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in peppermint extract tilt toward processing economies with established botanical extraction infrastructure, creating distinct import-export patterns across major consuming regions. Germany and the United States maintain processing surpluses while India balances raw leaf exports against value-added extract imports.
United States
Beverage manufacturers in the Pacific Northwest are scaling natural extract procurement under FDA clean-label guidance for synthetic menthol replacement. USDA organic certification requirements are tightening for premium therapeutic-grade products. Processing clusters in Oregon and Washington State are expanding supercritical CO2 extraction capacity for pharmaceutical-grade output.
Germany
EMA-compliant pharmaceutical compounding facilities in Bavaria are validating supercritical CO2 extracts for API-grade menthol applications. REACH compliance costs for cosmetic and fragrance applications favor larger batch procurement from established extract houses. The Eindhoven-adjacent processing corridor is consolidating European supply chain control for therapeutic-grade material.
India
CDSCO-regulated facilities in Maharashtra and Gujarat are expanding encapsulation capacity for menthol-based respiratory and gastrointestinal formulations. FSSAI standards are converging with export market requirements for botanical extract purity. The Indore-Mandsaur belt in Madhya Pradesh remains the dominant Mentha piperita cultivation zone, supplying raw leaf to domestic and international processors.
China
SAMR oversight of food additive classifications is tightening documentation requirements for botanical extracts in ingestible applications. Processing clusters in Jiangsu and Zhejiang provinces are upgrading from basic distillation to supercritical extraction for higher-value export markets. Dual carbon goals are pressuring energy-intensive steam distillation operations toward cleaner extraction technologies.
Japan
PMDA therapeutic validation requirements are slowing market entry for novel peppermint extract applications in topical analgesics. METI industrial policy is supporting domestic extraction technology development to reduce import dependence. The Kansai region's pharmaceutical manufacturing base represents the primary demand concentration for high-purity menthol derivatives.
Peppermint Extract Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers rather than scale concentration alone. Large integrated flavor houses with captive cultivation control premium therapeutic-grade supply chains. Mid-scale specialists dominate contract manufacturing for pharmaceutical and food-grade specifications. Small-batch artisanal producers serve wellness and aromatherapy channels with traceability premiums. Dominant competitive moves include backward integration into controlled-origin farming and technology licensing for supercritical extraction systems.
Among the integrated flavor and fragrance houses, Givaudan and Symrise AG occupy positions spanning raw botanical sourcing through finished formulation. Young Living Essential Oils LLC exemplifies the direct-to-consumer archetype with farm-to-bottle traceability platforms. Synthite Industries Ltd. represents the contract manufacturing tier serving pharmaceutical and food manufacturers with scaled extraction capacity. These three anchors illustrate how competitive positioning diverges across end-use segments and channel strategies.
| Leading Market Players |
|---|
| Synthite Industries Ltd. |
| Aromaaz International |
| Mondelez |
| Givaudan |
| Biolandes |
| doTERRA |
| The Lebermuth Company |
| Symrise AG |
| Young Living Essential Oils LLC |
| Others |
Pricing and Supply Chain Analysis
The Indore-Mandsaur belt in Madhya Pradesh anchors raw Mentha piperita leaf supply, concentrating upstream bargaining power among processors with captive cultivation contracts. Supercritical CO2 extraction capacity expansion in Oregon and Washington State is compressing the technology premium over steam distillation, reshaping margin capture across therapeutic-grade segments.
Pricing Analysis
Steam-to-supercritical technology-generation pricing gaps are narrowing as commercial-scale CO2 systems achieve yield parity in United States processing plants. Pricing stratifies across therapeutic-grade, food-grade, and fragrance-grade tiers, with FDA and EFSA purity thresholds driving certification-based premiums. Cost compression in fragrance-grade material intensifies due to synthetic menthol from petrochemical feedstocks. Food manufacturers show highest price sensitivity, while pharmaceutical compounders accept premiums for batch-level terpene documentation.
Supply Chain Analysis
REACH chemical safety regulations and FDA food additive classifications restrict cross-border flows of concentrated botanical extracts, fragmenting regulatory compliance across jurisdictions. Supply concentrates in India for raw leaf, Germany for pharmaceutical-grade processing, and the United States for flavor and therapeutic extraction. Mentha piperita biomass, stainless steel extraction vessels, and analytical testing capacity anchor upstream dependencies. Single-source vulnerability runs through Pacific Northwest climate-exposed growing regions. Distribution runs through flavor house intermediaries for food manufacturers and direct sales for pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Beverage and confectionery manufacturer consolidation is shifting procurement leverage toward larger buyers with reformulation mandates. Three buyer archetypes now dominate contract negotiations, forcing extract suppliers into longer-term offtake structures.
For Market Incumbents: Harden supply chain control through backward integration into controlled-origin Mentha piperita cultivation in Pacific Northwest growing regions. Invest in dual FDA-EMA certification capacity to capture pharmaceutical-grade premiums. Synthetic menthol substitution pressure in fragrance applications demands defensive positioning in therapeutic-grade segments where natural traceability commands price premiums.
For New Entrants and Emerging Players: Build out supercritical CO2 extraction capacity serving CDSCO-regulated pharmaceutical facilities in India, where respiratory and gastrointestinal formulation demand outpaces domestic supply. Target wellness center channels with USDA organic certification and farm-to-bottle traceability platforms. Direct-to-consumer online retail offers the most penetrable go-to-market angle for transparency-seeking buyers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors extract specialists with installed supercritical capacity and established regulatory dossier capabilities. Long-term viability hinges on pharmaceutical-grade margin sustainability as food-grade segments face synthetic substitution. Watch EFSA novel food designation enforcement as the inflection signal for reformulation-driven demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Captive Mentha piperita farming in Oregon secures therapeutic-grade supply chains against climate volatility. |
| Supercritical CO2 Capacity Expansion | German EMA-compliant facilities validate extracts for API-grade menthol applications with batch-level documentation. |
| Dual Certification Investment | USDA organic and ISO 9001 dual-certification unlocks premium pricing tiers in wellness center channels. |
| Direct-to-Consumer Channel Launch | Farm-to-bottle traceability platforms capture transparency premiums from online retail buyers. |
| Pharmaceutical Partnership Development | Long-term supply agreements with CDSCO-regulated Indian facilities lock in respiratory formulation demand. |
Research Methodology
A spread of perspectives from extraction plant managers, flavor house procurement directors, pharmaceutical regulatory affairs leads, and wellness channel buyers converged on the working assumptions. Primary interviews combined with secondary validation from FDA food additive filings, EFSA botanical safety assessments, CDSCO manufacturing facility registrations, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the analysis window.
Demand-supply balance dynamics shaped the analytical framework across product type, application, distribution channel, and end-user segmentation dimensions. CAGRs derived from installed base growth rates and penetration assumptions for emerging therapeutic applications. Forecast inputs included supercritical CO2 system deployment timelines, EFSA novel food designation enforcement patterns, and synthetic menthol price spreads.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by flavor houses or sudden synthetic menthol price collapses would shift outcomes. Material shifts in REACH compliance thresholds or Pacific Northwest climate patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Spices and Seasonings
Espresso Salt Market
Spices and Seasonings
Middle East and Africa Ashwagandha Market
Spices and Seasonings
Oregano Seasoning Market
Spices and Seasonings
Onion Salt Market
Spices and Seasonings
Mustard Market
Spices and Seasonings
Garlic Oleoresin Market
Spices and Seasonings
Boswellia Extract Market
Spices and Seasonings
Basil Essential Oil Market
Spices and Seasonings
Poultry Seasoning Market
Spices and Seasonings
Global Oregano Essential Oil Market
Spices and Seasonings
Paprika Color Market
Spices and Seasonings
Europe Spice and Herb Extracts Market
Spices and Seasonings
North America Seasonings Market
Spices and Seasonings
Asafoetida Market
Spices and Seasonings
Plastic Spice Jars Market
Spices and Seasonings
Carthamus Yellow Market