
 Smart Food Packaging Market | 2026-2036
Smart Food Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Food Packaging Market Intelligence
The EU Green Deal is pivoting smart food packaging demand toward biodegradable substrates and traceable supply chains. Amcor plc leverages its global manufacturing scale to supply integrated RFID-enabled films across multiple continents. Sealed Air Corporation anchors North American fresh protein segments with active barrier technologies. Mondi Limited specializes in paperboard-based connected packaging for European grocery retailers.
Smart food packaging encompasses materials and systems that monitor, communicate, or respond to product condition through embedded sensors, indicators, or digital identifiers. These systems typically incorporate oxygen-scavenging layers, time-temperature indicators, or NFC-enabled substrates to extend shelf stability and authenticate chain-of-custody. Biosensors represent the fastest-expanding technology segment as real-time pathogen detection migrates from laboratory settings to primary packaging. Biodegradable polymers command premium positioning among sustainability-driven food manufacturers, while plastic films retain volume dominance in cost-sensitive emerging markets.
The European Commission's Packaging and Packaging Waste Regulation, the U.S. FDA's food contact substance notification requirements, and Japan's METI circular economy standards collectively shape material compliance pathways and digital traceability mandates. REACH chemical restrictions and the EU AI Act's algorithmic transparency rules are extending compliance burdens to sensor-embedded packaging systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid fragmented certification investments that erode scale economics.
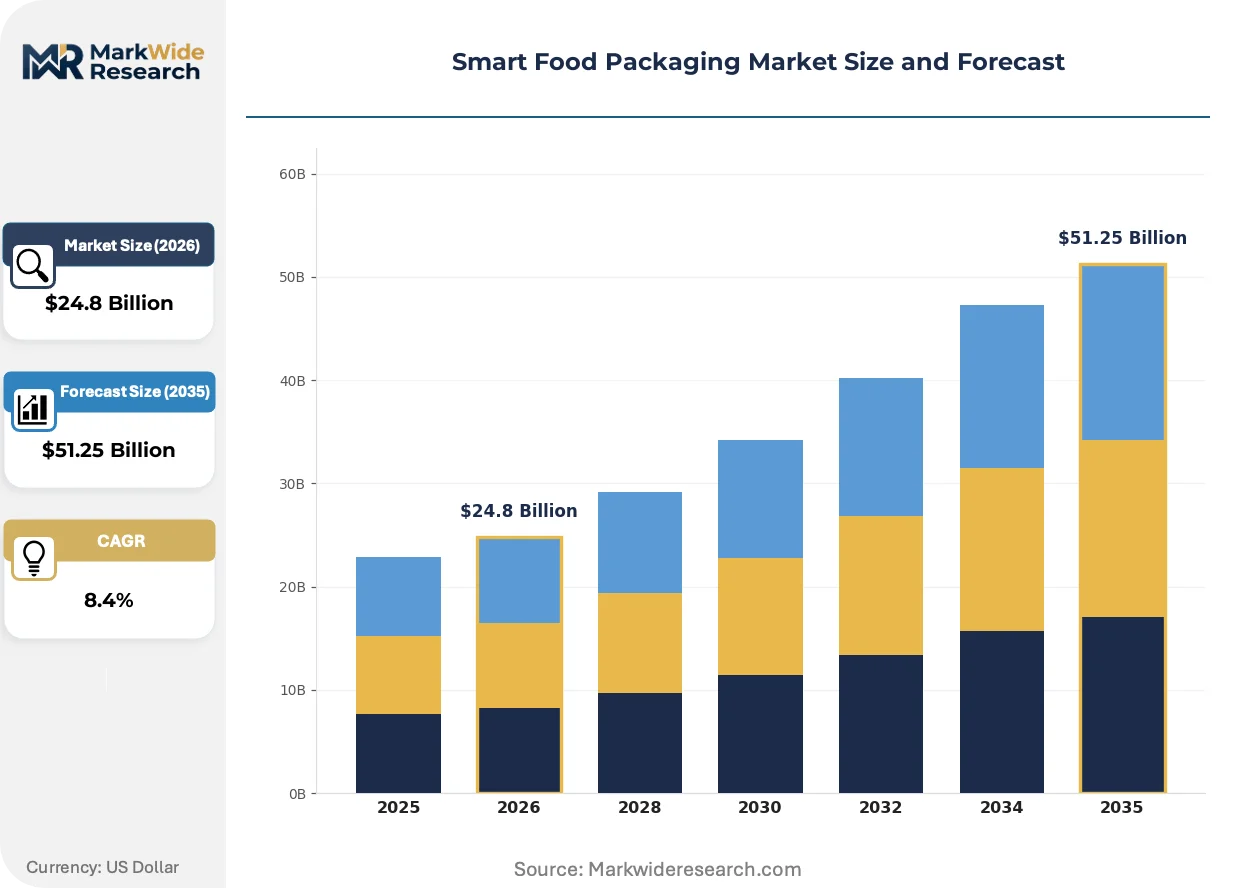
Market Dynamics
EU Green Deal packaging waste directives are forcing material transitions across European food manufacturing, while biosensor integration accelerates as real-time pathogen detection migrates from laboratories to primary packaging substrates.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets are compelling food manufacturers to adopt biodegradable polymers and connected traceability systems for compliance verification.
- Biosensor miniaturization:Laboratory-grade pathogen detection is embedding directly into primary packaging films, enabling retail chains to guarantee shelf-life transparency at point of sale.
- German retail concentration:Discounters and supermarket chains are retrofitting supply chains for RFID-enabled freshness monitoring, creating concentrated demand for integrated packaging solutions.
Market Restraints
- Biodegradable polymer cost premiums:Polylactic acid and polyhydroxyalkanoate substrates command 40-60% price premiums over conventional plastics, constraining adoption in price-sensitive emerging markets.
- Sensor supply concentration:NFC and RFID chip fabrication concentrates in East Asian foundries, exposing European converters to geopolitical supply disruptions and extended lead times.
- REACH chemical restrictions:Embedded sensor electronics face evolving substance restrictions that complicate multi-jurisdictional compliance and fragment certification investments.
Strategic Opportunities
- Fresh protein traceability gaps:North American meat and seafood processors remain underpenetrated for active barrier technologies with integrated time-temperature indicators.
- EU AI Act algorithmic transparency:Predictive spoilage models embedded in smart packaging must meet explainability standards, creating first-mover advantage for compliant solution architects.
- Japan METI circular economy standards:Food exporters to Japanese markets require packaging with embedded digital passports, opening premium positioning for NFC-enabled substrate suppliers.
Industry Challenges
- Cross-functional talent scarcity:Packaging engineers with simultaneous expertise in materials science, sensor integration, and food safety compliance remain exceptionally scarce.
- Legacy line retrofitting complexity:Converting existing form-fill-seal equipment for connected packaging integration demands extended downtime and specialized mechanical adaptation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Food Packaging Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biodegradable Polymers, Metallic Films, Paperboard, Plastic Films, Glass Coatings Technology: QR Codes, RFID Tags, Near Field Communication, Time-Temperature Indicators, Biosensors Application: Fresh Produce Packaging, Meat & Seafood, Dairy Products, Baked Goods, Beverages End User: Food Manufacturers, Retail Chains, Logistics Providers, Quality Control Labs, Packaging Designers |
| Companies Covered | Mondi Limited, Tetra Pak, Amcor plc, DS Smith, Smurfit Kappa Group PLC, Sealed Air Corporation, Avery Dennison Corporation, Gerresheimer AG, Berry Global Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Food Packaging Market Strategic Shifts & Innovations
Biosensor-enabled packaging is electrifying competitive dynamics as real-time freshness monitoring becomes a table-stakes requirement for premium food positioning.
Oxygen-scavenging films with embedded enzymatic biosensors detect spoilage metabolites at parts-per-billion sensitivity. Premium dairy and ready-to-eat meal producers in Germany and France are mandating these specifications for supplier qualification. This capability is electrifying differentiation strategies as retailers compete on shelf-life guarantees rather than price alone.
REACH chemical restrictions and the EU AI Act's algorithmic transparency rules are extending compliance burdens to sensor-embedded packaging systems. Food contact substance notifications now require detailed disclosure of electronic component migration risks. Small and mid-sized European converters face disproportionate certification costs, accelerating consolidation toward integrated multinationals with dedicated regulatory affairs functions.
Retail procurement teams are consolidating supplier relationships around full-stack traceability partners rather than discrete packaging vendors. German grocery chains now specify end-to-end digital custody records from farm to shelf. This concentration is most visible in fresh produce categories, where discounters compete on transparency credentials and reject suppliers unable to deliver batch-level authentication data.
Smart Food Packaging Market Segmentation
Smart food packaging segmentation reveals how material science, digital connectivity, and application-specific requirements intersect to create distinct value tiers. Manufacturers configure solutions across four primary axes that determine performance specifications, regulatory pathways, and procurement economics.
Material Type:
Substrate selection governs barrier performance, end-of-life compliance, and sensor integration compatibility.
- Biodegradable Polymers:Polylactic acid and polyhydroxyalkanoate formulations decompose under industrial composting conditions while maintaining oxygen barrier properties. German dairy processors mandate these substrates for private-label products under EU Green Deal packaging waste directives, accepting 40-60% cost premiums for regulatory compliance.
- Plastic Films:Multilayer polyethylene and polypropylene structures dominate volume economics through established extrusion infrastructure and proven moisture barrier performance. Emerging market food manufacturers in India and Brazil prioritize these substrates for cost-sensitive mass-market applications despite limited recyclability credentials.
- Metallic Films:Aluminum oxide-coated polyester delivers ultra-high oxygen barrier performance for extended shelf-life applications.
- Paperboard:Fiber-based substrates with barrier coatings serve European grocery retailers seeking plastic reduction commitments.
- Glass Coatings:Silicon dioxide vapor-deposited layers provide transparent barrier enhancement for premium beverage applications.
Plastic films lead on scale; biodegradable polymers lead on momentum.
Technology:
Digital identification and sensing capabilities differentiate premium positioning from commodity packaging.
- Biosensors:Enzymatic and antibody-based detection systems embedded in primary packaging films identify pathogen metabolites and spoilage markers at parts-per-billion sensitivity. French and German ready-to-eal meal producers now require these specifications for supplier qualification, migrating laboratory-grade detection directly to retail shelves.
- RFID Tags:Passive and active radio-frequency identification enables batch-level traceability through warehouse and retail environments. German discount grocery chains retrofit entire supply chains for RFID-enabled freshness monitoring, creating concentrated demand for integrated tag-inlay substrates.
- Near Field Communication:Short-range wireless connectivity allows consumer smartphone interaction with product authentication and provenance data.
- Time-Temperature Indicators:Chemical or electronic sensors provide visual or digital confirmation of cold chain integrity.
- QR Codes:Printed two-dimensional barcodes deliver cost-effective digital linkage to traceability databases.
RFID tags anchor current deployment scale; biosensors command the steepest expansion trajectory.
Application:
Product perishability and safety sensitivity determine smart packaging specification intensity.
- Fresh Produce Packaging:Modified atmosphere films with embedded ethylene scavengers and humidity sensors extend retail display life for leafy greens and berries. Retail chains in Germany and France compete on shelf-life guarantees rather than price alone, mandating integrated freshness monitoring for supplier qualification.
- Meat & Seafood:Active barrier technologies with oxygen-scavenging layers and time-temperature indicators protect protein products through distribution. North American processors remain underpenetrated for these integrated solutions, presenting expansion opportunity for active packaging suppliers.
- Dairy Products:Light-blocking and oxygen barrier films preserve nutritional integrity for fluid milk and fermented products.
- Baked Goods:Moisture-regulating packaging maintains texture profiles for extended retail availability.
- Beverages:Smart closures and label-integrated sensors monitor carbonation retention and temperature exposure.
Fresh produce packaging leads on deployment velocity; meat and seafood applications hold the largest unrealized volume potential.
End User:
Procurement sophistication and technical integration capability vary sharply across buyer categories.
- Retail Chains:Discounters and supermarket operators specify end-to-end digital custody records from farm to shelf, consolidating supplier relationships around full-stack traceability partners. German grocery procurement teams now reject suppliers unable to deliver batch-level authentication data.
- Food Manufacturers:Brand owners retrofit existing form-fill-seal equipment for connected packaging integration, demanding extended downtime tolerance and specialized mechanical adaptation from equipment vendors.
- Logistics Providers:Cold chain operators deploy sensor-embedded packaging to validate temperature integrity during transport.
- Quality Control Labs:Testing facilities validate smart packaging performance against regulatory food contact requirements.
- Packaging Designers:Creative agencies integrate digital functionality with brand aesthetic requirements.
Retail chains concentrate purchasing power; food manufacturers control specification origination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart food packaging traces its commercial origins to German industrial clusters that pioneered oxygen-scavenging films for meat preservation in the 1990s. Today, regulatory divergence across major economies fragments certification pathways while concentrated retail procurement in Northern Europe accelerates technology diffusion.
Germany
Discounters and supermarket chains in Germany mandate RFID-enabled freshness monitoring for supplier qualification, retrofitting entire supply chains for connected packaging integration. The EU Green Deal's packaging waste directives compel material transitions toward biodegradable substrates. Bavarian dairy processors lead private-label adoption of polylactic acid films despite 40-60% cost premiums.
United States
North American meat and seafood processors remain underpenetrated for active barrier technologies with integrated time-temperature indicators. The FDA's food contact substance notification requirements govern sensor-embedded packaging compliance. Chicago-area cold chain operators deploy sensor-embedded films to validate temperature integrity during interstate transport.
France
French ready-to-eat meal producers now require enzymatic biosensor specifications for supplier qualification, migrating laboratory-grade pathogen detection to retail shelves. REACH chemical restrictions complicate multi-jurisdictional compliance for embedded sensor electronics. The Île-de-France region concentrates packaging converter operations serving pan-European grocery retailers.
Japan
Food exporters to Japanese markets require packaging with embedded digital passports under METI circular economy standards. Premium positioning opens for NFC-enabled substrate suppliers meeting algorithmic transparency requirements. The Kanto region around Tokyo anchors demand for traceable supply chain solutions in seafood and prepared foods.
China
Domestic food manufacturers prioritize cost-sensitive plastic films for mass-market applications despite limited recyclability credentials. The country's national packaging regulator enforces evolving standards for smart packaging material safety. The Yangtze River Delta concentrates converter capacity serving both export and domestic fresh produce segments.
Smart Food Packaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across material sophistication and digital integration depth. The vendor base stratifies between integrated multinationals with dedicated regulatory affairs functions and regional converters facing disproportionate certification costs. Three archetypes dominate: full-stack traceability partners, specialized biosensor substrate suppliers, and scale-driven commodity film producers. Competitive moves concentrate on strategic partnerships for sensor supply security and portfolio diversification into biodegradable polymers.
Among integrated packaging multinationals, Amcor plc, Sealed Air Corporation, and Mondi Limited occupy positions spanning multiple technology vectors. Amcor exemplifies the global manufacturing scale archetype with RFID-enabled film supply across continents. Sealed Air anchors the active barrier specialization tier with North American fresh protein segment focus. Mondi represents the paperboard-based connected packaging archetype serving European grocery retailer plastic reduction commitments.
| Leading Market Players |
|---|
| Mondi Limited |
| Tetra Pak |
| Amcor plc |
| DS Smith |
| Smurfit Kappa Group PLC |
| Sealed Air Corporation |
| Avery Dennison Corporation |
| Gerresheimer AG |
| Berry Global Inc. |
| Others |
Cost & Logistics Intelligence
EU Green Deal packaging waste directives gate qualified supply for biodegradable polymer substrates while reserving premium-tier pricing access for converters with dedicated regulatory affairs functions and multi-jurisdictional certification capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates RFID-enabled biosensor substrates from active barrier films from commodity multilayer plastics. Price differentiation hinges on certification grade for REACH compliance and volume scale of integrated sensor orders. Cost compression in the economy tier is intensifying because Indian and Brazilian manufacturers prioritize cost-sensitive plastic films despite limited recyclability credentials. Emerging market food manufacturers exhibit highest price sensitivity, while German retail chains demonstrate lowest sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Freight cost escalation from East Asian sensor foundries to European converting facilities is reshaping regional procurement patterns for NFC and RFID chip components. Supply concentrates in China, South Korea, and Taiwan for semiconductor fabrication, while Germany and France anchor downstream converting operations. Raw material dependencies include polylactic acid resins, polyhydroxyalkanoate formulations, and aluminum oxide barrier coatings. Single-source vulnerability in East Asian chip fabrication exposes European converters to geopolitical supply disruptions. Distribution runs through consolidated retail procurement teams rather than fragmented packaging distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory layering, with the EU Packaging and Packaging Waste Regulation mandating recyclability targets that perpetually refresh demand for compliant substrate suppliers.
For Market Incumbents: Anticipate biosensor miniaturization trends by securing long-term supply agreements with East Asian semiconductor foundries before capacity constraints tighten. Consolidate regulatory affairs capabilities across REACH, EU AI Act, and FDA jurisdictions to defend margin position against mid-sized converters facing disproportionate certification costs. Prioritize backward integration into polylactic acid resin production to capture biodegradable polymer premiums. For New Entrants and Emerging Players: Launch via direct partnerships with North American meat and seafood processors, the most underpenetrated segment for active barrier technologies with integrated time-temperature indicators. Target fresh protein traceability gaps through specialized cold chain validation services rather than commodity film supply. Establish beachhead positioning in Japan METI circular economy compliance for NFC-enabled digital passport applications. For Investors and Strategic Acquirers: Roll-up economics work for regional European converters with existing FDA notification pathways because REACH chemical restrictions and EU AI Act algorithmic transparency rules are accelerating consolidation toward integrated multinationals. Long-term viability centers on five-to-ten year regulatory compliance moats rather than short-term volume scale. Watch for inflection when German discounters mandate batch-level authentication data as a non-negotiable supplier qualification threshold.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Investment | Dedicated REACH and EU AI Act compliance functions differentiate integrated multinationals from fragmented regional converters. |
| Sensor Supply Security Partnership | Long-term foundry agreements with Taiwanese and South Korean chip fabricators mitigate geopolitical disruption exposure. |
| Biodegradable Polymer Capacity Expansion | Polylactic acid and polyhydroxyalkanoate production scale captures EU Green Deal-driven material transition premiums. |
| Full-Stack Traceability Integration | End-to-end digital custody records from farm to shelf meet German retail chain procurement consolidation requirements. |
| Biosensor Substrate Specialization | Enzymatic detection systems embedded in primary packaging films command supplier qualification mandates from French ready-to-eat meal producers. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with packaging engineers, food safety compliance officers, retail procurement managers, and sensor integration specialists with secondary validation from FDA food contact substance notifications, ECHA REACH registration databases, EU Green Deal directive texts, and SEC filings of listed packaging multinationals. Bottom-up volume estimates from application-specific deployment rates were triangulated against top-down market sizing from material consumption trends.
Segment-weighting approaches distributed value across material type, technology, application, and end user dimensions, with additional weighting for regulatory compliance tier and geographic adoption pattern. CAGRs were derived from fitted growth curves anchored to base-year validation points and stress-tested against scenario assumptions for biosensor penetration rates and biodegradable polymer cost reduction trajectories. Industry-specific forecast inputs included German retail chain retrofit timelines and North American meat processor active barrier adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated REACH chemical restrictions or East Asian semiconductor export controls. Forecasts reflect assumptions about regulatory enforcement consistency and sensor cost reduction slopes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market
Smart Packaging
Smart Bottle Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Smart Label Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Self Cooling Packaging Market