
 Digital Packaging Market | 2026-2036
Digital Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Packaging Market Analysis
ISO 15378 certification for primary packaging materials is collapsing the supplier base as pharmaceutical-grade digital print operations consolidate. Amcor leverages its integrated film and inkjet infrastructure to sustain high-barrier flexible packaging contracts across North America. Mondi anchors European demand through specialty kraft paper substrates optimized for HP Indigo presses. Constantia Flexibles dominates pharmaceutical blister lidding with cold-form foil digitally printed for serialization compliance.
Digital packaging encompasses variable-data printing, embedded RFID inlays, and QR-linked interactive surfaces applied to primary and secondary containers for traceability, authentication, and consumer engagement. Electrophotographic and inkjet systems deposit food-safe pigment inks at resolutions exceeding 1200 dpi onto polymer films, folding cartons, and self-adhesive labelstocks. Flexible packaging leads value contribution due to short-run customization needs in specialty food and personal care, while smart packaging with NFC and temperature-logging sensors represents the fastest-expanding margin pool. Rigid packaging occupies a mature position in beverage cans and glass decoration where direct-to-shape digital printing remains capacity-constrained.
FDA food contact notification rules and EPA VOC emission limits for commercial printing operations shape substrate and ink formulation choices in the United States, while EU F-Gas Regulation and REACH chemical restrictions constrain solvent-based digital press adoption across Europe. Stakeholders must monitor evolving EPR packaging fee structures and state-level extended producer responsibility laws that will recalibrate total cost of ownership calculations for digital versus analog print transitions.
Market Dynamics
Pharmaceutical serialization mandates are compressing order quantities while multiplying SKU complexity, forcing converters to abandon analog economies of scale for digital production architectures that absorb variable-data requirements without plate-change downtime.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization deadlines across Germany, France, and Italy mandate unique identifiers on every pharmaceutical pack, driving investment in inkjet and electrophotographic systems capable of depositing variable codes at production speeds.
- Short-run SKU proliferation:Specialty food brands in craft chocolate, functional beverages, and limited-edition cosmetics now launch 500-2,000 unit batches, eliminating minimum-order thresholds that previously locked out smaller players.
- HP Indigo and Xeikon press penetration:Electrophotographic platforms capable of food-safe pigment transfer onto polymer films and metallized substrates now operate across 40+ countries, collapsing lead times from weeks to hours for flexible packaging converters.
Market Restraints
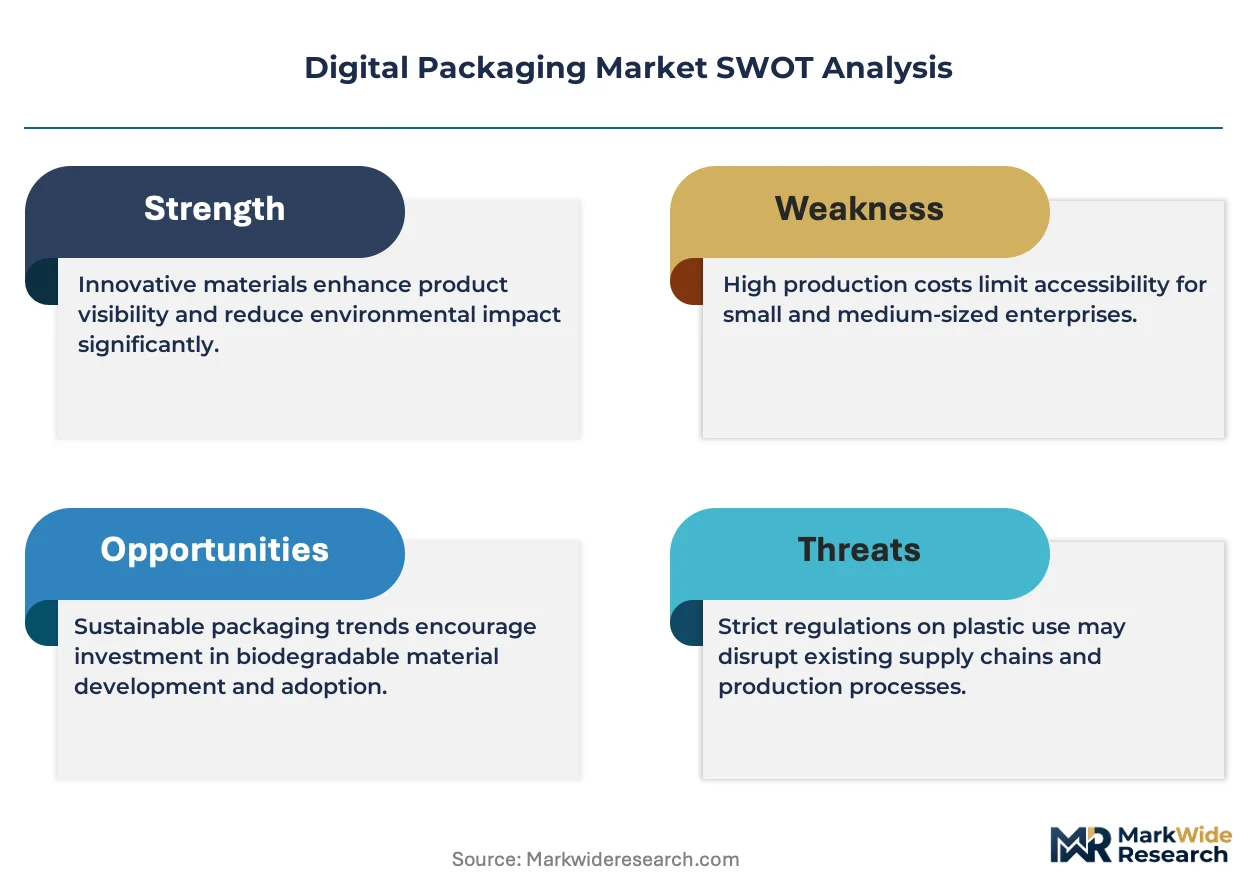
- Pigment ink cost structure:Food-grade aqueous and UV-curable pigment formulations cost 3-4x conventional solvent inks, eroding margin on sub-10,000 unit runs where setup savings no longer offset material premiums.
- Substrate supply concentration:Pharmaceutical-grade cold-form foil and high-barrier films for blister lidding concentrate among three European suppliers, exposing converters to allocation risk during raw aluminum or PVC volatility.
- Direct-to-shape throughput ceilings:Digital decoration of beverage cans and glass bottles remains constrained to 600-1,200 containers per minute versus 2,000+ for conventional offset or flexo, limiting adoption in mass-market carbonated drinks.
Strategic Opportunities
- NFC-embedded pharmaceutical compliance:Near-field communication inlays combined with printed electronics enable real-time temperature logging and authentication verification, opening premium pricing for cold-chain biologics in North American and European markets.
- India PLI scheme for packaging machinery:Production-linked incentives for capital goods manufacturing reduce import duties on digital press components, positioning domestic converters to serve Southeast Asian pharmaceutical export demand.
- QR-linked consumer engagement surfaces:Variable-data QR codes printed via inkjet enable traceability storytelling and reordering portals, capturing first-party data for CPG brands previously blind to post-purchase behavior.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical-grade digital print operations require 12-18 month validation cycles for primary packaging materials, delaying revenue conversion after capital deployment.
- Color management skill scarcity:ICC profile development for substrate-ink-press combinations demands specialized prepress talent unavailable in traditional flexo converter workforces, forcing competitive bidding for limited specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Packaging Market |
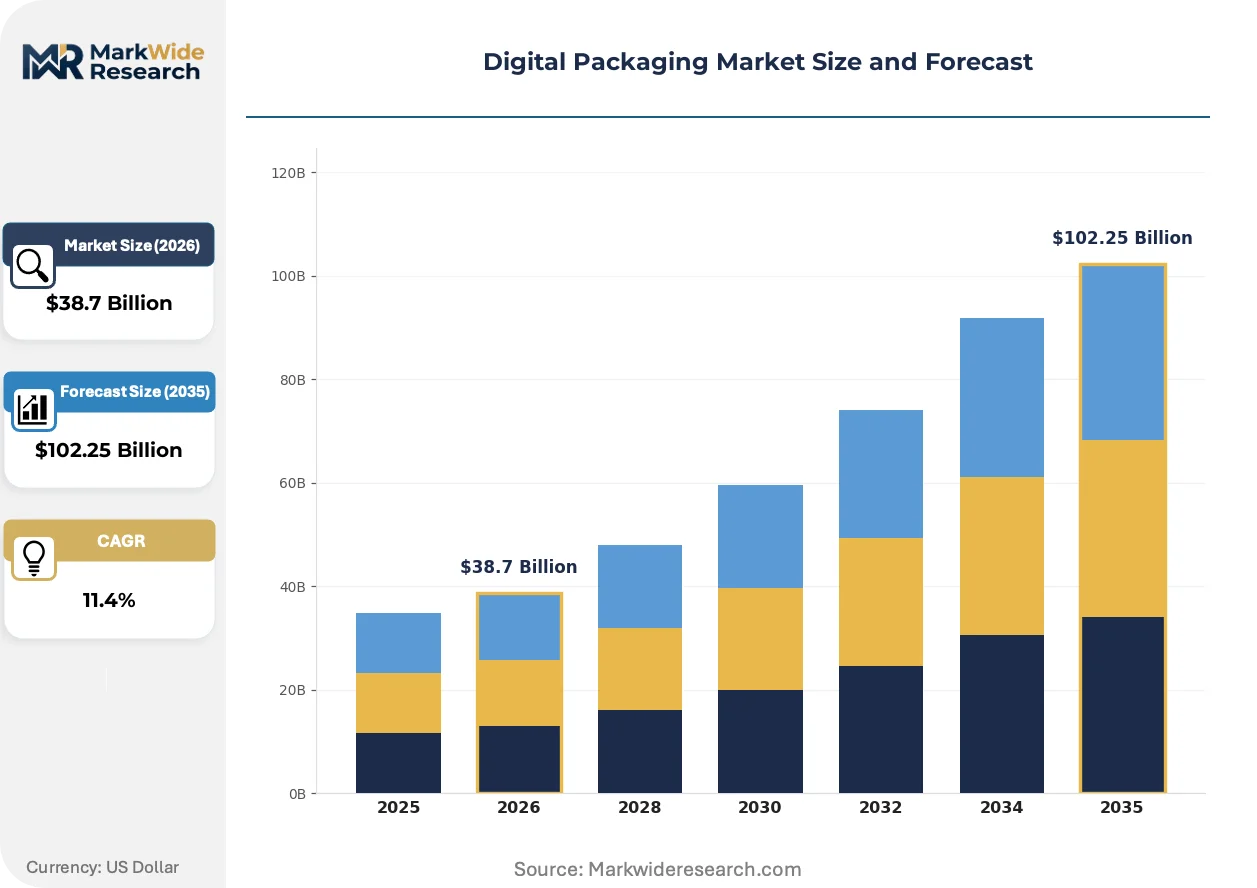
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Labels, Flexible Packaging, Rigid Packaging, Tags Technology: Digital Printing, RFID, QR Code, Smart Packaging End User: Food & Beverage, Healthcare, Consumer Electronics, Personal Care Material: Plastic, Paper, Metal, Glass |
| Companies Covered | Constantia Flexibles, Stora Enso, Amcor, Huhtamaki, Mondi, Sealed Air, Smurfit Westrock, Graphic Packaging International, CCL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Packaging Market Emerging Trajectories
Variable-data infrastructure is migrating from label decoration into primary flexible and rigid containers, collapsing the distinction between packaging as protection and packaging as interactive media channel.
Single-pass inkjet arrays with 1200+ dpi native resolution and food-safe aqueous pigment sets are decomposing the traditional flexo-rotogravure duopoly in snack, confectionery, and personal care flexible packaging. Mid-sized converters in Germany, Italy, and the United States now run 24-hour changeover cycles across 40+ SKUs weekly, compressing inventory carrying costs and obsoleting plate warehousing. The technology is decomposing minimum efficient scale thresholds that previously required 50,000+ unit commitments.
REACH Annex XVII restrictions on N-methyl-2-pyrrolidone and other solvent carriers are accelerating water-based and UV-curable ink formulation investment across European converter operations. Industrial consequence includes 15-20% throughput reduction on legacy narrow-web presses unable to handle higher viscosity aqueous systems without drying module retrofit. Pharmaceutical blister lidding and food contact applications in France, Germany, and Benelux face the most acute compliance deadlines, driving consolidation toward integrated ink-substrate-press suppliers with in-house toxicology documentation.
Brand procurement teams now specify outcome-based packaging contracts tied to serialization accuracy rates and interactive engagement metrics rather than unit cost per thousand. Traditional spot-buy relationships with multiple regional converters fragment into multi-year partnerships with digital-native suppliers capable of absorbing data-integration requirements. This pattern concentrates most visibly among North American pharmaceutical and European premium food exporters where regulatory documentation and consumer transparency demands intersect.
Digital Packaging Market Segmentation
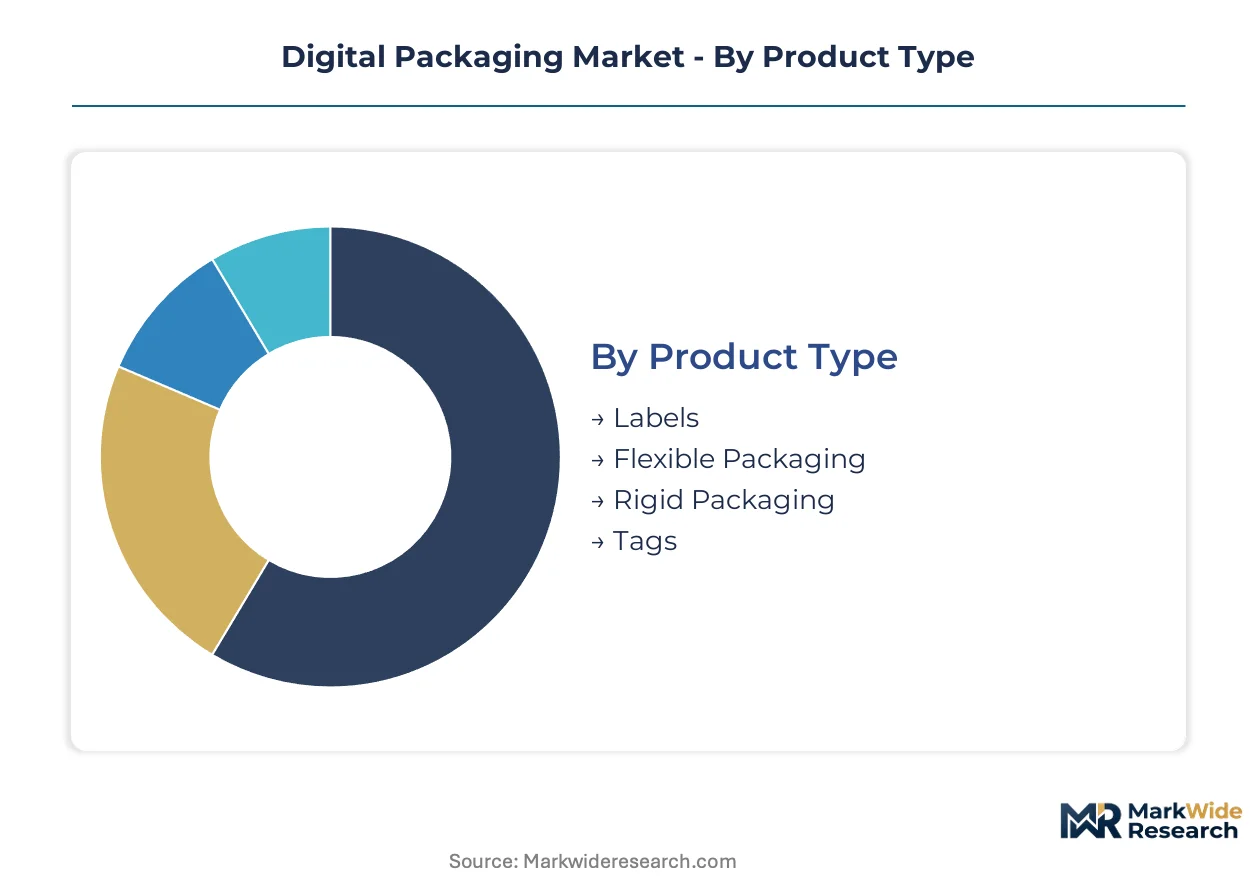
Digital packaging segmentation reveals how variable-data capabilities and smart substrate integration reshape procurement priorities across converter operations. Product type and technology choices determine capital allocation, while end-user compliance requirements and material specifications govern ink formulation and press configuration decisions.
Product Type:
Flexible packaging and labels face the most acute substitution pressure from conventional flexo and rotogravure as run lengths compress below 10,000 units.
- Labels:Self-adhesive and shrink-sleeve formats dominate pharmaceutical serialization and craft beverage branding. German and Italian converters deploy electrophotographic systems to absorb 500-unit minimum orders previously uneconomical for analog plate production.
- Flexible Packaging:High-barrier films and pouches for specialty foods and personal care represent the largest value pool. North American converters integrate HP Indigo presses to collapse lead times from weeks to hours on metallized substrates.
- Rigid Packaging:Direct-to-shape decoration of beverage cans and glass bottles remains capacity-constrained at 600-1,200 containers per minute versus 2,000+ for conventional offset.
- Tags:Garment and logistics applications leverage variable-data inkjet for inventory management and authentication marking.
Flexible packaging retains volume leadership; labels hold the steepest expansion curve as SKU proliferation accelerates across European premium food exporters.
Technology:
Cost tier differentiation separates capital-intensive press infrastructure from lower-barrier smart packaging integration.
- Digital Printing:Electrophotographic and single-pass inkjet systems deposit food-safe pigment inks at 1200+ dpi onto polymer films and folding cartons. REACH Annex XVII solvent restrictions accelerate water-based and UV-curable formulation investment across French and German converter operations.
- Smart Packaging:NFC-embedded and temperature-logging sensors enable real-time cold-chain verification for biologics. North American pharmaceutical brands specify outcome-based contracts tied to serialization accuracy rates.
- RFID:Inlay integration for supply chain tracking concentrates in retail apparel and pharmaceutical distribution.
- QR Code:Variable-data matrix codes printed via inkjet link physical packs to traceability storytelling and reordering portals.
Digital printing anchors current revenue; smart packaging climbs the fastest as regulatory mandates and consumer transparency demands converge.
End User:
Application maturity varies sharply across compliance intensity and consumer engagement sophistication.
- Healthcare:Pharmaceutical serialization mandates under EU Falsified Medicines Directive compress order quantities while multiplying SKU complexity. Cold-form foil blister lidding requires ISO 15378 certification cycles of 12-18 months.
- Food & Beverage:FDA food contact notification rules and EPA VOC emission limits govern substrate and ink formulation choices in the United States.
- Personal Care:Limited-edition cosmetics and functional positioning drive short-run customization needs.
- Consumer Electronics:Anti-counterfeiting and unboxing experience requirements sustain premium packaging investment.
Healthcare commands premium pricing; food and beverage generates the broadest volume base across converter operations.
Material:
Supply concentration risk clusters around pharmaceutical-grade substrates and high-barrier films.
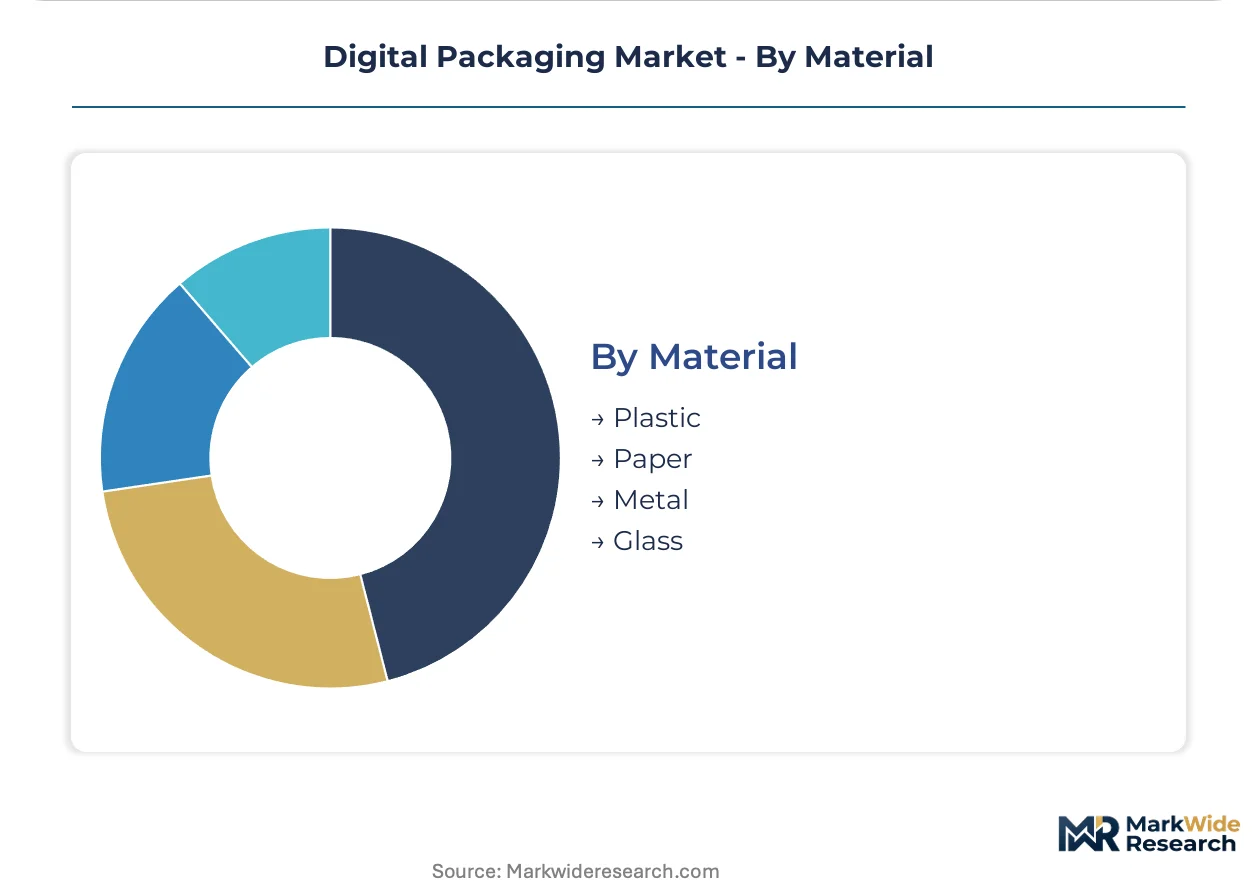
- Plastic:Polymer films and pouches for snack, confectionery, and personal care flexible packaging absorb the majority of inkjet press capacity. Three European suppliers concentrate pharmaceutical-grade cold-form foil and blister lidding materials.
- Paper:Specialty kraft substrates optimized for electrophotographic presses serve European premium food and sustainable positioning requirements.
- Metal:Aluminum cold-form foil for pharmaceutical blister packs faces raw material volatility and allocation risk during supply disruptions.
- Glass:Direct-to-shape digital decoration for beverage and cosmetic bottles remains throughput-limited versus conventional screen printing.
Plastic dominates current converter throughput; paper gains share fastest as sustainability specifications tighten across EU packaging regulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives in India and serialization mandates across the EU are redrawing capital deployment patterns for digital packaging infrastructure. Regulatory deadlines in pharmaceutical markets now outweigh labor cost considerations in site selection decisions.
Germany
Pharmaceutical exporters in Baden-Württemberg and Bavaria drive demand for serialized blister lidding and cold-form foil with integrated track-and-trace codes. REACH Annex XVII restrictions on solvent carriers accelerate converter migration to water-based inkjet systems. The Stuttgart-Mannheim corridor hosts the densest concentration of ISO 15378-certified digital print operations serving EU Falsified Medicines Directive compliance.
United States
FDA food contact notification rules and EPA VOC emission limits shape substrate formulation choices across flexible packaging converters. Short-run SKU proliferation in craft beverages and functional foods concentrates demand in California's Central Valley and Pacific Northwest brewing clusters. Chicago-area converters integrate HP Indigo infrastructure to serve Midwestern pharmaceutical and food brands with sub-10,000 unit production cycles.
India
The PLI scheme for packaging machinery reduces import duties on digital press components, positioning domestic converters to capture Southeast Asian pharmaceutical export demand. Gujarat and Maharashtra pharmaceutical clusters invest in electrophotographic systems for serialization-compliant primary packaging. Hyderabad's vaccine manufacturing corridor generates specialized demand for temperature-logging smart labels with NFC inlays.
China
Dual carbon goals and tightening MEE enforcement on industrial emissions accelerate water-based ink formulation adoption across Pearl River Delta converter operations. Yangtze River Delta personal care and electronics brands specify variable-data QR codes for anti-counterfeiting and consumer engagement. Shenzhen's packaging equipment manufacturers develop single-pass inkjet arrays for regional snack and confectionery flexible packaging.
Italy
Premium food exporters in Emilia-Romagna and Piedmont leverage digital printing for limited-edition positioning and traceability storytelling. ECHA compliance documentation requirements favor integrated ink-substrate suppliers with in-house toxicology capabilities. Bologna's converter cluster specializes in metallized substrate decoration for specialty coffee and craft chocolate brands serving Northern European markets.
Digital Packaging Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and certification depth. The market exhibits tiered concentration with integrated multinational converters occupying pharmaceutical-grade segments and regional specialists capturing short-run food and beverage customization. Three archetypes dominate: film-and-inkjet integrated suppliers, specialty substrate developers, and serialization-focused pharmaceutical contractors. Competitive moves center on backward integration into substrate production and multi-year outcome-based contracting with brand procurement teams.
Within the integrated multinational tier, Amcor and Mondi exemplify divergent geographic anchoring strategies. Amcor sustains North American flexible packaging contracts through captive film production and inkjet infrastructure. Mondi anchors European demand through kraft paper substrate optimization for electrophotographic presses. Constantia Flexibles occupies a specialized position within pharmaceutical blister lidding, where cold-form foil serialization requirements demand extended certification cycles and toxicology documentation capabilities.
| Leading Market Players |
|---|
| Constantia Flexibles |
| Stora Enso |
| Amcor |
| Huhtamaki |
| Mondi |
| Sealed Air |
| Smurfit Westrock |
| Graphic Packaging International |
| CCL Industries |
| Others |
Supply Flow & Price Mechanics
Water-based pigment ink substitution for solvent-based formulations simultaneously redraws raw material sourcing geography toward European specialty chemical producers and compresses margin structures for converters unable to absorb 15-20% throughput losses on legacy press retrofits. This input transition concentrates pricing power among integrated ink-substrate-press suppliers with in-house toxicology documentation capabilities.
Pricing Analysis
Certification level (ISO 15378 versus standard food-grade) creates the primary spread between premium pharmaceutical blister lidding and commodity flexible packaging tiers. Three-tier pricing structure separates validated primary packaging materials from secondary decoration and generic label stocks. Cost compression in sub-10,000 unit runs intensifies because food-grade aqueous pigment formulations command 3-4x conventional solvent ink premiums. Brand procurement teams in North American pharmaceutical markets exhibit lowest price sensitivity, prioritizing serialization accuracy guarantees over unit economics.
Supply Chain Analysis
Inventory carrying costs have collapsed from weeks to hours as German and Italian converters adopt 24-hour changeover cycles across 40+ SKUs weekly. Pharmaceutical-grade cold-form foil and high-barrier blister lidding materials draw from concentrated European supplier bases in Germany, Italy, and Belgium. Raw aluminum and PVC volatility exposes converters to allocation risk during supply disruptions. Distribution runs through multi-year outcome-based partnerships with digital-native suppliers rather than fragmented spot-buy relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against analog-to-digital converter migration that threatens incumbent flexo-rotogravure specialists with stranded plate production assets.
For Market Incumbents: Compound certification depth in ISO 15378 pharmaceutical-grade operations to create switching-cost barriers against emerging digital-native competitors. Prioritize backward integration into cold-form foil substrate production to secure allocation priority during raw material volatility. Lock in multi-year outcome-based contracts with North American pharmaceutical brands before serialization mandate deadlines consolidate buyer relationships. For New Entrants and Emerging Players: Rapid-response short-run services for European premium food exporters represent the most penetrable white-space where legacy converters maintain 2-3 week lead times. Target craft chocolate and functional beverage clusters in Italy's Emilia-Romagna region with 500-2,000 unit minimum order capabilities. Lead with QR-linked consumer engagement surfaces that capture first-party data for brands previously blind to post-purchase behavior. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-cap converters that acquired digital press capacity but lack integrated substrate supply and toxicology documentation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than equipment depreciation schedules alone. Watch for EU Falsified Medicines Directive enforcement intensity in Germany and France as inflection indicators for pharmaceutical-grade digital packaging demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive supply of pharmaceutical-grade cold-form foil insulates converters from aluminum allocation risk during supply disruptions. |
| ISO 15378 Certification Investment | Validation cycles of 12-18 months create switching-cost barriers against emerging digital-native competitors in pharmaceutical segments. |
| NFC-Embedded Smart Packaging Development | Real-time temperature logging capabilities open premium pricing for cold-chain biologics in North American and European markets. |
| Multi-Year Outcome-Based Contracting | Serialization accuracy guarantees replace unit-cost procurement metrics for North American pharmaceutical brand procurement teams. |
| Water-Based Ink Formulation Transition | REACH Annex XVII compliance positions European converters ahead of solvent restriction enforcement across France and Germany. |
Methodological Framework
The analysis maps electrophotographic press deployment, single-pass inkjet adoption, smart packaging integration, and substrate-ink certification pathways, each validated through converter operations managers, pharmaceutical packaging procurement leads, food-grade ink formulation specialists, and regulatory compliance officers. Primary fieldwork across Germany, the United States, Italy, and India combined with secondary validation from FDA food contact notifications, ECHA REACH Annex XVII documentation, EU Falsified Medicines Directive implementation timelines, and HP Indigo/Xeikon press installation records. Bottom-up capacity modeling and top-down demand segmentation triangulate market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type (labels, flexible packaging, rigid packaging, tags), technology (digital printing, smart packaging, RFID, QR code), end user (healthcare, food and beverage, personal care, consumer electronics), and material (plastic, paper, metal, glass). CAGRs derived from annualized growth rate calculations applied to base-year market estimates. Industry-specific forecast inputs incorporated pharmaceutical serialization mandate deadlines and REACH chemical restriction phase-in schedules.
Forecasts assume regulatory continuity in EU Falsified Medicines Directive enforcement and FDA food contact notification frameworks; material policy shifts or accelerated EPA VOC emission limit revisions would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Label Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Smart Bottle Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Smart Retail Packaging Market