
 Smart Retail Packaging Market | 2026-2036
Smart Retail Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Retail Packaging Market Analytics
Supermarket shelf-to-warehouse data loops is narrowing as real-time inventory visibility becomes a baseline expectation rather than a premium feature. Avery Dennison leverages its RFID inlay manufacturing scale to dominate tag supply for apparel and grocery chains. Sealed Air anchors protective packaging intelligence through embedded freshness sensors that communicate spoilage risk. Amcor competes across flexible formats with connected closures that track pharmaceutical cold chain integrity.
Smart retail packaging integrates printed electronics, microsensors, and wireless communication substrates into primary and secondary packaging to enable traceability, authentication, and consumer engagement throughout the product lifecycle. These systems typically incorporate conductive inks, NFC or RFID antennae, and cloud-linked microcontrollers operating at frequencies between 860 and 960 MHz for passive ultra-high-frequency tracking. Plastic substrates currently lead material adoption due to barrier properties and printability, though biodegradable alternatives are gaining structural traction as regulatory deadlines for recyclability approach in European and North American markets. RFID technology occupies the highest-margin segment within the technology stack, while QR codes sustain volume leadership because of zero incremental hardware cost for brands.
The EU Green Deal and F-Gas Regulation constrain fluorinated barrier films in connected packaging, forcing reformulation toward mono-material or fiber-based substrates. FDA food contact notification requirements and EPA guidelines on per- and polyfluoroalkyl substances shape permissible sensor substrates and adhesive chemistries in the United States. Stakeholders must monitor whether emerging state-level extended producer responsibility frameworks in California and New York will mandate digital sorting markers that could accelerate NFC adoption or strand existing RFID infrastructure investments.
Market Dynamics
The EU Green Deal and packaging waste directives are compressing material substitution timelines while RFID inlay supply concentrates among three dominant manufacturers, creating procurement bottlenecks for mid-size retail chains.
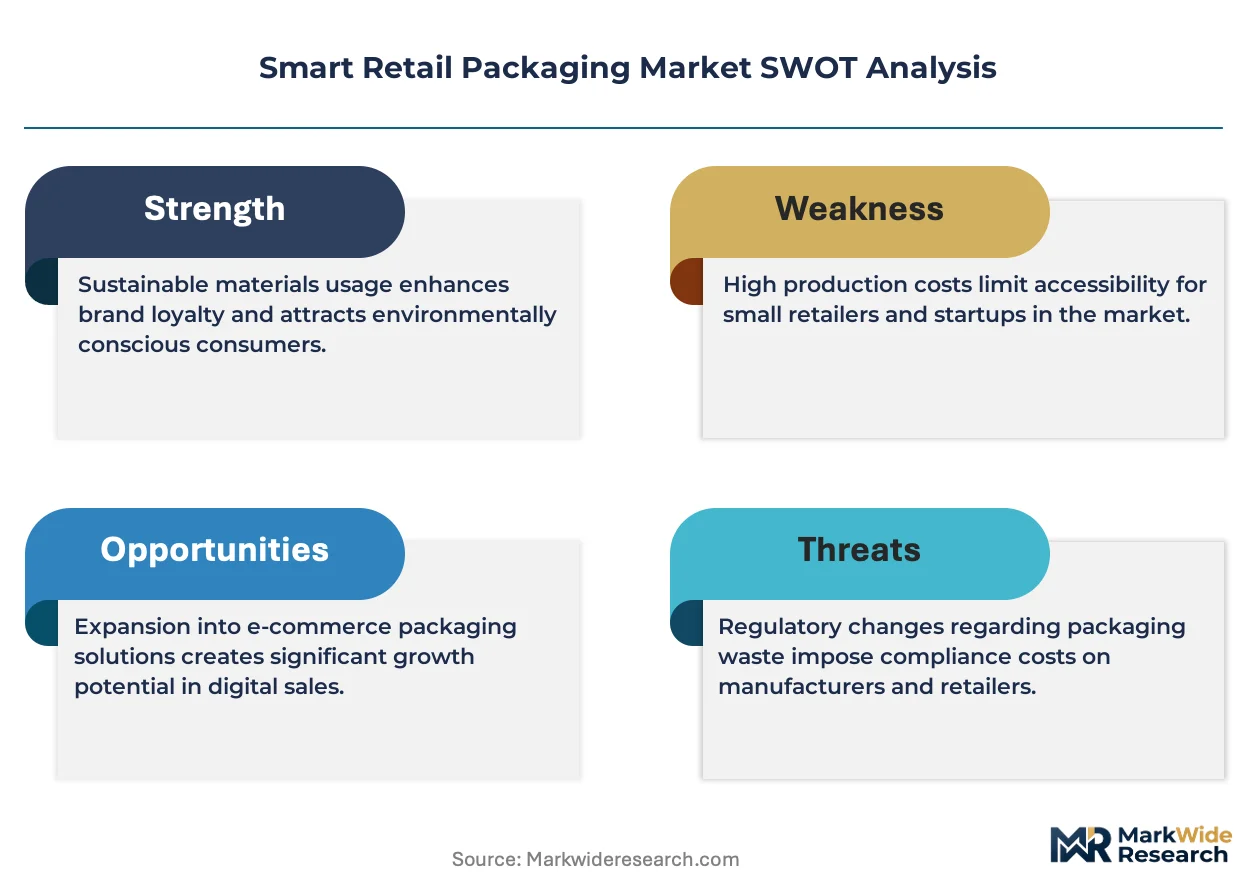
Growth Catalysts
- EU F-Gas Regulation:The phase-down of fluorinated greenhouse gases in barrier films is forcing reformulation toward mono-material substrates, opening capacity at European converters specializing in polyethylene and polypropylene structures.
- Food and beverage retail digitization:Supermarket chains in Germany, China, and the United States are deploying connected packaging for real-time spoilage monitoring, reducing shrinkage and enabling dynamic markdown automation.
- Printed electronics cost curves:Conductive ink deposition speeds have tripled since 2022, cutting unit costs for NFC antennae and enabling single-use authentication tags at mass-market price points.
Market Restraints
- RFID inlay supply concentration:Three manufacturers control over 80% of UHF inlay capacity, exposing buyers to allocation risk during demand surges and limiting price negotiation leverage.
- Silver conductive ink volatility:Precious metal price swings directly impact printed electronics economics, compressing margins for converters without long-term commodity hedging programs.
- Technical limitation in metalized substrates:RFID signal attenuation on aluminum-laminated barrier films restricts tag placement options in premium food packaging, forcing design compromises.
Strategic Opportunities
- Underpenetrated pharmaceutical cold chain:Biologics distributors in India and Brazil lack systematic temperature logging, creating demand for low-cost disposable sensors with cloud-linked alert systems.
- California extended producer responsibility frameworks:Emerging state mandates for digital sorting markers could accelerate NFC adoption in North American markets if interoperability standards align with European practice.
- Convergence of blockchain and NFC:Immutable provenance verification is gaining traction in luxury cosmetics, where counterfeit detection justifies per-unit authentication costs above commodity thresholds.
Industry Challenges
- Embedded firmware talent scarcity:Packaging converters lack in-house microcontroller programming capabilities, forcing reliance on third-party design houses and extending development cycles.
- Multi-jurisdiction certification complexity:FDA food contact notifications, EU EFSA compliance, and China's GB standards require parallel testing programs, inflating time-to-market for global product launches.
- Legacy ERP integration friction:Retailer inventory management systems require custom middleware to ingest real-time packaging sensor data, slowing pilot-to-scale transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Retail Packaging Market |
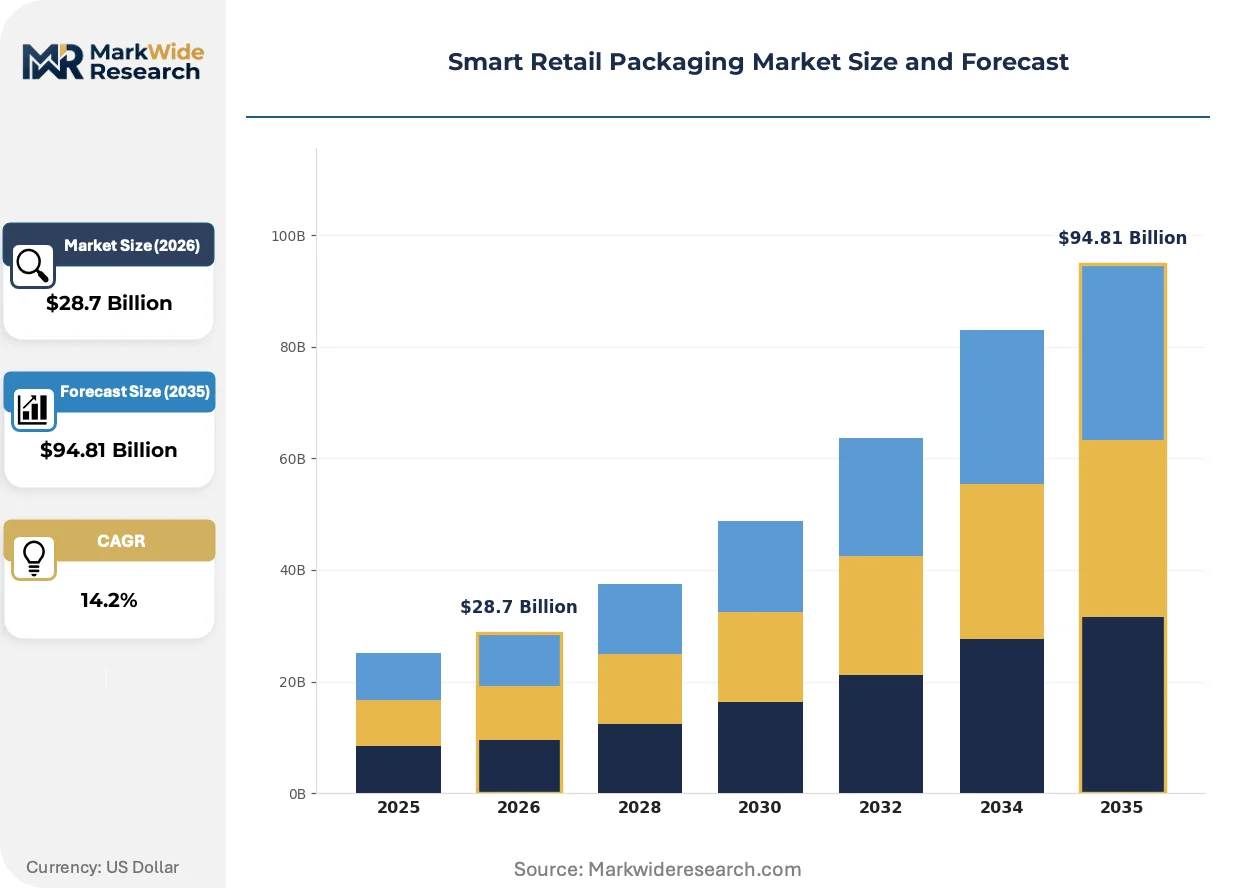
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $94.81 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Paper, Metal, Biodegradable Technology: RFID, QR Codes, Near Field Communication, IoT Sensors Application: Food & Beverage, Cosmetics, Electronics, Pharmaceuticals End User: Retail Stores, E-commerce Platforms, Wholesalers, Distributors |
| Companies Covered | Avery Dennison, Sealed Air, Amcor, Smurfit Kappa, Mondi Group, WestRock, Tetra Pak, DS Smith, Graphic Packaging International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Retail Packaging Market Evolving Landscape
Printed electronics and microsensor integration are compressing the cost-performance frontier for connected packaging, while regulatory deadlines in Europe and North America accelerate material transitions ahead of technical readiness.
Biodegradable substrates derived from cellulose nanofibers and polylactic acid blends are rendering obsolete conventional multi-layer plastic structures in fresh produce packaging. German supermarket chains have committed to pilot deployments across 2,000 SKUs by 2025, pressuring converters to solve moisture barrier limitations that previously confined bio-based materials to dry goods. The structural consequence is a capacity race among European film extruders to install compostable barrier coating lines before the EU Green Deal's 2030 recyclability mandates take full effect.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier chemistries from food contact applications. The industrial consequence is a forced migration toward silicon oxide and aluminum oxide vapor-deposited barriers, which currently cost 40% more per square meter and exhibit brittleness in flex-crimp sealing operations. Pharmaceutical cold chain packaging in Germany and France is most affected, with manufacturers accelerating validation programs for alternative substrates ahead of 2025 enforcement deadlines.
Retailers are consolidating vendor relationships for connected packaging procurement, favoring turnkey providers who integrate sensor hardware, cloud analytics, and compliance documentation. This concentration is displacing point-solution specialists who previously supplied discrete components. The shift is most visible in United States grocery and mass merchandiser channels, where category managers now mandate single-source accountability for traceability system performance rather than assembling multi-vendor stacks.
Smart Retail Packaging Market Segmentation
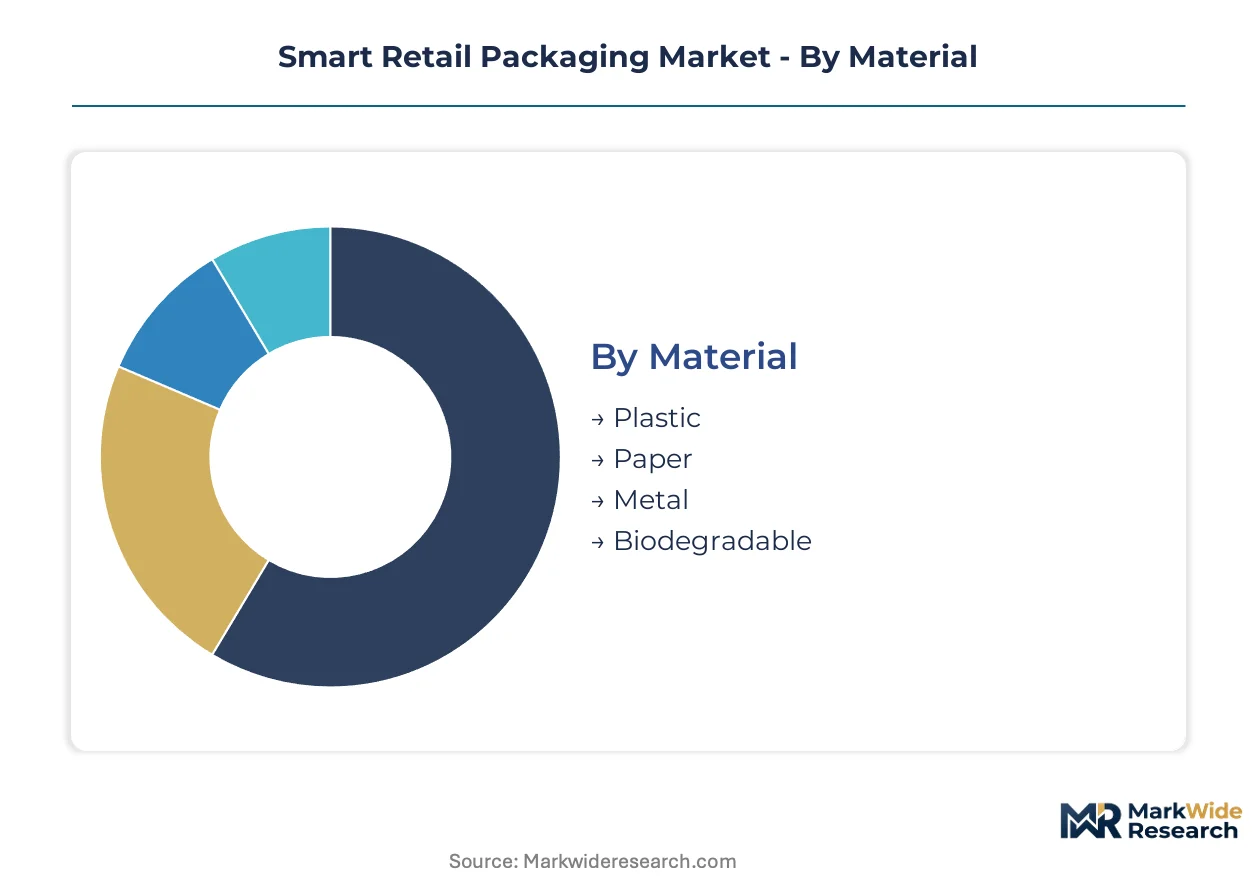
Smart retail packaging segmentation reveals divergent replacement cycles across material substrates and technology tiers. RFID inlays and biodegradable films turn over rapidly as regulatory deadlines compress adoption windows, while plastic-based QR implementations enjoy longer deployment horizons.
Material:
Cycle times vary dramatically: biodegradable films refresh every 12-18 months as formulations improve, whereas multi-layer plastic structures persist for 3-5 years before compliance-driven replacement.
- Plastic:Multi-layer polyethylene and polypropylene structures dominate current installations due to printability and barrier performance. German supermarket chains and US grocery distributors specify these substrates for high-volume fresh produce tracking where moisture resistance is non-negotiable.
- Biodegradable:Cellulose nanofiber and polylactic acid blends are displacing conventional plastics in pilot deployments across 2,000 SKUs. EU Green Deal recyclability mandates are compressing adoption timelines as converters race to install compostable barrier coating capacity ahead of enforcement deadlines.
- Paper:Fiber-based substrates with vapor-deposited silicon oxide barriers serve dry goods authentication where flex-crimp durability is less critical.
- Metal:Aluminum-laminated structures persist in pharmaceutical cold chain applications despite RFID signal attenuation constraints that limit tag placement flexibility.
Plastic dominates installed base. Biodegradable is where expansion concentrates.
Technology:
Cost tiers separate mass-market deployment from premium authentication, with zero-incremental-hardware solutions scaling fastest in price-sensitive channels.
- RFID:Passive UHF inlays operating at 860-960 MHz anchor high-margin traceability for apparel and grocery chains. Supply concentration among three dominant manufacturers creates procurement bottlenecks for mid-size retail chains during demand surges.
- QR Codes:Zero hardware cost sustains volume leadership across mass-market consumer goods. Printed electronics cost curves have tripled deposition speeds since 2022, enabling single-use authentication at commodity price points.
- Near Field Communication:Cloud-linked microcontrollers enable consumer engagement and dynamic content delivery for luxury cosmetics authentication.
- IoT Sensors:Embedded freshness monitors communicate spoilage risk in real-time, reducing shrinkage and enabling automated markdown workflows for supermarket chains.
QR codes capture volume leadership. RFID commands margin concentration.
Application:
Customer type determines specification intensity, with regulated industries demanding validated cold chain documentation versus retail's focus on inventory velocity.
- Food & Beverage:Real-time spoilage monitoring and dynamic markdown automation drive supermarket digitization investments in Germany, China, and the United States. Connected closures track cold chain integrity from distribution center to shelf.
- Pharmaceuticals:Biologics distributors in India and Brazil lack systematic temperature logging, creating demand for low-cost disposable sensors with cloud-linked alert systems.
- Cosmetics:Luxury brands deploy NFC-enabled provenance verification to justify per-unit authentication costs above commodity thresholds.
- Electronics:Anti-counterfeiting tags protect high-value components through supply chain visibility from manufacturing to retail.
Food and beverage anchors current deployment. Pharmaceuticals show steepest expansion trajectory.
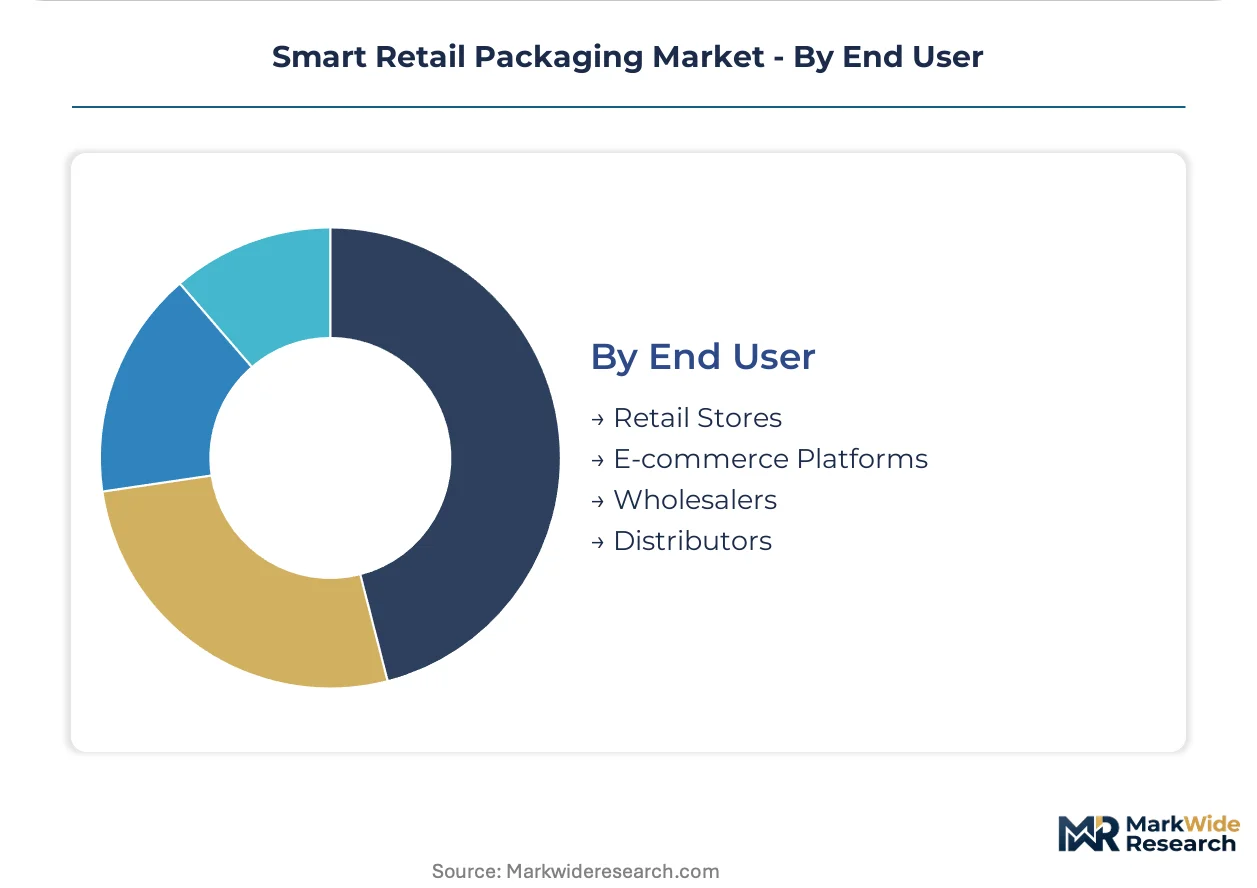
End User:
Volume scale separates enterprise procurement patterns, with national chains mandating single-source accountability versus fragmented wholesaler adoption.
- Retail Stores:Category managers now mandate turnkey traceability system performance rather than assembling multi-vendor stacks. Consolidated vendor relationships favor providers integrating sensor hardware, cloud analytics, and compliance documentation.
- E-commerce Platforms:Return fraud prevention and authentication verification drive investment in connected packaging for high-value shipments.
- Wholesalers:Legacy ERP integration friction slows pilot-to-scale transitions as inventory management systems require custom middleware to ingest real-time sensor data.
- Distributors:Pharmaceutical and perishable goods specialists prioritize cold chain documentation to satisfy regulatory audit requirements.
Retail stores command procurement concentration. E-commerce platforms are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters extract 15-20% pricing premiums on compostable barrier films versus Chinese exporters of conventional multi-layer structures. This asymmetry reflects regulatory deadline pressure and technical validation requirements that concentrate value capture in European manufacturing clusters.
United States
Supermarket chains in California and New York are piloting NFC-enabled dynamic markdown systems to reduce perishable shrinkage. State-level extended producer responsibility frameworks emerging in these jurisdictions mandate digital sorting markers that could strand existing RFID infrastructure. The Midwest packaging corridor around Chicago anchors converter capacity for high-volume grocery distribution networks.
Germany
Fresh produce retailers have committed to biodegradable packaging pilots across 2,000 SKUs by 2025, pressuring converters to solve moisture barrier limitations. EU F-Gas Regulation phase-down deadlines are forcing migration from fluorinated barrier films to silicon oxide vapor-deposited alternatives ahead of 2025 enforcement. The Baden-Württemberg industrial cluster hosts specialized extruders installing compostable coating lines.
China
E-commerce platforms are deploying connected packaging for return fraud prevention in high-value electronics shipments. GB standards on food contact materials and MIIT guidelines on wireless communication substrates shape permissible sensor hardware configurations. The Yangtze River Delta concentration around Shanghai dominates printed electronics manufacturing for NFC antennae and conductive ink deposition.
India
Biologics distributors lack systematic temperature logging infrastructure, creating demand for low-cost disposable sensors with cloud-linked alert systems. CDSCO cold chain documentation requirements for vaccine distribution are accelerating validation programs for alternative substrate materials. The Maharashtra pharmaceutical manufacturing belt around Mumbai and Pune represents the primary deployment zone for pilot cold chain tracking programs.
Brazil
Perishable goods wholesalers are adopting QR-code traceability to satisfy retailer audit requirements for agricultural export compliance. ANVISA pharmaceutical distribution regulations are tightening documentation standards for temperature-sensitive products. The São Paulo state industrial corridor hosts converters developing fiber-based substrates for dry goods authentication where flex-crimp durability constraints are less severe.
Smart Retail Packaging Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying sensor hardware and conductive substrates to converters lacking in-house microcontroller programming capabilities. The vendor base organizes into three functional layers: turnkey traceability providers integrating cloud analytics, substrate converters with barrier film expertise, and printed electronics specialists depositing NFC antennae. Consolidation pressure is concentrating procurement relationships as retailers mandate single-source accountability. Dominant competitive moves include backward integration into sensor hardware production and geographic expansion toward Asian pharmaceutical cold chain markets.
Among substrate and integration specialists, Avery Dennison, Sealed Air, and Amcor occupy positions that exemplify divergent strategic archetypes. Avery Dennison represents the component scale tier through RFID inlay manufacturing concentration. Sealed Air sits within the protective packaging intelligence segment with embedded sensing capabilities. Amcor anchors flexible format competition across connected closure applications. These three manufacturers collectively illustrate how supply concentration in UHF inlay capacity creates procurement leverage dynamics for downstream retail chains.
| Leading Market Players |
|---|
| Avery Dennison |
| Sealed Air |
| Amcor |
| Smurfit Kappa |
| Mondi Group |
| WestRock |
| Tetra Pak |
| DS Smith |
| Graphic Packaging International |
| Others |
Value Network & Pricing Analysis
Undercapacity at European compostable barrier coating lines is compressing lead times and elevating supplier pricing power against German supermarket chains facing EU Green Deal deadlines. This utilization squeeze simultaneously rewards early-mover converters with volume commitments while forcing late adopters toward premium spot-market sourcing.
Pricing Analysis
The customization-premium spread between configured-to-order RFID inlays and standard QR-code implementations spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on certification grade for FDA food contact compliance and volume scale in annual tag procurement. Cost compression in printed electronics is intensifying because conductive ink deposition speed gains have outpaced silver price volatility. Mass-market grocery chains exhibit highest price sensitivity, whereas pharmaceutical cold chain operators absorb premium pricing for validated sensor documentation.
Supply Chain Analysis
Upstream silver conductive ink and UHF antenna substrate supplies draw from China, Germany, and the United States manufacturing clusters. Raw material dependencies center on precious metal feedstocks, polyethylene and polypropylene resins, and cellulose nanofiber pulp. Single-source vulnerability concentrates in RFID inlay manufacturing where three dominant suppliers control capacity allocation. Distribution runs through converter-direct relationships with national retail chains, bypassing traditional packaging distributors for connected packaging implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: EU F-Gas Regulation phase-down deadlines and state-level extended producer responsibility frameworks create compliance barriers that favor incumbent converters with validated certification pathways.
For Market Incumbents: Insulate market position through backward integration into sensor hardware production and captive supply of conductive ink deposition capacity. The threat of printed electronics specialists encroaching on converter margins demands in-house microcontroller programming capabilities to reduce third-party design house dependency. Certification investment in parallel FDA food contact notification and EU EFSA compliance programs extends the moat against mid-size competitors lacking parallel testing infrastructure. For New Entrants and Emerging Players: Establish a beachhead in pharmaceutical cold chain applications across India and Brazil where systematic temperature logging infrastructure remains underdeveloped. The most penetrable segment is low-cost disposable sensors with cloud-linked alert systems for biologics distributors. A direct-to-distributor go-to-market angle bypasses consolidated retail procurement relationships that favor turnkey providers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among turnkey traceability providers integrating sensor hardware, cloud analytics, and compliance documentation under single-source accountability contracts. Long-term viability over the projection horizon favors acquisition targets with validated multi-jurisdiction certification libraries and established relationships with category managers at national grocery chains. The signal to watch is California and New York state-level digital sorting marker mandates that could accelerate NFC adoption or strand existing RFID infrastructure investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captive microcontroller programming capabilities reduce third-party design house dependency and compress development cycles for German supermarket chains. |
| Compostable Barrier Coating Capacity Expansion | Early installation of coating lines ahead of EU Green Deal enforcement deadlines secures volume commitments from pressured fresh produce retailers. |
| Multi-Jurisdiction Certification Investment | Parallel FDA food contact notification and EU EFSA compliance programs accelerate time-to-market for global pharmaceutical cold chain launches. |
| Pharmaceutical Cold Chain Geographic Expansion | Validated sensor documentation for CDSCO cold chain requirements opens biologics distributor relationships across Maharashtra manufacturing belt. |
| Cloud Analytics Platform Integration | Turnkey traceability system performance mandates from US grocery category managers favor providers with integrated cloud-linked alert infrastructure. |
Research Methodology
Operator-level perspectives from packaging converter plant managers, supermarket category buyers, pharmaceutical distribution procurement leads, and printed electronics R&D directors anchored the qualitative base. Primary interviews combined with secondary validation against SEC 10-K filings from substrate manufacturers, EU EFSA compliance documentation databases, and customs records for RFID inlay trade flows. Bottom-up and top-down triangulation cross-checked converter capacity announcements against retailer pilot deployment disclosures.
Scenario-bracketing framed analytical approaches across the analysis window, modeling material substitution timelines against regulatory enforcement schedules and printed electronics cost curve trajectories. Segmentation dimensions included material substrate tier, technology tier, application vertical, and end-user procurement scale. CAGRs were derived from elasticity-adjusted adoption curves incorporating EU F-Gas Regulation phase-down mandates and state-level extended producer responsibility framework emergence.
Stress conditions across silver price volatility, RFID inlay allocation rationing, and biodegradable film moisture barrier performance were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory deadline adherence and converter capacity installation schedules. Cross-checking against retailer pilot deployment announcements and converter capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
Smart Label Market
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Smart Bottle Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Smart Medication Packaging Market