
 Smart Packaging Market | 2026-2036
Smart Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Packaging Market Intelligence
Procurement power from multinational pharmaceutical firms and consumer goods companies is consolidating, creating demand for standardized, high-volume smart packaging solutions. Amcor plc leverages its global manufacturing footprint to serve these large accounts, while Sealed Air Corporation specializes in technologies for food safety and product integrity. Avery Dennison Corporation leads in the development of intelligent label technologies, including RFID and NFC, which are critical for supply chain visibility.
Smart packaging incorporates active or intelligent features into conventional packaging substrates to enhance functionality. These systems utilize embedded components like RFID tags, printed sensors, or time-temperature indicators to monitor freshness, track shipments, or authenticate products. Within the technology segment, NFC and sensor-based solutions are gaining preference over basic QR codes for high-value applications. Demand from pharmaceutical firms is outpacing other sectors, driven by stringent track-and-trace requirements for prescription drugs.
Regulatory frameworks are a primary catalyst for adoption, shaping technical specifications for market entry. The US FDA's rules for food and drug safety, the EU's Falsified Medicines Directive, and China's NMPA standards for medical devices all mandate features enabled by smart packaging. Navigating the trade-offs between advanced functionality, unit cost, and the recyclability of electronic components remains the central strategic challenge for vendors and adopters.
Market Dynamics
The central dynamic shaping the smart packaging market is the requirement to embed digital traceability and authentication into physical supply chains. This pressure, originating from regulators like the FDA and EMA, forces adoption ahead of pure cost-benefit calculations for many firms.
Growth Catalysts
- Regulatory Mandates:The EU's Falsified Medicines Directive and similar track-and-trace laws for pharmaceuticals in the US and China create a non-discretionary need for serialization and authentication features that smart packaging provides.
- Spoilage Reduction:Demand from the food and beverage industry for time-temperature indicators and other freshness sensors is rising to minimize waste in the cold chain and enhance food safety for consumers.
- Technology Maturation:The falling cost and increasing miniaturization of RFID and NFC components make their inclusion economically viable for a wider range of high-value consumer electronics and medical devices.
Market Restraints
- Unit Cost Economics:The incremental cost of adding active or intelligent components to a package remains a significant barrier for high-volume, low-margin fast-moving consumer goods, limiting adoption to premium categories.
- Recycling Complexity:Integrating electronic components into paper and plastic substrates complicates end-of-life processing, creating friction with corporate sustainability goals and circular economy regulations in Europe.
- Infrastructure Gaps:A lack of standardized reader infrastructure and universal data protocols across different logistics networks and retail environments inhibits the seamless interoperability required for widespread adoption.
Strategic Opportunities
- Emerging Geographies:Pharmaceutical supply chains in Latin America and Southeast Asia present significant opportunities for anti-counterfeiting solutions, where regulatory enforcement is strengthening and brand protection is critical.
- High-Value Cosmetics:The luxury cosmetics sector offers a new frontier for smart packaging, enabling product authentication, tracking gray market diversion, and providing interactive consumer experiences via NFC tags.
- Biodegradable Electronics:Developing transient or biodegradable sensors and power sources represents a key opportunity to resolve the conflict between smart functionality and environmental sustainability, appealing to ESG-focused brands.
Industry Challenges
- System Integration:A primary operational hurdle is integrating the massive data volumes generated by smart packages with legacy enterprise resource planning (ERP) and supply chain management (SCM) systems, which often lack compatible APIs.
- Supply Chain Vulnerability:The heavy reliance on a few specialized foundries in Taiwan and South Korea for the advanced semiconductors used in RFID and NFC tags creates significant sourcing risk and price volatility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Packaging Market |
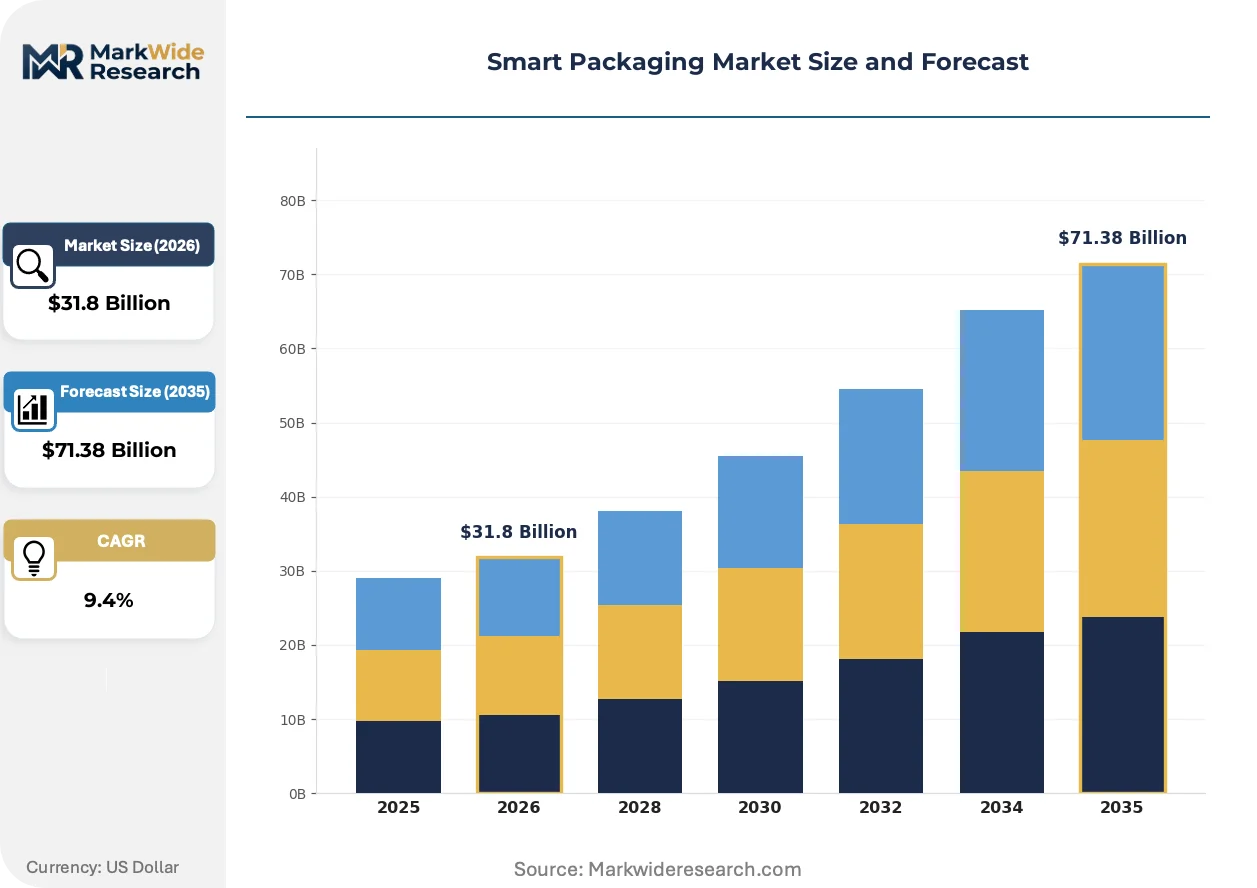
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $71.38 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, QR Code, NFC, Electronic Shelf Labels, Augmented Reality, Sensor-Based Product Type: Active Packaging, Intelligent Labeling, Time-Temperature Indicators, Security Packaging, Tamper-Evident Packaging, Anti-Counterfeit Packaging End User Industry: Pharmaceutical Firms, Food & Beverage Producers, Personal Care Manufacturers, Electronics Brands, Consumer Goods Companies, Luxury Goods Distribution Channel: Direct Sales, E-Commerce Platforms, Wholesalers, Retail Stores, Distributors, Specialty Packaging Suppliers |
| Companies Covered | Amcor plc, Sealed Air Corporation, Avery Dennison Corporation, Ball Corporation, Mondi Group, Huhtamaki Oyj, BASF SE, WestRock Company, CCL Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Packaging Market Strategic Shifts & Innovations
A definitive shift from passive data carriers to active, intelligent systems defines the market's current trajectory. Packaging is evolving from a simple container into a connected device that generates data and interacts with its environment throughout the supply chain.
Printed electronics technology enables the creation of thin, flexible sensors directly on packaging substrates. Pharmaceutical and cold-chain logistics firms are the primary adopters, using these to monitor temperature or humidity on a per-item basis. This on-package intelligence is converging with cloud-based analytics platforms, creating a complete, real-time view of product condition from the factory floor to the final point of use.
Regulatory frameworks increasingly specify the use of technology for compliance. The US FDA’s Food Safety Modernization Act (FSMA), particularly its traceability rules for high-risk foods, compels companies to adopt more advanced tracking methods than manual logs. Consequently, the fresh produce and seafood sectors are accelerating investments in RFID and sensor-based packaging to meet these stringent federal requirements for rapid recall capability.
Consumer goods companies are increasingly adopting direct-to-consumer (D2C) sales models, altering packaging requirements. This shift bypasses traditional retail channels, creating a need for packaging that provides authentication, usage instructions, and reorder functions directly to the end customer. This trend is most visible in North American and European markets, where NFC-enabled labels on pharmaceuticals and high-end products deliver an interactive experience.
Smart Packaging Market Segmentation
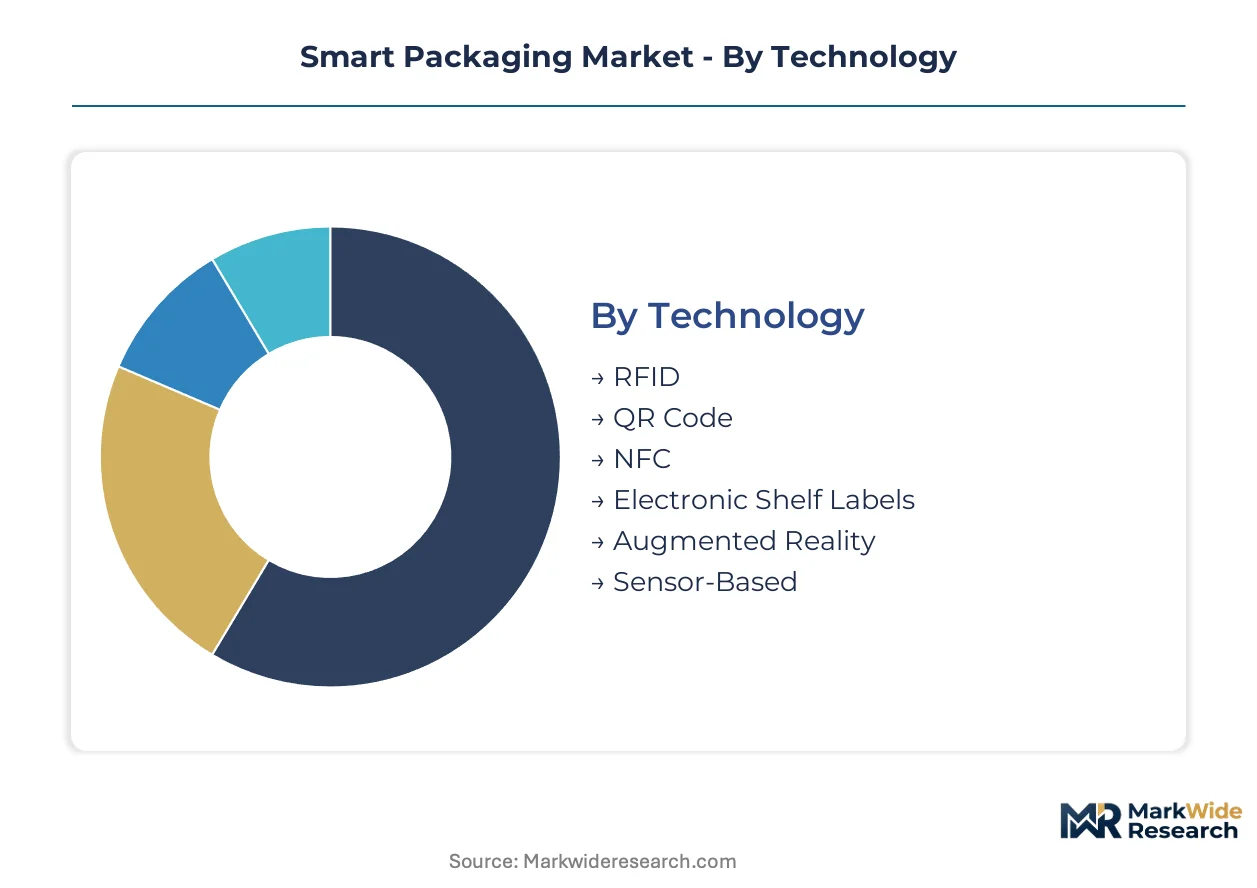
The smart packaging market categorizes solutions based on their core technology, product functionality, end-user application, and channel for market access. This segmentation highlights the diverse demands driving innovation, from regulatory compliance in pharmaceuticals to consumer engagement in luxury goods.
Technology:
The market for smart packaging technology exhibits a clear split between high-volume, cost-sensitive solutions and premium, data-rich applications.
- RFID:Radio-Frequency Identification tags embed microchips and antennas to enable wireless data transfer for inventory management and supply chain visibility. Demand concentrates in logistics operations for electronics and apparel, where efficient tracking of high-value items reduces operational costs.
- Sensor-Based:These solutions integrate printed or embedded sensors to detect environmental changes like temperature, humidity, or gas composition, providing real-time condition monitoring. Pharmaceutical firms and cold chain logistics providers in Germany and South Korea extensively adopt these for critical product integrity.
- QR Code:Quick Response codes offer a low-cost, scannable link to digital content for product information or marketing campaigns.
- NFC:Near Field Communication tags facilitate short-range wireless interactions, popular for product authentication and interactive consumer experiences in Europe.
- Electronic Shelf Labels:Digital displays on retail shelves provide dynamic pricing and product information, primarily used by large grocery chains.
- Augmented Reality:This technology overlays digital information onto physical packaging via smartphone cameras, enhancing consumer engagement in North America.
Today's leader: RFID. Tomorrow's challenger: Sensor-Based.
Product Type:
Smart packaging product types differentiate by their primary function, ranging from extending shelf life to combating counterfeiting across global supply chains.
- Anti-Counterfeit Packaging:These solutions integrate features like holograms, overt/covert inks, or serialized codes to verify product authenticity and deter illicit trade. Pharmaceutical companies in the US and China extensively employ these to meet stringent track-and-trace regulations.
- Active Packaging:This type incorporates components that interact with the product or its environment to extend shelf life or improve food safety. Food and beverage producers in Europe utilize active packaging with oxygen scavengers or moisture absorbers to reduce spoilage.
- Intelligent Labeling:Labels embedded with RFID, NFC, or sensor technologies provide dynamic data for tracking, authentication, or condition monitoring.
- Time-Temperature Indicators:These visual indicators change color irreversibly when exposed to specific temperature thresholds over time, critical for cold chain monitoring.
- Security Packaging:Features designed to prevent tampering or theft, including seals, closures, and overt security elements.
- Tamper-Evident Packaging:Packaging that visibly indicates if a product has been opened or altered before reaching the consumer.
The segment expanding most quickly is Anti-Counterfeit Packaging, driven by escalating regulatory pressures and brand protection needs.
End User Industry:
The smart packaging market's end-user segmentation highlights industries with specific compliance, safety, and consumer engagement requirements, influencing technology adoption rates.
- Pharmaceutical Firms:This sector demands smart packaging for product authentication, serialization, and temperature monitoring to comply with global regulations like the EU's Falsified Medicines Directive. Procurement power from major pharmaceutical firms in Germany and the US drives high-volume, standardized solutions.
- Food & Beverage Producers:These companies adopt smart packaging to extend product shelf life, monitor freshness, and ensure food safety across the cold chain. The US FDA’s Food Safety Modernization Act directly influences investment in sensor-based solutions for fresh produce and seafood.
- Consumer Goods Companies:Brands use smart packaging for product authentication, supply chain visibility, and interactive consumer experiences.
- Electronics Brands:Smart packaging provides anti-theft measures, component tracking, and authenticity verification for high-value electronic devices.
- Luxury Goods:The sector employs smart packaging for brand protection, anti-diversion, and enhancing the premium unboxing experience with NFC tags.
- Personal Care Manufacturers:Companies utilize smart packaging for product authentication, inventory management, and consumer engagement initiatives.
Demand concentration remains with Pharmaceutical Firms, while Luxury Goods offers significant growth potential.
Distribution Channel:
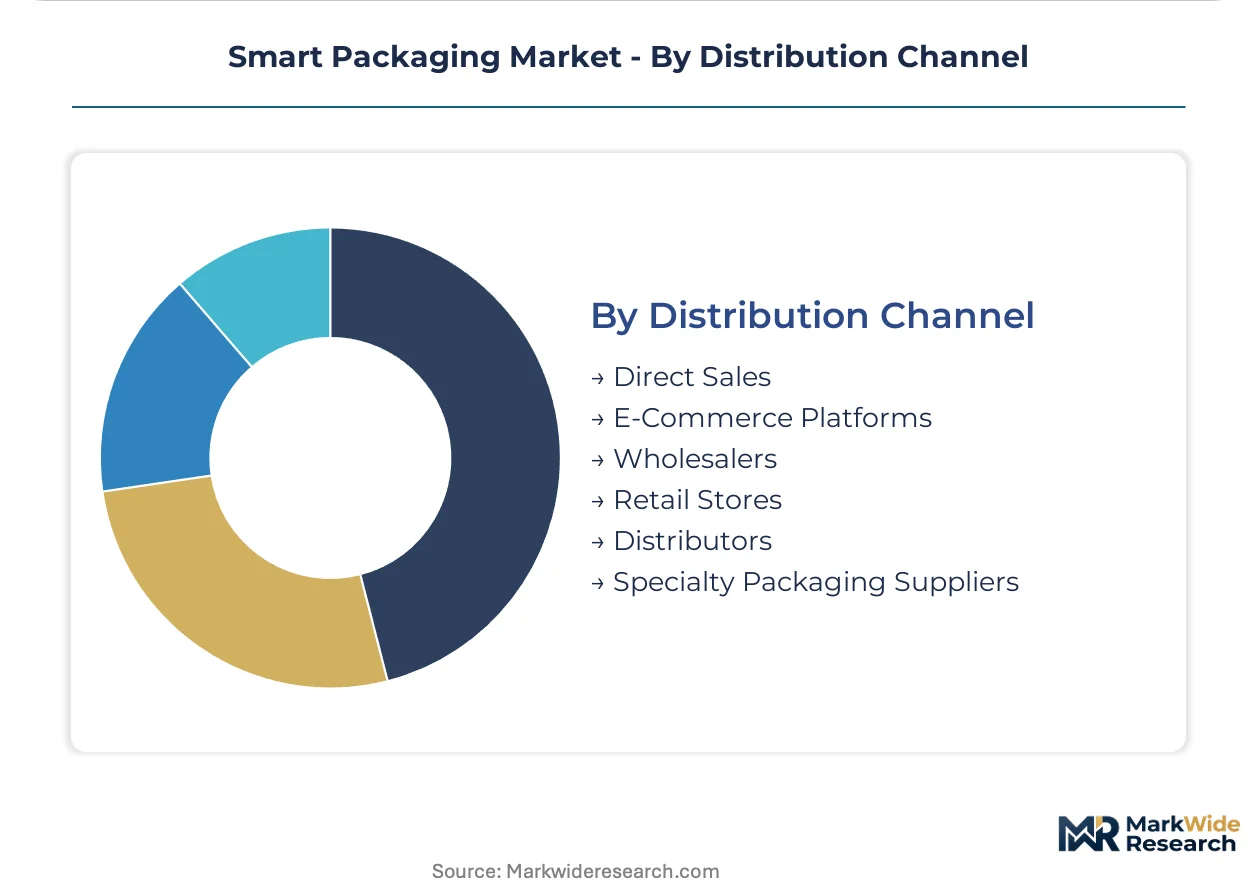
The distribution channel for smart packaging solutions reflects evolving procurement patterns and end-user access models, from traditional supplier relationships to digital platforms.
- Direct Sales:This channel involves direct engagement between smart packaging manufacturers and large enterprise clients, facilitating custom solutions and high-volume contracts. Multinational pharmaceutical firms and major consumer goods companies often prefer this approach for integrated supply chain solutions.
- E-Commerce Platforms:Online marketplaces and specialized B2B platforms serve as a growing channel for smaller smart packaging components or standardized solutions. This channel caters to a broader base of small to medium-sized businesses seeking accessible smart packaging options.
- Wholesalers:These intermediaries aggregate products from multiple manufacturers, offering bulk purchasing options to a wide array of businesses.
- Retail Stores:Smart packaging components are sometimes integrated into retail-ready packaging solutions supplied directly to stores.
- Distributors:Companies specializing in logistics and supply chain management often distribute smart packaging solutions as part of broader service offerings.
- Specialty Packaging Suppliers:Firms focusing on niche packaging requirements provide tailored smart packaging solutions for specific product categories.
The channel experiencing the steepest expansion trajectory is E-Commerce Platforms, due to the increasing digital procurement by diverse businesses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States manufacturers prioritize advanced smart packaging for pharmaceutical and food safety, while German firms focus on high-integrity solutions for cold chain logistics. These distinct regional priorities drive innovation in specific technology segments, reflecting varied regulatory landscapes and industrial strengths. Global demand for smart packaging solutions is concentrating in key manufacturing and consumption hubs.
United States
Pharmaceutical track-and-trace requirements and food safety mandates drive significant smart packaging adoption in the United States. The US FDA's Food Safety Modernization Act (FSMA) compels companies to invest in sensor-based solutions for perishables. Major pharmaceutical firms in the Northeast Corridor and agricultural producers in California are accelerating investments in advanced packaging technologies.
Germany
German industries demand high-precision smart packaging for pharmaceutical integrity and advanced manufacturing supply chains. The EU's Falsified Medicines Directive creates a non-discretionary need for serialization and authentication features. Chemical and automotive clusters in Bavaria and North Rhine-Westphalia integrate intelligent labels for component tracking and anti-counterfeiting measures.
South Korea
South Korean electronics brands and pharmaceutical companies seek smart packaging for supply chain visibility and product authentication. The country's MFDS standards for medical devices encourage the use of advanced monitoring technologies. Technology hubs in the Seoul Capital Area and logistics centers around Busan are key development sites for NFC and sensor-based solutions.
China
China's vast pharmaceutical market and growing e-commerce sector generate substantial demand for anti-counterfeiting and traceability solutions. The NMPA standards for medical devices and increasing consumer protection regulations spur adoption. Manufacturing centers in the Yangtze River Delta and Pearl River Delta are integrating smart packaging for both domestic and export markets.
Smart Packaging Market Key Industry Players
European producers anchor one tier of the smart packaging market, focusing on advanced active and intelligent solutions, while North American specialists hold another, emphasizing high-volume, standardized offerings. The market structure is tiered, featuring large diversified packaging conglomerates alongside niche technology developers. Strategic partnerships for technology integration and portfolio diversification into intelligent labels represent dominant competitive moves.
Global diversified packaging giants like Amcor plc exemplify players offering a broad range of smart packaging solutions across multiple end-user industries. Sealed Air Corporation occupies a position as a specialist in technologies enhancing food safety and product integrity, particularly for cold chain applications. Avery Dennison Corporation anchors the intelligent label segment, providing critical RFID and NFC technologies for supply chain visibility and consumer engagement.
| Leading Market Players |
|---|
| Amcor plc |
| Sealed Air Corporation |
| Avery Dennison Corporation |
| Ball Corporation |
| Mondi Group |
| Huhtamaki Oyj |
| BASF SE |
| WestRock Company |
| CCL Industries Inc. |
| Others |
Cost & Logistics Intelligence
Silicon wafer price index fluctuations directly impact smart packaging component costs, cascading into tiered pricing for advanced solutions. This volatility shapes long-term contract negotiations and procurement strategies for pharmaceutical and electronics firms.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for RFID and NFC tags, influencing the smart packaging market. Pricing primarily operates on a contract-based long-term offtake for large enterprises and per-unit transactional models for smaller clients. Price differentiation stems from customization level, FDA compliance certification, and volume scale. Pricing softness for standardized components reflects increased manufacturing capacity, with high-volume consumer goods companies exhibiting the most price sensitivity, while pharmaceutical firms prioritize compliance over cost.
Supply Chain Analysis
Regional distribution centers for smart packaging components often operate in hub-and-spoke patterns, optimizing delivery to manufacturing hubs. Geographic supply concentrates in Taiwan, South Korea, and China for advanced semiconductors and specialized polymers. The market relies on conductive inks and microchips as critical inputs. Single-source vulnerability for advanced semiconductors creates supply chain risk. Distribution runs through direct sales for multinational pharmaceutical firms and e-commerce platforms for smaller businesses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
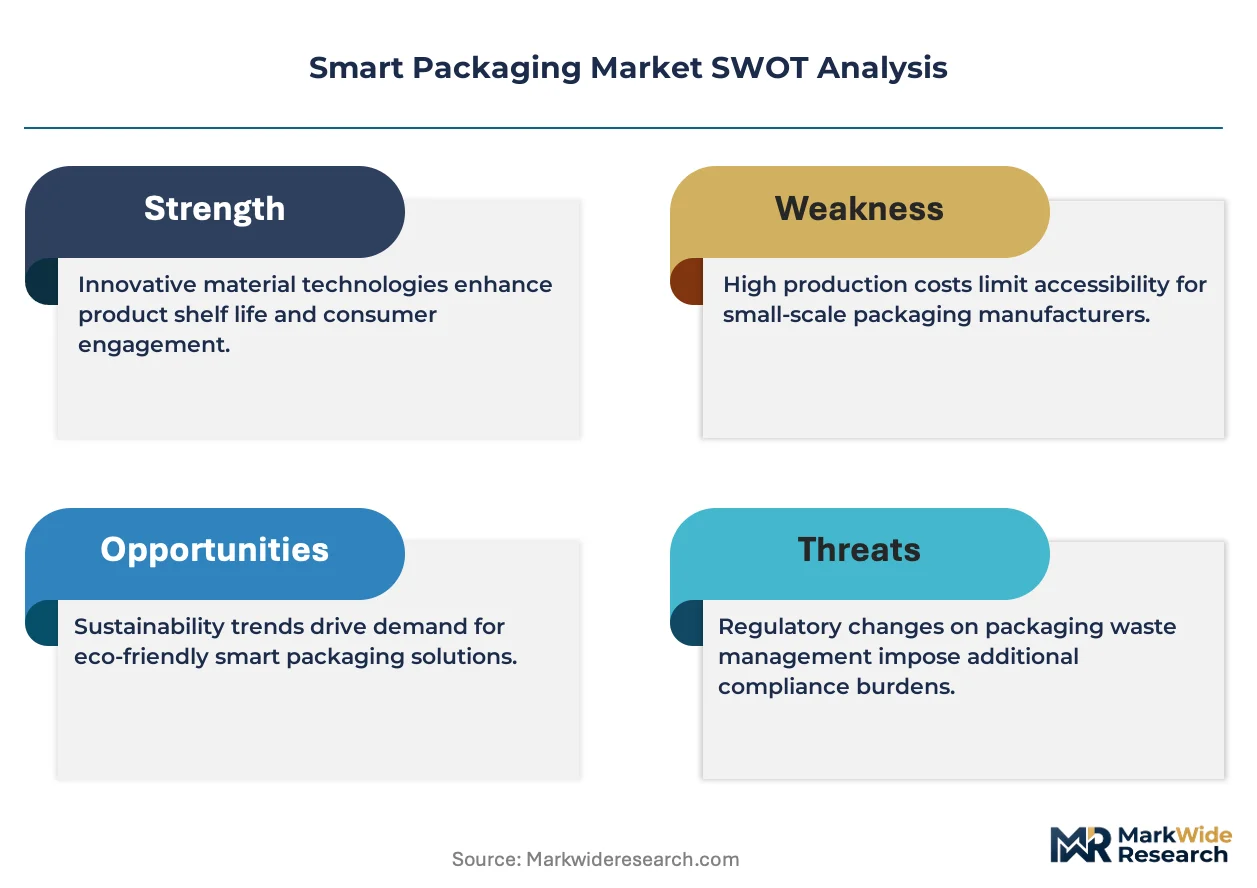
The smart packaging market is entering a late-cycle quality story, driven by a demand-shift toward premium specifications for product authentication and real-time condition monitoring. Regulatory mandates and brand protection needs underscore this transition.
For Market Incumbents: Cement long-term supplier relationships with key pharmaceutical and electronics firms through integrated solution offerings. Invest in advanced R&D for biodegradable electronics to counter recycling complexity, a significant threat. Acquire niche technology developers specializing in sensor miniaturization to maintain a competitive edge against emerging entrants. Expand manufacturing capacity in strategic regions like Germany to better serve regulated markets, addressing regional demand.
For New Entrants and Emerging Players: Printed electronics technology offers a technology-first wedge into specialized applications, particularly for high-value cosmetics and fresh produce. Target underpenetrated segments like luxury cosmetics in Europe, focusing on interactive consumer experiences via NFC tags. Develop cost-effective, sensor-based solutions for cold chain monitoring in emerging geographies. A direct-to-consumer go-to-market angle can bypass established distribution channels.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory compliance costs are high and technology integration is complex. Long-term viability for smart packaging is strong due to non-discretionary regulatory demand. Acquisition targets should be vertically integrated specialists offering novel sensor technologies or robust data analytics platforms. The signal to watch is widespread adoption of biodegradable electronic components, indicating market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expands RFID tag production in Southeast Asia, reducing supply chain vulnerability and serving growing demand in emerging markets. |
| R&D Investment | Develops biodegradable sensor technologies, resolving environmental concerns and aligning with corporate sustainability goals for consumer brands. |
| Strategic Partnership | Forms alliances with cloud analytics providers, enhancing real-time data insights and offering comprehensive traceability solutions to clients. |
| Geographic Expansion | Establishes manufacturing presence in Latin America, addressing anti-counterfeiting needs and strengthening brand protection in new regions. |
| Technology Acquisition | Acquires a specialist in printed electronics, accelerating innovation in flexible, low-cost sensor integration for packaging substrates. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region. This involved combining in-depth interviews with industry stakeholders and secondary validation. Interviews included pharmaceutical procurement managers, packaging R&D directors, and cold chain logistics specialists. Secondary data sources included FDA filings, NMPA standards, and trade association reports, triangulated with bottom-up and top-down market sizing.
Granularity modeling detailed segmentations across technology type, product function, end-user industry, and distribution channel. The analytical framework projected market trajectory across the analysis window by assessing historical trends and future demand drivers. Compound Annual Growth Rates were derived from a weighted average of segment-specific growth rates. Key forecast inputs included regulatory mandate timelines and component miniaturization.
The model holds under current regulatory stability and projected technology maturation; deviation in global trade policies or raw material supply disruptions would shift market dynamics. Forecasts reflect documented assumptions regarding adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Label Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
Smart Bottle Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market