
 Self Cooling Packaging Market | 2026-2036
Self Cooling Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Self Cooling Packaging Market Analytics
Refrigeration-as-a-service pricing for event logistics and pharmaceutical transport is rebalancing how self-cooling packaging generates recurring revenue alongside unit sales. Tempra Technology leverages its phase change material expertise to sustain long-term contracts with beverage distributors. Crown Holdings anchors its position through metal-based container manufacturing scale across North American and European facilities. Icetec differentiates by specializing in compact thermoelectric systems for last-mile pharmaceutical delivery.
Self-cooling packaging encompasses engineered thermal management systems that maintain sub-ambient temperatures without external power, typically employing desiccant-driven evaporative cooling, endothermic chemical reactions, or solid-state thermoelectric modules with specified temperature hold times ranging from two to seventy-two hours. These systems serve critical functions in preserving payload integrity for temperature-sensitive pharmaceuticals, fresh food products, and precision electronics during transit and temporary storage. Active Packaging and Smart Containers represent the leading product categories, with the former capturing established margin pools in pharmaceutical logistics while the latter achieves faster growth through IoT-enabled temperature monitoring and automated compliance reporting. Phase Change Materials dominate current technology deployment due to proven reliability, though Thermoelectric Cooling is expanding fastest as solid-state efficiency improves and unit costs decline for premium pharmaceutical applications.
FDA regulations governing pharmaceutical cold chain integrity, EU GDP guidelines mandating validated temperature-controlled transport, and EPA restrictions on hydrofluorocarbon refrigerants collectively reshape product design priorities and market access requirements for packaging manufacturers. Compliance with these frameworks demands extensive documentation, validated testing protocols, and material traceability that elevate barriers for new entrants while rewarding incumbents with established quality systems. Stakeholders must monitor evolving refrigerant phase-down schedules and emerging battery-electric vehicle compatibility standards to align R&D roadmaps with regulatory trajectories.
Market Dynamics
The EU F-Gas Regulation is forcing pharmaceutical logistics providers to abandon hydrofluorocarbon-dependent cooling systems, compressing the timeline for solid-state thermoelectric alternatives to achieve cost parity with conventional vapor-compression packaging.
Growth Catalysts
- EMA cold chain validation requirements:European pharmaceutical exporters must demonstrate temperature integrity across multi-modal transport, accelerating demand for self-cooling containers with embedded data loggers.
- mRNA vaccine distribution infrastructure:Ultra-low temperature requirements for lipid nanoparticle formulations have created permanent demand for portable -70°C packaging systems beyond pandemic emergency procurement.
- Germany's pharmaceutical export concentration:GDP-compliant logistics hubs in Frankfurt and Munich are driving regional adoption of validated thermal packaging for biologics shipments to Middle Eastern and Asian markets.
Market Restraints
- Bismuth telluride supply concentration:Thermoelectric module manufacturers depend on Chinese rare earth processing for 80% of high-purity bismuth and tellurium feedstock, exposing cost volatility and export restriction risk.
- Phase change material energy density limits:Salt hydrate and paraffin wax systems cannot achieve sub-zero temperatures without excessive mass penalties, constraining payload efficiency for frozen pharmaceutical applications.
- REACH substance authorization timelines:Novel desiccant chemistries face 18-36 month registration delays before commercial deployment in European consumer beverage packaging.
Strategic Opportunities
- Indian cold chain infrastructure gaps:CDSCO's expanding temperature-sensitive generic drug export requirements and fragmented domestic refrigeration networks create demand for point-of-manufacture cooling solutions.
- Battery-electric vehicle compatibility standards:Emerging NHTSA and EU protocols for auxiliary power draw from electric commercial vehicles enable thermoelectric packaging to tap vehicle battery reserves without dedicated fuel cells.
- Refrigeration-as-a-service contracts:Event logistics and pharmaceutical transport providers are shifting from capital purchase to per-shipment pricing models, unlocking recurring revenue streams for packaging fleet operators.
Industry Challenges
- Thermal engineering talent scarcity:Cross-disciplinary expertise combining phase change material science, thermoelectric device physics, and pharmaceutical regulatory compliance commands premium compensation and extends R&D timelines.
- GDP qualification documentation burden:Each container variant requires 6-12 months of validated stability testing across temperature profiles, humidity ranges, and transit vibration spectra before commercial deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Cooling Packaging Market |
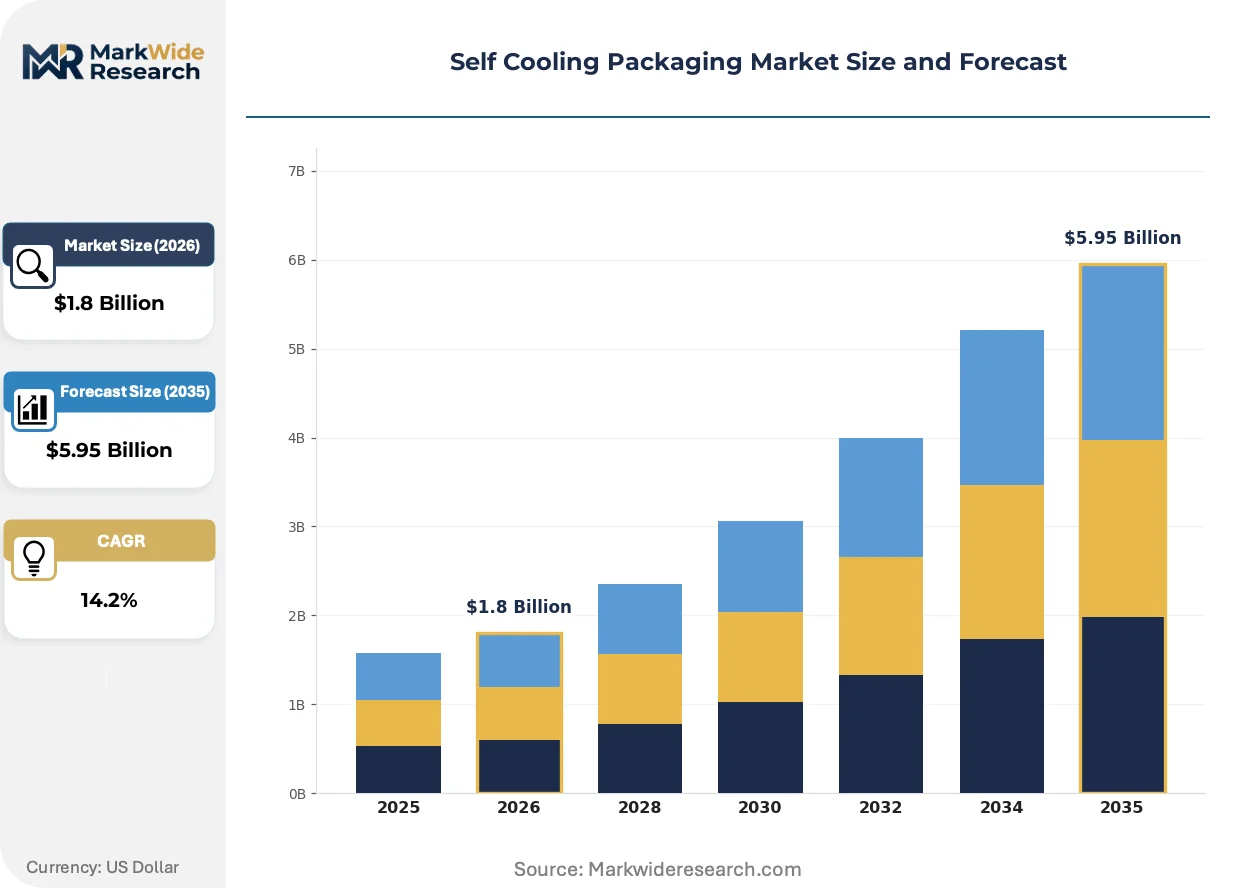
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Packaging, Passive Packaging, Temperature-Controlled Solutions, Smart Containers Technology: Phase Change Materials, Thermoelectric Cooling, Refrigeration Techniques, Insulation Technologies End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Application: Transport, Retail, Warehousing, Event Logistics |
| Companies Covered | Tempra Technology, Crown Holdings, Icetec, deltaH Innovations, HeatGen LLC, Luxfer Magtech, The 42 Degrees Company, Hydropac, NanoCool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Cooling Packaging Market Evolving Landscape
Solid-state cooling architectures are displacing passive phase change systems across premium pharmaceutical applications, while regulatory refrigerant phase-downs compress the viable design space for conventional compressor-based portable units.
Thermoelectric cooling modules paired with lithium-ion battery packs are consolidating technical validation pathways for last-mile pharmaceutical delivery. Cold chain logistics providers in Germany and Switzerland are adopting these systems for urban same-day biologics transport. The technology is consolidating supplier relationships around integrated battery-thermal module vendors capable of delivering complete qualified subsystems rather than discrete components.
The EU F-Gas Regulation's accelerated hydrofluorocarbon phase-down schedule is eliminating R-134a and R-404A from new transport refrigeration equipment. Packaging manufacturers serving European pharmaceutical exporters must redesign vapor-compression prototypes around HFO-1234yf or hydrocarbon alternatives. German GDP auditors are already rejecting validation protocols for legacy refrigerant systems in multi-modal container qualifications.
Hospital and clinic procurement departments are unbundling temperature monitoring from physical container supply, creating separate vendor relationships for IoT-enabled data loggers versus thermal packaging hardware. Pharmaceutical distributors in the United States are driving this fragmentation through FDA 21 CFR Part 11 compliance requirements for electronic records. The shift is most pronounced in oncology and rare disease therapeutic categories where temperature excursion liability exceeds container capital cost by orders of magnitude.
Self Cooling Packaging Market Segmentation
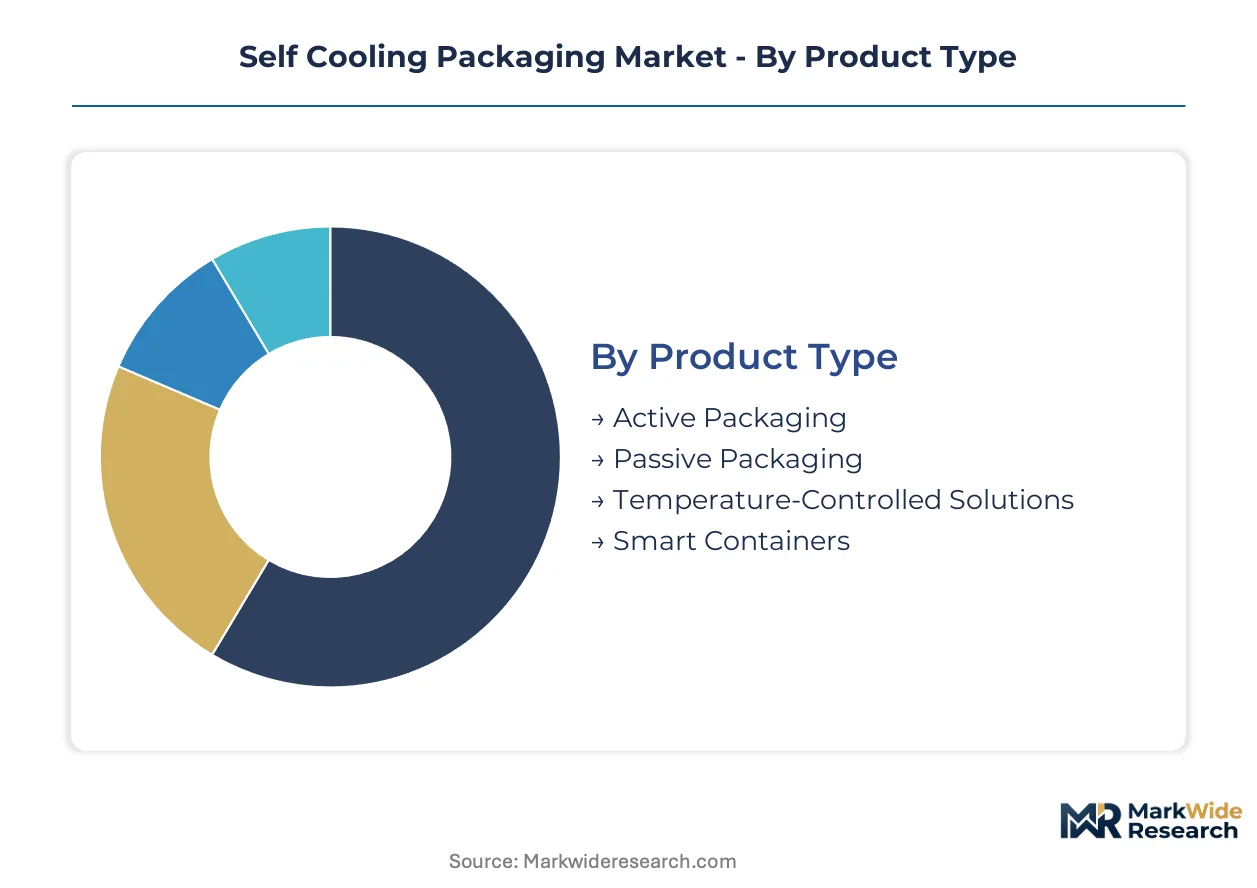
Self-cooling packaging segments map directly to divergent regulatory burdens and performance thresholds across pharmaceutical, food, and electronics verticals. Technology choices determine whether suppliers compete on unit economics or premium qualification timelines.
Product Type:
Supply concentration tilts toward qualified pharmaceutical container manufacturers with established GDP documentation systems.
- Active Packaging:Engineered systems with powered cooling elements, battery management, and integrated temperature logging. Demand clusters in German biologics exports where EMA validation requirements mandate continuous thermal monitoring. GDP auditors in Frankfurt and Munich reject passive alternatives for high-value mRNA shipments.
- Smart Containers:IoT-enabled units with real-time telemetry, automated compliance reporting, and blockchain-secured chain-of-custody records. Swissmedic and FDA 21 CFR Part 11 requirements are concentrating procurement among oncology distributors where temperature excursion liability dwarfs hardware costs. These units gain share fastest in last-mile pharmaceutical networks.
- Passive Packaging:Insulated containers relying on pre-conditioned phase change materials without active power.
- Temperature-Controlled Solutions:Hybrid systems combining passive insulation with limited active intervention.
Today's leader: Active Packaging. Tomorrow's challenger: Smart Containers.
Technology:
Cost tier separation runs widest between mature phase change systems and emerging solid-state alternatives.
- Phase Change Materials:Salt hydrate and paraffin wax formulations store latent heat at specified temperatures through solid-liquid transitions. Paraffin dominates European food logistics where REACH authorization timelines delay novel desiccant chemistries. Salt hydrates face payload efficiency constraints for sub-zero pharmaceutical applications.
- Thermoelectric Cooling:Solid-state Peltier modules generating temperature differentials through electrical current across bismuth telluride junctions. CDSCO's expanding temperature-sensitive export requirements and India's fragmented cold chain infrastructure are driving point-of-manufacture adoption. Bismuth and tellurium supply concentration in Chinese rare earth processing creates cost volatility exposure.
- Refrigeration Techniques:Vapor-compression systems using HFO-1234yf or hydrocarbon refrigerants post EU F-Gas Regulation phase-down.
- Insulation Technologies:Vacuum-insulated panels and advanced aerogel barriers extending passive hold durations.
Phase Change Materials anchor current volume. Thermoelectric Cooling climbs the fastest as solid-state efficiency improves.
End User:
Application intensity varies sharply across customer types with divergent compliance maturity.
- Pharmaceuticals:Temperature-sensitive biologics, vaccines, and precision therapeutics requiring validated cold chain integrity. Ultra-low temperature demands for lipid nanoparticle formulations have entrenched portable -70°C packaging demand beyond emergency procurement cycles. German export concentration and GDP compliance requirements sustain premium pricing.
- Food & Beverage:Fresh produce, dairy, and prepared meals requiring maintenance of chill chains without freezing.
- Cosmetics:Active ingredient formulations sensitive to thermal degradation during transit.
- Electronics:Precision components and semiconductor devices requiring stable thermal environments.
Pharmaceuticals command margin concentration. Food & Beverage offers volume scale.
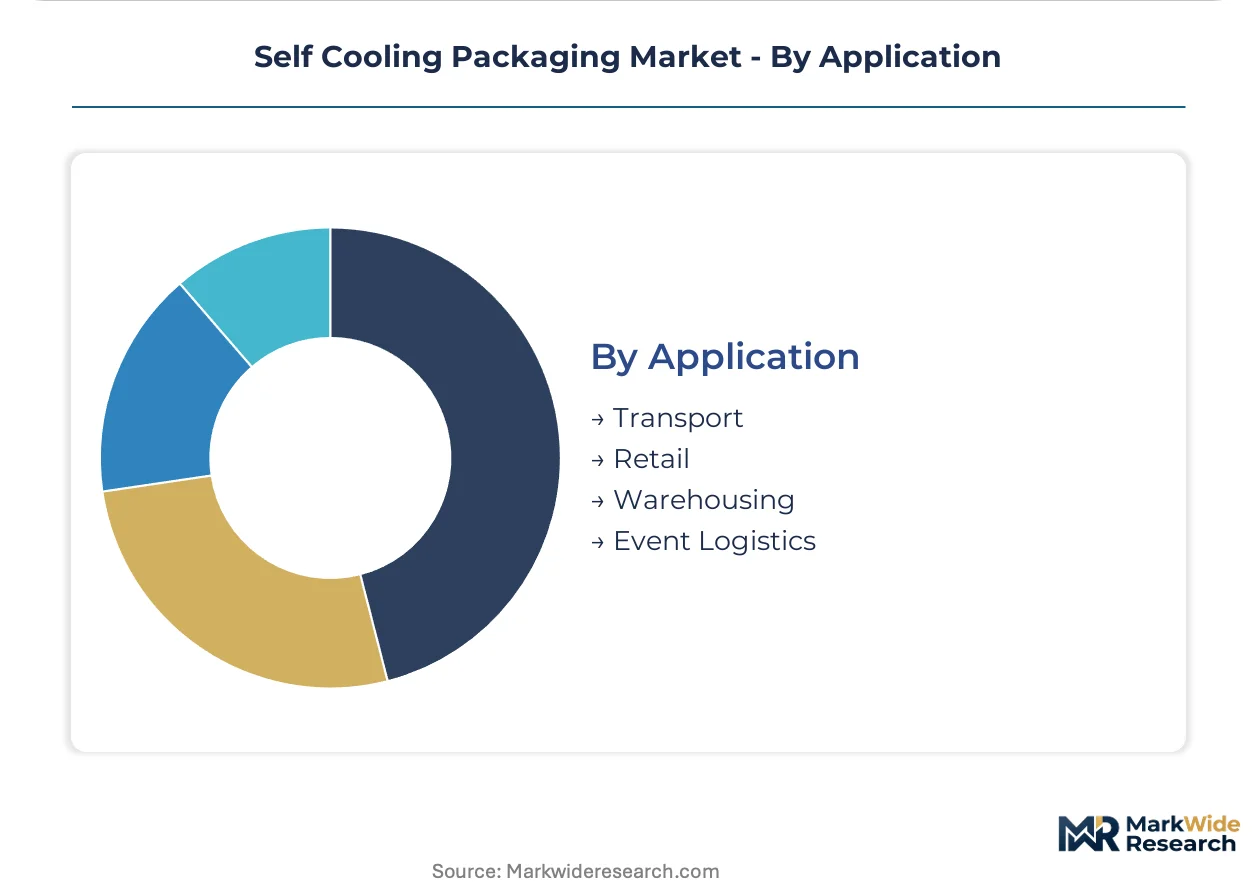
Application:
Customer type fragmentation separates capital purchasers from refrigeration-as-a-service subscribers.
- Transport:Multi-modal container systems spanning air freight, ocean, and ground distribution. EMA cold chain validation requirements for European pharmaceutical exporters mandate temperature integrity documentation across handoffs. German logistics hubs in Frankfurt and Munich drive regional adoption for Middle Eastern and Asian market shipments.
- Event Logistics:Temporary cooling for outdoor catering, sporting events, and entertainment venues. Per-shipment pricing models are displacing capital purchases among rental fleet operators. Tempra Technology's long-term beverage distributor contracts exemplify recurring revenue extraction.
- Retail:In-store display cooling and customer-facing temperature maintenance.
- Warehousing:Short-term buffer storage without fixed refrigeration infrastructure.
Transport captures established margin pools. Event Logistics shows steepest expansion trajectory through service model conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical export concentration contrasts with India's fragmented cold chain infrastructure, creating divergent adoption pathways for self-cooling packaging across major economies.
Germany
GDP-compliant logistics hubs in Frankfurt and Munich drive demand for validated thermal packaging serving biologics shipments to Middle Eastern and Asian markets. The EU F-Gas Regulation accelerates phase-out of hydrofluorocarbon-dependent cooling systems in transport packaging. Bavaria's pharmaceutical manufacturing clusters anchor regional adoption of solid-state thermoelectric alternatives.
United States
FDA 21 CFR Part 11 compliance requirements for electronic records reshape procurement patterns among oncology and rare disease distributors. The EPA restricts hydrofluorocarbon refrigerants in portable cooling equipment, compressing design timelines for HFO-1234yf alternatives. Cold chain logistics providers in Greater Boston and the San Francisco Bay Area pioneer thermoelectric-battery integration for last-mile delivery.
India
CDSCO's expanding temperature-sensitive generic drug export requirements create demand for point-of-manufacture cooling solutions. The PLI scheme for pharmaceutical manufacturing indirectly supports packaging infrastructure investment. Gujarat's active pharmaceutical ingredient clusters and Maharashtra's formulation hubs drive regional container procurement for export compliance.
Switzerland
Swissmedic requirements for temperature integrity documentation concentrate procurement among high-value biologics distributors. The country's pharmaceutical logistics sector maintains stringent validation protocols exceeding baseline EU standards. Basel's pharmaceutical manufacturing corridor and Zurich's distribution networks sustain premium pricing for qualified container systems.
China
NMPA cold chain regulations for domestic vaccine distribution expand addressable market for portable cooling systems. Dual carbon goals pressure manufacturers toward solid-state alternatives to vapor-compression equipment. Yangtze River Delta pharmaceutical clusters and Pearl River Delta logistics hubs represent concentrated demand centers for thermoelectric packaging.
Self Cooling Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with qualification-heavy pharmaceutical applications favoring established documentation systems while event logistics reward flexible rental fleet operators. The vendor base organizes around three strategic archetypes: integrated metal packaging conglomerates with manufacturing scale, phase change material specialists with long-term service contracts, and compact thermoelectric system developers targeting last-mile pharmaceutical delivery. Competitive moves center on refrigeration-as-a-service model conversion and vertical integration into battery-thermal module subsystems.
Within the phase change material tier, Tempra Technology exemplifies recurring revenue extraction through beverage distributor contracts. Crown Holdings occupies a position among metal-based container manufacturers with North American and European facility networks. Icetec anchors the compact thermoelectric specialization vector for pharmaceutical last-mile applications.
| Leading Market Players |
|---|
| Tempra Technology |
| Crown Holdings |
| Icetec |
| deltaH Innovations |
| HeatGen LLC |
| Luxfer Magtech |
| The 42 Degrees Company |
| Hydropac |
| NanoCool |
| Others |
Value Network & Pricing Analysis
The EU F-Gas Regulation's hydrofluorocarbon phase-down gates qualified supply access and premium-tier pricing power, as German GDP auditors reject validation protocols for legacy refrigerant systems while rewarding solid-state alternatives with documented environmental compliance. Pharmaceutical cold chain logistics providers face bifurcated sourcing economics: qualified container manufacturers with established EMA documentation command sustained margin premiums, while event logistics operators compete on per-shipment service pricing with compressed hardware margins.
Pricing Analysis
Capacity additions in China's Yangtze River Delta thermoelectric module manufacturing are reshaping price floors for solid-state cooling systems, compressing premiums previously captured by European specialists. Three-tier pricing structure across GDP-validated pharmaceutical containers, standard commercial units, and economy event logistics hardware separates certification-grade documentation from basic thermal performance. Cost compression in the economy tier is intensifying because Indian CDSCO export requirements are pulling manufacturing investment toward lower-cost production hubs. Oncology distributors exhibit the lowest price sensitivity due to temperature excursion liability exposure, while beverage rental fleet operators face acute margin pressure from per-shipment pricing model conversion.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for pharmaceutical packaging serving export markets, redirecting procurement toward Gujarat and Maharashtra manufacturing clusters. Bismuth telluride feedstock draws from Chinese rare earth processing, lithium-ion battery cells source from South Korean and Japanese cell manufacturers, and vacuum-insulated panels concentrate in German and Swiss specialty materials firms. Single-source vulnerability in bismuth and tellurium supply creates cost volatility exposure for thermoelectric module assemblers. Distribution runs through qualified logistics providers in Frankfurt, Mumbai, and Basel who maintain GDP-compliant handling protocols for high-value biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where EMA cold chain validation requirements and FDA 21 CFR Part 11 compliance are shifting procurement toward premium specifications with embedded IoT telemetry and automated compliance reporting.
For Market Incumbents: Acquire battery-thermal module subsystem capabilities to consolidate supplier relationships around integrated qualified subsystems rather than discrete components. Secure backward integration into phase change material chemistry or bismuth telluride sourcing to defend margin position against Chinese rare earth export restriction risk. Crown Holdings and Tempra Technology archetypes should extend manufacturing scale advantages through captive supply of critical thermal components. For New Entrants and Emerging Players: Enter via India's fragmented cold chain infrastructure where CDSCO temperature-sensitive export requirements and domestic refrigeration network gaps create point-of-manufacture cooling demand. Target event logistics refrigeration-as-a-service contracts where per-shipment pricing models displace capital purchases and flexible rental fleet operations reward agile entrants. Pursue Swissmedic-tier validation documentation as a go-to-market wedge into high-margin oncology distribution channels. For Investors and Strategic Acquirers: Roll-up economics work for qualified pharmaceutical container specialists because GDP qualification documentation burdens create six-to-twelve month validation timelines that elevate barriers for new entrants while rewarding incumbents with established quality systems. Focus acquisition screening on firms with embedded IoT telemetry capabilities and blockchain-secured chain-of-custody records. Watch for inflection in battery-electric vehicle auxiliary power draw standards enabling thermoelectric packaging to tap vehicle battery reserves.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Validation Documentation Investment | EMA auditors in Frankfurt and Munich reject passive alternatives for high-value mRNA shipments without continuous thermal monitoring records. |
| Battery-Thermal Module Integration | Cold chain logistics providers in Greater Boston and the San Francisco Bay Area consolidate procurement around complete qualified subsystems. |
| Refrigeration-as-a-Service Model Conversion | Tempra Technology's long-term beverage distributor contracts demonstrate recurring revenue extraction from per-shipment pricing. |
| Solid-State Cooling Architecture Transition | German GDP auditors already reject validation protocols for legacy hydrofluorocarbon refrigerant systems in multi-modal container qualifications. |
| Indian Manufacturing Footprint Establishment | Gujarat's active pharmaceutical ingredient clusters and Maharashtra's formulation hubs drive regional container procurement for CDSCO export compliance. |
Research Methodology
Multiple input streams — primary interviews with cold chain logistics executives, pharmaceutical regulatory affairs leads, and thermal packaging procurement managers; secondary validation through EMA submission databases, FDA 21 CFR Part 11 guidance documents, and EU F-Gas Regulation implementation schedules; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned German GDP-compliant logistics hubs, Swissmedic-authorized distribution networks, and Indian CDSCO export compliance officers.
Historical shipment data cross-referenced against panel input from packaging fleet operators and pharmaceutical distributors anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included product type, cooling technology, end-use vertical, application mode, and regional regulatory cluster. CAGRs were derived from unit economics analysis of active packaging versus smart container deployment, with specific inputs from thermoelectric efficiency improvement curves and phase change material energy density constraints.
Inputs from EMA qualification protocols and GDP auditor inspection records were available through the study window; gaps in real-time pricing data for refrigeration-as-a-service contracts introduce uncertainty bands around service revenue projections. Forecasts reflect assumptions regarding EU F-Gas Regulation enforcement timelines and Chinese rare earth export policy continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Global Spoil Detection-Based Smart Label Market
Smart Packaging
Global Nano Enabled Packaging Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Smart Label Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Smart Bottle Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Smart Packaging Market