
 Global Spoil Detection-Based Smart Label Market | 2026-2036
Global Spoil Detection-Based Smart Label Market Size, Share, and Industry Trends Forecast 2026-2036
Global Spoil Detection-Based Smart Label Market Analysis
The EU Green Deal is shifting procurement criteria across European fresh food retail, compelling suppliers to demonstrate verifiable spoilage prevention. Avery Dennison Corporation leverages its materials science portfolio to integrate temperature-responsive chemistry directly into adhesive substrates. Zebra Technologies dominates enterprise-grade printing and encoding infrastructure that activates smart labels at scale. Evigence Sensors specializes in color-metric time-temperature indicators that require no electronic reader, extending access to cost-sensitive supply chain nodes.
Spoil detection-based smart labels comprise multi-layer substrates incorporating sensor elements that undergo irreversible visual or electronic state changes when cumulative thermal exposure, humidity excursions, or volatile organic compound thresholds breach programmed limits, typically operating between minus 30°C and 60°C with accuracy margins of plus or minus 0.5°C. Their primary commercial purpose is to replace static expiration dates with dynamic freshness signaling, reducing food waste and liability exposure across temperature-sensitive value chains. Chemical indicators occupy the largest volume share due to minimal unit cost and zero infrastructure requirements, while RFID tags represent the fastest-expanding value pool as pharmaceutical serialization mandates and automated warehouse robotics proliferate. NFC-enabled labels within wireless communication technology concentrate margin capture in premium consumer engagement applications where brand owners fund per-unit premiums for direct-to-smartphone traceability.
FDA food safety modernization requirements in the United States, EFSA contact material regulations under the EU framework, and China's GB standards administered by SAMR collectively elevate barrier-to-entry for substrate and sensor chemistry suppliers. These bodies enforce migration limits, biocompatibility testing, and traceability documentation that shape product development roadmaps and determine market access eligibility. Stakeholders must monitor divergence between electromagnetic spectrum allocation for RFID in major economies and emerging biodegradability certification schemes that threaten to obsolete conventional polymer-based label constructions.
Market Dynamics
The EU Green Deal's packaging sustainability mandates are compressing development cycles for biodegradable substrates while simultaneously demanding higher sensor reliability, creating a structural tension between material innovation and performance verification that reshapes supplier R&D roadmaps.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory biodegradability thresholds for food-contact materials are forcing substrate manufacturers to reformulate adhesives and barrier layers, expanding addressable demand for compliant smart label chemistries.
- Cold-chain logistics density:Germany's refrigerated transport network concentration creates deployment clusters where RFID-enabled spoil detection achieves economies of scale through shared reader infrastructure across pharmaceutical and fresh food verticals.
- FDA Food Safety Modernization Act:Enhanced traceability requirements for high-risk foods are compelling US retailers to replace static date codes with dynamic temperature-logging labels that document chain-of-custody.
Market Restraints
- Sensor chemistry input volatility:Rare earth elements and specialized chromogenic compounds face supply concentration from Chinese processing facilities, exposing label manufacturers to price swings and quota risks.
- Biodegradability-performance trade-off:Current biodegradable substrates exhibit inferior moisture barrier properties versus conventional polymers, limiting deployment in high-humidity supply chain segments.
- RFID spectrum fragmentation:Divergent electromagnetic allocation between FCC (United States), ETSI (Europe), and MIIT (China) regimes forces multi-region suppliers to maintain distinct product SKUs, inflating inventory carrying costs.
Strategic Opportunities
- India's cold-chain infrastructure buildout:FSSAI mandatory cold storage requirements for dairy and pharmaceuticals create first-mover advantage for low-cost color-metric indicators that bypass reader infrastructure dependencies.
- Cellular-IoT convergence:Integration of low-power wide-area connectivity with disposable labels enables real-time spoilage alerts without smartphone proximity, opening pharmaceutical distribution monitoring applications.
- Extended Producer Responsibility expansion:France's AGEC law and similar frameworks in Italy and Spain impose packaging waste fees that favor smart labels enabling precise consumption-timing, reducing premature disposal.
Industry Challenges
- Multiphysics simulation talent scarcity:Designing temperature-responsive chemistries requires combined expertise in polymer science, microfluidics, and thermal modeling that concentrates in a handful of academic-industry crossover specialists.
- Legacy ERP integration friction:Enterprise fresh food retailers operate warehouse management systems that cannot ingest dynamic freshness data streams, forcing parallel data architectures and reconciliation overhead.
- Migration testing timeline compression:EFSA and FDA food-contact notification reviews now exceed eighteen months for novel biodegradable substrates, delaying revenue recognition for reformulated products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Spoil Detection-Based Smart Label Market |
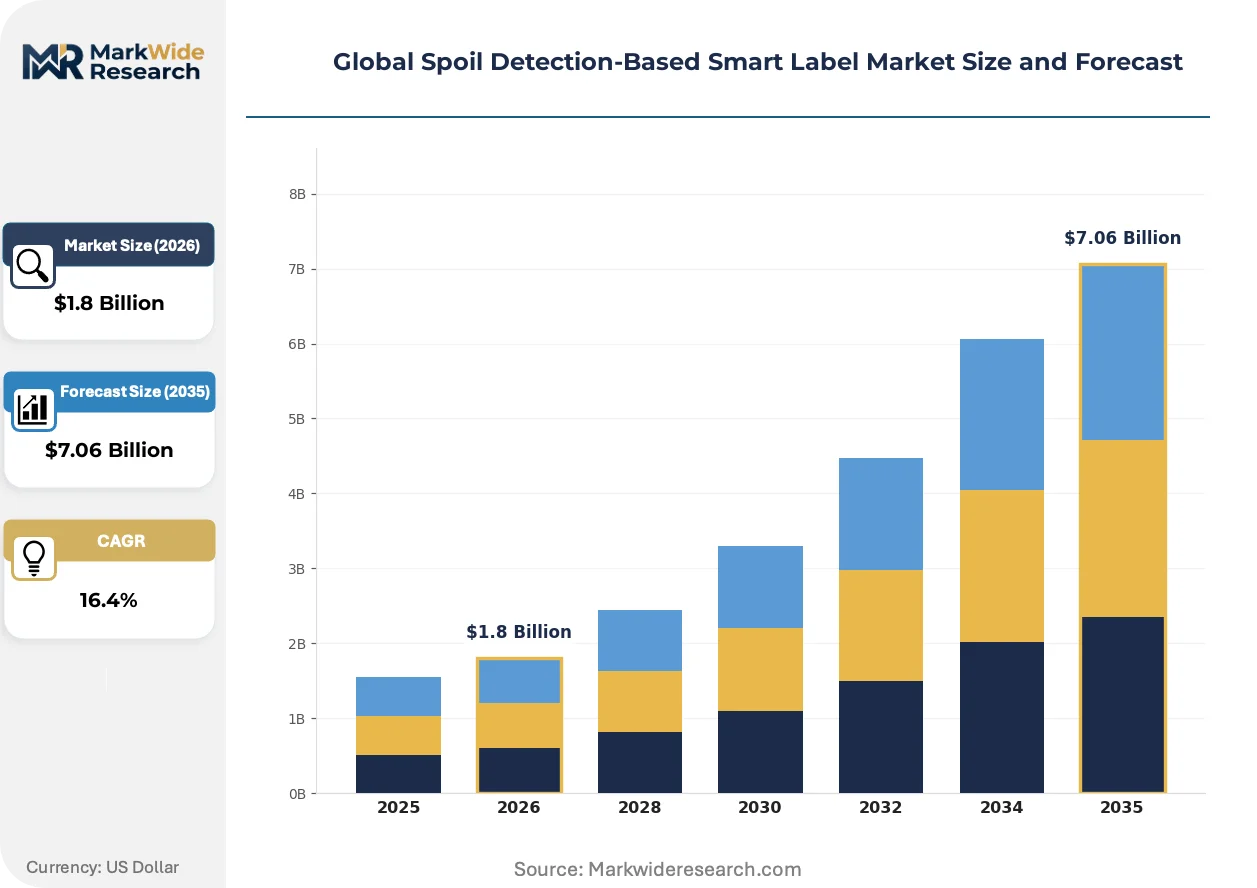
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Humidity Sensors, RFID Tags, Chemical Indicators End User: Food Processing, Retail, Pharmaceuticals, Logistics Technology: Wireless Communication, NFC, QR Code, Bluetooth Low Energy Application: Supply Chain Management, Inventory Tracking, Quality Control, Consumer Engagement |
| Companies Covered | Avery Dennison Corporation, Zebra Technologies, Evigence Sensors, Insignia Technologies, SpotSee, Innoscentia, Impinj, NXP Semiconductors, Sato Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Spoil Detection-Based Smart Label Market Emerging Trajectories
Machine-readable freshness signaling is displacing human-interpreted date codes across temperature-sensitive value chains, with adoption velocity determined by regulatory mandate timing rather than pure commercial preference.
Printed electronics incorporating conductive inks and microencapsulated leuco dyes are automating spoilage detection at unit cost levels approaching conventional barcodes. Pharmaceutical distributors in Germany and the Netherlands are deploying these labels at scale for insulin and biologics shipments. The technology is automating compliance documentation that previously required manual temperature logger retrieval and data transcription.
REACH substance restriction expansions under the EU framework are banning specific phthalate plasticizers and bisphenol derivatives commonly used in label adhesives and thermal coatings. Industrial consequence includes forced reformulation of time-temperature indicator chemistries and substrate laminates. Pharmaceutical serialization applications in France and Benelux markets are most affected, with suppliers accelerating substitution testing to maintain MDR compliance timelines.
Retailer private-label procurement teams are consolidating smart label specifications into master agreements that span multiple fresh food categories, displacing category-specific sourcing. This concentration forces label converters to bid on multi-year, multi-SKU contracts with stringent performance guarantees. The pattern is most visible in UK and Nordic grocery retail, where Tesco, Sainsbury's, and ICA Gruppen have centralized technical specification authority.
Global Spoil Detection-Based Smart Label Market Segmentation
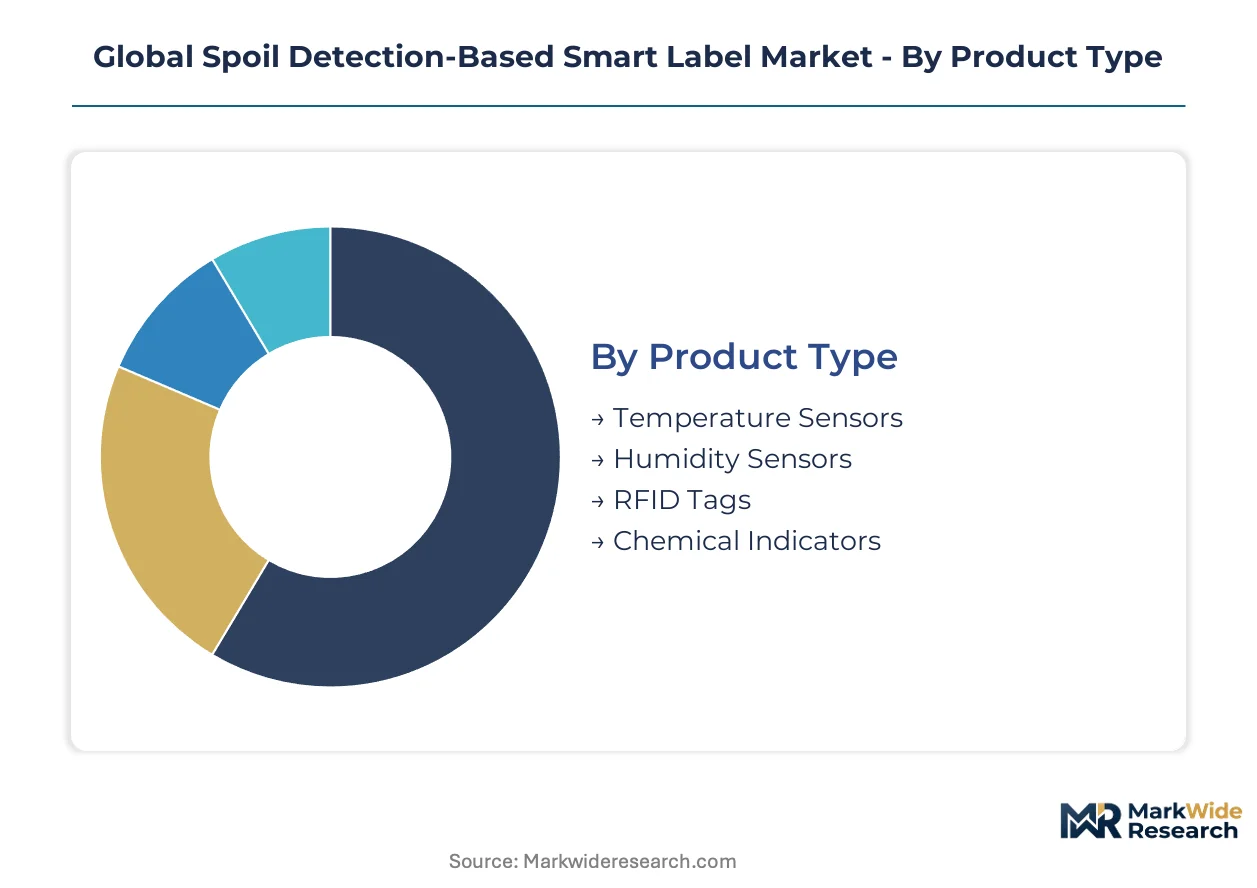
Spoil detection-based smart labels serve divergent supply chain nodes with incompatible cost and performance requirements. Chemical indicators dominate unit volume in emerging cold chains, while RFID-enabled systems capture premium value in automated pharmaceutical distribution. Understanding these segment boundaries determines supplier resource allocation and partnership targeting.
Product Type:
Chemical indicators anchor the volume base through zero-infrastructure deployment, while RFID tags command premium pricing through automated data capture capabilities.
- Chemical Indicators:Multi-layer substrates incorporating microencapsulated leuco dyes or enzymatic reactions that undergo irreversible color shifts when cumulative thermal exposure breaches programmed thresholds. Demand concentrates in India's dairy sector under FSSAI cold storage mandates, where unit economics must accommodate fragmented last-mile distribution without reader hardware.
- RFID Tags:Inlay constructions combining antenna substrates with temperature-logging integrated circuits that communicate via UHF or NFC protocols. Germany's pharmaceutical serialization requirements under EU MDR drive deployment density, with shared reader infrastructure across insulin and biologics distribution achieving economies of scale.
- Temperature Sensors:Printed electronics with conductive polymer traces that modulate resistance across calibrated thermal ranges.
- Humidity Sensors:Hygroscopic substrate layers that swell or conduct differentially when moisture vapor transmission exceeds thresholds.
Today's leader: Chemical Indicators. Tomorrow's challenger: RFID Tags.
End User:
Retail procurement consolidation is compressing supplier margins, while pharmaceutical traceability mandates create protected pricing corridors for compliant label technologies.
- Pharmaceuticals:Serialization-compliant labels documenting chain-of-custody for temperature-sensitive biologics, insulin, and vaccines. EU MDR and FDA DSCSA requirements in the United States compel investment in automated temperature logging that replaces manual logger retrieval. REACH substance restrictions are forcing adhesive reformulation timelines that disadvantage non-specialized converters.
- Retail:Private-label fresh food categories deploying dynamic freshness signaling to replace static expiration dates and reduce shrink. UK grocers including Tesco and Sainsbury's have centralized technical specifications across produce, meat, and dairy, demanding multi-year performance guarantees that strain converter working capital.
- Food Processing:In-plant quality control applications verifying thermal processing adequacy and cold-chain handoff integrity.
- Logistics:Third-party cold-chain operators documenting custody transfers without smartphone-dependent consumer engagement.
Pharmaceuticals currently extract the highest per-unit premiums. Retail offers the steepest expansion trajectory through private-label consolidation.
Technology:
Proximity-dependent protocols dominate current deployment, while emerging wide-area connectivity promises real-time alerting without infrastructure proximity.
- NFC:Near-field communication inlays enabling smartphone-tap consumer engagement and brand-direct traceability. Premium food brands in France and Benelux fund per-unit premiums for direct-to-consumer freshness verification, though AGEC law packaging waste fees are compressing acceptable cost ceilings.
- Wireless Communication:Cellular-IoT and LPWAN integrations enabling real-time spoilage alerts across extended distribution corridors. Pharmaceutical distributors in the Netherlands pilot these systems for transcontinental biologics monitoring where smartphone proximity cannot be assumed.
- QR Code:Static optical codes linking to dynamic freshness databases with minimal substrate cost.
- Bluetooth Low Energy:Beacon-enabled labels transmitting temperature logs to intermediate gateway devices.
NFC holds current margin concentration. Wireless Communication is gaining share fastest through pharmaceutical distribution automation.
Application:
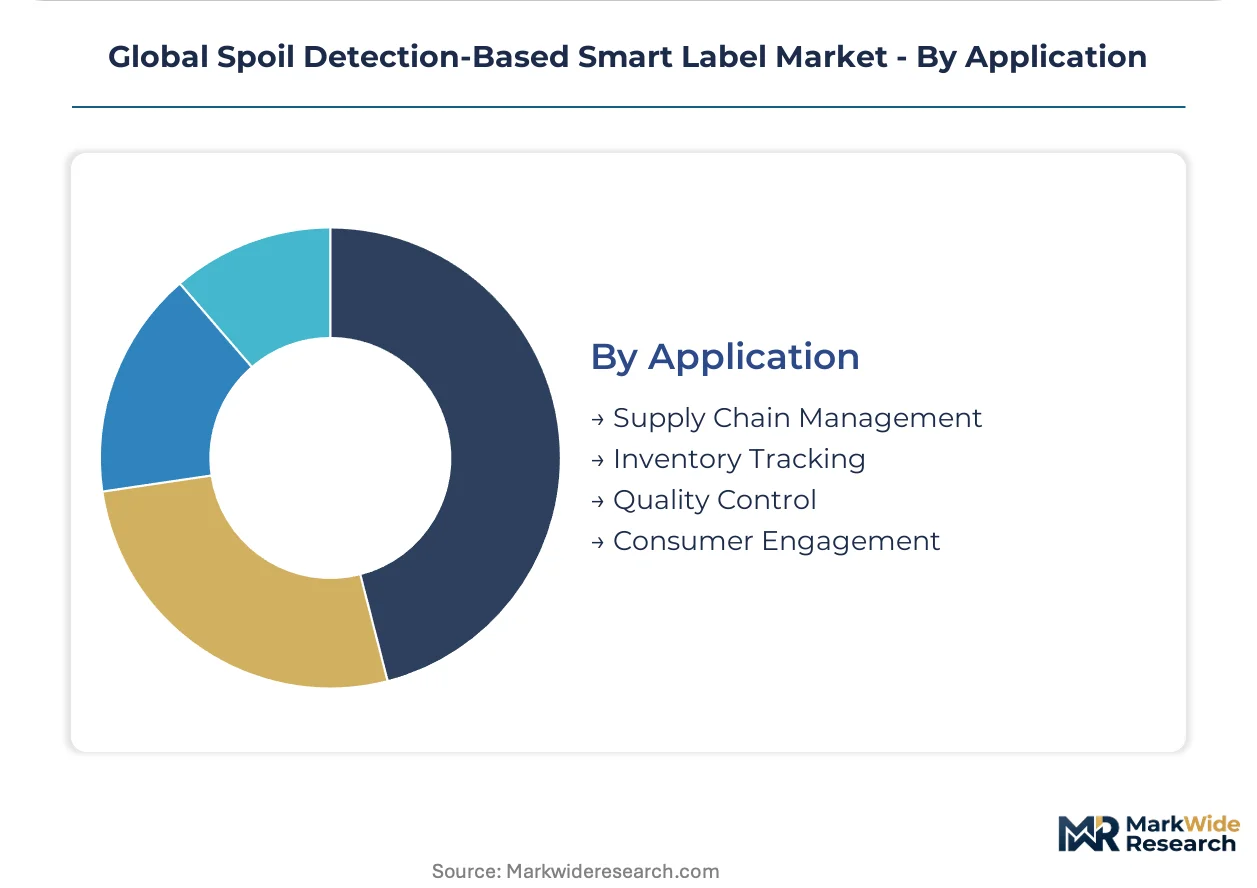
Supply chain documentation commands enterprise budgets, while consumer engagement applications depend on brand marketing allocations with higher volatility.
- Supply Chain Management:End-to-end temperature documentation replacing manual logger retrieval and data transcription. Germany's cold-chain logistics density enables shared reader infrastructure across pharmaceutical and fresh food verticals, amortizing hardware costs across multiple shipper networks.
- Quality Control:In-process verification of thermal processing, storage, and transport adequacy. FDA Food Safety Modernization Act traceability requirements in the United States are compelling replacement of static date codes with dynamic temperature-logging documentation for high-risk food categories.
- Inventory Tracking:Automated freshness-based stock rotation in warehouse management systems.
- Consumer Engagement:Smartphone-interactive freshness verification and brand storytelling.
Supply Chain Management absorbs the largest enterprise technology budgets. Quality Control is expanding most quickly through regulatory mandate acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Materials scientists and polymer chemists cluster in Germany's industrial heartland, anchoring European substrate innovation. Cold-chain logistics specialists concentrate in the Netherlands and Denmark. Regulatory compliance expertise pools in Brussels and Washington corridors.
Germany
Pharmaceutical serialization mandates under EU MDR drive RFID-enabled spoil detection deployment across insulin and biologics distribution networks. The country's national pharmaceutical regulator enforces strict chain-of-custody documentation that favors automated temperature logging. Cold-chain logistics density in the Rhine-Ruhr corridor enables shared reader infrastructure across pharmaceutical and fresh food verticals.
United States
FDA Food Safety Modernization Act traceability requirements compel retailers to replace static date codes with dynamic freshness signaling for high-risk food categories. FCC electromagnetic spectrum allocation shapes RFID tag design specifications distinct from European ETSI standards. Fresh food retail chains in California and the Pacific Northwest lead procurement of sensor-integrated labels to reduce waste and protect brand equity.
India
FSSAI mandatory cold storage requirements for dairy and pharmaceuticals create deployment opportunities for low-cost color-metric indicators. The country's food safety regulator mandates temperature documentation that bypasses reader infrastructure dependencies in fragmented last-mile distribution. Dairy processing clusters in Gujarat and Maharashtra pilot spoil detection labels under compliance timelines accelerating through 2025.
China
GB standards administered by SAMR elevate barrier-to-entry for substrate and sensor chemistry suppliers seeking market access. The Ministry of Industry and Information Technology governs electromagnetic spectrum allocation that diverges from FCC and ETSI regimes. Cold-chain infrastructure buildout in the Yangtze River Delta concentrates demand for humidity-responsive labels in high-value seafood and pharmaceutical corridors.
France
AGEC law packaging waste fees impose cost structures that favor smart labels enabling precise consumption-timing and reduced premature disposal. ANSM pharmaceutical serialization requirements align with EU MDR timelines. Fresh food retail procurement consolidation in the Île-de-France region centralizes technical specifications across private-label categories.
Global Spoil Detection-Based Smart Label Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across substrate manufacturing and sensor chemistry formulation. The market exhibits tiered concentration with specialized materials scientists commanding premium positioning against commodity label converters. Three archetypes dominate: integrated materials-converter hybrids, pure-play sensor technology licensors, and enterprise printing infrastructure providers. Strategic moves concentrate on adhesive formulation partnerships and multi-year retail procurement consolidation.
Within the materials science tier, Avery Dennison Corporation anchors integrated substrate-sensor capabilities. Zebra Technologies exemplifies enterprise-grade printing and encoding infrastructure scale. Evigence Sensors occupies a specialist position in color-metric time-temperature indicators requiring no electronic reader. These three represent divergent competitive vectors: vertical materials control, automation hardware dominance, and cost-accessible chemical indicator simplicity.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Zebra Technologies |
| Evigence Sensors |
| Insignia Technologies |
| SpotSee |
| Innoscentia |
| Impinj |
| NXP Semiconductors |
| Sato Holdings |
| Others |
Supply Flow & Price Mechanics
Private-label procurement consolidation among UK and Nordic grocery retailers concentrates buying power across multi-year master agreements, compressing converter margins and forcing three-tier pricing stratification across premium sensor-integrated labels, standard RFID inlays, and economy chemical indicators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with premium tiers capturing value through EU MDR serialization compliance and NFC-enabled consumer engagement, while economy tiers compete on unit cost for India's FSSAI-mandated dairy applications. Price differentiation hinges on certification grade—FDA food-contact notification versus EFSA compliance—and volume scale through consolidated retail procurement. Cost compression in standard RFID tags is intensifying because reader infrastructure sharing across pharmaceutical and fresh food verticals amortizes hardware investments. Small-scale dairy processors in fragmented last-mile distribution exhibit highest price sensitivity; pharmaceutical serialization mandates render biologics distributors least sensitive.
Supply Chain Analysis
EFSA and FDA food-contact notification reviews exceeding eighteen months for novel biodegradable substrates create qualification gating that advantages incumbent converters with established regulatory dossiers. Substrate manufacturing concentrates in Germany, China, and the United States, with sensor chemistry formulation anchored in specialized facilities across the Netherlands and Japan. Rare earth element processing for chromogenic compounds draws from Chinese facilities, creating single-source vulnerability for leuco dye supply. Distribution runs through converter networks serving retail private-label programs and pharmaceutical serialization distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU Green Deal biodegradability mandates impose substrate reformulation costs that Indian cold-chain buildout avoids through zero-infrastructure color-metric indicators, creating divergent margin structures across regulatory jurisdictions.
For Market Incumbents: Anchor market position through backward integration into biodegradable adhesive formulation, securing EFSA compliance timelines that emerging converters cannot match. Invest in multi-physics simulation talent pools to accelerate temperature-responsive chemistry development before REACH substance restrictions expand. Defend against private-label procurement consolidation by locking multi-year performance guarantees with Tesco, Sainsbury's, and ICA Gruppen technical specification teams. For New Entrants and Emerging Players: Begin with India's FSSAI-mandated dairy sector, where fragmented last-mile distribution rewards zero-reader color-metric simplicity over RFID infrastructure. Target Gujarat and Maharashtra processing clusters piloting spoil detection labels under accelerating compliance timelines. Enter through low-cost enzymatic indicator licensing partnerships with established label converters lacking chemical formulation expertise. For Investors and Strategic Acquirers: Enterprise printing infrastructure providers are the most active acquirer in this space, seeking sensor chemistry capabilities to complete integrated substrate-sensor offerings. Long-term viability rests on regulatory mandate acceleration rather than discretionary brand marketing budgets. Target acquisition archetype: specialized materials scientists with polymer-microfluidics crossover expertise and existing FDA or EFSA notification dossiers. Watch for India's FSSAI enforcement intensity as inflection indicator for emerging market demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Reformulation | EU Green Deal packaging rules force adhesive layer redesign to meet mandatory biodegradability thresholds. |
| Multi-Physics Simulation Talent Acquisition | Combined polymer science and thermal modeling expertise concentrates among scarce academic-industry crossover specialists. |
| Pharmaceutical Serialization Compliance Investment | EU MDR and FDA DSCSA mandates compel automated temperature logging that replaces manual logger retrieval. |
| Private-Label Procurement Consolidation | Tesco and Sainsbury's centralized technical specifications strain converter working capital through multi-SKU contracts. |
| Cellular-IoT Integration Development | Low-power wide-area connectivity enables real-time spoilage alerts without smartphone proximity for transcontinental biologics. |
Methodological Framework
Direct dialogue with label converter operations managers, pharmaceutical packaging procurement leads, retail category buyers, and biodegradable substrate R&D directors grounded qualitative findings. Secondary validation drew from EFSA food-contact notifications, FDA food safety modernization guidance documents, FSSAI cold storage mandates, EU MDR serialization requirements, and customs data on chromogenic compound trade flows. Bottom-up unit economics modeling triangulated against top-down regulatory mandate timing projections.
Bottom-up volume and value outputs reflect segment-level modeling across product type, end user, technology, and application dimensions, with additional granularity on regional regulatory cluster adoption curves. CAGRs derived from mandate-driven deployment timelines rather than discretionary procurement elasticity. Forecast inputs incorporated REACH substance restriction expansion schedules, RFID spectrum allocation divergence between FCC and ETSI regimes, and cold-chain logistics density metrics for shared reader infrastructure economics.
Several conditions sit outside the modeled scope, including unilateral tariff impositions on Chinese rare earth processing, accelerated biodegradability certification schemes obsoleting conventional polymers, and breakthrough printed electronics cost curves disrupting chemical indicator volume dominance. Forecasts reflect documented assumptions on regulatory enforcement intensity and retailer private-label consolidation velocity. A model refresh is warranted upon material change in EU Green Deal implementation timelines or FSSAI cold storage mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Packaging
Smart Label Market
Smart Packaging
Digital Packaging Market
Smart Packaging
Smart Retail Packaging Market
Smart Packaging
Smart Medication Packaging Market
Smart Packaging
Intelligent Tamper-Proof Packaging Market
Smart Packaging
Smart Food Packaging Market
Smart Packaging
Smart Bottle Market
Smart Packaging
North America Smart Label Market
Smart Packaging
Smart Tag Packaging Market
Smart Packaging
Self Cooling Packaging Market
Smart Packaging
Smart Packaging Market
Smart Packaging
Global Personalized Packaging Market
Smart Packaging
Global Nano Enabled Packaging Market