
 Europe Home Furniture Market | 2026-2036
Europe Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Furniture Market Foresight
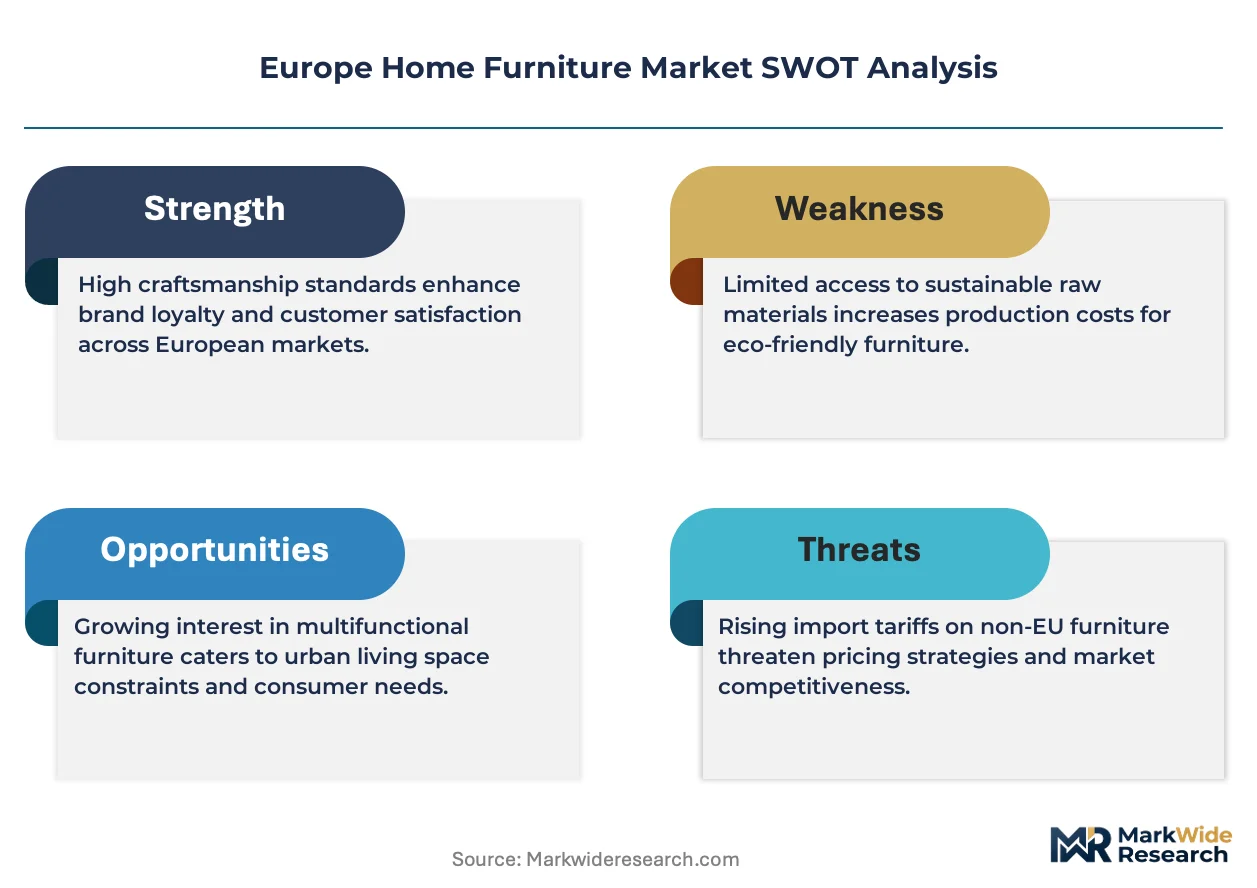
Premium solid-wood certification tiers is redrawing competitive boundaries across the Europe home furniture landscape. IKEA leverages its Baltic supply chain to sustain cost leadership in flat-pack distribution. Hülsta anchors German manufacturing heritage through precision-engineered bedroom systems. Ligne Roset differentiates via artisan upholstery workshops in France's Rhône-Alpes region.
Europe home furniture encompasses movable residential fixtures constructed from engineered or solid substrates, finished with lacquers, oils, or textile coverings, and dimensioned for dwelling-unit interiors. Primary commercial purpose centers on enabling domestic activity zones—seating, storage, surface work, and sleep—while conforming to EN 12520 structural safety standards for seating durability and EN 14749 stability requirements for storage units. Sofas and cabinets capture the deepest margin pools due to replacement-cycle compression and premium-configuration upselling. Wood material grades command price premiums where FSC chain-of-custody documentation satisfies retailer procurement mandates. Online retail channels are displacing general retailers in Nordic markets, though exclusive showrooms retain decisive influence in Italian and French urban centers.
REACH chemical restrictions and the EU Green Deal's deforestation-free supply-chain rules are tightening substrate-origin documentation requirements for all market participants. ECHA substance-of-very-high-concern listings are accelerating water-based finish substitution across Polish and Romanian manufacturing clusters. Stakeholders must monitor pending CSRD scope expansions that will force Scope 3 emissions disclosure from upholstered goods importers.
Market Dynamics
EU Green Deal deforestation-free supply-chain rules are compressing substrate-origin documentation timelines while REACH chemical restrictions accelerate water-based finish substitution across Polish and Romanian manufacturing clusters. This regulatory pressure is restructuring competitive positioning around certified timber grades and low-emission production systems.
Growth Catalysts
- CSRD Scope 3 Mandates:Upcoming emissions disclosure requirements for upholstered goods importers are forcing supply-chain transparency upgrades that favor documented low-carbon producers.
- Urban Density Patterns:Metropolitan corridor expansion across Germany's Rhine-Ruhr and Netherlands Randstad regions drives demand for modular multifunctional furniture configurations.
- FSC Chain-of-Custody Certification:Retailer procurement mandates for documented sustainable timber grades are creating price-premium capture opportunities for certified manufacturers.
Market Restraints
- Substrate Cost Volatility:Baltic birch plywood and certified oak supply fluctuations compress margin predictability for flat-pack producers dependent on engineered wood inputs.
- ECHA SVHC Listings:Accelerating substance-of-very-high-concern designations force rapid reformulation of solvent-based finishes, creating compliance lag for smaller Polish and Romanian finish houses.
- Geographic Supply Concentration:Bedroom system manufacturing clusters in North Rhine-Westphalia create vulnerability to regional logistics disruptions and labor cost inflation.
Strategic Opportunities
- Portuguese Cork-Aluminum Hybrid Seating:Underpenetrated Iberian design aesthetics combining regional cork harvesting with precision metalwork offer differentiation in Mediterranean markets.
- Direct-to-Consumer Configurators:Nordic markets demonstrate online retail channel displacement of general retailers, suggesting replicable model expansion into Baltic states.
- EU Green Deal Circular Economy Action Plan:Take-back and recycling mandates create aftermarket service revenue streams for furniture-as-a-service platforms targeting corporate housing providers.
Industry Challenges
- Water-Based Finish Technical Gap:Polish and Romanian manufacturing clusters face skill shortages in spray-application techniques for low-VOC coatings that match solvent-based durability standards.
- Legacy ERP Integration:CSRD-compliant Scope 3 emissions tracking requires supply-chain data architecture upgrades that conflict with existing procurement software systems.
- CE Marking Documentation Burden:EN 12520 and EN 14749 testing protocol updates demand extended certification timelines that delay product launches.
Report Scope
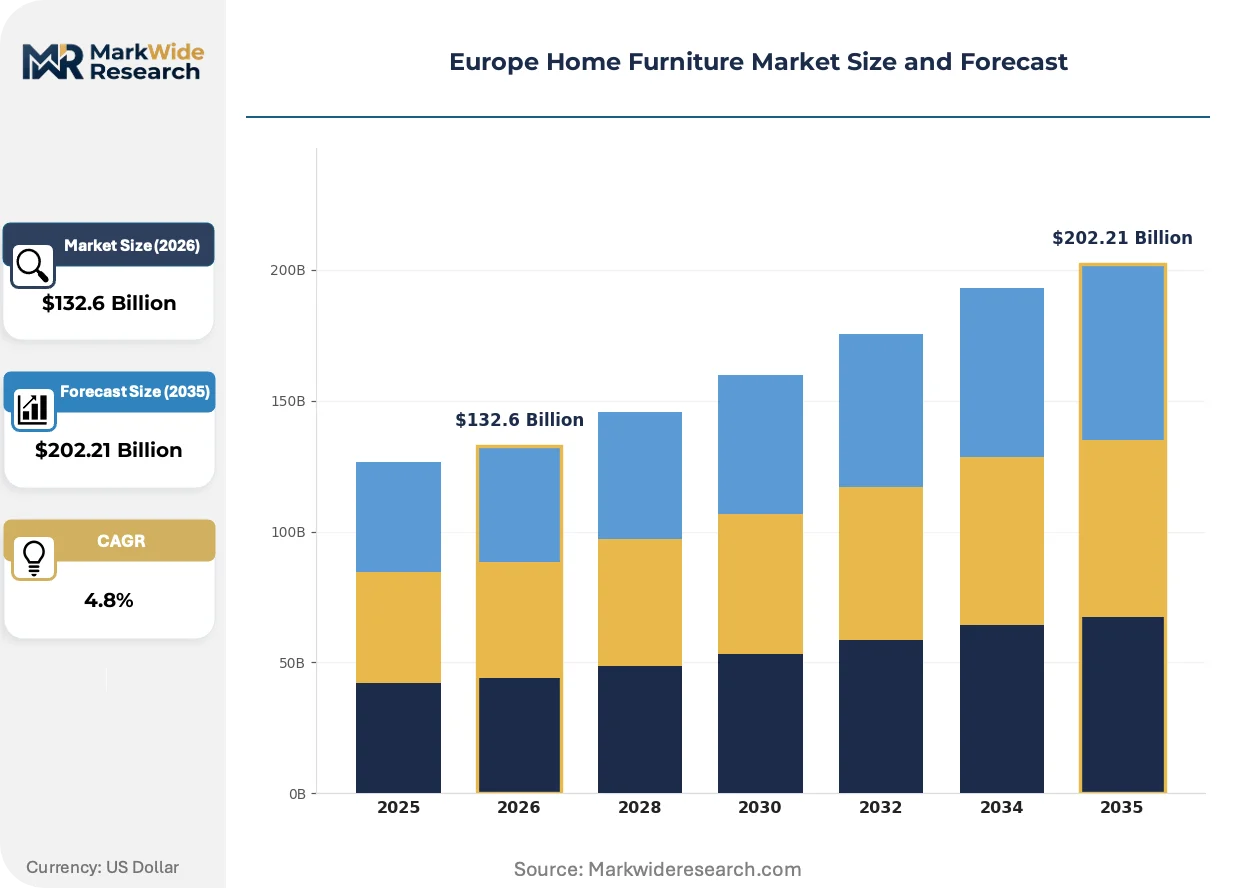
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Furniture Market |
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $202.21 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Style: Modern, Traditional, Vintage, Contemporary Material: Wood, Metal, Glass, Fabric Distribution Channel: Online Retail, Exclusive Showrooms, General Retailers, Wholesale |
| Companies Covered | Maisons du Monde, Hülsta, IKEA, Ligne Roset, BoConcept, Conforama, JYSK, Natuzzi, Habitat, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Furniture Market Shifts & Advancements
Digital fabrication and biomaterial substitution are fragmenting traditional manufacturing hierarchies while regulatory disclosure mandates restructure competitive transparency requirements across the value chain.
Mass-customization software paired with CNC routing equipment is fragmenting batch-size economics in upholstered goods production. Italian and French artisan workshops adopt parametric design tools to compress made-to-order lead times from weeks to days. This capability diffusion enables smaller Rhône-Alpes and Brianza producers to compete on configuration breadth previously monopolized by scale manufacturers.
REACH chemical restrictions are accelerating water-based finish substitution across Polish and Romanian manufacturing clusters. ECHA substance-of-very-high-concern listings force reformulation of legacy lacquer systems within compressed compliance windows. Upholstered goods importers face the steepest adaptation curves as textile adhesive and foam flame-retardant chemistries require simultaneous requalification.
Exclusive showroom influence persists in Italian and French urban centers despite Nordic online channel displacement. Milan and Paris design districts anchor high-consideration purchase journeys where tactile material evaluation determines premium configuration selection. This bifurcation rewards dual-channel operators capable of serving immediate digital convenience in Copenhagen while sustaining immersive brand environments in Lombardy.
Europe Home Furniture Market Segmentation
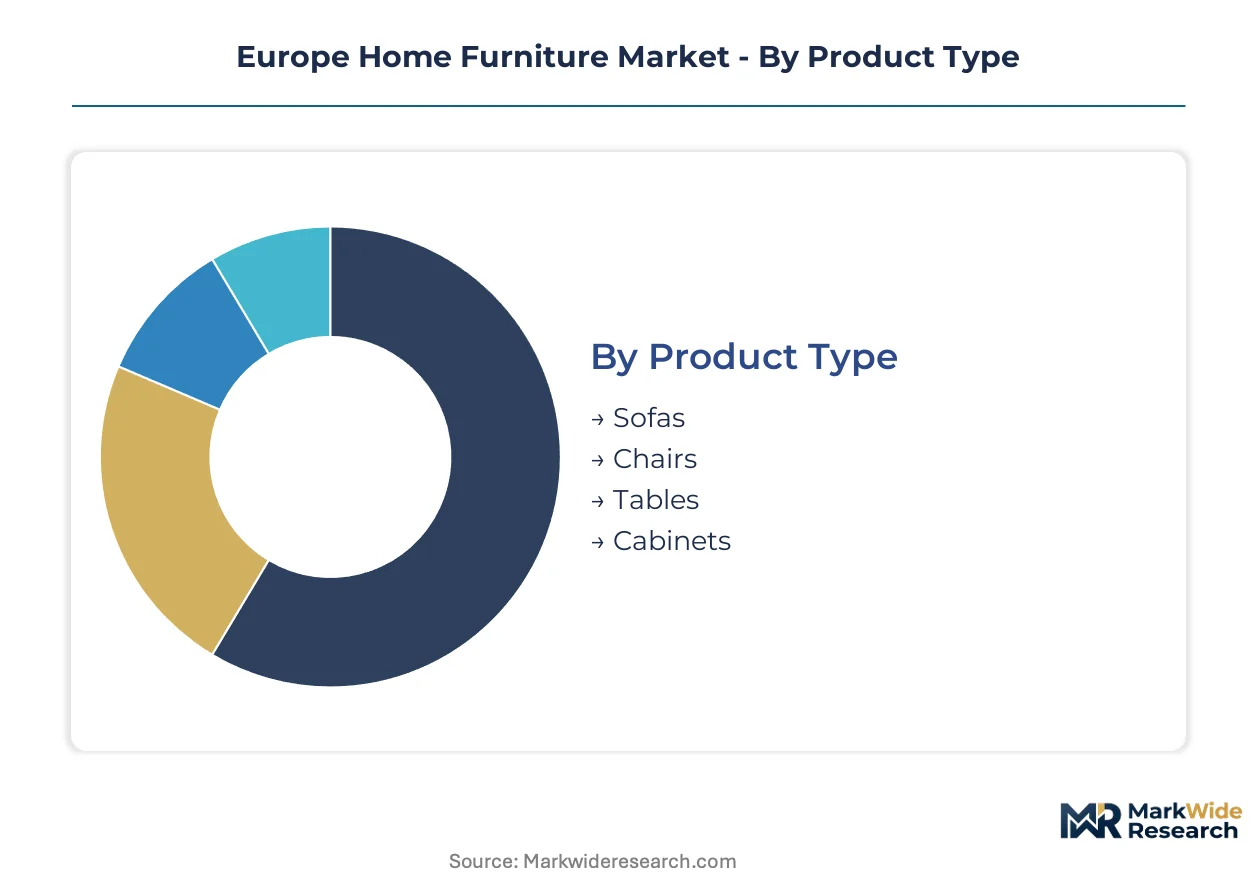
Segmentation in the Europe home furniture market reveals how regulatory pressure and urban living patterns split demand across distinct technical and aesthetic categories. Manufacturers align product portfolios with REACH chemical mandates and FSC certification tiers to capture price premiums in Germany, France, and Italy.
Product Type:
REACH chemical restrictions and EN 12520 durability standards create divergent compliance burdens across movable fixture categories.
- Sofas:Multi-component upholstered systems combining timber frames, steel suspension, and textile coverings. Demand concentrates in Paris and Milan design districts where tactile material evaluation drives premium configuration selection. ECHA SVHC listings on flame-retardant foams force rapid textile adhesive reformulation.
- Cabinets:Vertical and horizontal storage units engineered from engineered wood substrates with surface finishes. Rhine-Ruhr metropolitan corridor apartment dwellers favor modular multifunctional configurations with integrated cable management. EN 14749 stability requirements extend certification timelines for new product launches.
- Chairs:Seating fixtures spanning dining, accent, and ergonomic office categories for residential deployment.
- Tables:Surface work platforms including dining, coffee, and desk configurations across material combinations.
Established volume favors cabinets; emerging adoption favors sofas.
Style:
Customer acquisition cost tiers separate heritage craftsmanship from mass-manufactured aesthetics.
- Modern:Clean-line geometries with minimal ornamentation emphasizing functional spatial efficiency. Netherlands Randstad urban density patterns drive demand for low-profile silhouettes suited to compact floor plans. Direct-to-consumer configurators in Nordic markets displace traditional retail for this aesthetic.
- Contemporary:Current-period designs blending material innovation with adaptable modularity. Brianza producers leverage parametric design tools to compress made-to-order lead times from weeks to days. This capability diffusion enables smaller manufacturers to compete on configuration breadth.
- Traditional:Ornamented forms referencing historical European design vocabularies with carved detailing and rich finishes.
- Vintage:Reclaimed or reproduction pieces emphasizing patina, wear patterns, and period authenticity.
Margin concentration sits with modern; configuration breadth expansion favors contemporary.
Material:
Supply chain documentation requirements intensify around substrate origin verification under EU Green Deal deforestation-free rules.
- Wood:Solid timber and engineered substrates including Baltic birch plywood and certified oak grades. Polish and Romanian manufacturing clusters face compressed compliance windows for water-based finish substitution. FSC chain-of-custody documentation satisfies retailer procurement mandates in German dense metropolitan corridors.
- Fabric:Woven, knitted, and non-woven textile coverings for upholstered goods including natural and synthetic fibers. Portuguese cork-aluminum hybrid seating offers underpenetrated Iberian design aesthetics combining regional cork harvesting with precision metalwork. REACH restrictions on textile adhesives create steepest adaptation curves for importers.
- Metal:Steel, aluminum, and alloy frameworks providing structural support and decorative elements.
- Glass:Tempered and laminated surface materials for tabletops and display components.
Certification premium capture favors wood; biomaterial substitution momentum favors fabric.
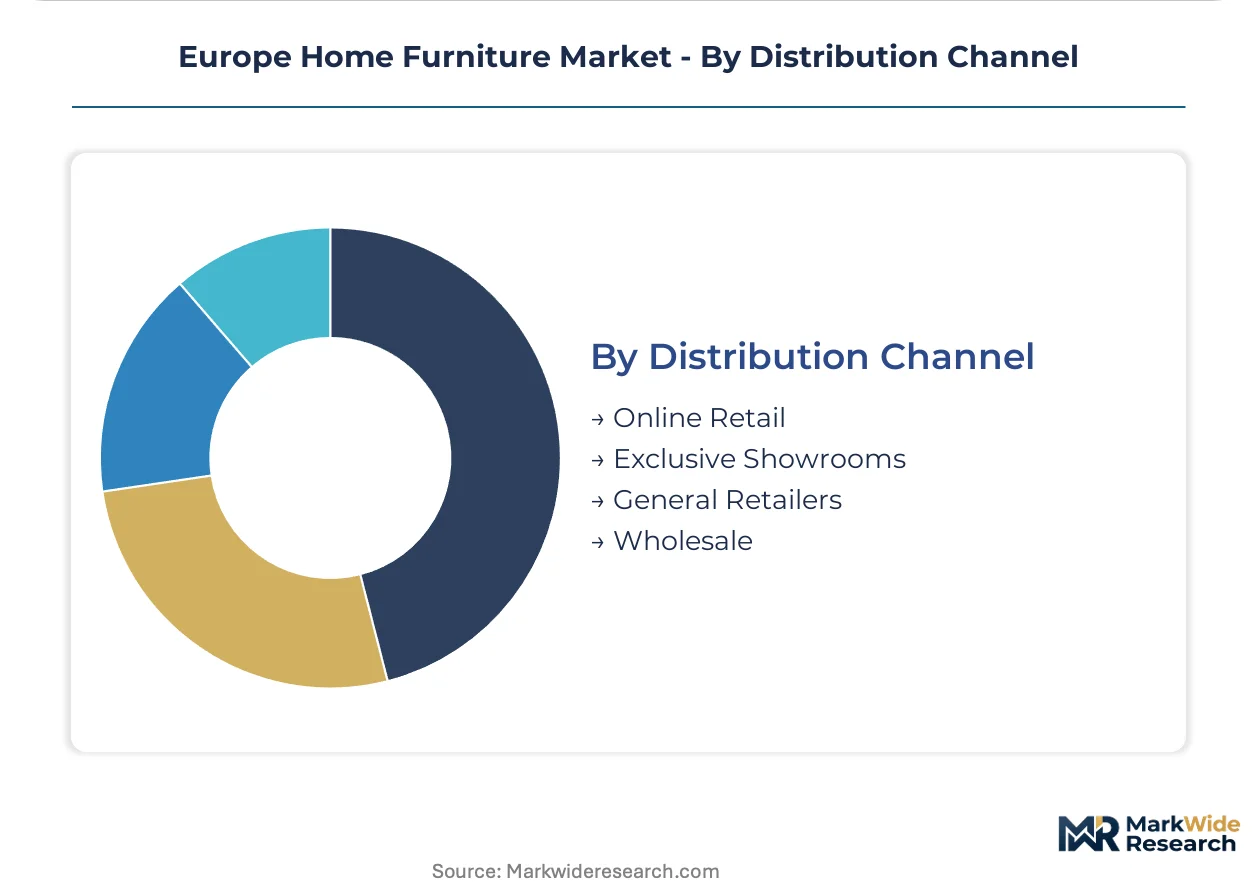
Distribution Channel:
Channel economics fragment between immersive brand environments and immediate digital convenience.
- Exclusive Showrooms:Dedicated brand environments enabling tactile material evaluation and high-consideration purchase journeys. Lombardy and Paris design districts anchor premium configuration selection where spatial staging determines upselling success. Milan furniture week events reinforce showroom influence for design-forward segments.
- Online Retail:Digital commerce platforms with mass-customization software and home delivery logistics. Copenhagen and Stockholm demonstrate complete channel displacement of general retailers for standardized product categories. Nordic replicability suggests model expansion into Baltic states.
- General Retailers:Multi-brand physical stores carrying curated furniture assortments alongside complementary home goods.
- Wholesale:Business-to-business volume transactions serving property developers, hospitality operators, and corporate housing providers.
Consideration intensity favors exclusive showrooms; volume scaling favors online retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany maintains the largest furniture trade surplus in Europe, exporting precision-engineered bedroom systems to Nordic markets while importing upholstered components from Italy and Eastern European manufacturing clusters.
Germany
Rhine-Ruhr metropolitan corridor apartment dwellers drive demand for modular multifunctional configurations with integrated storage. The EU Green Deal's deforestation-free supply-chain rules compress documentation timelines for Baltic birch plywood imports. North Rhine-Westphalia bedroom system manufacturers face vulnerability to regional logistics disruptions and labor cost inflation.
France
Paris design districts anchor high-consideration purchase journeys where tactile material evaluation determines premium configuration selection. ECHA substance-of-very-high-concern listings force rapid reformulation of solvent-based finishes within compressed compliance windows. Rhône-Alpes artisan upholstery workshops adopt parametric design tools to compress made-to-order lead times from weeks to days.
Italy
Milan furniture week events reinforce showroom influence for design-forward segments where spatial staging determines upselling success. REACH chemical restrictions accelerate water-based finish substitution across manufacturing clusters. Brianza producers leverage digital fabrication capabilities to compete on configuration breadth previously monopolized by scale manufacturers.
Netherlands
Randstad urban density patterns drive demand for low-profile silhouettes suited to compact floor plans. CSRD Scope 3 emissions disclosure requirements force supply-chain transparency upgrades for upholstered goods importers. Amsterdam and Rotterdam demonstrate complete online retail channel displacement of general retailers for standardized product categories.
Poland
Manufacturing clusters face skill shortages in spray-application techniques for low-VOC coatings that match solvent-based durability standards. ECHA substance-of-very-high-concern designations force rapid reformulation of legacy lacquer systems. Polish finish houses experience compliance lag as water-based technical gaps persist in production workforce capabilities.
Europe Home Furniture Market Competitive Landscape
Concentration sits with flat-pack scale operators and heritage craftsmanship specialists competing across divergent margin architectures. The vendor base splits between Baltic supply chain-dependent volume producers and Rhône-Alpes or Brianza design ateliers commanding premium positioning. Three strategic archetypes dominate: Nordic cost-leaders leveraging mass-customization software, German precision-engineered system manufacturers, and French-Italian artisan upholstery houses. Competitive moves center on FSC chain-of-custody certification acquisition and direct-to-consumer configurator platform deployment.
Within the heritage craftsmanship tier, Ligne Roset and Natuzzi exemplify artisan upholstery positioning anchored in French and Italian manufacturing traditions. IKEA occupies the scale-driven archetype with Baltic supply chain integration and flat-pack distribution economics. Hülsta represents German precision-engineered bedroom system manufacturing, sustaining heritage positioning through documented quality protocols. These three anchors illustrate the market's tripartite competitive structure.
| Leading Market Players |
|---|
| Maisons du Monde |
| Hülsta |
| IKEA |
| Ligne Roset |
| BoConcept |
| Conforama |
| JYSK |
| Natuzzi |
| Habitat |
| Others |
Supply & Pricing Matrix
Water-based finish substitution across Polish and Romanian manufacturing clusters simultaneously redraws supply geography toward certified timber regions and compresses pricing economics for solvent-dependent producers. This input transition forces Baltic birch plywood suppliers to absorb documentation costs while FSC-certified oak grades capture widening price premiums in German metropolitan corridors.
Pricing Analysis
Urban apartment dwellers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FSC chain-of-custody certification and modular configuration complexity. Cost compression in flat-pack segments is intensifying because REACH compliance adds reformulation overhead. Price sensitivity peaks among Randstad density-driven buyers seeking space-efficient solutions; Milan and Paris design districts show lowest sensitivity where tactile evaluation dominates.
Supply Chain Analysis
Inventory cycles stretch from Baltic timber harvests through Rhône-Alpes upholstery workshops due to EN 12520 certification timelines. Supply concentrates in Poland, Romania, and Italy's Brianza region. Raw material dependencies span Baltic birch plywood, certified oak grades, and low-VOC coating chemistries. Single-source vulnerability sits with North Rhine-Westphalia bedroom system clusters. Distribution runs through exclusive showrooms in Lombardy and Paris alongside Nordic direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe home furniture market represents early-cycle expansion as CSRD Scope 3 mandates force supply-chain transparency upgrades that favor documented low-carbon producers with established certification protocols.
For Market Incumbents: Compound FSC chain-of-custody advantages by acquiring distressed Polish finish houses facing water-based technical gaps. Expand parametric design capabilities in Brianza to compress made-to-order lead times against emerging digital-native competitors. Vertical integration into Portuguese cork harvesting secures biomaterial differentiation for Mediterranean market penetration. For New Entrants and Emerging Players: Differentiate on circular economy service models targeting corporate housing providers with furniture-as-a-service platforms. White-space opportunities concentrate in Baltic states where Nordic online retail displacement remains incomplete. Iberian cork-aluminum hybrid seating offers underpenetrated design aesthetics with regional material sourcing advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flat-pack operators struggling with Baltic plywood cost volatility. Long-term viability favors manufacturers with integrated certification documentation and direct-to-consumer configurator deployment. Watch ECHA SVHC listing velocity as inflection indicator for finish house consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Certification Acquisition | Retailer procurement mandates in Germany and France reward documented sustainable timber with price-premium capture. |
| Water-Based Finish Transition | REACH compliance deadlines force rapid Polish and Romanian manufacturing cluster adaptation or exit. |
| Direct-to-Consumer Configurator Launch | Nordic channel displacement patterns suggest replicable model expansion into Baltic states. |
| Parametric Design Tool Adoption | Italian and French artisan workshops compress lead times to compete with scale manufacturers. |
| Circular Economy Service Platform | EU Green Deal take-back mandates create aftermarket revenue streams for corporate housing providers. |
Research Methodology
A spread of perspectives from furniture manufacturing executives, retailer procurement managers, ECHA regulatory affairs specialists, and finish house technical directors converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation against EU customs records, FSC chain-of-custody databases, REACH substance listings, and EN standard certification registries. Bottom-up segment sizing triangulated against top-down trade flow analysis across the analysis window.
Segmentation dimensions modeled include product type, style category, material grade, and distribution channel across the projection horizon. CAGRs derive from trend extrapolation anchored in documented adoption patterns for certified timber and low-emission finishes. Industry-specific forecast inputs incorporate CSRD disclosure timeline assumptions and urban density projections for metropolitan corridor expansion.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or accelerated ECHA SVHC designation would require recalibration. Forecasts reflect assumptions about certification adoption curves and supply-chain transparency investment levels. Specific risks that could revise projections include tariff disruption to Baltic plywood flows, labor cost inflation in North Rhine-Westphalia, or technical failure in water-based finish durability matching. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Lecterns Market
Furniture
Fireplace Mantels Market
Furniture
Bounding Table Market
Furniture
High Density Fiberboard (HDF) Market
Furniture
China Home Furniture Market
Furniture
Pool Tables Market
Furniture
United States Home Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
Global Organic Furniture Market
Furniture
Cabinet Market
Furniture
GCC Home Furniture Market
Furniture
Global Home Furniture Market
Furniture
Children Furniture Market
Furniture
Europe Wood Decorative Wall Panel Market
Furniture
Italy Office Furniture Market
Furniture
Saudi Arabia Home Furniture Market