
 Global Photo Management Software Market | 2026-2036
Global Photo Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photo Management Software Market Foresight
Cloud distribution channels is reconfiguring how photo management software reaches enterprise buyers. Adobe leverages deep creative-suite integration to sustain subscription retention across marketing agencies. Google Photos competes on storage scale and AI-powered search, while SmugMug specializes in photographer-centric portfolios with print-commerce hooks. Bynder anchors the DAM segment with brand-template workflows that extend into campaign execution.
Photo management software comprises digital platforms that ingest, organize, edit, archive, and distribute image assets through metadata indexing, AI-driven facial recognition, and cloud-sync protocols operating at sub-second latency thresholds. These systems serve commercial purposes from personal memory preservation to enterprise brand governance and multi-channel content orchestration. Cloud-based deployment leads in enterprise traction due to elastic storage economics, while digital asset management use cases capture the deepest margin pools as marketing agencies consolidate creative operations. Tagging and archiving solution types now outpace basic editing in growth velocity as unstructured image volumes explode across organizations.
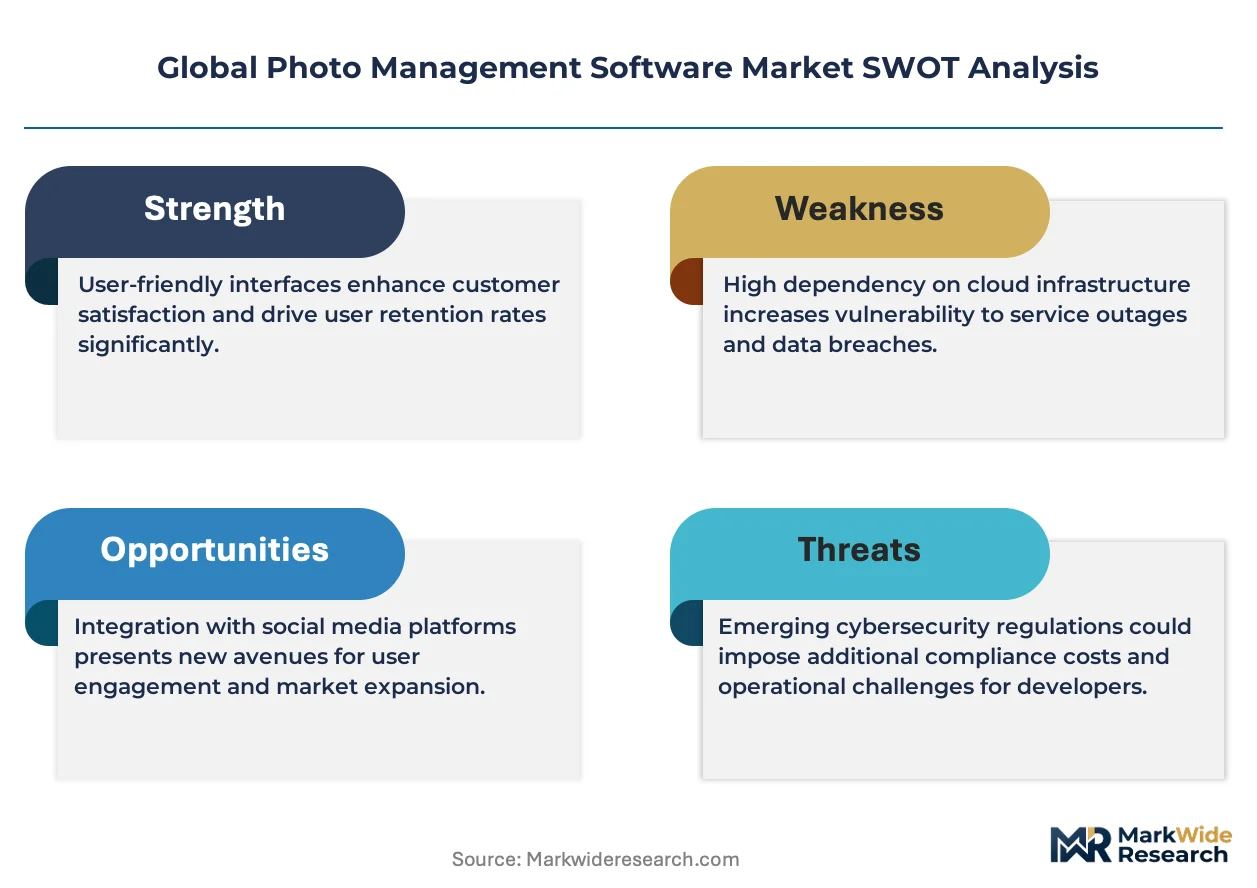
GDPR in Europe, the EU AI Act, and HIPAA in the United States impose divergent compliance burdens on facial recognition features and cross-border data residency, forcing vendors to modularize architecture by jurisdiction. ISO 27001 and SOC 2 certifications function as table stakes for enterprise procurement, particularly among media houses and educational institutes with federated user bases. Stakeholders must weigh localization investment against unified platform economics as regulatory fragmentation deepens.
Market Dynamics
Cloud-native architectures are collapsing the distinction between storage infrastructure and workflow orchestration, forcing vendors to rebuild around API-first delivery models that embed directly into creative production pipelines.
Growth Catalysts
- GDPR Article 17 right-to-erasure mandates:European enterprises are procuring photo management platforms with automated deletion workflows to satisfy data-subject requests without manual archive trawling.
- Marketing agency consolidation:Holding companies are centralizing creative operations onto unified DAM platforms, creating procurement pull for multi-tenant solutions with brand-template governance.
- Edge computing deployment:Sub-second latency requirements for real-time collaboration are driving investment in geographically distributed processing nodes that reduce round-trip delays for large RAW files.
Market Restraints
- Cross-border data residency friction:India's data localization directives and China's Cybersecurity Law fragment cloud architecture economics, forcing redundant infrastructure builds.
- Facial recognition algorithm licensing costs:Proprietary biometric indexing engines carry per-seat fees that inflate enterprise TCO by 15-40% versus basic metadata solutions.
- Storage input cost volatility:NAND flash pricing swings and hyperscaler egress fee structures create unpredictable operating expenditure for high-volume image archives.
Strategic Opportunities
- Underpenetrated SME segment in India:Tier-2 content studios lack dedicated DAM procurement expertise, creating whitespace for freemium-to-enterprise conversion models.
- EU AI Act compliance tooling:Automated audit trails for AI-generated image provenance represent an attachable module opportunity as synthetic media disclosure mandates expand.
- Blockchain-anchored copyright verification:Immutable timestamping for image ownership is converging with smart-contract licensing to serve stock photography marketplaces.
Industry Challenges
- Metadata taxonomy standardization gaps:Inconsistent IPTC and XMP implementation across camera manufacturers forces costly normalization pipelines for enterprise ingestion workflows.
- ISO 27001 certification timeline compression:Security-conscious buyers demand 90-day compliance windows that strain vendor audit preparation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photo Management Software Market |
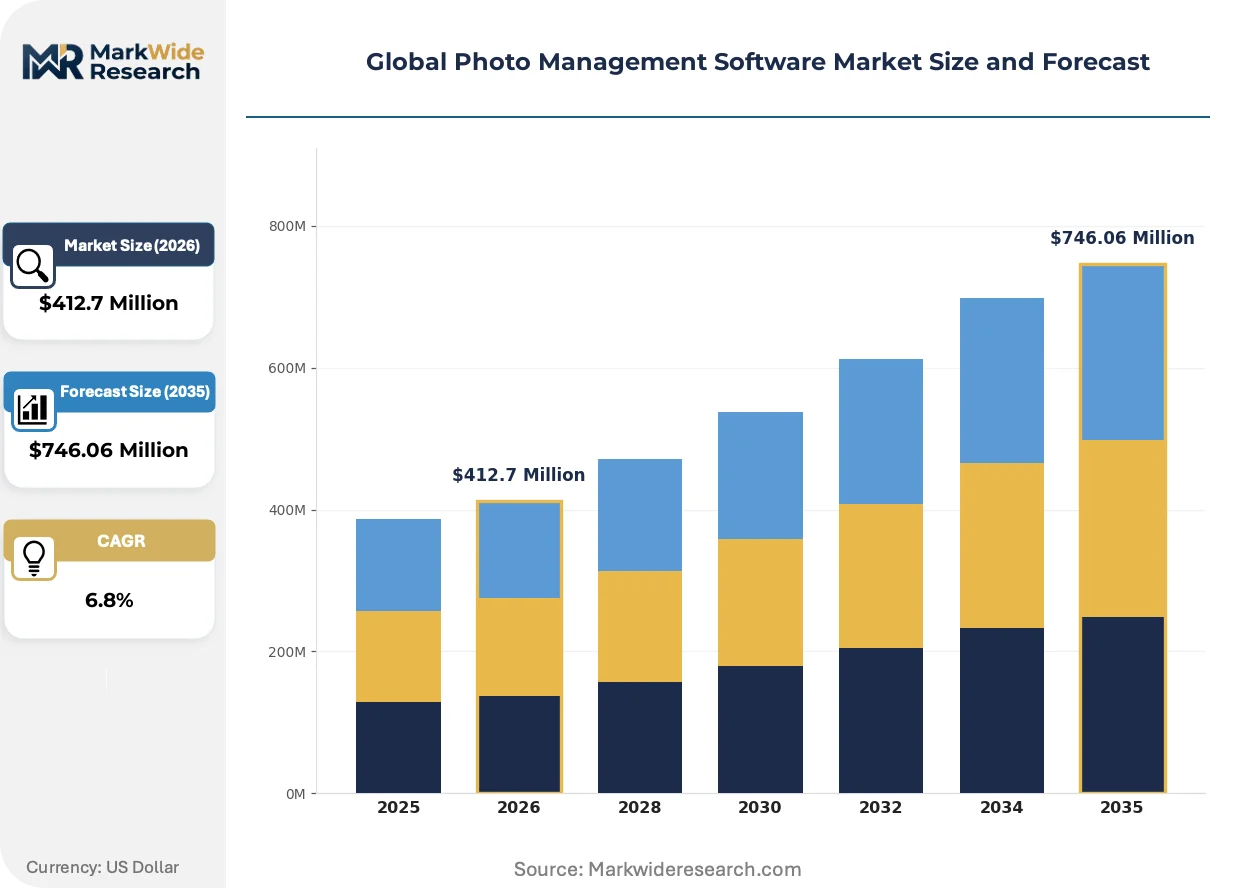
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $746.06 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Mobile Application Solution Type: Basic Editing, Advanced Editing, Archiving, Sharing, Tagging Use Case: Personal Use, Event Management, Marketing, Content Creation, Digital Asset Management End User: Photographers, Marketing Agencies, Media Houses, Educational Institutes, Event Organizers |
| Companies Covered | Flickr, 500px, Adobe, Photobucket, Photo Mechanic, Google Photos, SmugMug, Bynder, Apple Photos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photo Management Software Market Shifts & Advancements
Computational indexing and federated governance models are redefining how image assets move from capture to monetization, collapsing traditional boundaries between personal, commercial, and archival storage tiers.
AI-powered semantic search is migrating from experimental feature to procurement requirement as marketing agencies reject keyword-dependent retrieval for natural-language queries that surface contextually relevant assets without manual tagging investment. Enterprise buyers now mandate neural indexing in RFPs, compressing vendor differentiation around raw storage scale toward intelligence layer performance. This migration is forcing mid-tier platforms to license third-party vision APIs or cede procurement decisions to integrated suite providers.
The EU AI Act's transparency obligations for biometric identification systems are compelling European deployments to maintain human-in-the-loop review queues for facial recognition indexing, adding workflow friction that slows automated archive processing. Vendors serving German media houses and French publishing groups are modularizing facial detection as an opt-in feature with explicit consent logging. This regulatory architecture is segmenting product roadmaps between privacy-forward European builds and permissive configurations for other jurisdictions.
Enterprise buying committees are consolidating photo management procurement under broader digital asset management umbrellas, displacing standalone solutions that lack campaign execution integration. Marketing operations directors in United States agencies and United Kingdom brand studios now require direct connectivity to social publishing and print production systems. This bundling preference favors vendors with pre-built connectors to Adobe Creative Cloud, Canva, and Salesforce Marketing Cloud over specialized storage platforms.
Global Photo Management Software Market Segmentation
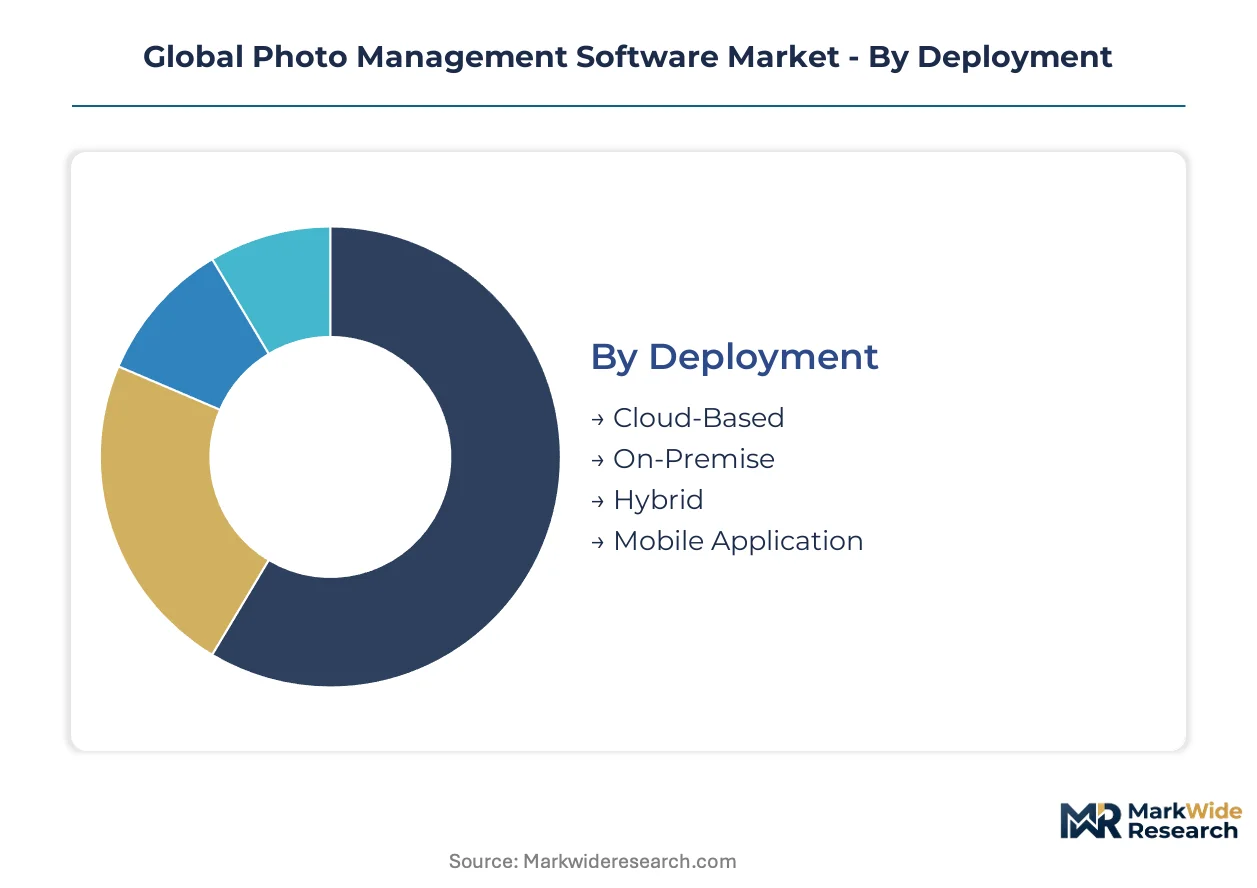
Segmentation in photo management software reveals how deployment economics, workflow complexity, and buyer sophistication create distinct margin pools. Vendors must align pricing architecture with the operational intensity each segment demands.
Deployment:
After-sales service intensity varies sharply across deployment modes, with cloud-native implementations requiring continuous latency optimization and on-premise demanding specialized hardware support.
- Cloud-Based:Elastic infrastructure scales storage and compute independently through API-orchestrated resource provisioning. Marketing agencies in the United States and Germany consolidate procurement here, driven by distributed team collaboration requirements and GDPR-mandated data residency controls that force regional node deployment.
- On-Premise:Dedicated server installations maintain full data sovereignty through localized physical infrastructure. Financial services and defense contractors in India and Switzerland anchor demand, constrained by air-gapped security mandates and the 15-25% TCO premium versus cloud alternatives.
- Hybrid:Split architectures synchronize hot-tier cloud assets with cold-archive on-premise storage through policy-driven tiering engines.
- Mobile Application:Native iOS and Android clients optimize for capture-to-share latency through device-side preprocessing and selective sync protocols.
Cloud-Based holds the largest share; momentum sits with Hybrid as data sovereignty requirements fragment pure-cloud economics.
Solution Type:
Cost tier stratification separates commodity editing tools from premium intelligence layers that command per-seat licensing premiums.
- Tagging:AI-powered metadata extraction automates object recognition, facial indexing, and contextual labeling through neural vision models. Enterprise DAM deployments in the United Kingdom and France prioritize this capability, driven by unstructured archive volumes that render manual keyword entry economically unviable.
- Archiving:Long-term preservation systems enforce retention policies, format migration, and integrity verification through checksum-validated storage tiers. Media houses in Japan and Germany anchor demand, constrained by broadcast regulatory mandates and petabyte-scale legacy format conversion costs.
- Basic Editing:Crop, rotate, and exposure adjustment tools target consumer memory preservation workflows.
- Advanced Editing:Layer-based compositing and color grading serve professional photographer post-production pipelines.
- Sharing:Permission-controlled distribution enables client review, social publishing, and external collaboration through time-limited access links.
Archiving commands the deepest enterprise margins; Tagging is expanding most quickly as marketing operations automate asset discovery.
Use Case:
Application maturity separates established personal storage from emerging enterprise governance workflows that integrate with martech stacks.
- Digital Asset Management:Enterprise-grade platforms govern brand consistency through template libraries, rights management, and campaign workflow orchestration. Marketing agencies in the United States and holding companies in Germany centralize procurement here, driven by multi-brand portfolio complexity and the need for Creative Cloud connector ecosystems.
- Content Creation:Streamlined ingestion-to-publish pipelines serve influencer economies and freelance production studios through rapid turnaround tooling. Tier-2 cities in India and Brazil anchor demand, constrained by payment friction and the absence of enterprise procurement infrastructure.
- Personal Use:Memory preservation and family sharing dominate consumer subscription conversion.
- Event Management:Real-time capture, curation, and guest delivery for weddings and corporate functions.
- Marketing:Campaign-specific asset organization distinct from full DAM governance scope.
Digital Asset Management holds the largest share; momentum sits with Content Creation as creator economy monetization tools mature.
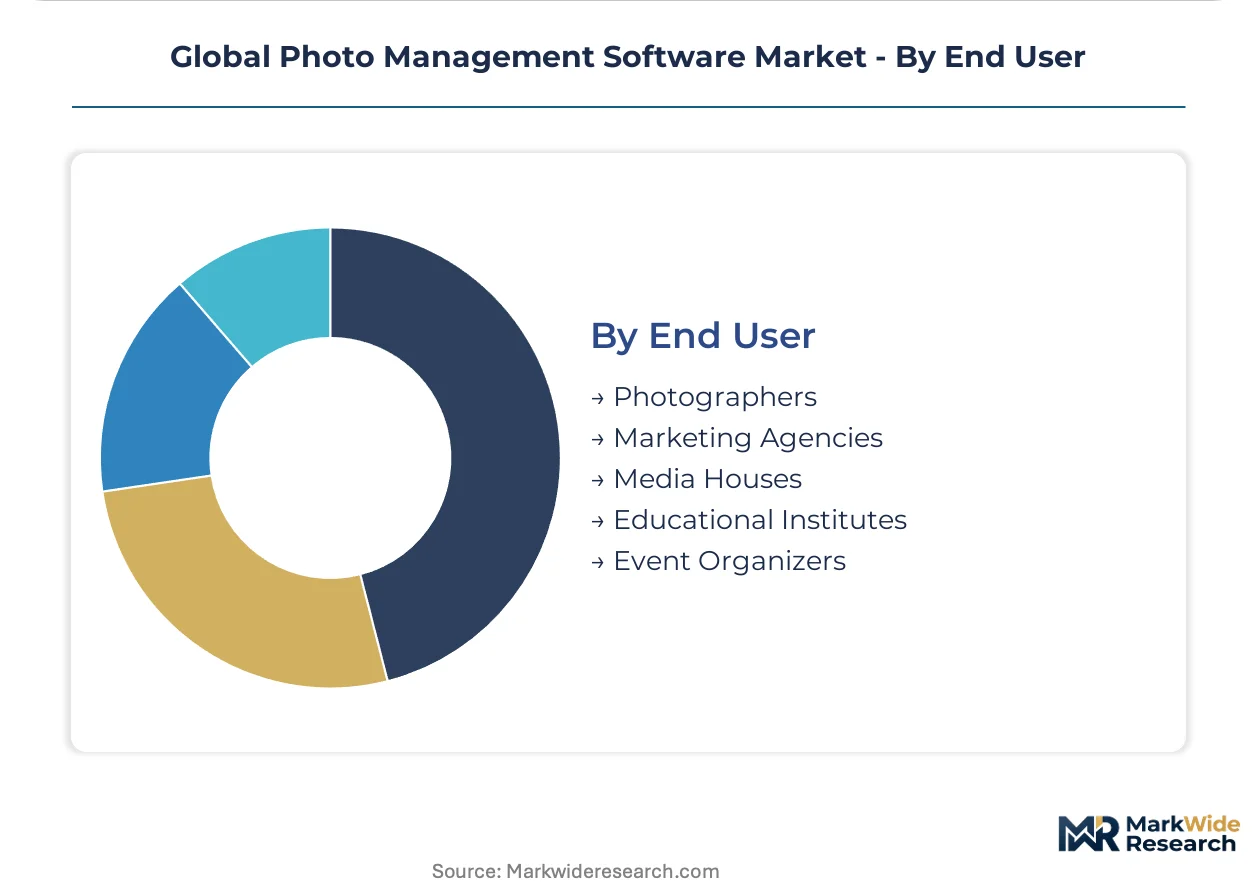
End User:
Customer type determines pricing elasticity, with procurement centralization in agencies enabling volume discounts versus fragmented individual purchasing.
- Marketing Agencies:Holding companies and independent shops consolidate creative operations onto unified platforms with multi-tenant brand separation. WPP and Publicis Groupe deployments in France and the United Kingdom drive standardization, constrained by 90-day ISO 27001 compliance windows that strain vendor audit capacity.
- Photographers:Freelance and studio professionals prioritize portfolio presentation, print commerce integration, and client proofing workflows. Individual practitioners in the United States and Germany anchor demand, with SmugMug and similar platforms capturing this segment through photographer-centric feature roadmaps.
- Media Houses:Broadcast and publishing organizations require broadcast-safe archival and multi-format distribution.
- Educational Institutes:Universities and K-12 systems manage institutional visual identity and course content repositories.
- Event Organizers:Corporate and social event planners need rapid turnaround from capture to delivery.
Marketing Agencies hold the largest share; momentum sits with Educational Institutes as campus digitization initiatives expand DAM procurement beyond traditional media buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC and HIPAA compliance requirements in the United States anchor the regulatory framework that shapes enterprise procurement patterns across the photo management software landscape. GDPR and the EU AI Act impose parallel constraints on European deployments, particularly around biometric data processing and cross-border storage architectures.
United States
Marketing agencies in New York and Los Angeles drive enterprise DAM adoption, consolidating multi-brand portfolios onto unified cloud platforms. HIPAA compliance mandates force healthcare-adjacent visual content workflows toward audited infrastructure with Business Associate Agreements. Austin and Seattle tech clusters host emerging vendors building AI-powered semantic search layers for mid-market buyers.
Germany
Industrial marketing departments and publishing groups anchor demand for GDPR-compliant archiving with automated right-to-erasure workflows. The KBA and BSI influence procurement standards for automotive and defense-adjacent visual asset governance. Munich and Hamburg media houses mandate ISO 27001 certification within 90-day windows, compressing vendor onboarding timelines.
India
Tier-2 content studios in Bangalore and Mumbai lack dedicated DAM procurement expertise, creating whitespace for freemium conversion models targeting the creator economy. RBI data localization directives and impending personal data protection legislation fragment cloud architecture economics. Hyderabad and Chennai enterprise campuses drive campus-wide digitization initiatives that extend DAM procurement beyond traditional media buyers.
United Kingdom
London brand studios and Manchester marketing operations require direct connectivity to social publishing and print production systems, consolidating procurement under broader martech umbrellas. The Information Commissioner's Office enforces GDPR-aligned transparency obligations for AI-powered facial recognition indexing. Bristol and Edinburgh emerging clusters experiment with blockchain-anchored copyright verification for stock photography marketplaces.
Japan
Broadcast regulatory mandates from METI drive petabyte-scale legacy format conversion demand among Tokyo and Osaka media houses. JIS standards and PMDA-adjacent compliance frameworks influence archival integrity verification requirements. Nagoya industrial marketing departments and Fukuoka content creation studios represent underpenetrated mid-market segments for automated tagging solutions.
Global Photo Management Software Market Competitive Landscape
Integrated creative-suite providers and specialized DAM platforms split the market along workflow depth versus storage scale vectors. Consolidation pressure concentrates procurement decisions among holding companies with multi-tenant governance requirements. Three archetypes dominate: legacy creative software vendors extending into cloud orchestration, pure-play DAM specialists building connector ecosystems, and consumer-platform incumbents pushing enterprise upsell ladders. Competitive moves center on API-first architecture rebuilds and pre-built martech connector expansion.
Within the integrated-suite tier, Adobe exemplifies creative-ecosystem extension into subscription-based cloud orchestration. Among specialized DAM architects, Bynder occupies a position exemplifying brand-template governance with campaign execution integration. Google Photos represents the consumer-platform archetype pushing toward enterprise storage scale with AI-powered search differentiation. These three anchors illustrate how vendor positioning stratifies around workflow depth, connector breadth, and infrastructure scale respectively.
| Leading Market Players |
|---|
| Flickr |
| 500px |
| Adobe |
| Photobucket |
| Photo Mechanic |
| Google Photos |
| SmugMug |
| Bynder |
| Apple Photos |
| Others |
Supply & Pricing Matrix
Overcapacity in hyperscaler cloud storage regions is compressing infrastructure margins and forcing vendors toward API-first differentiation to defend pricing power against commoditization pressure.
Pricing Analysis
Geographic price spreads between United States enterprise deployments and India SME tiers exceed 3x at equivalent feature depth, reflecting divergent after-sales service intensity and compliance certification burdens. SaaS-tiered subscription models dominate enterprise procurement, with ISO 27001 certification tiers and multi-tenant governance capabilities commanding substantial premiums over basic storage tiers. Pricing pressure stems from hyperscaler storage price wars that erode standalone vendor margins. Marketing agencies show lowest price sensitivity due to consolidated procurement volume, while individual photographers in Tier-2 Indian cities exhibit highest elasticity.
Supply Chain Analysis
Tariff exposure between United States and Chinese semiconductor manufacturing dominates supply chain risk mapping for AI vision processing hardware. Taiwan, South Korea, and the United States anchor GPU and neural accelerator supply. NAND flash memory, hyperscaler egress bandwidth, and proprietary facial recognition algorithms constitute critical input dependencies. Single-source vulnerability concentrates in NVIDIA's datacenter GPU allocation frameworks. Distribution runs through direct enterprise sales teams for DAM deployments and self-service app marketplaces for consumer tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as marketing agency consolidation creates procurement niches for specialized compliance-forward and creator-economy-native platforms that bypass holding-company standardization.
For Market Incumbents: Pre-empt open-source AI vision model commoditization by embedding proprietary workflow intelligence layers that lock in campaign execution integration. Defend margin position through backward integration into edge computing node deployment, reducing hyperscaler egress dependency. ISO 27001 certification acceleration in Germany and United Kingdom markets creates defensible switching costs against mid-tier challengers. For New Entrants and Emerging Players: Build out freemium conversion infrastructure targeting Tier-2 Indian content studios lacking dedicated DAM procurement expertise. White-space concentration sits with EU AI Act compliance tooling for automated synthetic media provenance tracking. Go-to-market leverage through photographer community platforms bypasses enterprise sales cycle friction. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid deployment architectures requiring geographically distributed infrastructure. Long-term viability favors platforms with pre-built martech connector ecosystems rather than storage-scale pure-plays. Acquisition target archetype: mid-tier DAM specialists with vertical-specific template libraries. Signal to watch: holding-company RFP consolidation velocity as procurement centralization indicator.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Rebuild | Enables direct embedding into Adobe Creative Cloud and Canva production pipelines. |
| EU AI Act Compliance Module Launch | Captures automated audit trail demand from French and German publishing groups. |
| Edge Computing Node Expansion | Reduces round-trip latency for RAW file collaboration in distributed marketing teams. |
| Blockchain Copyright Verification Integration | Serves immutable timestamping demand from Bristol and Edinburgh stock photography clusters. |
| Freemium-to-Enterprise Conversion Infrastructure | Addresses procurement expertise gaps in Bangalore and Mumbai Tier-2 studios. |
Research Methodology
A standing panel of marketing operations directors, DAM procurement officers, cloud infrastructure architects, and photographer community platform managers provided ongoing calibration across the study period. Primary interview data combined with secondary validation from SEC filings of publicly traded creative software vendors, hyperscaler capex disclosures, and EU regulatory implementation guidance documents. Bottom-up deployment model sizing triangulated against top-down marketing technology spend allocation estimates.
Scenario-bracketing around GDPR enforcement intensity and hyperscaler pricing trajectory bounded value projections across the modeling period. Segmentation dimensions modeled encompass deployment architecture, organization size tier, solution type depth, and regional regulatory cluster. CAGRs derived from iterative convergence of adoption curve analysis and replacement cycle dynamics. AI vision API licensing cost trajectories and data localization infrastructure buildout requirements served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive bundling moves by integrated creative-suite providers or sudden hyperscaler storage price cuts would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
UX Services Market
Digital Solutions
Email Marketing Market
Digital Solutions
Real Time Bidding Market
Digital Solutions
United States ICT Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Self Service Technology Market
Digital Solutions
Cloud Based Manufacturing Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
IT Service Management Market
Digital Solutions
Italy Digital Twin Market
Digital Solutions
Product Design and Development Services Market
Digital Solutions
Global Digital Assurance Market
Digital Solutions
North America Digital Signage Market
Digital Solutions
Europe API Management Market
Digital Solutions
UAE ICT Market