
 Cyclotetrasiloxane Market | 2026-2036
Cyclotetrasiloxane Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclotetrasiloxane Market Outlook
ISO 22716 Good Manufacturing Practices certification is reorganizing supplier eligibility for cyclotetrasiloxane destined for cosmetic-grade applications. Dow Chemical Company leverages backward integration into chlorosilane feedstocks to sustain cost discipline across its siloxane portfolio. Wacker Chemie AG anchors European supply through its Burghausen manufacturing complex, while Shin-Etsu Chemical Co., Ltd. dominates Asian technical-grade output with proprietary direct-synthesis routes.
Cyclotetrasiloxane (D4) is a cyclic organosilicon compound with the formula [(CH3)2SiO]4, featuring a four-membered siloxane ring that imparts low surface tension and rapid volatility; manufacturers produce it via hydrolysis of dimethyldichlorosilane followed by fractional distillation and equilibration to isolate the tetramer. Liquid-grade material commands the widest formulation compatibility across skin-care and hair-care products, while gel and solid variants occupy narrower industrial niches where controlled release or thermal stability matters. The cosmetics application segment leads absolute volume, though coatings for electronics thermal management represent the fastest-expanding margin pool as semiconductor packaging demands higher-purity volatile silicones.
EPA oversight under the Toxic Substances Control Act and ECHA REACH restrictions on cyclic siloxane environmental persistence are elevating analytical certification costs for producers seeking dual-market access. China's MEE standards on volatile organic compound emissions from silicone manufacturing are forcing domestic producers toward closed-loop distillation systems. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory when purity thresholds or environmental hazard classifications shift without alignment.
Market Dynamics
REACH registration requirements and EPA chemical safety evaluations are tightening purity specifications simultaneously, forcing producers to recalibrate distillation infrastructure for dual-market compliance while cosmetic formulators accelerate procurement of volatile silicone delivery systems.
Growth Catalysts
- Cosmetic-grade volatile silicones:Formulators in skin-care and hair-care segments are expanding procurement of cyclotetrasiloxane for rapid-evaporation delivery systems that enhance spreadability without residue.
- China's MEE emission standards:Domestic silicone polymer capacity scaling under stricter volatile organic compound controls is concentrating downstream personal care compounder supply chains within the country's borders.
- Semiconductor thermal management:Electronics coatings demanding higher-purity volatile silicones for advanced packaging applications are pulling technical-grade material into faster-margin expansion.
Market Restraints
- Chlorosilane feedstock volatility:Dimethyldichlorosilane price swings transmit directly into cyclotetrasiloxane production economics, compressing margin buffers for non-integrated producers.
- European supply concentration:Burghausen complex dependency creates single-point vulnerability for REACH-certified cosmetic-grade material serving EU personal care manufacturers.
- Linear siloxane substitution:Low-viscosity dimethicone alternatives are penetrating fragrance and antiperspirant formulations where volatility specifications allow formulation flexibility.
Strategic Opportunities
- India personal care localization:BIS certification pathways for imported cyclic siloxanes remain underdeveloped, creating first-mover advantage for producers establishing analytical laboratories in Mumbai and Delhi clusters.
- Closed-loop distillation technology:China's MEE standards are forcing technology transfer partnerships between European engineering firms and domestic producers seeking emission-compliant capacity expansion.
- ISO 22716 GMP certification arbitrage:Supplier eligibility reorganization for cosmetic-grade applications enables tier-jumping for mid-scale producers investing in quality management systems ahead of customer mandates.
Industry Challenges
- Analytical chemist scarcity:EPA and ECHA divergence on cyclic siloxane environmental persistence classifications requires specialized toxicology expertise that competes with pharmaceutical sector hiring.
- Distillation column reconfiguration timelines:Shifting purity thresholds between jurisdictions strand capital equipment when regulatory alignment fails to materialize on forecast schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclotetrasiloxane Market |
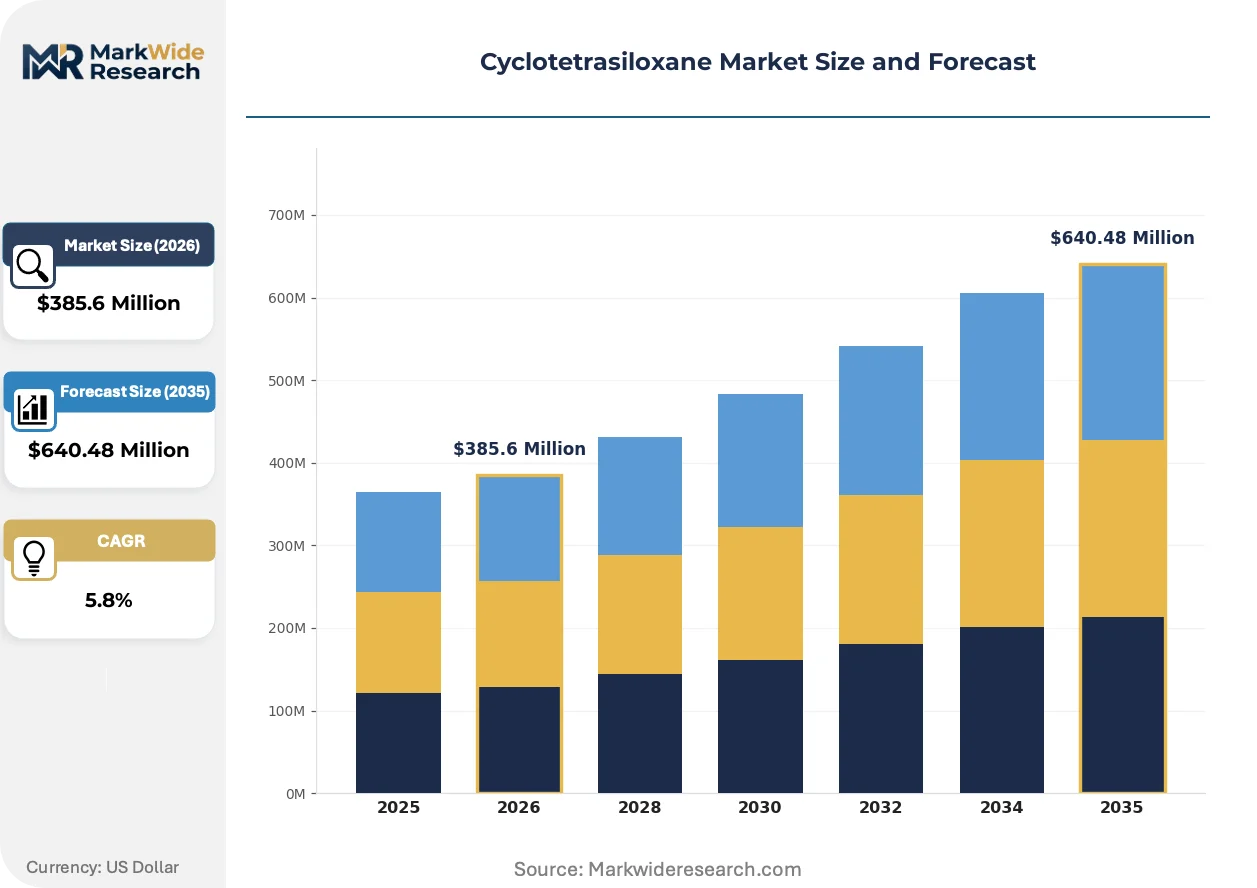
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Gel, Powder Application: Cosmetics, Textiles, Coatings, Adhesives End User: Beauty Brands, Textile Manufacturers, Automotive Sector, Electronics Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Dow Chemical Company, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Momentive Performance Materials Inc., Evonik Industries, BASF SE, Air Products and Chemicals, Inc., KCC Corporation, Elkem ASA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclotetrasiloxane Market Strategic Shifts
Direct-synthesis route refinement and regulatory divergence on environmental hazard classification are reshaping competitive capability requirements across the cyclotetrasiloxane value chain.
Membrane-based purification is supplanting conventional fractional distillation for high-purity electronics-grade material. Semiconductor packaging manufacturers in South Korea and Taiwan are specifying sub-ppm metallic impurity thresholds that legacy column technology cannot economically achieve. This shift is compressing the addressable market for standard-distillation producers while enabling premium pricing capture by technology leaders.
ECHA REACH restrictions on cyclic siloxane environmental persistence are elevating analytical certification costs for dual-market access. Producers seeking simultaneous US and EU qualification must maintain parallel testing protocols for biodegradation and bioaccumulation endpoints. Cosmetic-grade importers are responding by consolidating supplier relationships to amortize compliance overhead across larger volume commitments.
Personal care compounders are unbundling volatile silicone procurement from full-formulation service contracts. Brand owners in Germany and France are establishing direct relationships with certified raw material suppliers, bypassing traditional distributor intermediaries that previously managed specification compliance. This disintermediation concentrates volume with producers possessing in-house analytical laboratories and regulatory documentation capabilities.
Cyclotetrasiloxane Market Segmentation
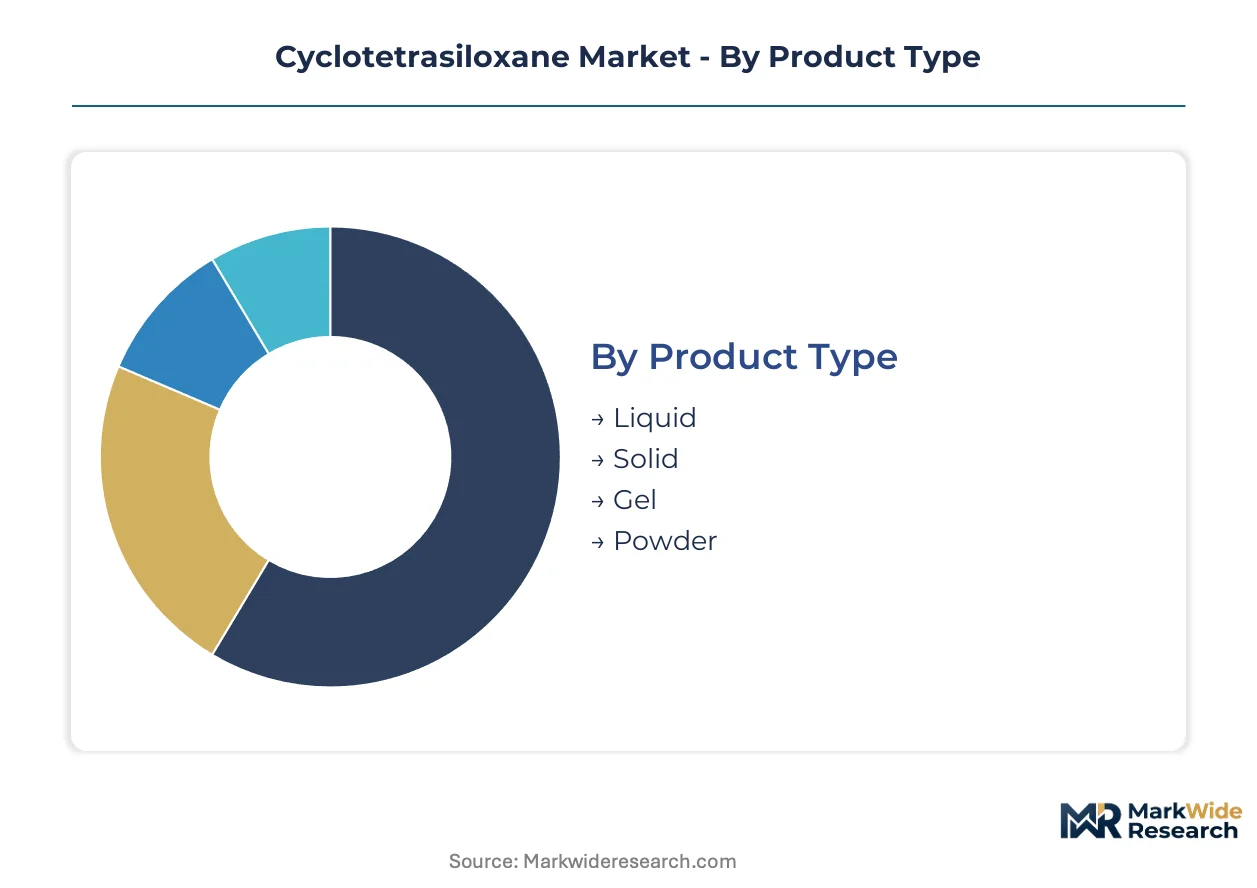
Cyclotetrasiloxane procurement patterns diverge sharply across physical form and customer sophistication, with cosmetic formulators prioritizing volatility control while industrial buyers emphasize thermal stability specifications. Understanding these segment boundaries enables producers to align distillation investments with margin architecture rather than treating the material as a commodity siloxane.
Product Type:
Substitution pressure from linear dimethicones and volatile hydrocarbons hits powder and solid grades hardest, while liquid formulations maintain formulation irreplaceability in premium cosmetic applications.
- Liquid:The dominant physical state for cosmetic-grade cyclotetrasiloxane, characterized by low viscosity and rapid evaporation kinetics that enable spreadable skin-care delivery systems without residue formation. Demand concentrates in Shanghai and Guangzhou personal care manufacturing clusters where domestic compounders localize supply chains under China's MEE emission standards.
- Gel:Semi-solid matrices formed through controlled crosslinking of cyclic siloxane precursors, offering sustained release properties valued in pharmaceutical topical applications. Electronics thermal management specialists in South Korea specify gel grades for conformal coating applications where viscosity stability under thermal cycling determines performance.
- Solid:Polymerized cyclic siloxane networks with elevated thermal stability, serving niche industrial applications where dimensional retention matters. Textile finishing operations in India represent emerging demand pockets as BIS certification pathways mature for imported cyclic siloxanes.
- Powder:Micronized particulate forms produced through spray-drying of emulsified siloxane fluids, encountering substitution pressure from fumed silica in powder cosmetic formulations. Dry shampoo and loose powder manufacturers in Germany evaluate powder cyclotetrasiloxane against cost-competitive mineral alternatives.
Liquid grade anchors the volume base while gel formulations gain share at the steepest rate as semiconductor packaging complexity escalates.
Application:
Cost tier stratification separates cosmetic applications commanding purity premiums from industrial coatings competing on throughput economics.
- Cosmetics:The leading application by absolute volume, spanning skin-care serums, hair-care conditioners, and antiperspirant bases where rapid volatility enhances sensory profile. ISO 22716 GMP certification requirements are reorganizing supplier eligibility as brand owners in France and Germany bypass distributor intermediaries for direct raw material procurement.
- Coatings:Electronics thermal management coatings represent the fastest-expanding margin pool, with sub-ppm metallic impurity thresholds specified by Taiwan semiconductor packaging manufacturers. Membrane-based purification technology is supplanting conventional distillation for this addressable market.
- Textiles:Fabric softening and water-repellency finishing applications where cyclotetrasiloxane serves as a volatile carrier for functional polymers. REACH registration requirements elevate analytical certification costs for European textile chemical distributors consolidating supplier relationships.
- Adhesives:Pressure-sensitive and structural adhesive formulations leveraging low surface tension for substrate wetting, competing with acrylic and silicone linear polymer alternatives. Automotive sector adhesive compounders in Japan specify technical-grade material where volatility specifications permit formulation flexibility.
Cosmetics commands the revenue concentration while coatings climbs the fastest as purity thresholds escalate in advanced packaging.
End User:
Customer type determines specification stringency, with beauty brands demanding full regulatory documentation and automotive buyers prioritizing supply security over analytical depth.
- Beauty Brands:Multinational personal care manufacturers and indie formulators alike requiring REACH-certified, EPA-registered material with full toxicology dossiers. Direct procurement relationships are displacing traditional distributor channels as brand owners internalize compliance risk management.
- Electronics:Semiconductor packaging houses and thermal interface material producers specifying electronics-grade purity with membrane-purification provenance. South Korean and Taiwanese manufacturers drive specification escalation through sub-ppm metallic impurity requirements.
- Textile Manufacturers:Fabric finishers and garment treatment facilities in India and Bangladesh evaluating cyclotetrasiloxane against European and Chinese supply alternatives. BIS certification gaps create first-mover opportunity for producers establishing Mumbai analytical capabilities.
- Automotive Sector:Adhesive and sealant compounders prioritizing supply security and volume pricing over cosmetic-grade documentation. Technical-grade cyclotetrasiloxane from Shin-Etsu's direct-synthesis routes serves this price-sensitive segment.
Beauty brands anchor the specification premium tier while electronics expands most quickly as thermal management complexity intensifies.
Distribution Channel:
Supply concentration in producer-direct relationships is compressing distributor margins as regulatory documentation requirements favor integrated supply chains.
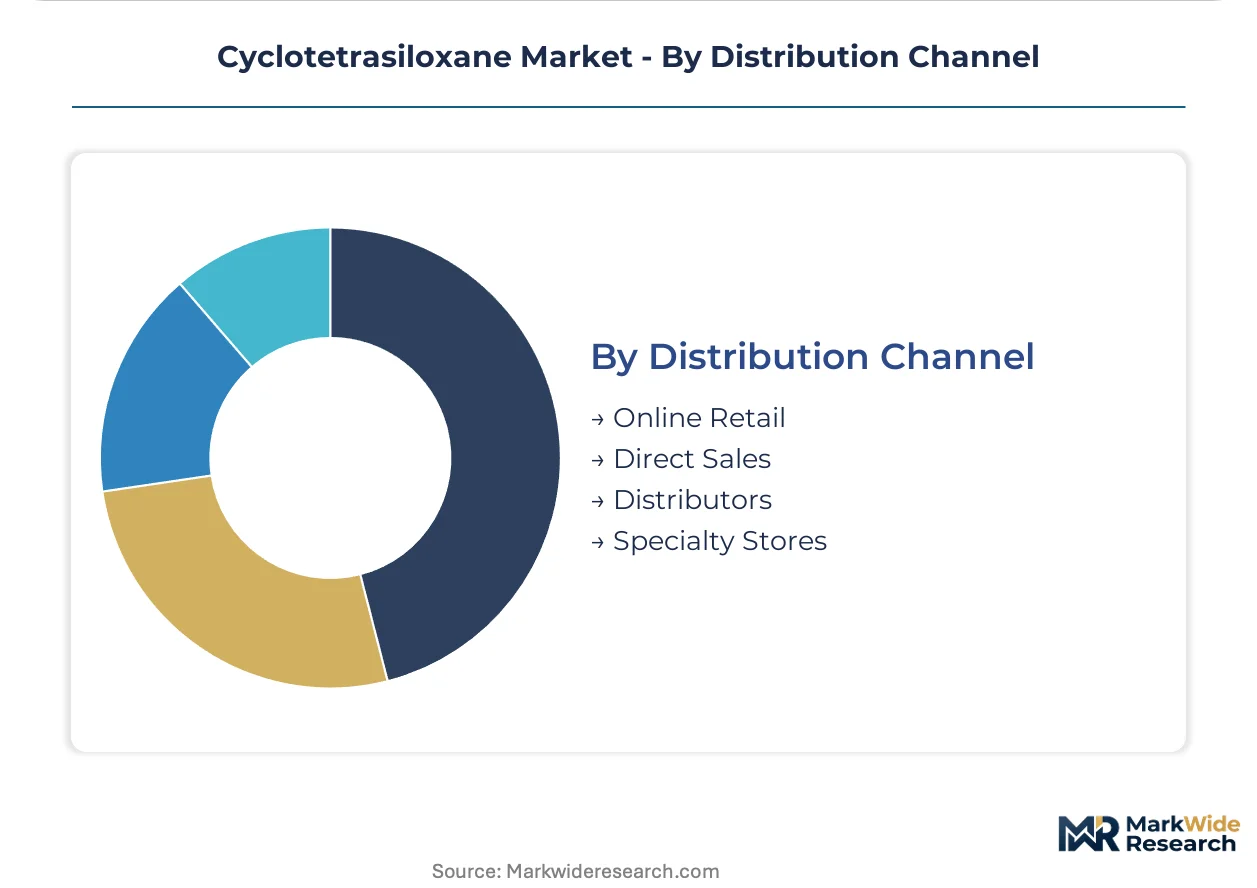
- Direct Sales:Producer-to-manufacturer relationships dominating cosmetic-grade and electronics-grade volume, enabled by in-house analytical laboratories and parallel EPA/ECHA testing protocols. Dow Chemical and Wacker Chemie leverage backward integration to sustain direct channel economics.
- Distributors:Traditional chemical distribution intermediaries facing disintermediation as brand owners consolidate supplier relationships to amortize compliance overhead. Surviving distributors specialize in technical-grade material for automotive and textile price-sensitive segments.
- Online Retail:Emerging channel for small-volume cosmetic compounders and research institutions requiring rapid sample turnaround. Alibaba and specialty chemical platforms serve India and Southeast Asia procurement patterns.
- Specialty Stores:Niche channel serving artisanal cosmetic formulators and academic research facilities with packaged laboratory quantities. Limited scale constrains producer investment in this channel infrastructure.
Direct sales anchors the volume base while online retail gains share at the steepest rate as procurement digitization penetrates mid-scale compounders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH registration requirements in Europe and EPA chemical safety evaluations in the United States are tightening purity specifications simultaneously, forcing producers to recalibrate distillation infrastructure for dual-market compliance while China's MEE emission standards reshape Asian supply chains.
United States
Cosmetic formulators in New Jersey and California are accelerating procurement of volatile silicone delivery systems for skin-care applications. EPA oversight under the Toxic Substances Control Act elevates analytical certification costs for cyclic siloxane imports. Houston-area chemical distributors consolidate supplier relationships to amortize compliance overhead across larger volume commitments.
Germany
Personal care brand owners in Frankfurt and Düsseldorf are establishing direct relationships with certified raw material suppliers, bypassing traditional distributor intermediaries. ECHA REACH restrictions on cyclic siloxane environmental persistence require parallel testing protocols for biodegradation endpoints. The Burghausen manufacturing complex anchors European supply for REACH-certified cosmetic-grade material.
China
Domestic silicone polymer capacity scaling concentrates downstream personal care compounder supply chains within Shanghai and Guangzhou manufacturing clusters. MEE standards on volatile organic compound emissions force producers toward closed-loop distillation systems. Technology transfer partnerships between European engineering firms and domestic producers enable emission-compliant capacity expansion.
South Korea
Semiconductor packaging manufacturers in Seoul and Suwon specify sub-ppm metallic impurity thresholds for electronics-grade volatile silicones. Membrane-based purification technology supplants conventional fractional distillation for high-purity thermal management coatings. Samsung and SK Hynix supply chain specifications drive specification escalation through direct producer relationships.
India
Textile finishers in Mumbai and garment treatment facilities in Delhi evaluate cyclotetrasiloxane against European and Chinese supply alternatives. BIS certification pathways for imported cyclic siloxanes remain underdeveloped, creating first-mover advantage for producers establishing analytical laboratories in Mumbai clusters. Domestic personal care localization accelerates procurement from certified raw material suppliers.
Cyclotetrasiloxane Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and regulatory documentation capability. The vendor base organizes around three tiers: integrated chlorosilane producers with backward control over feedstock economics, regional specialists leveraging proprietary direct-synthesis routes, and distributors facing disintermediation as brand owners internalize compliance risk. Dominant competitive moves include capacity expansion under stricter emission controls and strategic partnerships for technology transfer of closed-loop distillation systems.
Within the integrated chemical producer tier, Dow Chemical Company and Wacker Chemie AG exemplify archetypes combining captive feedstock supply with in-house analytical laboratories. Shin-Etsu Chemical Co., Ltd. occupies a position representing Asian technical-grade output specialists with proprietary manufacturing approaches. These three entities anchor the competitive structure across dual-market compliance requirements, with each representing distinct geographic and capability positioning within the broader cyclic siloxane value chain.
| Leading Market Players |
|---|
| Dow Chemical Company |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Momentive Performance Materials Inc. |
| Evonik Industries |
| BASF SE |
| Air Products and Chemicals, Inc. |
| KCC Corporation |
| Elkem ASA |
| Others |
Value Chain & Pricing Dynamics
Chlorosilane feedstock scale economies at integrated producers like Dow Chemical and Wacker Chemie establish cost floors that non-integrated competitors cannot match, compressing margins for merchant market participants while concentrating pricing power among backward-integrated suppliers serving dual REACH and EPA compliance requirements.
Pricing Analysis
Certification level creates the primary spread between cosmetic-grade and technical-grade material, with ISO 22716 GMP-certified product commanding substantial premiums over standard-distillation output for personal care applications. Three-tier pricing structure separates electronics-grade membrane-purified material from REACH-certified cosmetic grades and technical-grade automotive supply, with cost compression in the technical tier intensifying as Shin-Etsu's direct-synthesis routes expand Asian capacity. Beauty brands demonstrate lowest price sensitivity due to formulation lock-in requirements, while textile finishers in India exhibit highest elasticity as BIS certification gaps delay specification adoption.
Supply Chain Analysis
Burghausen complex dependency creates single-point vulnerability for European REACH-certified cosmetic-grade material, with Wacker Chemie's German manufacturing anchoring EU supply while Shin-Etsu's Japanese and Chinese facilities dominate Asian technical-grade output. Dimethyldichlorosilane feedstock draws from chlorosilane crackers concentrated in Germany, China, and the United States, with logistics exposure concentrated in Rotterdam-Antwerp chemical port throughput for European downstream access. Tariff exposure on cyclic siloxane imports into India elevates landed costs for non-localized suppliers. Distribution runs through direct producer relationships for certified grades, with surviving distributors relegated to technical-grade automotive and textile segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
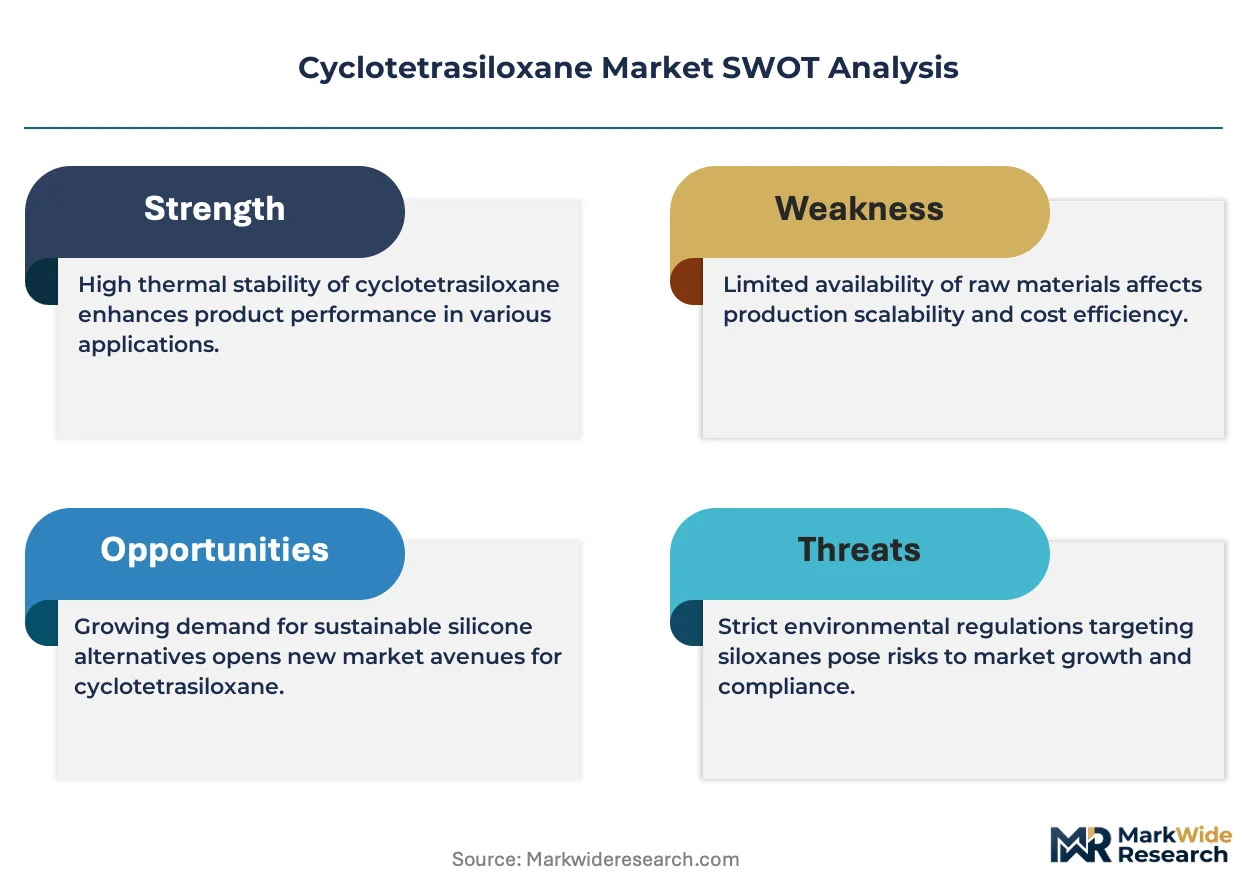
This market rewards regulatory entrenchment as a defensive moat, with ISO 22716 certification requirements and parallel EPA/ECHA testing protocols creating switching costs that cement incumbent positions against merchant competitors lacking in-house analytical infrastructure.
For Market Incumbents: Fortify backward integration into chlorosilane feedstocks to sustain cost discipline against emerging Chinese capacity, while accelerating ISO 22716 certification coverage ahead of customer mandate consolidation. Capacity addition in Mumbai analytical clusters captures India localization before BIS pathways mature. Threat from linear dimethicone substitution in fragrance applications demands formulation partnership defenses. For New Entrants and Emerging Players: Differentiate on membrane-purification technology for electronics-grade material where sub-ppm metallic thresholds exclude legacy distillation competitors. Target South Korean semiconductor packaging houses as the most penetrable premium segment, leveraging direct technical sales relationships bypassing distributor disintermediation. White-space exists in India textile finishing as BIS certification gaps delay incumbent localization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors producers with captive chlorosilane supply and dual-market regulatory documentation capabilities over pure-play distillation operators. Acquisition target archetype: regional specialists with proprietary direct-synthesis routes and established EPA registration portfolios. Signal to watch: MEE enforcement intensity in China forcing technology transfer partnerships that reveal compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstocks | Dow Chemical's captive dimethyldichlorosilane supply sustains margin buffers against merchant market volatility. |
| ISO 22716 GMP Certification Investment | Quality management system deployment enables tier-jumping ahead of cosmetic brand owner mandate consolidation. |
| Membrane-Purification Technology Adoption | South Korean electronics manufacturers specify sub-ppm metallic thresholds that exclude legacy column technology. |
| Mumbai Analytical Laboratory Establishment | First-mover positioning captures India textile and personal care localization before BIS certification pathways mature. |
| Closed-Loop Distillation Partnership | European engineering firm technology transfer enables Chinese producers to meet MEE emission standards during capacity expansion. |
Study Parameters
Cross-validation between primary interviews with plant managers at chlorosilane crackers and secondary analysis of customs trade data anchors the qualitative findings on supply concentration dynamics. Procurement leads at downstream personal care compounders, distribution channel partners in Houston and Rotterdam chemical ports, and technical R&D directors at membrane-purification technology providers contributed field intelligence. Secondary sources include ECHA REACH registration dossiers, EPA TSCA chemical data reporting, ACC silicone industry statistics, and SEC 10-K disclosures from listed chemical producers. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Sensitivity analysis across feedstock price scenarios and regulatory enforcement intensity variations shapes the projection framework. Segmentation dimensions modeled include physical form grade tier, end-use application, end-user customer type, and regional production hub classification. CAGRs derive from weighted-average growth contributions across these segments, with inputs from chlorosilane capacity utilization rates and semiconductor packaging thermal management demand trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EPA-ECHA regulatory divergence or abrupt MEE enforcement escalation would require recalibration. Forecasts reflect documented assumptions on capacity expansion timelines and substitution elasticity parameters. Practitioners should keep alternative scenarios live as chlorosilane feedstock volatility and India BIS certification maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surfactants
Global Silicone Surfactants Market
Surfactants
Global Demulsifiers Market
Surfactants
Emulsifying Wax Market
Surfactants
Sodium Lauroyl Sarcosinate Market
Surfactants
Coconut Derived Surfactants Market
Surfactants
Global Methyl Ester Sulfonate Market
Surfactants
North America Surfactants Market
Surfactants
Polyoxyethylene Sorbitan Tristearate Market
Surfactants
Amino Acid Surfactants Market
Surfactants
Asia Pacific Biosurfactants Market
Surfactants
Procream Market
Surfactants
Sulfosuccinate Market
Surfactants
Lauramide DEA Market
Surfactants
Sodium Naphthalene Sulphonate Formaldehyde Market
Surfactants
Global Low Foam Surfactants Market
Surfactants
Detergent Chemicals Market