
 North America Home Heating Appliances Market | 2026-2036
North America Home Heating Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
North America Home Heating Appliances Market Insights
Multi-source component procurement is decoupling from the legacy single-source relationships that dominated North American HVAC supply chains for decades. Honeywell International Inc. leverages its controls and automation portfolio to anchor positions across thermostat and building management interfaces. Daikin Industries Ltd. sustains manufacturing scale through its US-based heat pump production facilities, while Lennox International Inc. competes through dealer network density across the US Sun Belt and Midwest.
North America home heating appliances encompass closed-system thermal energy devices designed to raise and maintain indoor air or water temperature through combustion, electric resistance, or vapor-compression refrigeration cycles, typically rated between 40,000 and 120,000 BTU per hour for residential units. These systems serve the fundamental commercial purpose of occupant thermal comfort, freeze protection, and process heat in buildings ranging from single-family dwellings to multi-unit commercial structures. Furnaces and heat pumps command the largest installed base across the region, though heat pumps are gaining share fastest as cold-climate performance thresholds improve and utility rebate programs deepen. Natural gas retains dominance in existing stock while electric fuel types capture disproportionate new construction share, particularly in jurisdictions with building electrification mandates.
The US Department of Energy appliance efficiency standards and Canada's Natural Resources Canada EnerGuide program jointly shape minimum performance thresholds and testing protocols for products sold across the region. The US Inflation Reduction Act tax credits and state-level building codes in California, New York, and Massachusetts are accelerating heat pump penetration by narrowing first-cost gaps with conventional furnaces. Stakeholders must monitor evolving cold-climate heat pump certification standards and utility demand-response integration requirements as grid electrification intensifies.
Market Dynamics
Building electrification mandates across US states and Canadian provinces are forcing rapid product portfolio reconfiguration among heating equipment manufacturers, compressing development cycles for cold-climate heat pump variants.
Growth Catalysts
- US Inflation Reduction Act tax credits:Federal incentives up to $2,000 per heat pump installation narrow first-cost gaps with gas furnaces in retrofit applications across the US Northeast.
- Cold-climate performance thresholds:Heat pumps rated to -15°F operation expand addressable markets in Minnesota, Wisconsin, and Canadian provinces previously dependent on fossil fuel heating.
- Utility demand-response integration:Grid-interactive water heaters and smart thermostats create recurring revenue streams for manufacturers embedding controls in heating appliances.
Market Restraints
- Copper and aluminum price volatility:Heat pump coils and refrigerant piping expose manufacturers to commodity swings that compress margin on fixed-price contractor bids.
- Refrigerant supply concentration:US EPA phasedown of HFCs under AIM Act rules ties equipment availability to limited domestic production of low-GWP alternatives.
- Installer capacity constraints:Shortage of technicians certified for refrigerant handling and electrical work extends project timelines in high-demand markets.
Strategic Opportunities
- Quebec's accelerated building electrification:Provincial ban on fossil fuel heating in new construction from 2025 creates captive demand for electric heat pumps in multi-unit residential builds.
- Heat pump water heater convergence:Integration of space heating and domestic hot water functions reduces equipment footprint and installation labor for single-family retrofits.
- Aggregator-enabled grid services:Partnerships with virtual power plant operators monetize thermal storage in water heaters and space conditioning loads.
Industry Challenges
- AHRI certification backlog:Testing laboratory capacity constraints delay product launches for cold-climate heat pump ratings required by utility rebate programs.
- Legacy furnace replacement compatibility:Ductwork sizing and electrical panel upgrades complicate retrofit economics in 1970s-1990s US housing stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Home Heating Appliances Market |
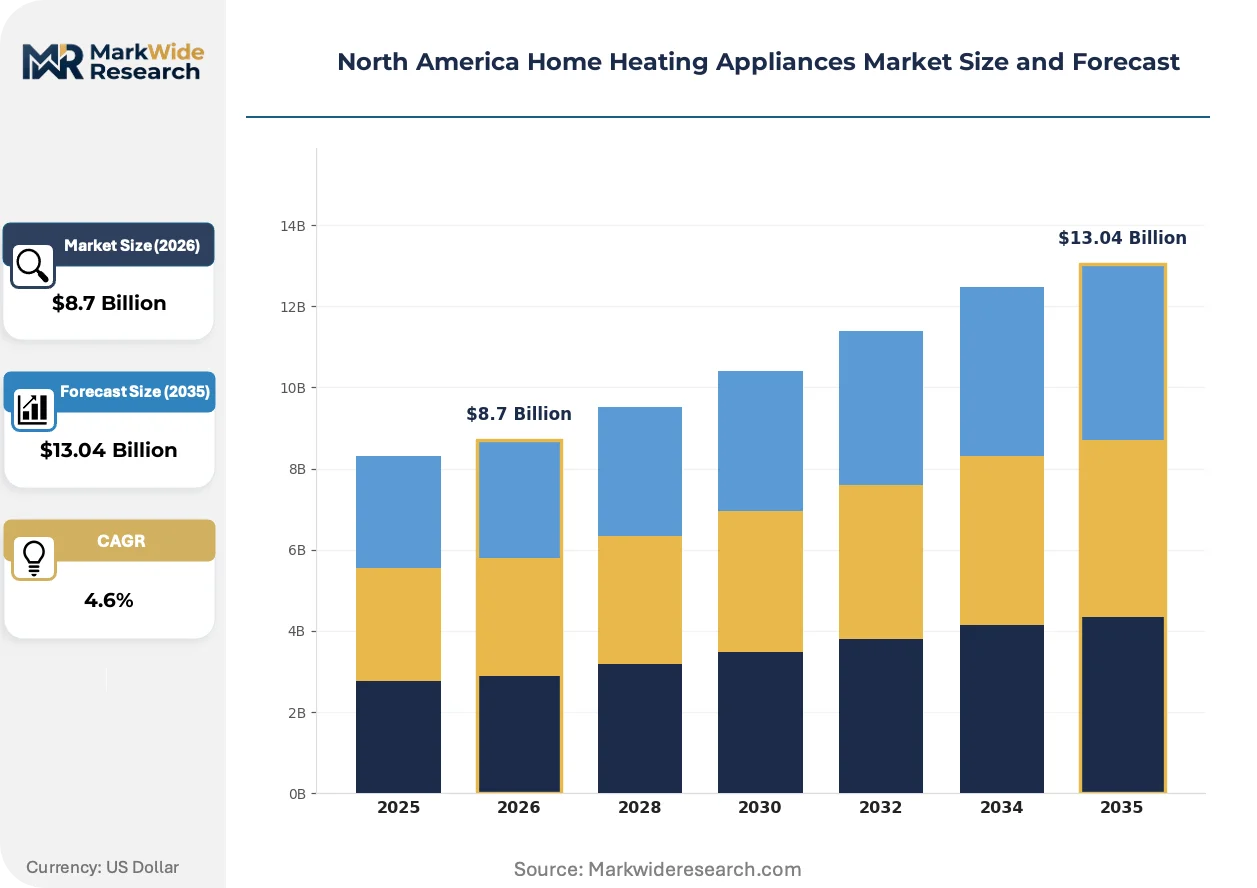
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furnaces, Heat Pumps, Boilers, Radiators Fuel Type: Natural Gas, Electric, Propane, Oil End User: Residential, Commercial, Industrial, Institutional Installation Type: New Construction, Retrofit, Modular, Centralized |
| Companies Covered | Honeywell International Inc., Daikin Industries Ltd., Lennox International Inc., Johnson Controls, Carrier, Trane Technologies plc, Emerson Electric Co., Siemens AG, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Home Heating Appliances Market Trends and Innovations
Electrification hardware and software are converging to transform heating appliances into grid-interactive assets, shifting value capture from equipment sales toward ongoing energy service relationships.
Cold-climate heat pump technology is absorbing compressor engineering advances that extend operating range below -20°F without auxiliary resistance heat. US Northeast utilities are prioritizing these systems for rebate eligibility. This capability expansion is absorbing market share from oil-fired boilers in Maine and Vermont residential retrofits.
Canada's Natural Resources Canada EnerGuide program is tightening testing protocols for seasonal performance factor ratings, forcing manufacturers to optimize defrost cycles and fan modulation. The regulatory pressure elevates variable-speed compressor adoption. Cold-climate heat pump categories face the steepest compliance redesign requirements.
Homeowner buying patterns are fragmenting across contractor-direct, utility-sponsored, and retail channels. Big-box retailers in the US Midwest are piloting heat pump SKUs with bundled installation services. This channel experimentation concentrates in Michigan and Ohio markets with aggressive utility electrification programs.
North America Home Heating Appliances Market Segmentation
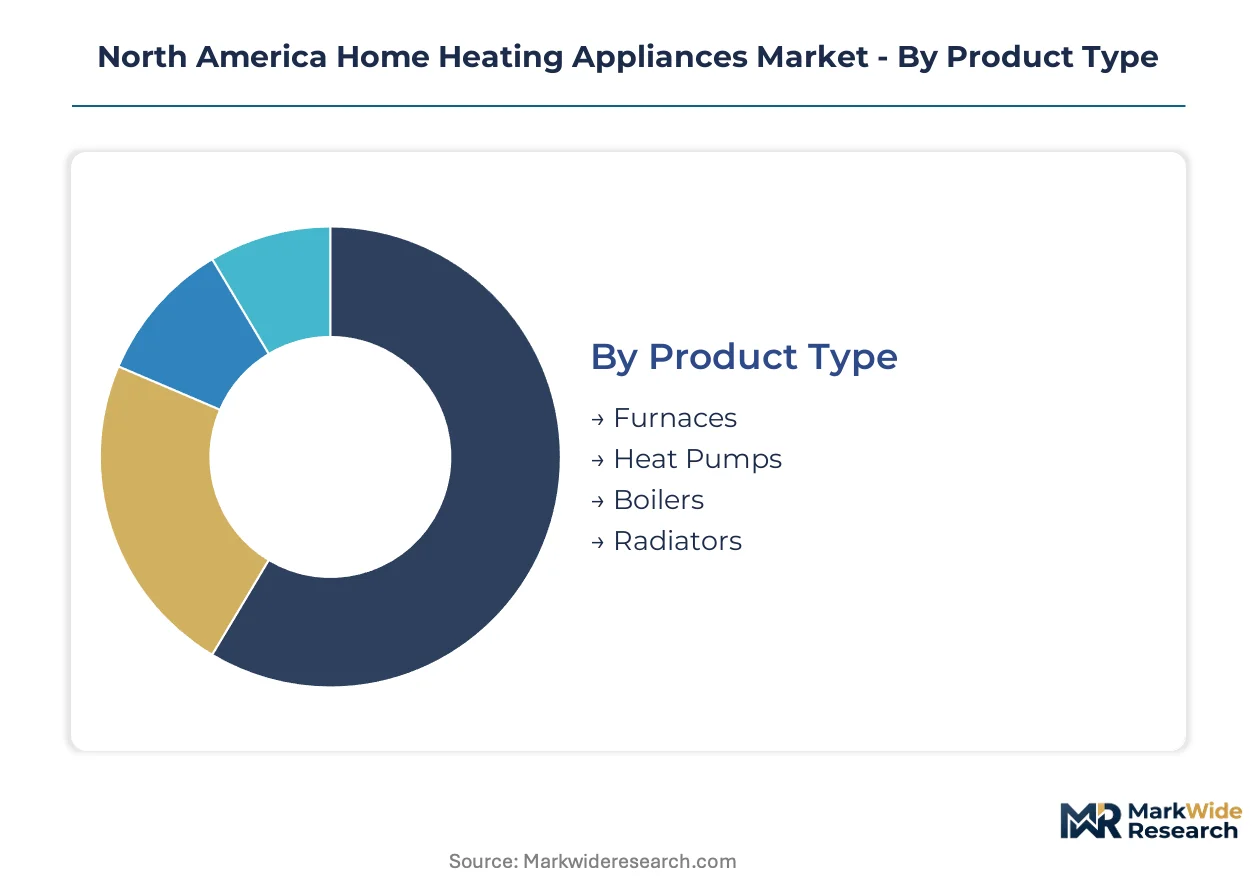
Product configuration in North American home heating varies sharply by building vintage, fuel availability, and electrification policy intensity. Segment boundaries are blurring as heat pump platforms absorb water heating and space conditioning functions.
Product Type:
Standalone appliances dominate residential retrofits where existing ductwork or hydronic distribution constrains replacement options. Embedded systems gain traction in new construction through integrated mechanical packages.
- Furnaces:Forced-air gas-fired units rated 80,000-100,000 BTU/hour remain the default replacement in US Midwest states with established natural gas distribution. Aging stock in 1980s housing drives consistent replacement demand despite electrification headwinds.
- Heat Pumps:Vapor-compression systems with cold-climate ratings to -15°F capture disproportionate policy support from US Northeast utilities and Canadian provincial rebate programs. Cold-climate variants now displace oil boilers in Maine and Vermont residential retrofits.
- Boilers:Hydronic heat generators serve legacy radiator systems in pre-1950s Northeast housing and multi-unit buildings where ductwork retrofit proves cost-prohibitive.
- Radiators:Terminal heat emitters in hydronic systems persist in institutional and heritage residential structures across Ontario and Quebec.
Furnaces lead volumes today; heat pumps are gaining share fastest.
Fuel Type:
Cost tiers stratify sharply by regional infrastructure maturity and carbon pricing exposure. Premium electric configurations command first-cost premiums that utility incentives and operating savings must offset.
- Natural Gas:Pipeline-delivered fossil fuel retains lowest levelized cost in US Great Lakes and Mid-Atlantic states with mature distribution networks. US EPA methane regulations and state-level building electrification mandates threaten long-term demand trajectory.
- Electric:Grid-sourced power drives heat pump operation and resistance backup, concentrated in jurisdictions with low-carbon electricity portfolios—Quebec hydro, Ontario nuclear, and Pacific Northwest hydro regions.
- Propane:Tank-stored liquefied petroleum gas serves rural exurbs beyond natural gas mains across US Mountain West and Canadian Prairie provinces.
- Oil:Delivered distillate fuel persists in isolated US Northeast rural markets and Atlantic Canada where pipeline gas never penetrated; carbon taxes accelerate displacement.
Natural gas dominates installed base; electric fuel types capture disproportionate new construction share.
End User:
Customer type determines specification rigor, maintenance protocols, and procurement channel. Institutional buyers impose extended warranty and service contract requirements absent from residential transactions.
- Residential:Single-family and multi-family dwellings constitute the volume core, with electrification mandates in California, New York, and Massachusetts reshaping new construction specifications.
- Commercial:Retail, office, and hospitality structures drive packaged rooftop and split-system demand with shorter replacement cycles than residential stock.
- Industrial:Process heat and freeze protection applications in manufacturing facilities specify higher-capacity units with specialized controls integration.
- Institutional:Schools, hospitals, and government buildings prioritize redundancy and compliance with ASHRAE standards, often requiring centralized plant configurations.
Residential segments anchor volume; commercial replacement cycles drive recurring revenue.
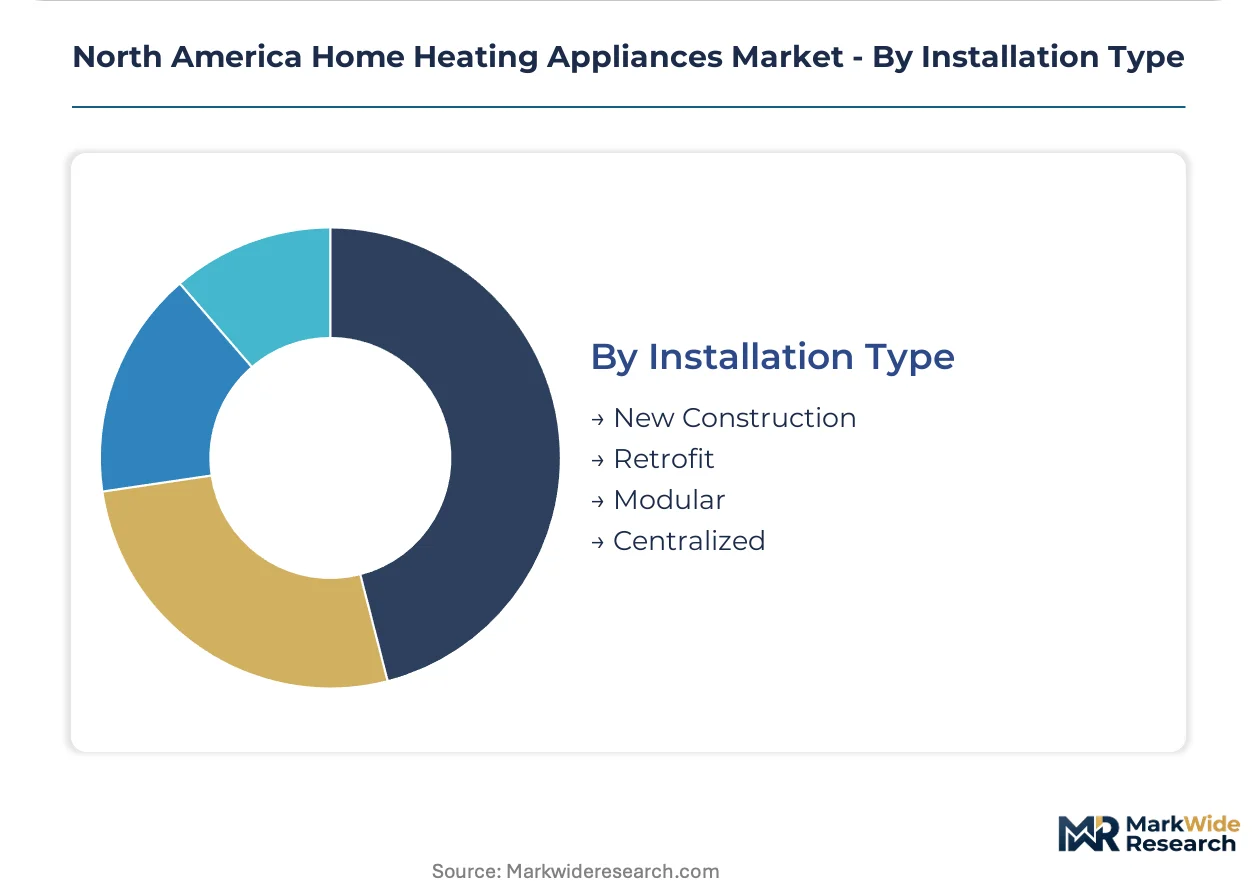
Installation Type:
Maturity gradients separate greenfield specification freedom from retrofit constraint. Modular and centralized approaches concentrate in multi-unit developments where scale economies justify custom engineering.
- New Construction:Greenfield installations specify right-sized heat pump systems without legacy distribution constraints, concentrated in US Sun Belt growth corridors and Canadian suburban expansion zones.
- Retrofit:Replacement applications in 1970s-1990s US housing stock face ductwork sizing and electrical panel upgrade complications that extend project timelines.
- Modular:Pre-engineered mechanical packages serve multi-unit residential and light commercial developments in Ontario and British Columbia where construction speed drives procurement decisions.
- Centralized:District-scale heating plants with distribution networks persist in university campuses and urban master-planned communities with shared thermal infrastructure.
Retrofit installations dominate replacement demand; new construction specifications are electrifying most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Great Lakes corridor anchors North American heating equipment manufacturing and demand concentration. Cold-climate heat pump adoption accelerates across jurisdictions with aggressive electrification mandates. Regional policy fragmentation creates divergent product specification requirements between US states and Canadian provinces.
United States
Retrofit installations in 1970s-1990s housing stock across the Northeast and Midwest drive replacement cycles for aging oil and natural gas systems. The US Department of Energy's updated appliance efficiency standards reshape product mix toward electric heat pumps. Minnesota and Wisconsin markets expand as cold-climate heat pump ratings to -15°F operation displace fossil fuel dependence.
Canada
Ontario and Quebec provinces concentrate demand where hydroelectric portfolios support building electrification economics. Natural Resources Canada EnerGuide program tightening of seasonal performance factor ratings forces defrost cycle optimization. Quebec's 2025 ban on fossil fuel heating in new construction creates captive demand for electric heat pumps in multi-unit residential builds.
Mexico
Northern border states exhibit nascent heat pump adoption tied to cross-border supply chain integration and US-export-oriented manufacturing facilities. Federal energy efficiency standards lag US and Canadian stringency, preserving natural gas furnace dominance. Monterrey and Tijuana industrial corridors drive commercial HVAC specification alignment with US efficiency benchmarks.
North America Home Heating Appliances Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cold-climate heat pump specialization and grid-interactive controls integration. The vendor base stratifies across three tiers: diversified industrial conglomerates with controls portfolios, dedicated HVAC specialists with manufacturing scale, and regional fabricators serving retrofit replacement cycles. Strategic archetypes include full-system integrators, component specialists, and utility-facing service aggregators. Competitive moves concentrate on M&A for refrigerant handling capabilities and strategic partnerships with virtual power plant operators.
Among diversified industrial conglomerates, Honeywell International Inc. and Siemens AG exemplify the controls-anchored archetype spanning thermostat interfaces and building management systems. Daikin Industries Ltd. occupies a position representing manufacturing scale through US-based production facilities. Mitsubishi Electric Corporation sits within the cold-climate specialization tier, with product positioning emphasizing extended operating range performance.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Daikin Industries Ltd. |
| Lennox International Inc. |
| Johnson Controls |
| Carrier |
| Trane Technologies plc |
| Emerson Electric Co. |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap HVAC fabricators across the US Midwest and Ontario anchor regional supply networks through multi-generational distributor relationships, translating procurement scale into pricing discipline that resists commoditization pressure from big-box retail channels. Their ownership structure enables long-term refrigerant supply contracting that insulates margin from spot-market volatility while sustaining dealer-exclusive pricing tiers.
Pricing Analysis
Input-cost pass-through from copper coil and aluminum fin stock volatility governs equipment pricing, with manufacturers indexing contract quotes to LME spot movements on 30-60 day lags. Three-tier pricing structure across premium cold-climate certified, standard efficiency, and economy contractor-grade equipment segments reflects AHRI certification tier and warranty length. Pricing pressure stems from utility rebate program co-pay requirements that cap installed-cost ceilings for rebate eligibility. Residential retrofit contractors exhibit highest price sensitivity due to competitive bidding environments, while institutional buyers prioritize lifecycle operating cost over first-cost.
Supply Chain Analysis
Warehouse-distribution layer consolidation across the US Great Lakes corridor concentrates inventory positioning within 200-mile radius of Detroit, Cleveland, and Toronto regional distribution centers. Manufacturing draws from Mexican compressor assembly plants, US Southeast coil fabrication facilities, and Chinese electronic control component suppliers. Single-source vulnerability in low-GWP refrigerant supply chains under US EPA AIM Act phasedown rules threatens equipment availability. Distribution runs through authorized dealer networks with exclusive territory assignments, though direct-to-contractor e-commerce platforms are eroding traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where the US Inflation Reduction Act's $2,000 residential heat pump tax credit and Quebec's 2025 fossil fuel heating ban in new construction create durable demand tailwinds independent of cyclical construction activity.
For Market Incumbents: Hedge refrigerant supply exposure through backward integration into low-GWP alternative sourcing or long-term offtake agreements with domestic chemical producers. Defend dealer network density against direct-channel encroachment by embedding utility rebate program administration into distributor service offerings. Cold-climate certification investment represents the priority capability lever as utility program eligibility tightens.
For New Entrants and Emerging Players: Direct-to-contractor digital procurement platforms bypass incumbent distributor markups in Michigan and Ohio markets with aggressive electrification mandates. White-space concentrates in grid-interactive water heater aggregation services for virtual power plant operators, and in packaged heat pump solutions for 1970s-1990s housing stock with constrained ductwork. Target utility-sponsored installation programs as the most penetrable channel, leveraging rebate program co-marketing for customer acquisition.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional HVAC service aggregators with refrigerant handling licenses and established utility program relationships, rather than equipment manufacturers facing commodity margin compression. The 5-10 year viability window favors asset-light service platforms over capital-intensive manufacturing. Watch cold-climate heat pump AHRI certification backlog resolution as the signal for product launch velocity inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Supply Agreement | Secures low-GWP alternative access ahead of US EPA AIM Act supply constraints. |
| Cold-Climate Certification Investment | Unlocks utility rebate program eligibility in Minnesota and Wisconsin markets. |
| Virtual Power Plant Partnership | Monetizes thermal storage in water heaters through grid services revenue streams. |
| Dealer Network Acquisition | Consolidates installation capacity in Quebec's electrifying multi-unit residential segment. |
| Integrated Heat Pump Water Heater Launch | Reduces equipment footprint for single-family retrofits in constrained 1980s housing stock. |
Research Methodology
Bottom-up residential and commercial end-use modeling reconciled against top-down manufacturing capacity and shipment tracking forms the analytical core of this study. Primary interviews with HVAC contractor business owners, utility program administrators, distributor procurement managers, and manufacturer product planning directors combined with secondary validation from US EIA residential energy consumption surveys, Natural Resources Canada EnerGuide appliance databases, AHRI certification directories, and EPA refrigerant phasedown regulatory filings. Triangulation across these sources isolates equipment replacement cycle timing from new construction demand.
Historical trendline analysis of equipment shipments, fuel-type switching patterns, and utility incentive program participation rates established baseline growth trajectories. Segmentation modeling across product type, fuel source, installation vintage, and regional electrification policy intensity generated volume and value outputs. CAGRs were derived from regression analysis of policy-driven adoption curves and technology cost reduction trajectories. Cold-climate performance threshold improvements and grid-interactive controls integration served as key technology input variables.
Regulatory implementation delays, refrigerant supply disruptions, and installer labor shortage intensification are the dominant revision risks to forecast assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home Appliances
GCC Major Home Appliances Market
Home Appliances
White Goods Market
Home Appliances
United Kingdom Washing Machine Market
Home Appliances
Australia Home Appliances Market
Home Appliances
Merchandizing Refrigerators Market
Home Appliances
Colombia Home Appliances Market
Home Appliances
Kuwait Small Home Appliances Market
Home Appliances
China Home Appliances Market
Home Appliances
UAE Home Appliances Market
Home Appliances
South Korea Major Home Appliances Market
Home Appliances
Italy Home Appliances Market
Home Appliances
Asia-Pacific Home Appliances Market
Home Appliances
Household Electric Steamer Cooker Market
Home Appliances
Mexico Small Home Appliances Market
Home Appliances
Russia Home Appliances Market
Home Appliances
Europe Laundry Appliances Market