
 Smart Clothing Market | 2026-2036
Smart Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Clothing Market Intelligence
A capital-intensity divergence between sensor-integrated apparel makers and conventional athletic brands is bifurcating competitive dynamics. Nike sustains R&D intensity through its proprietary performance labs and athlete-testing protocols. Google dominates embedded electronics architecture, leveraging its software-hardware integration capabilities for fabric-integrated computing. Under Armour anchors North American distribution through controlled specialty retail partnerships and direct-to-consumer digital infrastructure.
Smart clothing encompasses textile-based garments engineered with conductive fibers, microelectronic sensors, and wireless communication modules to capture biometric or environmental data. These garments typically integrate silver-coated nylon circuits, stretchable printed electrodes, and low-power Bluetooth transceivers operating below 10 mW for continuous physiological monitoring. Fitness Trackers and Smart Shirts currently occupy the largest installed base, while Sleep Monitors represent the fastest-growing product category as consumers prioritize recovery analytics. Wearable Sensors technology leads in patent filings and component margin capture, whereas Bluetooth Connectivity standardizes interoperability across the ecosystem.
FDA clearance pathways for software-as-medical-device functions shape product development timelines for health-oriented smart garments in the United States. The EU AI Act and GDPR impose algorithmic transparency and biometric data consent requirements that elevate compliance costs for European market entry. Stakeholders must monitor evolving cybersecurity certification standards and decide whether to pursue medical-grade regulatory status or remain in consumer wellness positioning.
Market Dynamics
The convergence of FDA software-as-medical-device pathways with EU AI Act algorithmic transparency mandates is forcing dual-track compliance architectures for health-oriented smart garments, bifurcating product development timelines and capital allocation strategies across the ecosystem.
Growth Catalysts
- Remote Patient Monitoring:Healthcare Providers in the United States are deploying conductive-fiber garments for post-surgical recovery tracking, with reimbursement codes from CMS accelerating clinical adoption.
- EU AI Act:The European Union's algorithmic transparency requirements for biometric wearables are creating first-mover advantages for vendors with pre-certified governance frameworks, concentrating procurement toward compliant suppliers.
- Silver-Coated Nylon Circuits:Advances in stretchable printed electrode manufacturing are reducing per-unit sensor costs, enabling mass-market penetration in athletic recovery applications.
Market Restraints
- Input Cost Volatility:Silver and rare-earth element prices for conductive fiber production fluctuate with commodity cycles, compressing component margins for textile-integrated electronics.
- Supply Concentration:Stretchable battery and microtransceiver fabrication concentrates in East Asian contract manufacturers, exposing brands to single-source disruption risks.
- GDPR Biometric Consent:The European Union's data governance framework imposes granular user-consent architectures that extend sales cycles and elevate legal infrastructure costs for market entry.
Strategic Opportunities
- Underpenetrated Clinical Sleep Monitoring:Polysomnography labs in Germany and France are piloting smart pajama systems for home-based apnea diagnosis, bypassing facility capacity constraints.
- CSRD Reporting Integration:The European Union's Corporate Sustainability Reporting Directive is mandating workforce health metrics, creating enterprise procurement pull for biometric workwear in logistics and manufacturing.
- Bluetooth-5.3 and Ultra-Wideband Convergence:Low-power wireless protocols are enabling spatial-aware garments for fall detection and industrial safety, opening construction and mining end-uses previously inaccessible to wearables.
Industry Challenges
- Embedded Systems Talent Scarcity:Textile engineering programs lack firmware development curricula, forcing brands to compete with consumer electronics firms for scarce software-hardware integration specialists.
- FDA 510(k) Timeline Compression:Software-as-medical-device clearances for arrhythmia detection algorithms require clinical validation studies that extend product launches by 18-24 months versus wellness-positioned alternatives.
- Interoperability Standardization Delays:Competing proprietary data formats between Apple HealthKit, Google Fit, and hospital EHR systems force redundant integration engineering for multi-platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Clothing Market |
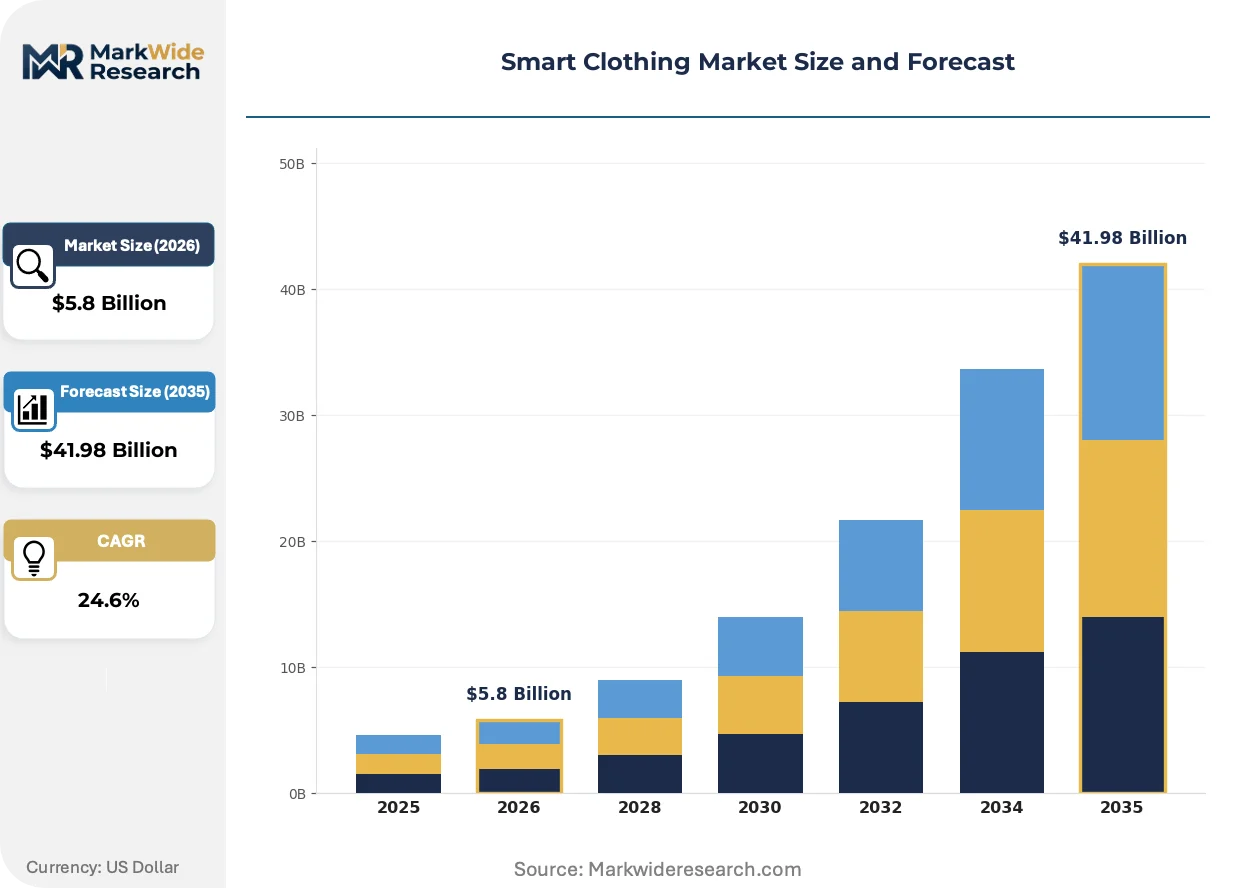
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fitness Trackers, Smart Shirts, Smart Shoes, Sleep Monitors Technology: Wearable Sensors, Bluetooth Connectivity, NFC, RFID End User: Fitness Enthusiasts, Athletes, Healthcare Providers, Retail Consumers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, E-commerce |
| Companies Covered | Stella McCartney, Nike, Under Armour, Outdoor Voices, Turms, Levi Strauss & Co., Adidas, Everlane, Google, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Clothing Market Strategic Shifts & Innovations
Wearable sensor architectures are diverging from centralized hub-and-spoke models toward distributed computing fabrics, with processing power migrating directly into textile substrates and reshaping competitive differentiation around power efficiency rather than smartphone tethering.
Printed electronics using graphene-based conductive inks is fragmenting the incumbent silver-nylon supply base. Athletic brands are piloting these materials in compression sleeves for muscle-activation mapping, with wash-cycle durability tests from Germany's Hohenstein Institute validating 50+ industrial laundering cycles. This materials shift is fragmenting component supplier hierarchies and enabling regional manufacturing footprints previously uneconomical at small batch scales.
The EU AI Act's risk-classification framework for biometric inference algorithms is tightening documentation requirements for emotion-recognition and stress-detection features in smart garments. Vendors must now maintain technical files demonstrating algorithmic transparency, with notified body involvement required for health-claim positioning. Sleep monitoring applications face the steepest compliance gradient, with several products repositioning from "sleep quality scoring" to "movement tracking" to avoid high-risk system classification.
Hospital procurement departments are unbundling device acquisition from data-analytics subscriptions, with GPOs in the United States negotiating separately for garment hardware, cloud storage, and algorithmic interpretation services. This disaggregation is compressing vendor margins on initial hardware sales while elevating recurring revenue visibility for platform-integrated suppliers, with the Veterans Health Administration's recent RFP structure exemplifying the model's spread through federal healthcare channels.
Smart Clothing Market Segmentation
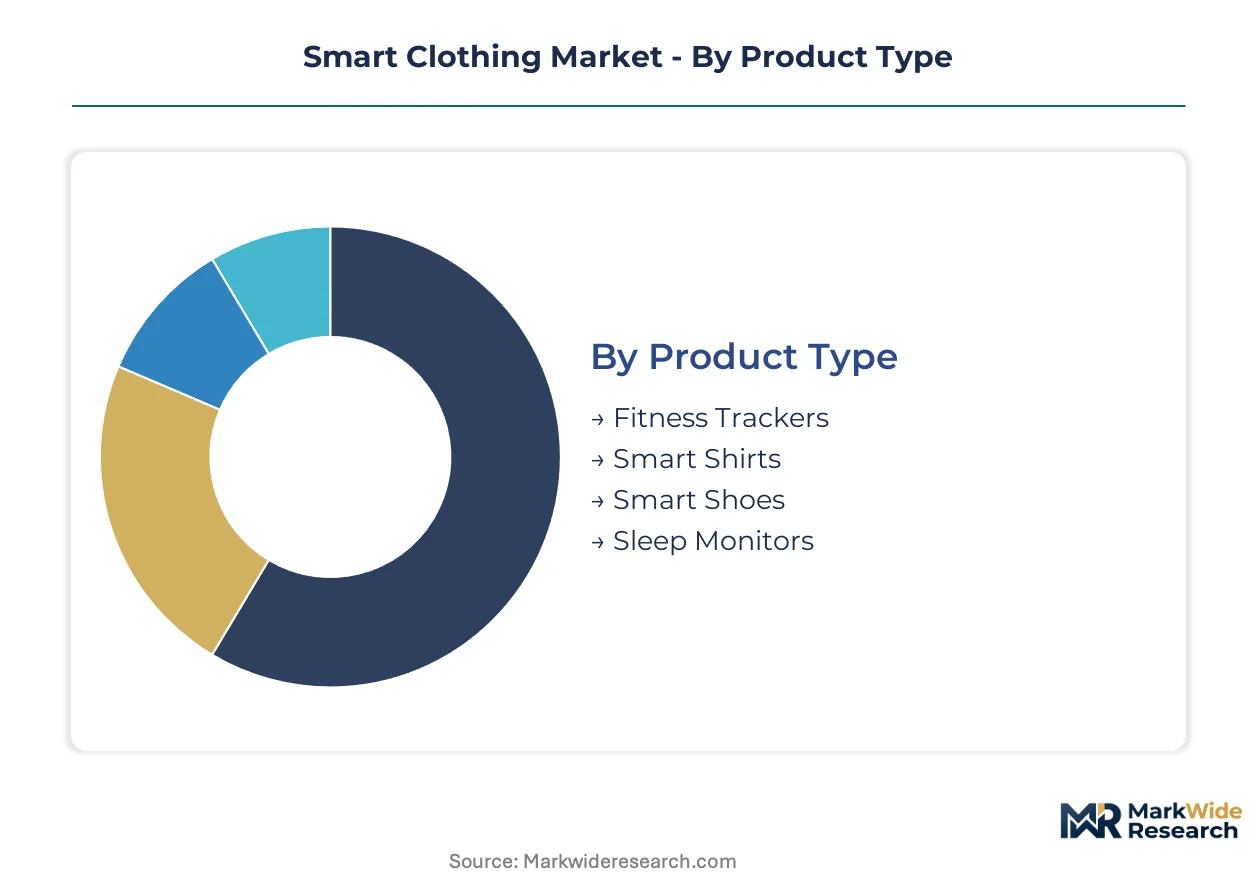
Smart clothing segmentation reveals divergent margin profiles across hardware-integrated versus software-enabled product architectures. Technology choices and distribution pathways determine whether vendors capture value through component sales, recurring data subscriptions, or platform licensing fees.
Product Type:
Substitution pressure from wrist-worn wearables and smartphone health apps forces differentiation around fabric-integrated form factors that smartphone tethering cannot replicate.
- Fitness Trackers:Textile-integrated heart rate and motion sensors embedded in compression sleeves or chest straps deliver continuous monitoring without device removal. Demand concentrates among CrossFit affiliates and boutique studio chains in the United States where coach-led biometric feedback justifies premium garment pricing over disposable wristbands.
- Smart Shirts:Silver-coated nylon circuit arrays capture multi-lead ECG signals and respiratory rate through stretchable printed electrodes. Healthcare Providers in Boston's medtech corridor deploy these for post-cardiac rehabilitation monitoring, with CMS reimbursement codes validating clinical utility over consumer wellness alternatives.
- Smart Shoes:Pressure-mapping insoles with embedded piezoelectric sensors track gait mechanics and ground contact time. Professional running coaches in Kenya's high-altitude training camps pilot these for injury prevention protocols.
- Sleep Monitors:Conductive-fiber pajama systems detect sleep stages through thoracic impedance and accelerometry. German polysomnography labs validate home-based apnea screening accuracy against facility-based diagnostics.
Fitness Trackers anchor the volume base while Sleep Monitors gain share at the steepest rate.
Technology:
Component cost tiers stratify sharply between proprietary sensor architectures and commoditized wireless protocols.
- Wearable Sensors:Stretchable printed electrodes and textile-integrated accelerometers capture biometric signals with sub-milliwatt power budgets. Patent filings concentrate in the United States and Germany, with Hohenstein Institute wash-cycle certifications becoming a de facto quality gate for European hospital procurement.
- Bluetooth Connectivity:Low-energy transceivers operating below 10 mW standardize interoperability across smartphone ecosystems and hospital EHR systems. FCC certification requirements in the United States and CE marking under the EU Radio Equipment Directive impose modular testing costs that favor scaled suppliers.
- NFC:Near-field communication chips enable tap-to-authenticate garment pairing and secure health data handoffs. Retail Consumers in Japan's convenience-oriented culture adopt these for frictionless gym locker and transit integration.
- RFID:Passive radio-frequency tags embedded in care labels enable supply chain traceability and anti-counterfeiting. Athletic brands deploy these for inventory authentication in Southeast Asian contract manufacturing.
Wearable Sensors command the highest component margins while Bluetooth Connectivity delivers the broadest addressable market.
End User:
Customer lifetime value spreads across four orders of magnitude from impulse retail purchases to multi-year hospital service contracts.
- Fitness Enthusiasts:Amateur athletes purchasing through direct-to-consumer channels drive unit volume but exhibit high churn and price sensitivity. Strava and TrainingPeaks integration becomes a switching cost anchor.
- Athletes:Professional and collegiate programs demand calibrated accuracy for load management and return-to-play protocols. NCAA compliance offices in the United States mandate independent validation of performance claims.
- Healthcare Providers:Hospital systems and accountable care organizations procure through group purchasing organizations with unbundled hardware, cloud, and analytics contracts. The Veterans Health Administration's federal procurement structure exemplifies multi-year subscription economics.
- Retail Consumers:Mass-market buyers respond to wellness positioning and fashion aesthetics over clinical accuracy. EU AI Act algorithmic transparency requirements complicate emotion-recognition feature marketing in European markets.
Healthcare Providers deliver the highest revenue per account while Retail Consumers expand the installed base most rapidly.
Distribution Channel:
Channel selection determines regulatory exposure and margin retention simultaneously.
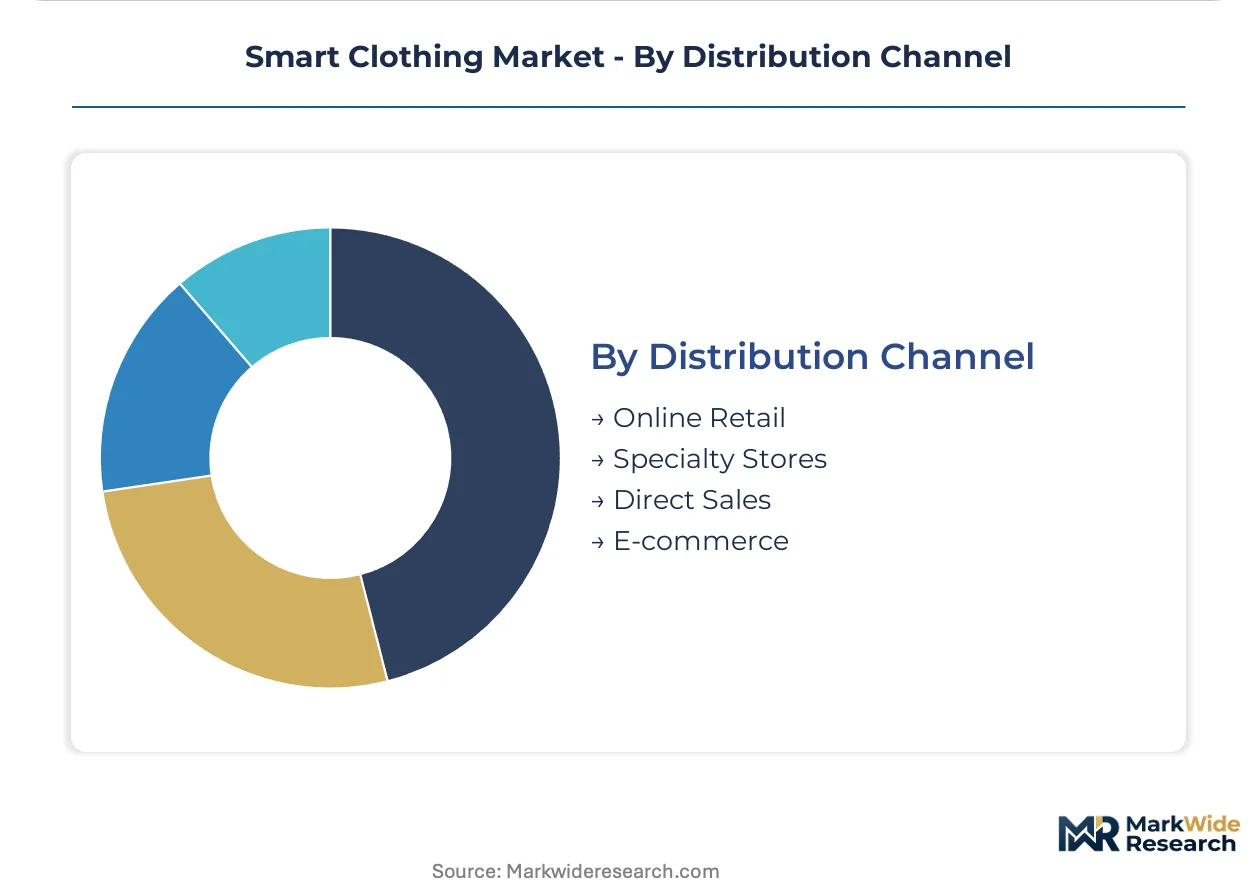
- Online Retail:Amazon and brand-direct storefronts capture consumer wellness positioning without clinical claim scrutiny. Return rates exceed 25% for sizing-dependent garments.
- Specialty Stores:Running and cycling boutiques provide fit expertise and community credibility. Boston's Marathon Sports and San Francisco's Sports Basement anchor regional brand loyalty.
- Direct Sales:Enterprise and healthcare contracts bypass retail markups through dedicated account management. FDA 510(k) consultation services bundled with hardware differentiate from consumer channels.
- E-commerce:D2C platforms with virtual try-on and subscription replenishment models reduce customer acquisition costs. GDPR-compliant consent architectures elevate European infrastructure requirements.
Specialty Stores sustain premium positioning while Direct Sales captures the enterprise health contract value pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's clinical procurement corridors while cost-sensitive athletic applications dominate volume flows through Vietnam's contract manufacturing basins. This asymmetry shapes capital allocation across the value chain.
United States
FDA 510(k) clearances for software-as-medical-device functions accelerate post-surgical recovery deployments through CMS reimbursement codes. The Veterans Health Administration's unbundled procurement structure separates garment hardware from analytics subscriptions. Boston's medtech cluster anchors cardiac rehabilitation monitoring programs with silver-coated nylon circuit validation.
Germany
Hohenstein Institute wash-cycle certifications gate European hospital procurement for stretchable printed electrodes. The EU AI Act's algorithmic transparency mandates elevate documentation burdens for emotion-recognition features in biometric workwear. Polysomnography labs in Munich and Hamburg pilot conductive-fiber pajama systems for home-based apnea diagnosis.
China
MIIT standards for low-power Bluetooth transceivers harmonize with FCC modular certification requirements for export-oriented manufacturers. NMPA pathway alignment with FDA breakthrough device designations accelerates dual-market submissions for arrhythmia detection garments. Shenzhen's hardware ecosystem concentrates stretchable battery fabrication for mass-market athletic recovery applications.
Japan
METI funding for textile-integrated computing supports printed electronics pilots using graphene-based conductive inks. JIS standards for wearable sensor durability create quality gates that favor established component suppliers over new entrants. Tokyo's fashion-technology crossover studios prototype NFC-enabled garments for frictionless transit and gym locker integration.
France
ANSM oversight of clinical-grade sleep monitoring devices tightens validation requirements for thoracic impedance algorithms. CNIL guidance on biometric consent architectures extends sales cycles for emotion-recognition marketing claims. Paris-based luxury houses experiment with RFID-embedded care labels for supply chain traceability and anti-counterfeiting in Southeast Asian contract manufacturing.
Smart Clothing Market Key Industry Players
Concentration sits with athletic-apparel incumbents who control distribution infrastructure and athlete-testing protocols. The vendor base stratifies across three tiers: multinational sportswear conglomerates with proprietary performance labs, technology platform owners commanding software-hardware integration, and specialized textile-electronics hybrids focused on clinical validation. M&A activity targets sensor-integrated apparel makers with FDA clearance pathways, while strategic partnerships concentrate around Bluetooth-5.3 and Ultra-Wideband protocol convergence for industrial safety applications.
Within the athletic-apparel tier, Nike and Under Armour occupy positions defined by controlled specialty retail partnerships and direct-to-consumer digital infrastructure. Adidas anchors European procurement through CE-marked garment validation. Among technology platform owners, Google exemplifies embedded electronics architecture leveraging software-hardware integration for fabric-integrated computing. Levi Strauss & Co. represents denim-sector incumbents piloting conductive-fiber integration for mass-market accessibility. Stella McCartney occupies the sustainable-luxury intersection where CSRD-aligned workforce health metrics create enterprise procurement pull.
| Leading Market Players |
|---|
| Stella McCartney |
| Nike |
| Under Armour |
| Outdoor Voices |
| Turms |
| Levi Strauss & Co. |
| Adidas |
| Everlane |
| Others |
Cost & Logistics Intelligence
Graphene-based conductive inks displacing silver-coated nylon circuits are redrawing manufacturing geographies and compressing component economics simultaneously. This materials transition enables regional production footprints previously uneconomical at small batch scales while fragmenting incumbent supplier hierarchies.
Pricing Analysis
Customization-premium spreads separate FDA-cleared clinical garments from wellness-positioned consumer alternatives. Pricing stratifies across medical-grade certification, standard athletic recovery, and economy mass-market tiers, with FDA 510(k) validation commanding substantial premia over uncertified equivalents. Cost compression in the standard tier intensifies as graphene ink suppliers compete with established silver-nylon vendors. Healthcare Providers exhibit the lowest price sensitivity due to CMS reimbursement coverage, while Fitness Enthusiants drive volume through promotional discounting.
Supply Chain Analysis
Just-in-time inventory strategies dominate consumer-facing athletic brands, whereas clinical procurement favors strategic stockpiles of FDA-validated components. Stretchable battery and microtransceiver fabrication concentrates in China, South Korea, and Taiwan, drawing from rare-earth element deposits and specialized polymer substrates. Single-source vulnerability in East Asian contract manufacturing exposes brands to geopolitical disruption risks. Distribution runs through controlled specialty retail partnerships for premium positioning and direct-to-consumer digital infrastructure for volume penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in clinical sleep monitoring and industrial safety applications, as unmet demand for home-based diagnostics and spatial-aware fall detection creates defendable niches outside athletic-apparel incumbent strongholds.
For Market Incumbents: Fortify regulatory moats by accelerating FDA 510(k) submissions for arrhythmia detection algorithms before EU AI Act transparency mandates harden compliance barriers. Deepen backward integration into stretchable printed electrode manufacturing to offset silver price volatility and capture component margins currently leaking to East Asian suppliers. Control distribution through exclusive specialty retail partnerships that gate competitor access to calibrated athlete-testing protocols. For New Entrants and Emerging Players: Differentiate on algorithmic transparency documentation to exploit EU AI Act first-mover advantages in biometric workwear procurement. Target German polysomnography labs and French hospital systems with conductive-fiber pajama systems for home-based apnea diagnosis, bypassing facility capacity constraints that incumbent athletic brands ignore. Pursue direct sales contracts with unbundled hardware-analytics structures that mirror Veterans Health Administration procurement models. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed textile-electronics hybrids possessing Hohenstein Institute wash-cycle certifications and pre-built FDA regulatory files. Long-term viability hinges on platform-integrated recurring revenue visibility rather than transactional hardware margins. Watch CMS reimbursement code expansion for post-surgical recovery garments as the inflection signal validating clinical adoption economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Software-as-medical-device clearances compress competitive entry timelines for arrhythmia detection garments. |
| EU AI Act Pre-Certification | Algorithmic transparency documentation creates procurement advantages with German hospital systems and French CNIL oversight. |
| Backward Integration into Electrode Manufacturing | In-house production of graphene-based conductive inks reduces silver price exposure and enables regional manufacturing. |
| Bluetooth-5.3 and Ultra-Wideband Convergence | Spatial-aware garment protocols open construction and mining safety applications previously inaccessible to wearables. |
| CSRD-Aligned Workforce Health Metrics | Enterprise procurement pull from EU Corporate Sustainability Reporting Directive mandates creates logistics and manufacturing demand. |
Research Approach
The analysis maps wearable sensor architectures, Bluetooth connectivity modules, and conductive-fiber garment categories, each validated through textile engineers, hospital procurement managers, GPO contracts specialists, and regulatory affairs leads. Primary interviews with firmware developers at athletic brands and biomedical engineers at Boston's medtech cluster combined with secondary validation against FDA 510(k) filings, CE marking databases, Hohenstein Institute certification records, and CMS reimbursement code updates. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Consistency checks validated volume and value outputs against hospital procurement database trends, GPO contract unbundling patterns, and stretchable electronics patent filing trajectories. Segmentation modeling incorporated product type, technology tier, end-user archetype, and distribution channel dimensions. CAGRs derived from installed base growth curves and replacement cycle assumptions, with specific inputs including silver commodity price volatility bands and EU AI Act implementation phase transitions.
Material uncertainties — FDA software-as-medical-device pathway delays, EU AI Act risk-classification revisions, and rare-earth supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement code stability and algorithmic transparency documentation burdens. Revision becomes warranted when CMS coverage determinations for remote patient monitoring garments cross threshold expansion levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Apparel Textiles
TIC for Apparel Market
Apparel Textiles
China Denim Jeans Market
Apparel Textiles
Apparel Supply Chain Market
Apparel Textiles
Head Scarves Market
Apparel Textiles
Down Jacket Market
Apparel Textiles
North America Footwear Sole Material Market
Apparel Textiles
Cosplay Clothing Market
Apparel Textiles
Sweat Resistant Apparel Market
Apparel Textiles
Dye Sublimated Apparel Market
Apparel Textiles
Stockings Market
Apparel Textiles
Cleanroom Apparels Market
Apparel Textiles
Smart Apparel Market
Apparel Textiles
Asia Pacific Garment Steamers Market
Apparel Textiles
Japan Denim Jeans Market
Apparel Textiles
School Uniform Market
Apparel Textiles
Organic Baby Clothes Market