
 North America Fire Pits Market | 2026-2036
North America Fire Pits Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fire Pits Market Analytics
Asset-light leasing and subscription-based outdoor furnishing models is narrowing the competitive field to players with flexible capital structures. Solo Stove leverages direct-to-consumer channels to sustain premium positioning without wholesale markup dependency. Breeo Industries LLC anchors its presence through American-made steel fabrication and smokeless combustion patents. The Outdoor GreatRoom Company LLC competes on integrated outdoor kitchen ecosystems that extend beyond standalone fire features.
North America fire pits are self-contained combustion or electric heating vessels designed for outdoor recreational use, typically constructed with steel walls exceeding three millimeters thickness to withstand thermal cycling and weather exposure, and engineered to contain open flames or radiant heat output measured in British thermal units per hour. Propane and natural gas variants command margin pools through convenience and regulatory compliance in municipalities with burn restrictions, while wood-burning units retain dominance in rural markets where fuel access and traditional aesthetics persist. Steel and cast iron materials lead fabrication due to cost efficiency and thermal mass properties, though stone-clad premium offerings occupy the luxury residential and hospitality segments.
EPA Phase II certification requirements for wood-burning appliances shape product development timelines and manufacturing compliance costs across the United States, while CSA Group standards and UL listings govern gas-fired unit safety in Canadian and American jurisdictions respectively. State-level burn ban ordinances in California, Colorado, and Texas create fragmented market access conditions that favor multi-fuel product portfolios. Stakeholders must monitor evolving municipal fire codes and air quality districts to anticipate where gas infrastructure expansion or electrification incentives will redirect replacement demand.
Market Dynamics
EPA Phase II emissions standards for wood-burning appliances are compressing product development cycles and forcing manufacturers toward dual-fuel engineering investments. The regulatory pressure is accelerating consolidation among fabrication specialists who lack capital for certification compliance.
Growth Catalysts
- Residential Outdoor Living Expansion:Homeowners in Texas, Arizona, and California are extending functional living space into backyards, creating sustained replacement demand for weather-resistant combustion vessels.
- EPA Phase II Certification:Federal emissions standards for wood-burning appliances are pulling investment toward cleaner combustion R&D and premium product tiers that command margin pools.
- Propane Infrastructure Density:Municipal gas line extensions across Colorado and Utah suburbs are converting wood-burning households to convenient gas-fired units with instant ignition.
Market Restraints
- Steel Input Volatility:Cold-rolled steel price swings above three-millimeter gauge thickness directly compress fabrication margins for steel-walled vessel producers.
- Seasonal Demand Concentration:Fourth-quarter sales spikes in northern climates force working capital intensity and inventory risk on distributors with limited warehousing.
- Substitution by Electric Patio Heaters:Zero-emission radiant alternatives are capturing balcony and small-space applications where burn bans restrict open flame.
Strategic Opportunities
- Underpenetrated Canadian Prairies:Saskatchewan and Manitoba exhibit low fire pit penetration relative to comparable US climates, presenting first-mover expansion potential.
- Integrated Outdoor Kitchen Ecosystems:Fire features bundled with cooking surfaces and refrigeration are capturing premium residential spend in California and Florida.
- CSA Group Certification Arbitrage:Dual UL and CSA listings unlock cross-border distribution efficiency for manufacturers serving both US and Canadian markets.
Industry Challenges
- Welding Specialist Scarcity:Certified steel fabricators capable of thermal-cycling-resistant seam work command premium wages and extend production lead times.
- Multi-Jurisdictional Compliance Timelines:State-level burn ban ordinances in California, Colorado, and Texas create fragmented testing requirements that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fire Pits Market |
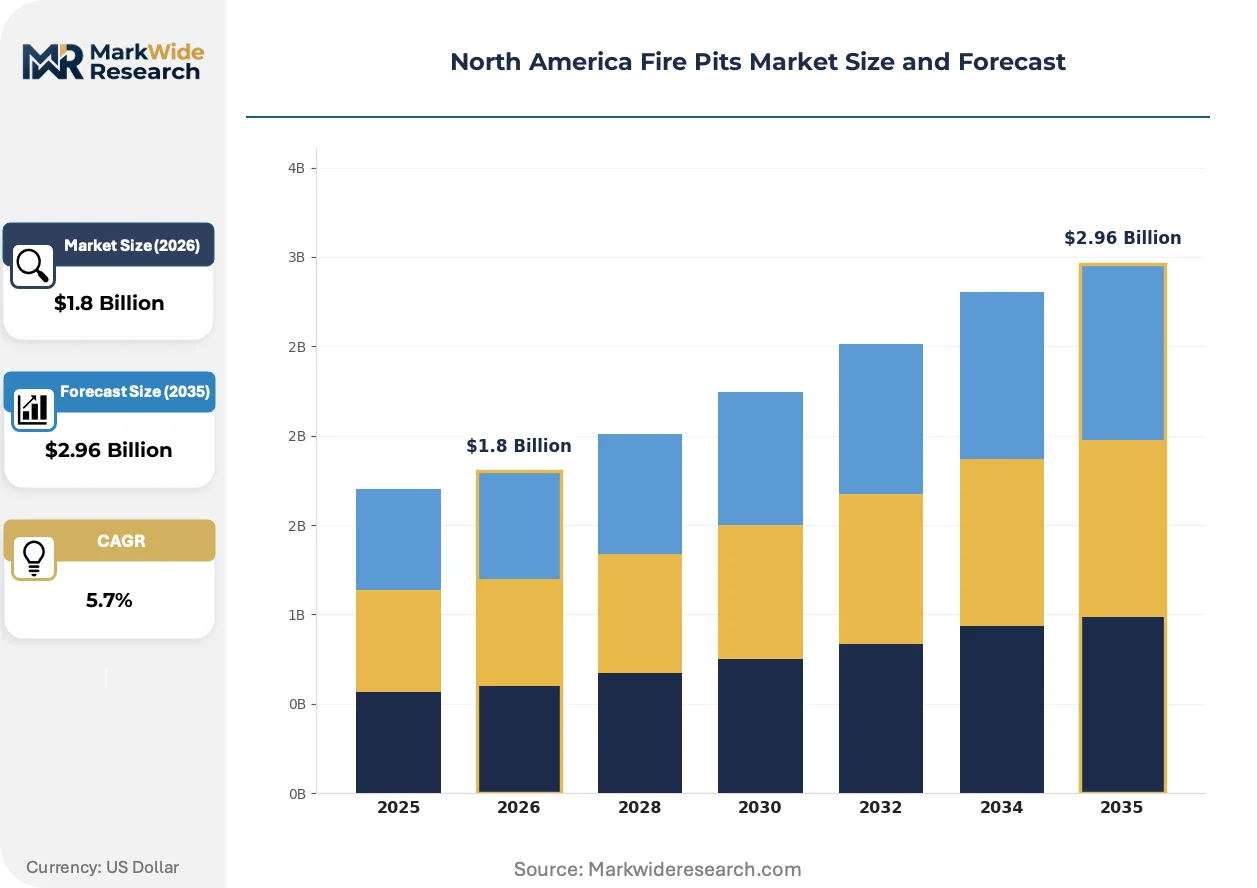
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Burning, Propane, Natural Gas, Electric Material: Steel, Aluminum, Stone, Cast Iron Size: Small, Medium, Large, Extra Large End User: Residential, Commercial, Hospitality, Events |
| Companies Covered | The Outdoor GreatRoom Company LLC, Fire Pit Art, Breeo Industries LLC, Solo Stove, Tropitone Furniture Co., Inc., The Blue Rooster Company, Prism Hardscapes, Ohio Flame, Inc., Camp Chef, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fire Pits Market Evolving Landscape
Clean combustion engineering and modular outdoor living systems are converging to redefine product architecture. Manufacturers are racing to embed connectivity and multi-fuel flexibility before regulatory windows narrow.
Smokeless secondary combustion technology is hybridizing traditional wood-burning aesthetics with gas-fired convenience. Residential buyers in burn-restricted municipalities are adopting these dual-chamber steel vessels at accelerated rates. The technology is hybridizing market segmentation by collapsing the distinction between rural wood-burning purists and suburban gas-convenience seekers.
EPA Phase II certification requirements are extending product development timelines by eight to fourteen months for wood-burning submissions. Testing laboratory bottlenecks in the United States are creating queue backlogs that favor capitalized incumbents with dedicated compliance teams. Rural and semi-rural product lines face the steepest cost absorption challenges as certification fees amortize across lower unit volumes.
Direct-to-consumer channel expansion is compressing wholesale distributor relevance in premium segments. Solo Stove's digital-native model is forcing traditional retailers to unbundle installation services or match price transparency. The shift is most visible in southwestern US markets where year-round outdoor entertaining sustains higher online purchase frequency and lower return rates.
North America Fire Pits Market Segmentation
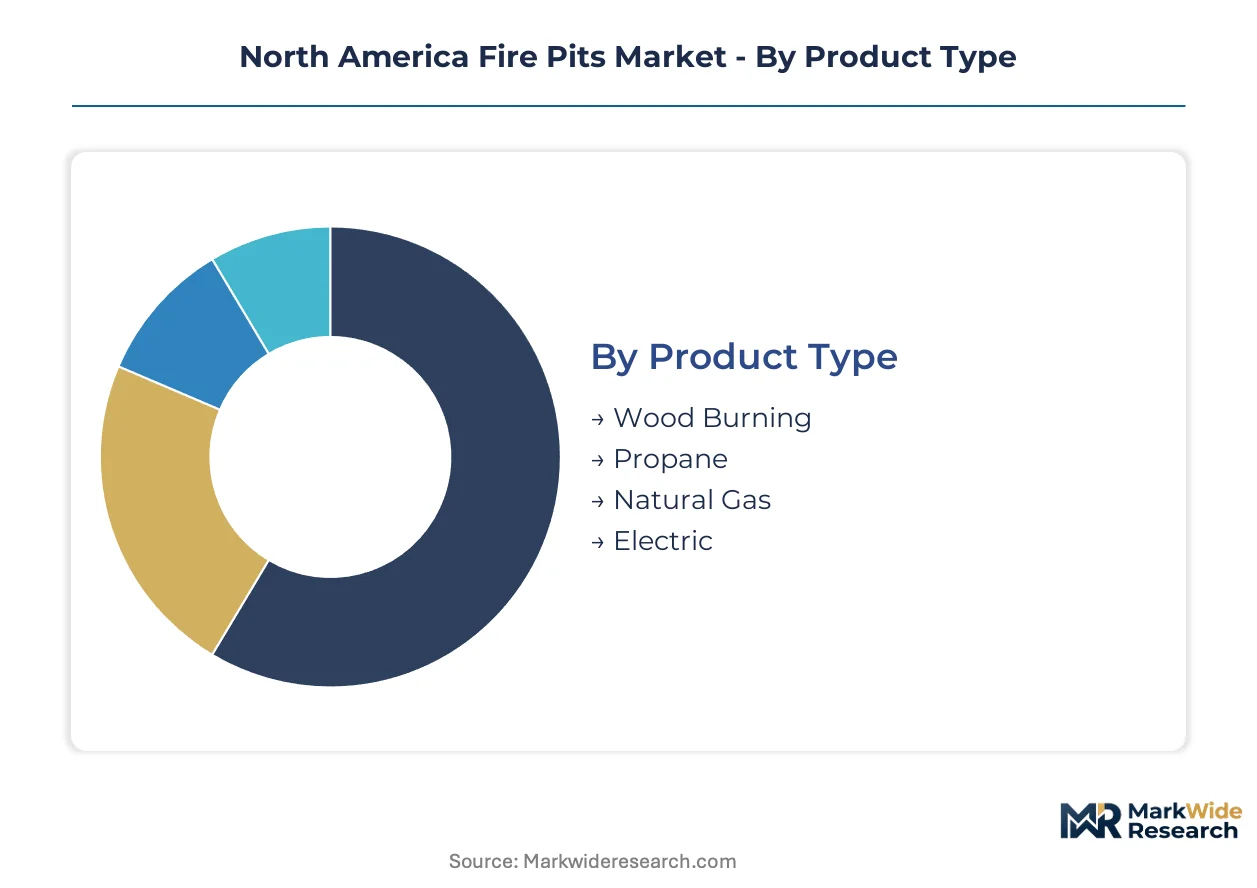
Fire pit segmentation reveals how fuel flexibility, material durability, and installation scale intersect with regulatory boundaries and seasonal usage patterns. Buyers sort across combustion types based on municipal burn codes, while material selection tracks climate exposure and aesthetic positioning.
Product Type:
Fuel source determines regulatory exposure, operating cost structure, and installation complexity across the United States and Canada.
- Wood Burning:Traditional open-flame vessels with EPA Phase II certification requirements for particulate emissions below 2.5 grams per hour. Rural Texas and Colorado counties sustain replacement demand where fuel access is abundant and burn bans are intermittent.
- Propane:Portable tank-fed systems with instant ignition and no ash disposal requirements. Arizona and California suburbs favor these units where municipal gas infrastructure is sparse but cylinder exchange networks are dense.
- Natural Gas:Hard-plumbed installations requiring permanent gas line connections. Utah and Colorado new construction markets absorb these units as builders spec permanent outdoor kitchen infrastructure.
- Electric:Zero-emission radiant heat elements with no combustion byproducts. Balcony installations in Vancouver, Toronto, and dense California metros adopt these where open flames are prohibited.
Propane holds installed capacity. Electric is rotating up the share rankings.
Material:
Fabrication substrate governs thermal cycling resistance, shipping economics, and price-tier positioning.
- Steel:Cold-rolled carbon steel exceeding three-millimeter gauge thickness dominates volume production. Southwestern US residential buyers prioritize weather-resistant powder-coated finishes for year-round exposure.
- Cast Iron:Dense thermal mass retains heat for extended burn periods. Michigan and Wisconsin lake house markets absorb these heavier units where stationary installation is standard.
- Aluminum:Lightweight corrosion-resistant alloy enables portable designs. Coastal California and Florida beach communities favor these for salt-air resistance and mobility.
- Stone:Masonry-clad premium vessels with integrated seating or cooking surfaces. Luxury residential and hospitality segments in Napa Valley and Scottsdale specify these for architectural integration.
Steel commands volume leadership. Stone is climbing the fastest among premium tiers.
Size:
Physical footprint determines heat output capacity, fuel consumption rate, and placement flexibility.
- Small:Compact vessels under 24 inches diameter for balconies and intimate patios. Urban Canadian markets in Montreal and Toronto absorb these for space-constrained outdoor areas.
- Medium:Standard 24-36 inch diameter range for typical suburban backyards. Texas and Arizona residential replacement cycles concentrate here.
- Large:36-48 inch diameter with elevated British thermal unit output for entertaining clusters. California outdoor kitchen integrations specify these for cooking surface compatibility.
- Extra Large:Custom installations exceeding 48 inches for hospitality and event venues. Colorado ski resorts and Texas ranch properties deploy these for group gathering capacity.
Medium holds installed capacity. Large is gaining share fastest in integrated outdoor living projects.
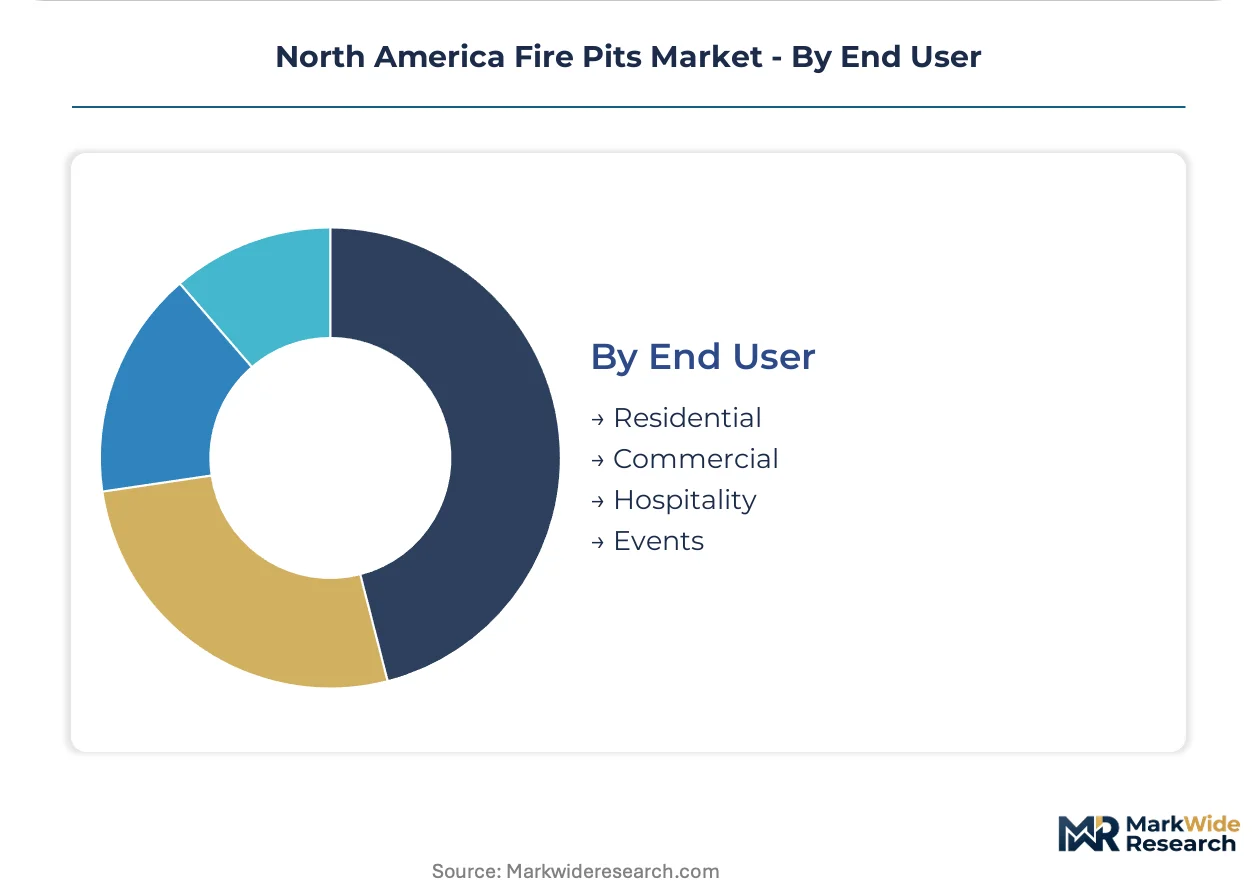
End User:
Customer type dictates purchase frequency, service requirements, and specification complexity.
- Residential:Individual homeowners purchasing through retail or direct-to-consumer channels. Southwestern US markets sustain the highest replacement frequency due to year-round usage.
- Commercial:Restaurants, bars, and retail establishments with high-duty-cycle requirements. California and Florida hospitality corridors specify CSA Group and UL-listed units for liability coverage.
- Hospitality:Hotels and resorts with brand-standard outdoor amenity programs. Arizona desert properties and Colorado mountain lodges prioritize smokeless combustion for guest experience consistency.
- Events:Rental and temporary installation operators serving weddings and corporate gatherings. Texas and California event markets favor propane portability for rapid deployment.
Residential holds installed capacity. Hospitality is expanding most quickly in resort development pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in southwestern United States markets where year-round outdoor entertaining sustains replacement cycles, while Canadian prairie provinces operate at lower price tiers due to compressed seasonal usage windows and thinner distribution infrastructure.
Southwestern United States
Texas and Arizona residential markets absorb the highest replacement frequency for steel-walled combustion vessels due to extended outdoor living seasons. EPA Phase II certification requirements pull investment toward cleaner combustion R&D in Phoenix and Dallas-Fort Worth fabrication clusters. Scottsdale and Austin luxury residential developments specify stone-clad premium vessels for architectural integration with outdoor kitchen ecosystems.
California
State-level burn ban ordinances in coastal metros create fragmented market access favoring multi-fuel product portfolios with gas-fired convenience. California Air Resources Board emissions protocols exceed federal standards and accelerate dual-fuel engineering investments. Napa Valley hospitality properties and Los Angeles hillside residences anchor demand for CSA Group and UL-listed integrated outdoor living systems.
Colorado
Mountain lodge hospitality corridors and Denver suburban new construction absorb hard-plumbed natural gas installations as builders spec permanent outdoor kitchen infrastructure. Municipal gas line extensions across Colorado Springs and Fort Collins suburbs convert wood-burning households to instant-ignition units. Ski resort properties in Aspen and Vail prioritize smokeless combustion patents for guest experience consistency.
Florida
Coastal corrosion resistance requirements favor aluminum alloy portable designs in beach communities from Miami to Tampa. Florida building codes for wind-load resistance shape vessel anchoring specifications in hurricane-prone counties. Orlando hospitality development pipelines and Naples luxury residential clusters specify integrated fire features bundled with cooking surfaces and refrigeration.
Canada
Saskatchewan and Manitoba exhibit low fire pit penetration relative to comparable US climates, presenting first-mover expansion potential for CSA Group-certified fabricators. Health Canada and CSA Group standards govern gas-fired unit safety and create certification arbitrage opportunities for dual-listed manufacturers. Toronto and Montreal urban markets absorb compact electric radiant units for balcony installations where open flames are prohibited.
North America Fire Pits Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with fabrication expertise. The vendor base stratifies between direct-to-consumer digital natives, American-made steel fabricators, and integrated outdoor kitchen ecosystem providers. Three archetypes dominate: premium direct-to-consumer brands, smokeless combustion patent holders, and full outdoor living system bundlers. Competitive moves concentrate on CSA Group and UL certification arbitrage for cross-border distribution efficiency, plus dual-fuel engineering investments to navigate fragmented municipal burn codes.
Within the direct-to-consumer tier, Solo Stove exemplifies platform-native positioning without wholesale markup dependency. Among American-made fabricators, Breeo Industries LLC and Ohio Flame, Inc. occupy positions anchored in domestic steel fabrication and thermal-cycling-resistant seam work. The Outdoor GreatRoom Company LLC represents the integrated ecosystem archetype, bundling fire features with cooking surfaces and refrigeration for premium residential and hospitality specifications.
| Leading Market Players |
|---|
| The Outdoor GreatRoom Company LLC |
| Fire Pit Art |
| Breeo Industries LLC |
| Solo Stove |
| Tropitone Furniture Co., Inc. |
| The Blue Rooster Company |
| Prism Hardscapes |
| Ohio Flame, Inc. |
| Camp Chef |
| Others |
Value Network & Pricing Analysis
Intermodal freight corridors through the Ports of Los Angeles and Long Beach transmit cold-rolled steel cost volatility directly to fabrication margins, concentrating pricing power among vessel producers with captive powder-coating capacity while forcing smaller fabricators toward commodity positioning or exit.
Pricing Analysis
Commercial hospitality buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on UL/CSA certification grade and geographic delivery cost to burn-restricted municipalities. Cost compression in the economy tier is intensifying because EPA Phase II compliance fees amortize poorly across low-volume rural product lines. Residential replacement buyers in southwestern states exhibit the lowest price sensitivity, while event rental operators in Texas and California face acute margin pressure from propane cylinder exchange economics.
Supply Chain Analysis
Cold-rolled steel feedstock draws from integrated mills in the United States, Canada, and Mexico, with gauge-thickness specifications exceeding three millimeters for thermal-cycling resistance. Fabrication depends on welding-grade carbon steel, high-temperature powder coatings, and CSA-certified gas valve assemblies. Single-source vulnerability concentrates in domestic certified welder pools capable of seam work for smokeless combustion chambers. Distribution runs through direct-to-consumer platforms, specialty outdoor retailers, and hospitality-specification dealers serving integrated outdoor kitchen projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified steel fabricators capable of EPA-compliant thermal cycling work represent the scarcest operational capability, constraining expansion velocity for all but capitalized incumbents with dedicated compliance teams.
For Market Incumbents: Build regulatory certification moats through dedicated EPA Phase II testing queue positions and dual UL-CSA listing maintenance. Acquire distressed fabrication assets in Phoenix and Dallas-Fort Worth clusters to consolidate welding specialist capacity. Electric patio heater substitution in California balcony segments threatens open-flame unit replacement frequency; counter with smokeless combustion patent bundling to hospitality specifiers. For New Entrants and Emerging Players: Saskatchewan and Manitoba prairie provinces offer first-mover expansion potential with compressed competitive density and CSA Group certification arbitrage against US-only rivals. Target propane portable segments in Alberta oil-field housing and Manitoba lake communities where cylinder exchange infrastructure outpaces natural gas line extension. Pursue direct-to-consumer digital launch with subscription-based seasonal storage and maintenance services to bypass wholesale distributor margin capture. For Investors and Strategic Acquirers: Smokeless combustion patent holders with American-made steel fabrication capabilities represent the highest-conviction acquisition archetype for outdoor living platform consolidation. Long-term viability rests on regulatory compliance cost absorption capacity across fragmented municipal burn codes. Monitor EPA testing laboratory queue lengths as the inflection indicator for product launch velocity divergence between capitalized and undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engineering Investment | Smokeless secondary combustion patents collapse segmentation between rural wood-burning and suburban gas-convenience buyers. |
| CSA Group Certification Arbitrage | Dual UL-CSA listings unlock cross-border distribution efficiency for Saskatchewan and Manitoba expansion. |
| Direct-to-Consumer Channel Buildout | Solo Stove's digital-native model forces wholesale margin compression and installation service unbundling. |
| Integrated Outdoor Kitchen Ecosystem | Fire features bundled with cooking surfaces capture premium residential spend in California and Florida developments. |
| Welding Specialist Capacity Acquisition | Certified fabricators capable of thermal-cycling-resistant seam work command premium wages and extend production lead times. |
Research Methodology
Operator-level perspectives from plant managers at steel fabrication facilities, procurement leads at hospitality property developers, and aftermarket service heads at specialty outdoor retailers anchored the qualitative base. These primary insights combined with secondary validation from EPA certification databases, CSA Group listing registries, and customs records for cold-rolled steel gauge imports. Bottom-up unit economics triangulated against top-down spending estimates from residential construction permits and hospitality development pipelines.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation modeled by fuel type, material substrate, installation size tier, and end-user category. CAGRs derived from replacement cycle frequency differentials between year-round southwestern markets and seasonal northern climates, cross-referenced against municipal burn ban ordinance expansion trajectories and propane infrastructure density curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by electric radiant heating specialists or cross-category outdoor living platform integrators would shift outcomes beyond modeled ranges. Cross-checking against regional housing starts data and hospitality construction pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Camping Tent Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Swimming Pool and Spa Market