
 Fire Pits Market | 2026-2036
Fire Pits Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Pits Market Intelligence
The market for fire pits is pivoting on the axis of design innovation versus mass-market affordability. Premium segments emphasize smokeless technology and architectural materials, while commodity tiers compete on price with basic steel wood-burning units. Solo Stove leverages its patented airflow design to dominate the premium portable category. Breeo Industries specializes in heavy-gauge steel, smokeless wood-burning models, while Landmann offers a broader range of traditional designs for European retail channels.
A fire pit is a controlled outdoor fireplace designed for recreational use, constructed from non-combustible materials like steel, copper, or concrete to safely contain flames. Its primary purpose is to provide ambient heat and a visual focal point for social gatherings in residential or commercial outdoor spaces. While wood-burning models retain a large installed base, propane and natural gas fuel types are gaining significant traction for their convenience and cleaner operation. Portable pits dominate unit sales, but the built-in and fire table product types command higher average selling prices and margins.
Product safety and emissions standards set the boundaries for market participants. In North America, gas-fueled appliances must often adhere to UL or CSA standards, while in Europe, CE marking is essential for market access. These regulations, along with local fire bans and air quality rules in cities like Denver or Sydney, influence design choices. Future success depends on navigating the trade-offs between fuel convenience, material durability, and evolving consumer aesthetic preferences.
Market Dynamics
The market's trajectory is defined by the tension between advanced, smokeless combustion systems designed for regulated urban environments and the persistent demand for traditional, lower-cost wood-burning units. This dynamic forces manufacturers to navigate diverging technological paths and consumer expectations.
Growth Catalysts
- Commercial Hospitality Expansion:Hotels, restaurants, and resorts are integrating fire pits to enhance outdoor guest experiences and extend the usability of patio spaces into cooler months, driving high-margin commercial sales, particularly in North America.
- Smokeless Combustion Technology:Patented airflow designs that dramatically reduce smoke and particulate emissions are unlocking the market in dense suburban and urban areas previously constrained by air quality rules or nuisance complaints.
- Residential Outdoor Living:A sustained consumer focus on upgrading backyards and patios into sophisticated outdoor rooms acts as a primary demand driver, with fire pits serving as a central feature for socialization and ambiance.
Market Restraints
- Local Fire Bans:Municipalities in fire-prone or densely populated areas, such as Denver or various California cities, increasingly implement seasonal or total bans on solid-fuel burning, which directly curtails the addressable market for wood-burning models.
- Input Cost Volatility:Price fluctuations for raw materials, especially heavy-gauge steel and copper, create margin pressure for manufacturers of premium, durable units and introduce uncertainty into retail pricing structures.
- Substitution from Electric Heaters:For consumers prioritizing convenience and zero emissions over flame aesthetics, high-output electric infrared patio heaters represent a viable and often less regulated alternative, competing for outdoor heating budgets.
Strategic Opportunities
- European Market Penetration:A significant opportunity exists to introduce advanced smokeless wood-burning and convenient propane-fueled fire pit models to European retail channels, which are currently underserved by such innovations compared to North America.
- Smart Technology Integration:Incorporating app-based controls via Wi-Fi or Bluetooth for gas-fueled models allows for features like remote ignition, flame control, and automated safety shut-offs, creating a new premium product category.
- Modular and Customizable Designs:Offering modular systems that allow consumers to customize the size, shape, material, and accessories of their fire pit can cater to the demand for personalized outdoor living spaces and command higher prices.
Industry Challenges
- Fragmented Safety Certification:Manufacturers face significant cost and time hurdles in securing separate safety certifications like UL, CSA, and CE marking to legally sell gas-fueled appliances across North American and European markets.
- Seasonal Demand Management:The business is characterized by strong seasonal sales peaks, creating complex inventory management challenges that can lead to stockouts during high season or costly overstock situations in the off-season.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Pits Market |
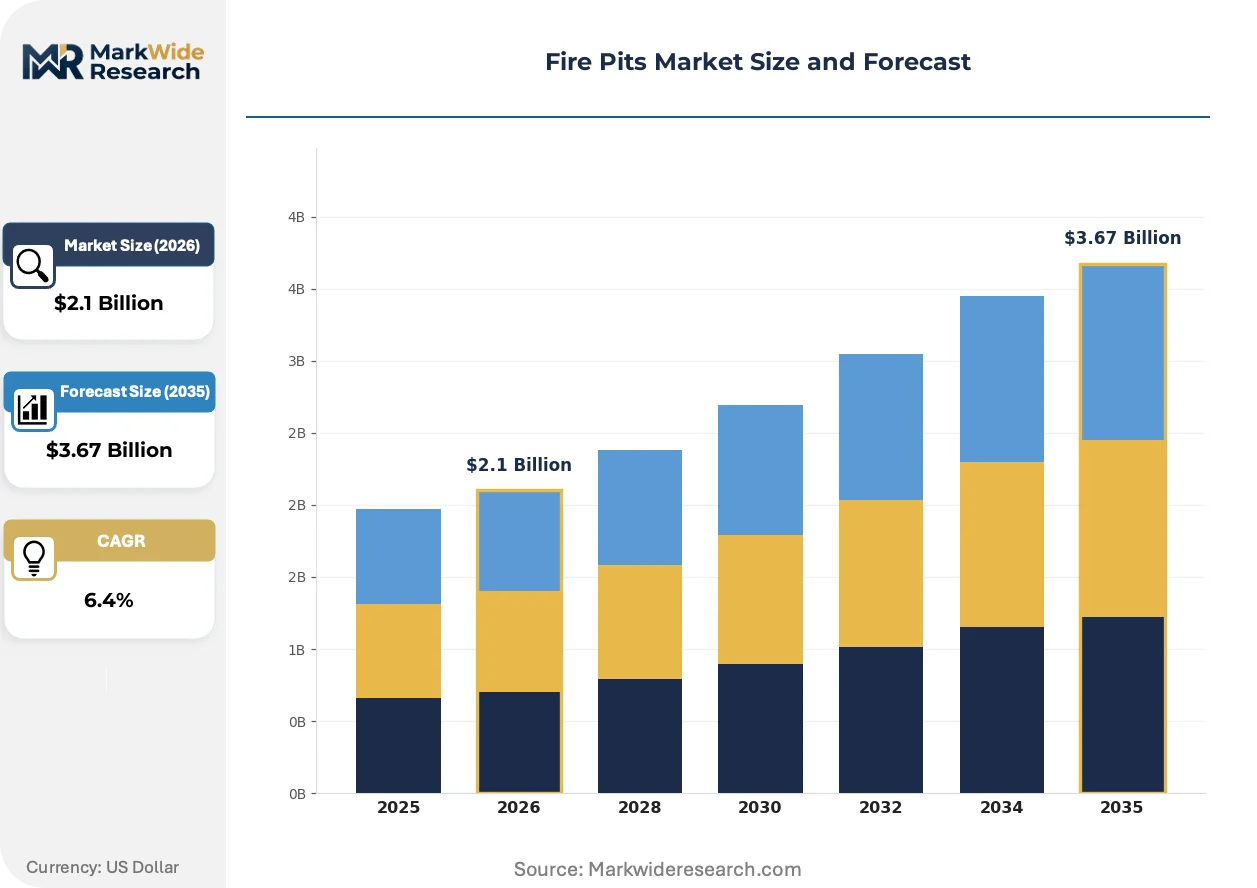
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.67 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Pits, Built-in Pits, Tabletop Pits, Fire Bowl Material: Steel, Cast Iron, Concrete, Copper Fuel Type: Wood, Propane, Natural Gas, Gel End User: Residential, Commercial, Outdoor, Hospitality |
| Companies Covered | Solo Stove, The Outdoor GreatRoom Company, Warming Trends, Landmann, Crate and Barrel, Firepits UK, Airxcel, Breeo Industries, Ohio Flame, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Pits Market Strategic Shifts & Innovations
Product development is increasingly focused on resolving the core user conflicts between authentic wood-burning ambiance and the clean, convenient operation demanded by modern lifestyles. This balance is being pursued through material science, regulatory compliance, and new user-centric designs.
Secondary combustion, using engineered airflow to re-burn smoke particles, is a key technological advance. Environmentally conscious consumers and residents in areas with air quality regulations are the primary adopters of these premium smokeless units. This technology is rewriting the rules for urban and suburban fire pit use, making wood-burning viable in locations where it was previously restricted or socially unacceptable.
Mandatory CE marking for gas appliances sold in the European Union verifies compliance with rigorous health, safety, and environmental standards. This regulation functions as a critical market access gate, often posing a barrier to non-compliant manufacturers outside the region. The gas-fueled fire table segment is most affected, compelling brands to invest significantly in third-party testing and technical documentation to target EU customers.
A discernible shift in consumer preference favors multi-functional units that integrate a fire feature with a usable tabletop surface. This movement disrupts the market for traditional, standalone fire bowls, particularly in the mid-range price bracket, as buyers seek greater utility from their investment. This demand for "fire tables" is most pronounced in residential settings across the United States, where they anchor outdoor entertaining spaces.
Fire Pits Market Segmentation
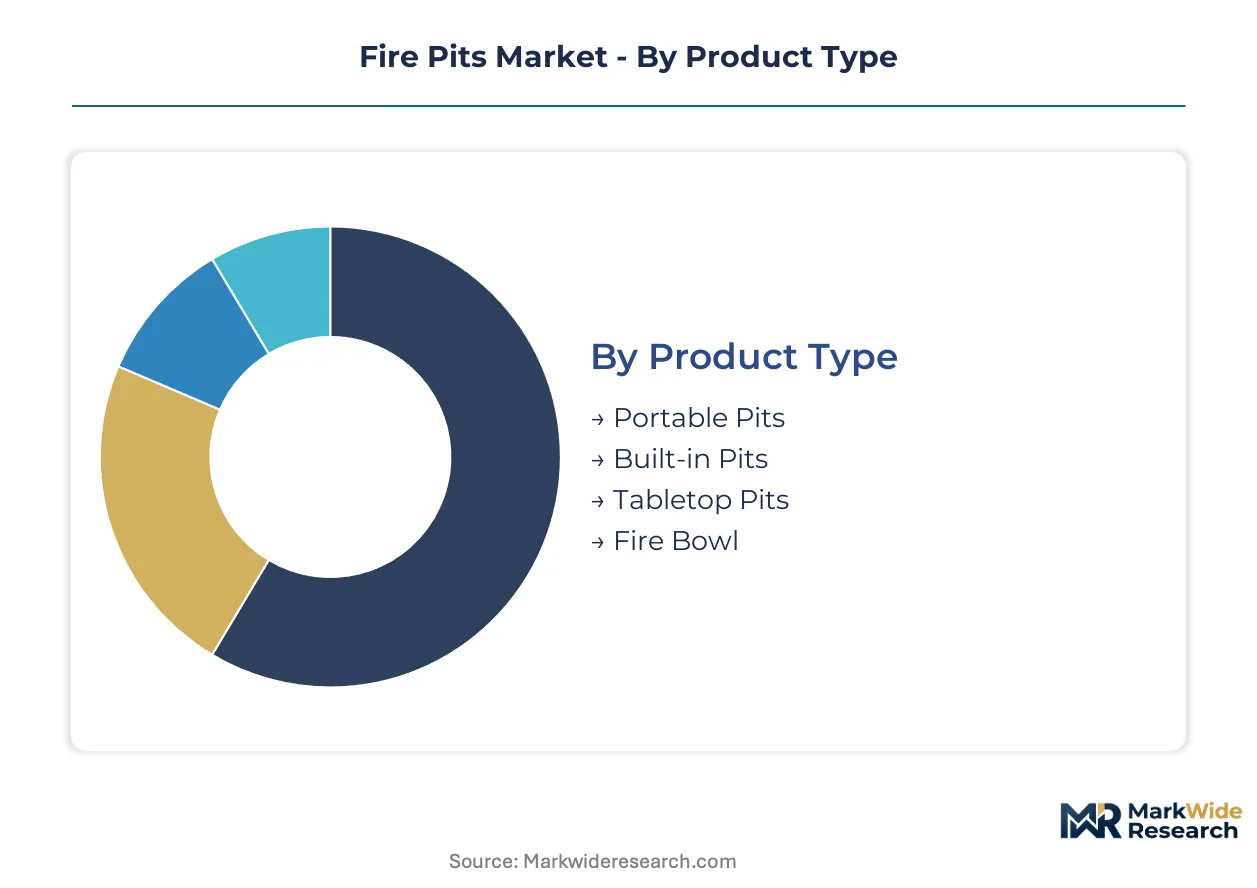
The fire pits market segments across diverse product types, materials, fuel sources, and end-user applications. Understanding these distinctions is critical for manufacturers to align product development with specific consumer demands and regulatory environments. Each segment presents unique challenges and opportunities, influencing design, distribution, and pricing strategies across the industry.
Product Type:
Supply chain configuration for fire pits often dictates the availability and specialization of product types, from mass-produced portable units to custom built-in installations.
- Portable Pits:These are controlled outdoor fireplaces designed for mobility, often featuring compact designs and lighter materials for easy transport. Demand concentrates in residential settings across North America, driven by backyard upgrades and camping applications.
- Built-in Pits:Permanently installed fire features integrated into outdoor living structures, typically using masonry or stone, requiring professional installation. These command higher average selling prices in commercial hospitality projects, enhancing luxury outdoor spaces.
- Tabletop Pits:Smaller, decorative fire features designed to sit on outdoor tables, often fueled by propane or gel for convenience.
- Fire Bowl:Freestanding, open-top vessels for burning wood or gas, providing a traditional focal point for outdoor gatherings.
Portable Pits absorb the bulk of installed capacity; Built-in Pits are expanding most quickly.
Material:
Price differentiation across materials reflects both raw input costs and the perceived value in outdoor aesthetics and long-term durability.
- Steel:Durable and versatile metal, commonly used in a wide range of fire pit designs from basic bowls to advanced smokeless units. Demand for steel models is concentrated in the residential mass market, valued for its balance of cost and longevity.
- Cast Iron:Robust and heavy material known for excellent heat retention, primarily utilized in traditional, rustic fire pit designs.
- Concrete:Heavy-duty, aesthetically appealing material offering a modern, integrated look, often used for built-in or fire table designs. Concrete fire pits command premium pricing in upscale residential and commercial projects due to their durability and design flexibility.
- Copper:Premium metal offering a distinctive aesthetic and natural patina development, often chosen for high-end decorative fire bowls and accents.
The market shows a clear preference for Steel due to its versatility; Concrete is gaining traction for its modern design appeal.
Fuel Type:
Consumer preferences heavily influence fuel type choices, balancing convenience against traditional ambiance and local regulatory constraints.
- Wood:Traditional fuel source providing authentic flame aesthetics and heat, favored by consumers seeking a classic outdoor experience. The wood-burning segment maintains a large installed base, particularly in less regulated suburban and rural areas.
- Propane:Convenient, portable, and cleaner-burning fuel, typically stored in external tanks, offering instant ignition and adjustable flames. Demand for propane-fueled units is concentrating in urban residential settings and commercial hospitality for ease of use and reduced emissions.
- Natural Gas:Clean-burning fuel connected directly to a home's gas line, providing unlimited runtime and consistent heat output for permanent installations.
- Gel:Small, self-contained canisters of ethanol-based fuel offering a smoke-free, portable flame, primarily used in tabletop or decorative fire features.
While Wood maintains a significant installed base, Propane is seeing accelerated adoption due to its ease of operation.
End User:
Application requirements drive distinct product configurations across end-user segments, from intimate residential settings to large commercial venues.
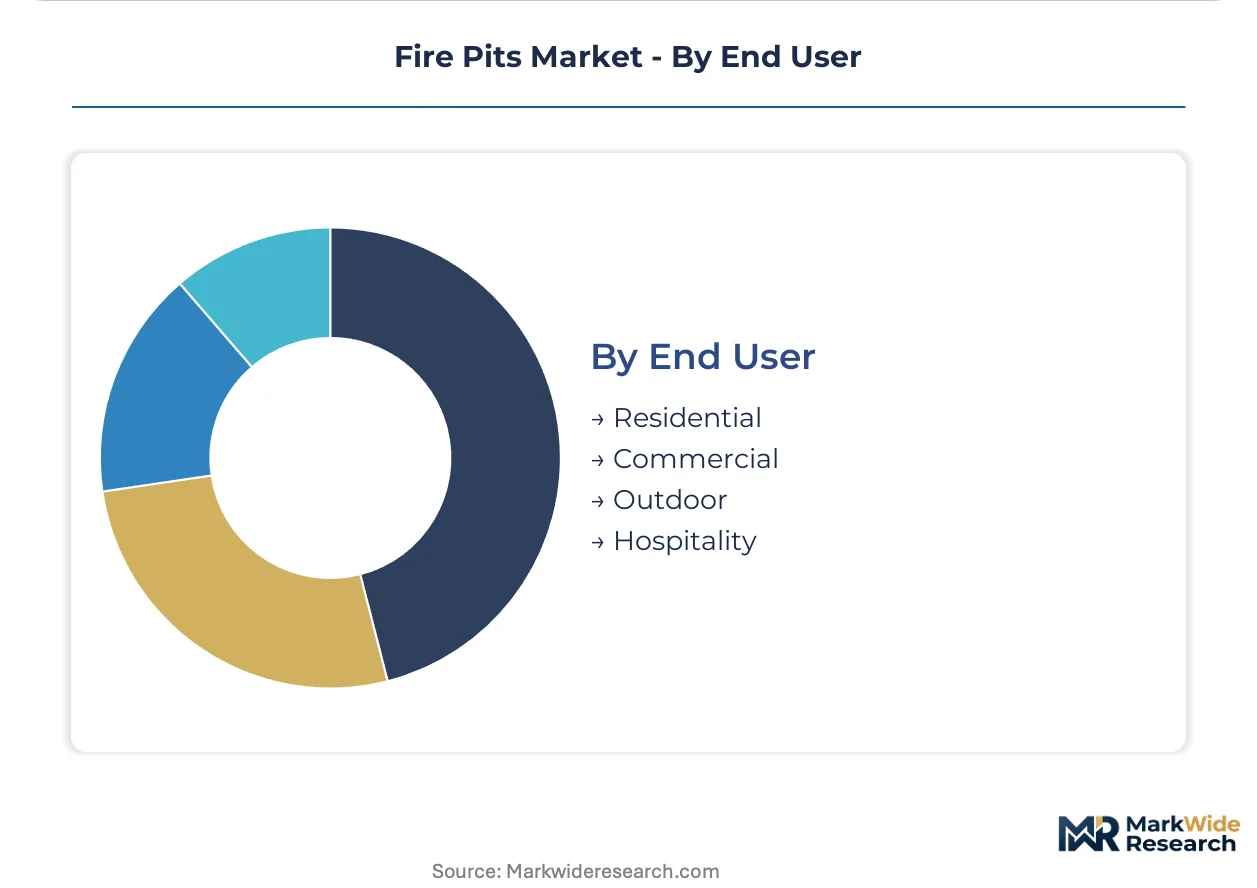
- Residential:Individual homeowners purchasing fire pits for private backyard, patio, or deck use, prioritizing aesthetics, convenience, and safety features. This segment accounts for the largest volume of unit sales, focusing on enhancing outdoor living spaces.
- Commercial:Businesses like hotels, restaurants, and event venues integrating fire pits to create inviting outdoor ambiances and extend operational seasons. Commercial demand is particularly strong in North America, enhancing guest experiences and property value.
- Outdoor:General outdoor recreational use, encompassing products for camping, tailgating, or public parks, often prioritizing portability and durability.
- Hospitality:Specific subset of commercial users including resorts, cruise lines, and luxury accommodations, demanding high-end, durable, and often custom fire pit installations.
The Residential segment drives the majority of unit sales, while Commercial represents a key growth vector for premium offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles, California, exemplifies the robust demand for fire pits, particularly in residential outdoor living and commercial hospitality sectors. This market expansion is notable across North America, driven by consumer focus on upgrading backyards. Manufacturers are adapting to varied regional preferences and regulatory landscapes.
United States
Residential outdoor living in the United States drives significant demand for fire pits, with consumers seeking enhanced backyard ambiance. Gas-fueled appliances must adhere to UL or CSA standards for safety. Cities across California, such as San Diego, experience local fire bans influencing product design towards cleaner-burning options.
Canada
Patio upgrades and commercial hospitality expansion fuel demand for fire pits throughout Canada. Health Canada guidelines influence product safety and emissions, especially for gas models. In Vancouver, British Columbia, there is a strong preference for smokeless and convenient propane units.
Germany
European market penetration offers a substantial opportunity for advanced fire pit models in Germany. CE marking is essential for gas-fueled appliances to ensure compliance with health and safety standards. Urban centers like Berlin are seeing increased interest in convenient and aesthetically pleasing outdoor heating solutions.
Australia
Australian residential outdoor living spaces demand fire pits, particularly multi-functional units that integrate tabletop surfaces. Local air quality rules and fire bans, such as those in Sydney, influence consumer choices towards cleaner fuel types. Melbourne also demonstrates a growing market for premium, durable concrete fire pit designs.
Fire Pits Market Key Industry Players
Premium-margin players sit above commodity-margin players across product innovation and material quality within the fire pits market. The competitive landscape features a tiered structure, from highly specialized manufacturers focusing on advanced combustion to broader retailers offering basic steel units. Strategic archetypes include technology innovators, design-focused specialists, and mass-market volume producers. Companies are engaging in both geographic expansion and portfolio diversification to capture market share.
Within the premium portable category, Solo Stove exemplifies companies leveraging patented airflow designs for smokeless combustion, appealing to urban and suburban consumers. Breeo Industries occupies a position among specialists in heavy-gauge steel, smokeless wood-burning models, emphasizing durability and performance. Landmann, conversely, represents brands offering a broader range of traditional designs, particularly for European retail channels, competing on accessibility and variety. These companies anchor different segments of the market by focusing on specific innovation or distribution strengths and catering to distinct consumer preferences.
| Leading Market Players |
|---|
| Solo Stove |
| The Outdoor GreatRoom Company |
| Warming Trends |
| Landmann |
| Crate and Barrel |
| Firepits UK |
| Airxcel |
| Breeo Industries |
| Ohio Flame |
| Others |
Cost & Logistics Intelligence
The bifurcation between premium smokeless fire pits and commodity wood-burning units drives distinct pricing strategies and supply chain configurations. Premium models emphasize specialized components and advanced manufacturing, while commodity tiers focus on raw material cost efficiency.
Pricing Analysis
Outcome-based pricing anchors premium fire pit models, reflecting their enhanced performance in smoke reduction and durability. The dominant pricing structure remains per-unit transactional, with price differentiation driven by material quality, specific safety certifications like UL or CE marking, and brand recognition. Pricing pressure on commodity wood-burning units stems from input cost volatility, particularly for steel and copper. Residential buyers for basic models exhibit high price sensitivity, while commercial hospitality clients prioritize features and durability over initial cost.
Supply Chain Analysis
Reverse-logistics for fire pits primarily manages warranty returns and material reclamation, with limited refurbishment activity due to product lifecycle and cost. Geographic supply concentration for components and finished goods largely centers on China and North America. Manufacturers depend on heavy-gauge steel, copper, and specialized gas components. Raw material price volatility, especially for steel and copper, represents a significant structural risk. Distribution runs through a multi-channel model encompassing big-box retailers, e-commerce platforms, and direct sales to commercial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
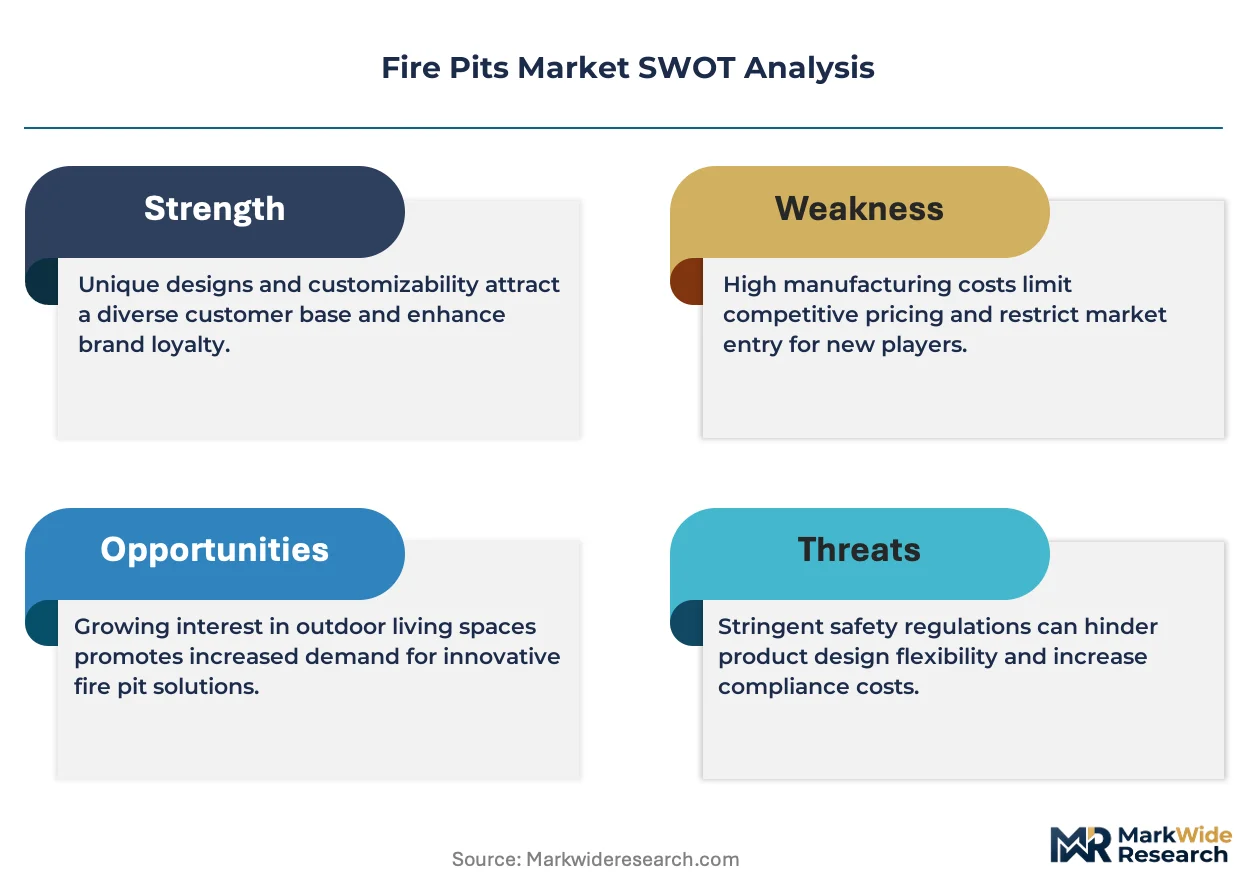
The fire pits market presents a cost-of-compliance narrative, where rigorous safety standards like CE marking for gas-fueled appliances establish a barrier-to-entry moat for compliant manufacturers. This regulatory landscape ensures product integrity and consumer safety, favoring established players.
For Market Incumbents: Anticipate continued investment in advanced smokeless combustion technology to counter local fire bans and air quality regulations. Consolidate market share by deepening penetration in the commercial hospitality sector, leveraging existing distribution networks. Reinforce brand premium through continuous material science innovation and securing comprehensive safety certifications like UL and CE marking. This strategy mitigates the threat from electric heaters and less regulated alternatives.
For New Entrants and Emerging Players: Begin with targeted market entry into underserved European retail channels, introducing advanced smokeless wood-burning and convenient propane-fueled models. Focus on the modular and customizable design segment within residential outdoor living, where personalized solutions command higher prices. Leverage direct-to-consumer e-commerce platforms with interactive design tools as a primary go-to-market angle. This approach allows for rapid iteration and direct customer feedback.
For Investors and Strategic Acquirers: Re-rating potential sits with technology-driven specialists in smokeless combustion given the increasing regulatory scrutiny on emissions and sustained consumer demand for convenience. The market demonstrates long-term viability, anchored by persistent residential outdoor living upgrades and commercial hospitality expansion. Prioritize acquisition targets with patented intellectual property in airflow design or smart home integration capabilities for gas models. Monitor the increasing stringency of local air quality rules as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Smokeless Technology R&D | Reduces particulate emissions, expanding market access in regulated urban areas. |
| Expand Commercial Hospitality Sales | Captures high-margin demand from hotels and resorts enhancing guest experiences. |
| Pursue CE Marking for Gas Appliances | Unlocks significant market access and sales opportunities across the European Union. |
| Develop Modular Fire Pit Systems | Caters to consumer demand for customization, commanding premium pricing and design flexibility. |
| Integrate Smart Home Controls | Enhances user convenience with remote ignition and flame adjustment, creating a new premium category. |
Research Approach
Document review covered industry reports, regulatory filings from UL, CSA, and CE, trade association publications, and company financial statements, complemented by interviews with key stakeholders. Primary research involved discussions with fire pit manufacturers, product developers, commercial hospitality buyers, and retail channel managers. This approach ensured comprehensive data collection. Findings were then triangulated using both bottom-up market sizing and top-down validation.
Historical data was cross-referenced with expert panel input to build the forecast framework across the analysis window. The analytical framework modeled market dynamics across product type, material, fuel type, end-user, and geographic region. Compound Annual Growth Rates were derived from regression analysis of historical trends and projected market growth assumptions. Key industry-specific forecast inputs included raw material price trends and residential construction spending.
Underlying measurement precision varies by segment; established residential and commercial segments carry tighter precision than emerging niche applications. Forecasts reflect assumptions regarding economic stability and regulatory environments. Practitioners should monitor new air quality regulations or significant raw material price shocks for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Paintball Field Service Market
Outdoor & Sports
Camping Lights and Lanterns Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Swimming Pool Liner Market
Outdoor & Sports
Swimming Pool Equipment Market
Outdoor & Sports
China Fishing Reels Market