
 Global Paintball Equipment Market | 2026-2036
Global Paintball Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Paintball Equipment Market Outlook
ASTM F2272 is recalibrating the cost-of-entry calculus for paintball marker manufacturers seeking North American market access. DYE Precision, Inc. leverages in-house anodizing capabilities to sustain premium positioning across tournament-grade electropneumatic platforms. Planet Eclipse Ltd anchors its competitive standing through UK-based precision machining and limited-production marker architectures. Valken Inc. controls distribution breadth across both direct-to-field supply and retail sporting goods channels.
Paintball equipment encompasses pneumatic or mechanically actuated projectile launch systems, protective optical-grade polymer masks, gelatin-shell projectiles filled with polyethylene glycol dye, and polymer ammunition containment pods designed for rapid-reload scenarios. Markers operate at standardized velocities below 300 feet per second, with compressed air or carbon dioxide propulsion systems calibrated for recreational and competitive play. The mask segment leads unit volume due to mandatory field-rental turnover and replacement cycles tied to lens degradation. Professional-tier markers command concentrated margin pools, while online retail channels are displacing specialty store foot traffic for replacement pod and paintball consumable purchases.
ASTM International governs marker safety and velocity standards in the United States, while the EU's REACH framework regulates chemical compositions in paintball fill materials and lens polymers across European markets. Brazil's national consumer protection regulator enforces import certification requirements that shape product availability for Latin American distribution. Stakeholders must monitor evolving polymer sustainability mandates and air system certification protocols as procurement criteria across institutional buyers and commercial field operators tighten.
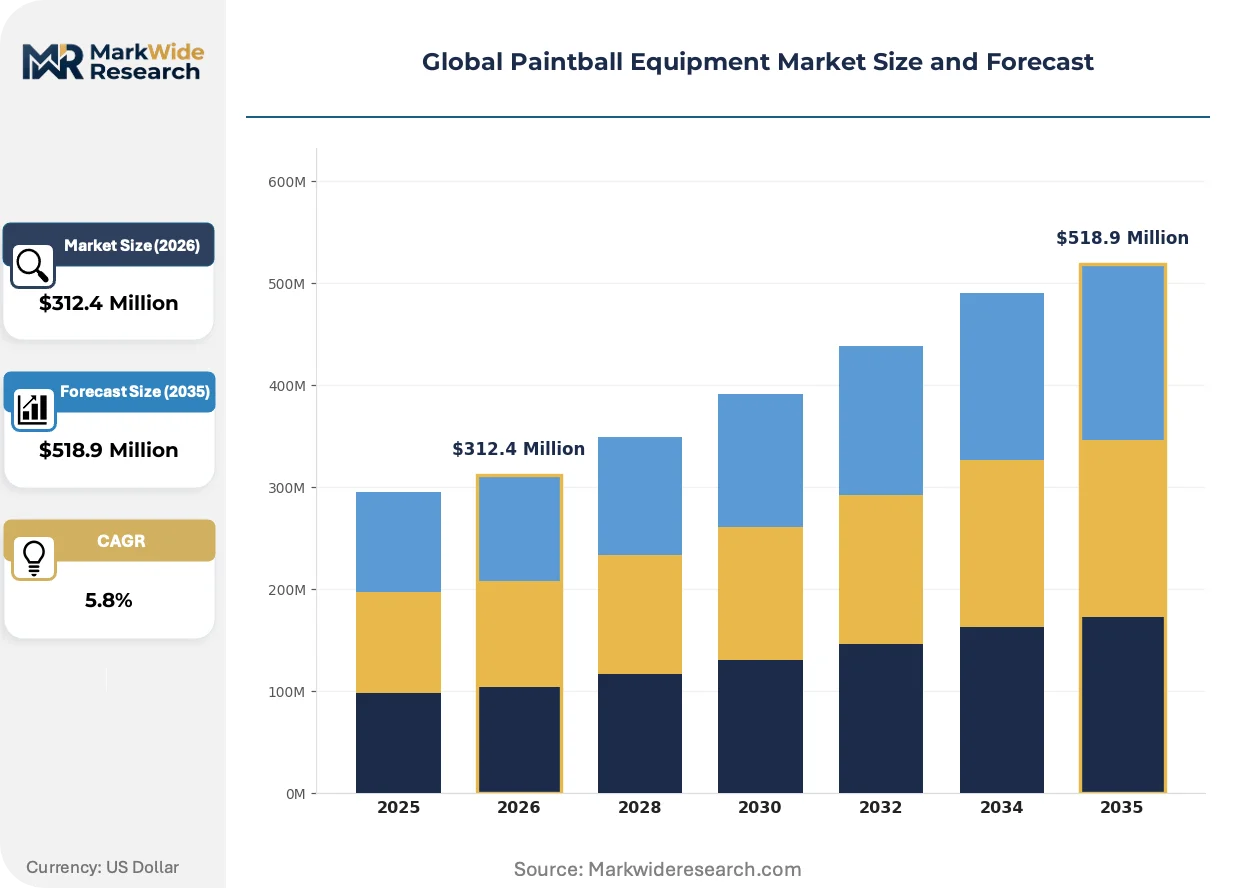
Market Dynamics
ASTM F2272 velocity certification requirements are compressing product development timelines for marker manufacturers seeking North American distribution, forcing upstream investment in testing infrastructure and recalibrating competitive entry thresholds.
Growth Catalysts
- São Paulo Tournament Circuit:Brazil's competitive league infrastructure is generating concentrated equipment refresh cycles among professional-tier players and affiliated field operators.
- REACH Framework Compliance:EU chemical safety standards for lens polymers and paintball fill materials are standardizing product specifications across European distribution channels.
- Compressed Air System Adoption:Carbon dioxide displacement by high-pressure air systems is extending marker maintenance intervals and reducing field operator liability exposure.
Market Restraints
- Polymer Input Volatility:Optical-grade polycarbonate lens blanks face petrochemical feedstock price swings that compress mask manufacturing margins.
- Import Certification Friction:Brazil's national consumer protection regulator enforces documentation requirements that delay Latin American product availability.
- Electronic Marker Complexity:Tournament-grade electropneumatic platforms require specialized technician labor pools that concentrate in developed markets.
Strategic Opportunities
- Baja California Recreational Corridor:Mexico's northern border region exhibits underdeveloped field infrastructure relative to cross-border demand from California recreational players.
- Sustainability-Driven Procurement:Biodegradable shell formulations and recyclable packaging are aligning with institutional buyer environmental mandates in Germany.
- Direct-to-Field Distribution:Bypassing traditional retail sporting goods channels is capturing replacement consumable volume from high-frequency recreational facilities.
Industry Challenges
- ASTM F2272 Certification Timeline:Third-party testing backlog for velocity compliance is extending product launch windows by 4-6 months for new marker entrants.
- Precision Machining Talent Scarcity:UK and German manufacturing clusters face competition for CNC programming expertise from adjacent aerospace and medical device sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Paintball Equipment Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Markers, Masks, Paintballs, Pods Customer Type: Individuals, Teams, Schools, Organizations Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Stores, Events Price Tier: Budget, Mid-Range, Premium, Professional |
| Companies Covered | Virtue Paintball, LLC, DLX Technology Group, Planet Eclipse Ltd, Arrow Precision Ltd, DYE Precision, Inc., Azodin Paintball Inc, Valken Inc., HK Army, Inc., Kore Outdoor (US) Inc. (G.I.Sportz), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Paintball Equipment Market Strategic Shifts
Electropneumatic firing control systems are compressing the performance gap between rental-grade and tournament-grade markers, reshaping equipment lifecycle management across commercial field operators and competitive leagues.
Electropneumatic solenoid valve technology is automating firing sequence calibration in mid-tier marker platforms. Recreational facility operators in the United States are adopting these systems to reduce rental equipment maintenance labor. This automation is compressing the traditional three-tier product hierarchy into two performance bands.
REACH chemical registration requirements are tightening disclosure obligations for polyethylene glycol dye formulations and lens polymer additives. European distributors are consolidating supplier relationships to manage documentation burden. Tournament-grade mask manufacturers serving EU markets are accelerating material substitution programs.
Online consumable procurement is displacing specialty store foot traffic for replacement pods and paintball purchases. High-frequency recreational players in Germany and Brazil are migrating to subscription-based replenishment models. Field operators in São Paulo state are responding by bundling entry fees with equipment-inclusive packages to capture margin upstream.
Global Paintball Equipment Market Segmentation
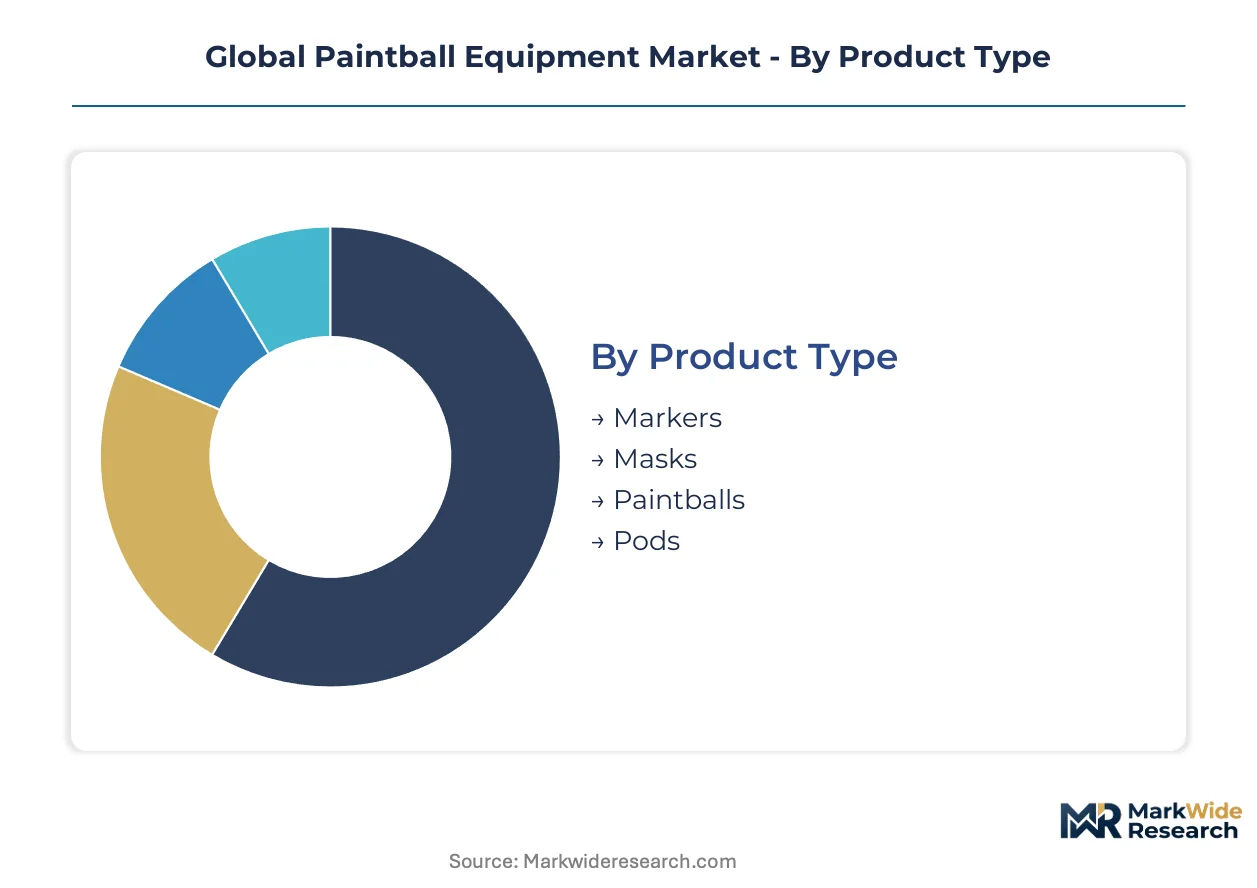
Paintball equipment segmentation reveals how certification burdens, procurement patterns, and channel economics concentrate margin across distinct product tiers and buyer categories. ASTM F2272 velocity compliance and REACH chemical disclosure requirements create divergent cost structures that reshape competitive positioning within each segment cluster.
Product Type:
ASTM F2272 velocity certification applies selectively across product categories, with pneumatic launch systems facing the most intensive third-party testing protocols while protective equipment navigates optical-grade polymer standards.
- Markers:Pneumatic or mechanically actuated projectile launch systems operating below 300 feet per second, with electropneumatic solenoid valve technology automating firing sequence calibration. Demand concentrates among tournament-grade purchasers in Brazil's São Paulo state circuit, where equipment refresh cycles accelerate amid competitive league infrastructure expansion. Compressed air system adoption is extending maintenance intervals and reducing field operator liability exposure.
- Masks:Protective optical-grade polymer face shields with lens systems subject to degradation-driven replacement cycles. Mandatory field-rental turnover in the United States and Germany sustains unit volume leadership, while REACH framework compliance is accelerating material substitution programs among European distributors managing documentation burden.
- Paintballs:Gelatin-shell projectiles filled with polyethylene glycol dye formulations regulated under EU chemical safety standards. Brazil's ANVISA enforces import certification requirements that shape Latin American product availability.
- Pods:Polymer ammunition containment systems designed for rapid-reload scenarios. Online retail channels are displacing specialty store foot traffic for replacement purchases among high-frequency recreational players.
Leading the category by volume: Masks. Growing fastest: Electropneumatic marker platforms.
Customer Type:
Procurement scale and frequency diverge sharply across buyer categories, with institutional purchasers leveraging environmental mandates while competitive players prioritize performance certification.
- Individuals:Recreational players driving replacement consumable volume through online channels and subscription-based replenishment models. São Paulo state field operators respond by bundling entry fees with equipment-inclusive packages.
- Teams:Organized competitive units generating concentrated equipment refresh cycles and professional-tier margin pools. Tournament circuit infrastructure in Brazil and Mexico's Baja California corridor anchors demand.
- Schools:Institutional buyers in Germany aligning procurement with sustainability-driven mandates for biodegradable shell formulations and recyclable packaging.
- Organizations:Corporate and recreational facility operators expanding field infrastructure in the United States and Germany, with direct-to-field distribution capturing replacement consumable volume.
Volume concentrates with Individual recreational players. Steepest expansion trajectory: Organizational buyers modernizing field infrastructure.
Distribution Channel:
Channel economics reflect divergent fulfillment costs and customer acquisition strategies, with digital platforms capturing consumable replenishment while experiential retail retains equipment trial advantages.
- Online Retail:Digital platforms displacing specialty store foot traffic for replacement pods and paintball purchases. High-frequency players in Germany and Brazil are migrating to subscription-based replenishment models.
- Specialty Stores:Focused retailers maintaining equipment trial and fitting services for mask purchases. Foot traffic erosion is compressing specialty store viability for consumable categories.
- Sporting Goods Stores:Generalist retail channels carrying mid-tier marker and protective equipment assortments. Inventory breadth constraints limit tournament-grade product availability.
- Events:Tournament and field-based direct sales capturing impulse replacement purchases and equipment upgrades. São Paulo circuit events concentrate event-based transaction volume.
Online Retail leads transaction frequency. Events channel is gaining share fastest among professional-tier equipment.
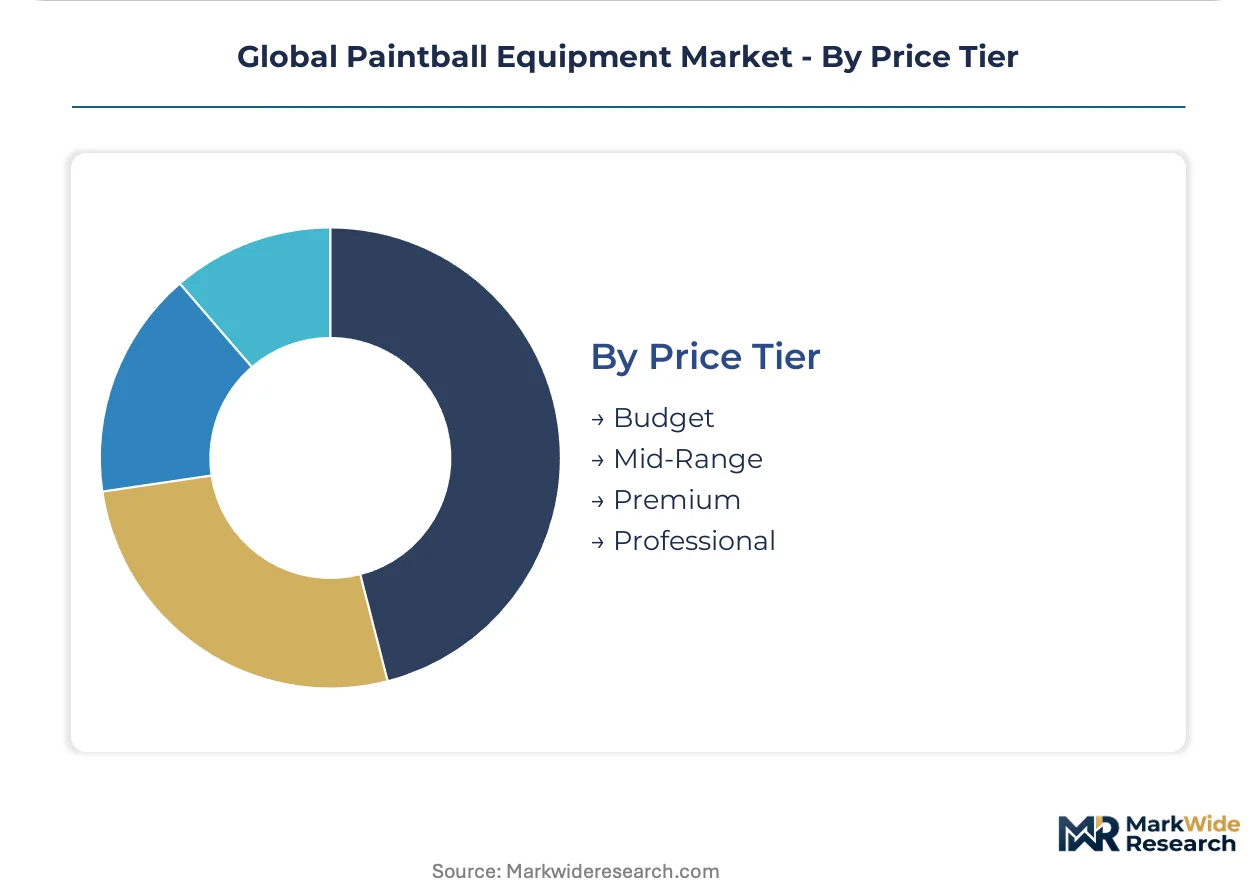
Price Tier:
Cost stratification aligns with performance certification requirements and manufacturing complexity, with professional tiers commanding concentrated margin pools and budget segments facing compressed economics.
- Budget:Entry-level mechanical markers and rental-grade protective equipment. Field operators in the United States adopt automated electropneumatic systems to reduce maintenance labor, compressing traditional three-tier hierarchy.
- Mid-Range:Electropneumatic platforms with solenoid valve automation bridging performance gaps. This tier is absorbing volume migration from both budget upgrades and premium downgrades.
- Premium:Tournament-grade equipment with precision machining and limited-production architectures. UK and German manufacturing clusters face CNC programming talent scarcity from competing aerospace and medical device sectors.
- Professional:Elite competitive platforms with in-house anodizing capabilities and certified velocity compliance. ASTM F2272 testing backlog extends product launch windows by 4-6 months for new entrants.
Mid-Range captures the greatest volume migration. Professional tier holds the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Baja California and São Paulo state concentrate field infrastructure investment. Tax incentives for recreational tourism development accelerate capital deployment. Regional regulatory divergence shapes equipment certification timelines and import clearance protocols.
United States
ASTM F2272 velocity certification compresses product launch windows for marker manufacturers. OSHA workplace safety guidelines influence field operator liability insurance requirements. California recreational players drive cross-border demand into Mexico's Baja California corridor.
Germany
REACH framework chemical disclosure mandates accelerate material substitution programs for mask lens polymers. Sustainability procurement criteria from institutional buyers favor biodegradable paintball shell formulations. Bavarian manufacturing clusters face CNC programming talent competition from aerospace and medical device sectors.
Brazil
São Paulo state tournament circuits generate concentrated equipment refresh cycles among professional-tier players. ANVISA import certification documentation requirements delay Latin American product availability. Field operators respond to online consumable migration by bundling entry fees with equipment-inclusive packages.
Mexico
Baja California recreational corridor exhibits underdeveloped field infrastructure relative to cross-border demand from California players. The country's national consumer protection regulator enforces documentation standards that shape distribution channel economics. Northern border region field operators capture spillover from US recreational player mobility.
United Kingdom
Precision machining expertise concentrates in manufacturing clusters serving tournament-grade marker architectures. CE marking requirements for protective equipment standardize product specifications across European distribution. UK-based fabricators anchor competitive standing through limited-production marker platforms.
Global Paintball Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across equipment tiers. The vendor base separates into three strategic archetypes: precision machining specialists, distribution-integrated operators, and consumable-focused suppliers. Consolidation pressure concentrates among mid-tier electropneumatic platform manufacturers. Dominant competitive moves include direct-to-field distribution bypass and in-house production capability acquisition.
Among UK-based precision fabricators, Planet Eclipse Ltd occupies a position within the tournament-grade machining specialist archetype. Valken Inc. exemplifies the distribution-integrated operator model with control across direct-to-field supply and retail sporting goods channels. DYE Precision, Inc. represents the premium-tier specialist segment with captive anodizing capabilities. These three anchors illustrate how geographic manufacturing concentration and channel control differentiate competitive positioning across the equipment value chain.
| Leading Market Players |
|---|
| Virtue Paintball, LLC |
| DLX Technology Group |
| Planet Eclipse Ltd |
| Arrow Precision Ltd |
| DYE Precision, Inc. |
| Azodin Paintball Inc |
| Valken Inc. |
| HK Army, Inc. |
| Kore Outdoor (US) Inc. (G.I.Sportz) |
| Others |
Value Chain & Pricing Dynamics
Petrochemical feedstock volatility in optical-grade polycarbonate lens blanks cascades through mask manufacturing into three performance tiers, with ASTM F2272 certification costs compressing margins at the professional marker tier while rental-grade equipment absorbs volume-driven cost efficiencies.
Pricing Analysis
Lead-time premiums for certified tournament-grade markers command substantial markups over spot inventory, with professional-tier purchasers absorbing extended delivery windows from third-party testing backlog. Three-tier pricing structure across premium, standard, and economy levels separates certified electropneumatic platforms from mid-range automation and mechanical rental units. Price differentiation hinges on velocity certification grade and in-house anodizing capability. Cost compression in budget tiers intensifies as field operators consolidate rental fleets. Individual recreational players exhibit highest price sensitivity, while team buyers prioritize certification compliance over unit cost.
Supply Chain Analysis
Brazil's ANVISA domestic-content documentation requirements reshape sourcing patterns for Latin American distribution, forcing inventory pre-positioning in São Paulo state. Manufacturing concentrates in the United Kingdom, Germany, and the United States, with precision machining clusters feeding tournament-grade marker architectures. Raw material dependencies center on optical-grade polycarbonate, high-pressure aluminum forgings, and gelatin-shell formulations. Single-source vulnerability concentrates in UK-based CNC programming expertise competing with aerospace and medical device sectors. Distribution runs through direct-to-field supply channels capturing replacement consumable volume from high-frequency recreational facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certification-capable manufacturers, with ASTM F2272 testing infrastructure requirements forcing weaker capitalized entrants toward private-label or distribution-only models.
For Market Incumbents: To counter mid-tier electropneumatic automation compressing the traditional product hierarchy, DYE Precision-style captive anodizing capabilities and Planet Eclipse-pattern limited-production architectures defend margin pools. Channel control through direct-to-field distribution captures consumable replenishment volume migrating from specialty retail. Certification investment in third-party velocity testing infrastructure extends competitive moats against new marker entrants.
For New Entrants and Emerging Players: Electropneumatic solenoid miniaturization offers entry into the mid-range automation segment where performance gaps between rental and tournament tiers are collapsing. White-space targets concentrate in Mexico's Baja California corridor field infrastructure and subscription-based consumable replenishment models for German high-frequency players. Go-to-market execution favors bundling equipment-inclusive packages with field entry fees, mirroring São Paulo state operator responses to online migration.
For Investors and Strategic Acquirers: Distressed-cycle entries favor distribution-integrated operators with direct-to-field channel control in the United States and Germany, where field infrastructure expansion accelerates capital deployment. Long-term viability centers on manufacturers with in-house precision machining and captive compliance testing capabilities. Watch compressed air system adoption rates as inflection indicator for maintenance-interval economics and field operator liability exposure reduction.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Infrastructure Investment | ASTM F2272 third-party testing capability compresses rival launch timelines by 4-6 months. |
| Direct-to-Field Distribution Expansion | Bypassing retail sporting goods channels captures replacement consumable volume from high-frequency facilities. |
| Electropneumatic Platform Miniaturization | Solenoid automation bridges rental-grade and tournament-grade performance bands. |
| Sustainability-Driven Material Substitution | Biodegradable shell formulations align with German institutional procurement mandates. |
| Precision Machining Talent Acquisition | CNC programming expertise scarcity in UK and German clusters threatens tournament-grade production capacity. |
Study Parameters
Independent corroboration across field operator interviews, precision machining facility assessments, and regulatory filing analysis underwrites the qualitative findings. Primary engagement encompassed tournament circuit organizers, commercial field operators, protective equipment procurement managers, and compressed air system distributors. Secondary validation drew from ASTM International certification records, ANVISA import documentation, REACH chemical registration databases, and trade flow customs data. Bottom-up equipment shipment tracking and top-down recreational facility investment analysis triangulate market sizing.
Comparable-period anchoring to historical certification timeline data and field infrastructure deployment cycles established the forecast reference framework. Segmentation modeling spanned product type, customer archetype, distribution channel, and price tier across the projection horizon. CAGRs derive from equipment refresh cycle analysis, consumable replenishment frequency patterns, and regulatory compliance cost trajectories. Compressed air system displacement rates and polymer substitution program timelines inform forward-looking inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory velocity threshold revisions, abrupt petrochemical feedstock disruptions, and tournament circuit cancellation events. Forecasts reflect documented assumptions regarding certification backlog durations and field operator capital expenditure continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Global Swimming Pool Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Cold Plunge Pools Market
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Camping Utensils Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Fire Pits Market