
 Swimming Pool and Spa Market | 2026-2036
Swimming Pool and Spa Market Size, Share, and Industry Trends Forecast 2026-2036
Swimming Pool and Spa Market Insights
Vinyl liner manufacturing capacity in the southeastern United States is shifting toward thicker gauge materials and welded seam technologies. Master Spas leverages vertical integration across its Fort Wayne production campus to control fiberglass shell quality. Jacuzzi sustains brand strength through dealer network density in coastal California markets. Catalina Spas competes on price-positioned configurations targeting entry-level residential buyers.
Swimming pools and spas are engineered water-retention structures designed for recreational immersion, hydrotherapy, or athletic training, typically incorporating circulation systems with specified turnover rates of six to eight hours and sanitization through chlorine, bromine, or salt-chlorine generation. Their primary commercial purpose centers on property value enhancement, wellness programming, and hospitality amenity provision. In-ground concrete installations occupy the highest margin pool within residential construction due to customization complexity and extended project timelines. Above ground pools lead volume throughput in North American big-box retail channels. Fiberglass shells represent the fastest-growing material category as factory-controlled gelcoat application reduces on-site curing variability.
EPA Energy Star certification mandates for pool pumps are reshaping motor specification requirements across OEM supply chains. ANSI/APSP standards govern structural safety and suction entrapment prevention in permanent installations. CPSC recall protocols and state-level barrier fence ordinances add compliance layers that filter smaller installers from qualified bidding pools. Stakeholders must monitor evolving refrigerant regulations for heat pump heaters and position sourcing strategies around low-GWP alternatives before phase-down deadlines compress equipment availability.
Market Dynamics
EPA Energy Star pump mandates are compressing OEM supply chains toward variable-speed motor architectures while suburban wellness demand pulls fiberglass shell production toward factory-controlled gelcoat standardization.
Growth Catalysts
- Suburban Wellness Migration:Residential buyers in Florida, California, and Texas are prioritizing backyard hydrotherapy installations over discretionary interior renovations.
- EPA Energy Star Certification:Mandatory efficiency thresholds for pool pumps are forcing motor replacement cycles and opening retrofit demand across existing installed bases.
- Fiberglass Gelcoat Standardization:Factory-controlled shell production reduces on-site curing variability and compresses project timelines for residential contractors.
Market Restraints
- Chlorine Supply Volatility:Sanitizer input costs fluctuate with chemical feedstock availability, squeezing margin on entry-level vinyl liner configurations.
- Installer Qualification Concentration:CPSC recall protocols and state barrier fence ordinances filter smaller contractors from qualified bidding pools in regulated municipalities.
- Heat Pump Refrigerant Phase-Down:F-Gas Regulation timelines in Europe and EPA SNAP restrictions in the US compress equipment availability before low-GWP alternative sourcing matures.
Strategic Opportunities
- Salt-Chlorine Generation Retrofit:Existing chlorine-based installations in Texas and Arizona present conversion potential as sanitization preference shifts toward reduced chemical handling.
- Dealer Network Densification:Coastal California markets demonstrate how localized service coverage captures premium positioning in high-property-value corridors.
- Welded Seam Vinyl Technology:Thicker gauge materials with thermally bonded seams are displacing traditional overlap liners in southeastern US manufacturing capacity.
Industry Challenges
- Gelcoat Technician Scarcity:Fiberglass shell production requires specialized spray application expertise that outpaces vocational training pipeline output in factory-controlled environments.
- Multi-Standard Compliance Overlap:ANSI/APSP structural safety standards, CPSC entrapment protocols, and municipal barrier ordinances create documentation burden for cross-jurisdictional installers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Swimming Pool and Spa Market |
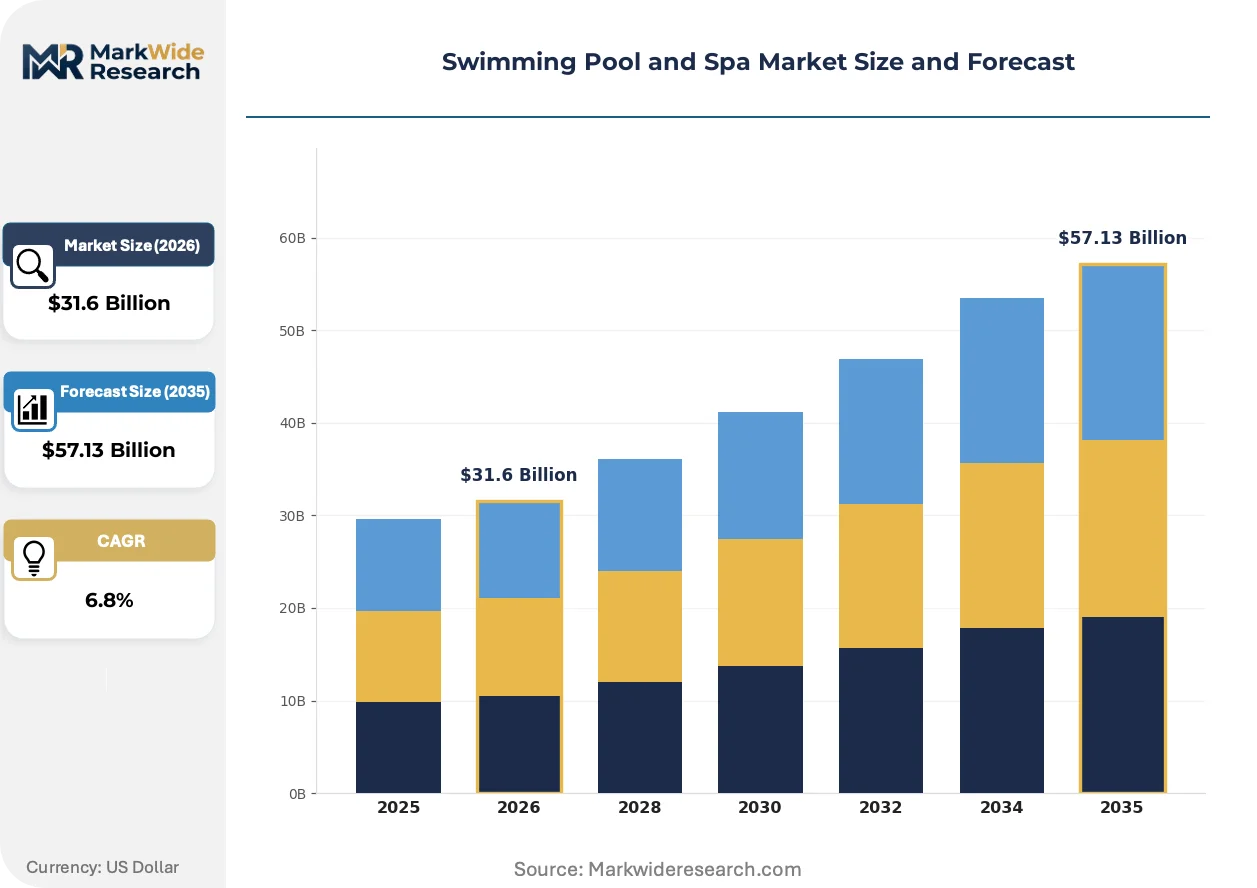
| Market Size in 2026 | $31.6 Billion |
| Market Size in 2035 | $57.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Above Ground Pools, In-Ground Pools, Spas, Hot Tubs Material: Fiberglass, Vinyl, Concrete, Steel Installation Type: Residential, Commercial, Portable, Semi-permanent Maintenance Service: Chemical Service, Cleaning, Repair, Renovation |
| Companies Covered | Master Spas, Catalina Spas, Jacuzzi, Bullfrog Spas, Cal Spas, Hot Spring, PDC Spas, Endless Pools, Sundance Spas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Swimming Pool and Spa Market Trends and Innovations
Connected circulation architecture and refrigerant-transition engineering are reconfiguring equipment procurement patterns while modular shell delivery compresses site labor dependency.
Variable-speed pump technology is decentralizing residential energy load profiles away from single-speed peak-demand spikes. Builders in Florida and California are specifying intelligent drive motors as default equipment. This shift compresses utility peak-demand exposure while extending motor replacement intervals.
EPA refrigerant phase-down schedules are accelerating heat pump heater redesign cycles toward R32 and CO2 alternatives. European F-Gas Regulation deadlines are pulling forward OEM engineering roadmaps by several product generations. Pool service contractors in Germany and France are pre-positioning low-GWP inventory ahead of availability constraints.
Buyer preference for turnkey project execution is consolidating procurement authority with regional dealer networks that bundle shell delivery, excavation coordination, and startup commissioning. This pattern concentrates volume with vertically integrated suppliers in suburban North American markets. Independent installers are responding by specializing in renovation and equipment retrofit segments.
Swimming Pool and Spa Market Segmentation
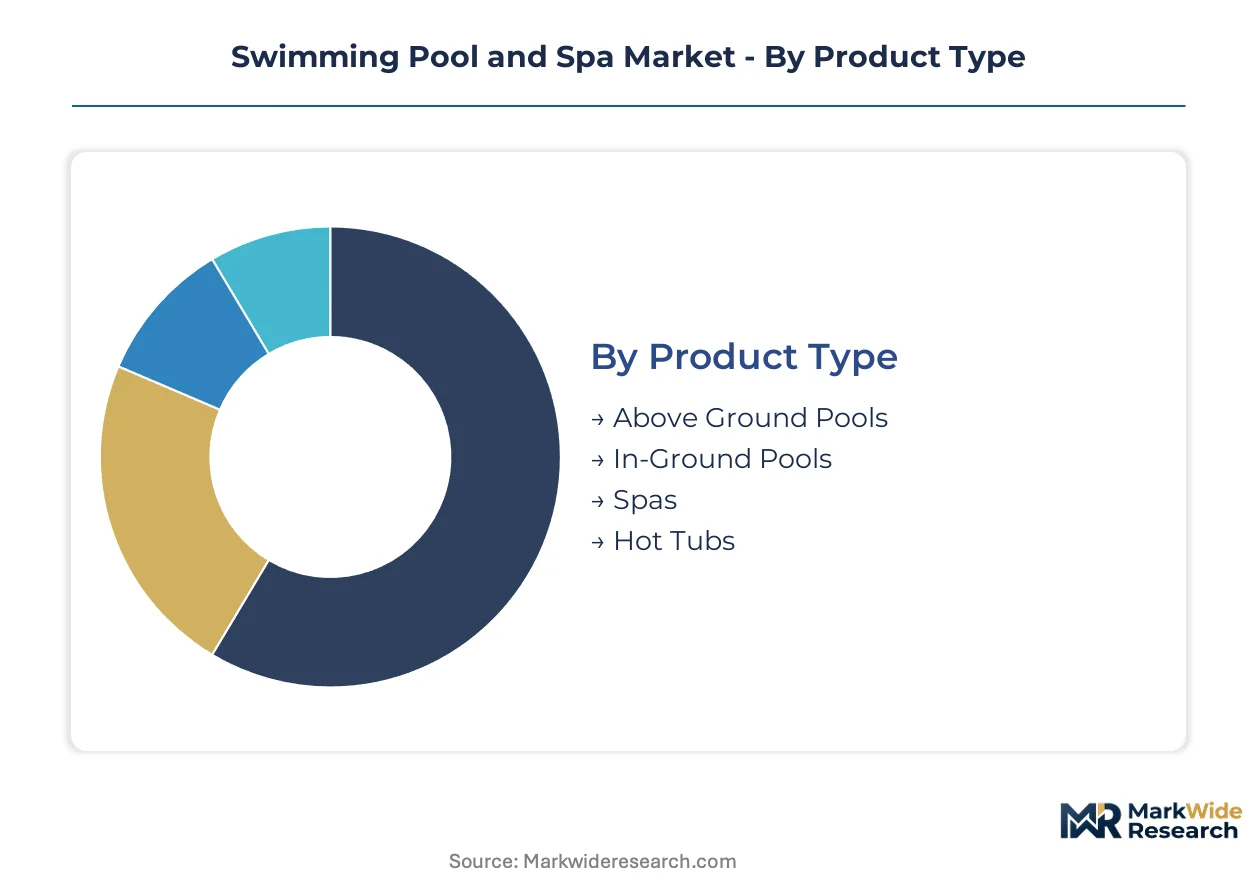
Product architecture in swimming pools and spas determines both upfront capital commitment and lifecycle service intensity. Material selection and installation permanence create distinct margin profiles that reshape competitive positioning across residential and commercial channels.
Product Type:
Buyers trade off customization depth against project velocity and total installed cost.
- Above Ground Pools:Modular steel or resin frame systems with drop-in liners dominate big-box retail throughput. Demand concentrates in suburban Texas and Florida where seasonal installation windows compress contractor availability and buyers prioritize speed.
- In-Ground Pools:Permanent excavated structures with gunite, shotcrete, or vinyl construction occupy the highest-margin tier in residential construction. California coastal markets drive specification complexity as property value enhancement motives override first-cost sensitivity.
- Spas:Self-contained hydrotherapy units with integrated seating and jet configurations serve wellness-focused suburban buyers. Portable electrical requirements expand addressable housing stock beyond permanent pool feasibility.
- Hot Tubs:Heated immersion vessels with dedicated circulation and sanitization systems target therapeutic use cases. Cold-climate states show elevated penetration where indoor installation extends usable seasons.
Volume sits with Above Ground Pools; growth tilts toward In-Ground Pools.
Material:
Manufacturing control over curing and finishing processes determines surface durability and warranty exposure.
- Fiberglass:Factory-molded gelcoat shells with standardized dimensions reduce on-site labor dependency and weather risk. Southeast US production capacity is shifting toward thicker laminates and welded seam integration.
- Vinyl:Flexible liner membranes stretched over steel or polymer wall panels enable custom perimeter shapes at moderate cost. Chemical service contracts concentrate with this material due to puncture vulnerability and replacement cycles.
- Concrete:Pneumatically applied gunite or hand-troweled plaster finishes permit unlimited form freedom and integrated water features. Skilled plasterer scarcity in Florida and Arizona compresses project completion rates.
- Steel:Corrosion-resistant wall panels with polymer or enamel coatings support above-ground and vinyl-liner in-ground structures. Cost positioning sustains volume in entry-level residential segments.
Fiberglass gains share fastest as factory quality control displaces field-cure variability.
Installation Type:
Permanence classification dictates regulatory compliance burden and financing structure.
- Residential:Single-family backyard installations driven by property value and wellness programming. Texas, Florida, and California account for disproportionate permit volume.
- Commercial:Multi-user facilities requiring ADA accessibility compliance and elevated liability coverage. Hospitality and municipal recreation departments dominate procurement authority.
- Portable:Inflatable or rigid-sided temporary structures avoiding excavation and permitting. Seasonal demand spikes concentrate in northern states with constrained permanent construction seasons.
- Semi-permanent:Deck-supported systems with removable anchoring for leasehold or rental properties. Multi-family housing conversions in suburban corridors show emerging specification.
Residential commands volume; Commercial carries margin concentration.
Maintenance Service:
Recurring service attachment rates vary by installation complexity and owner time constraints.
- Chemical Service:Scheduled water testing and sanitizer delivery sustaining EPA-compliant residual levels. Salt-chlorine generation retrofits in Arizona and Texas reduce chemical handling labor.
- Cleaning:Debris removal, surface vacuuming, and filter backwashing on weekly or bi-weekly cycles. Robotic cleaner penetration is compressing manual service pricing in premium markets.
- Repair:Structural patching, equipment replacement, and liner restoration addressing storm or wear damage. Fiberglass gelcoat technician scarcity extends lead times for cosmetic refinishing.
- Renovation:Full resurfacing, equipment modernization, and aesthetic upgrades extending asset life. Aging vinyl-liner installed bases in the Southeast present conversion opportunity.
Chemical Service anchors recurring revenue; Renovation shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida limestone deposits anchor fiberglass gelcoat supply chains for pool shell manufacturing across the southeastern United States. Suburban wellness demand concentrates in coastal zones where property values justify permanent installation investments.
United States
Texas, Florida, and California drive permit volume for residential pool installations as suburban buyers prioritize backyard hydrotherapy over interior renovations. EPA Energy Star pump mandates are forcing motor replacement cycles and opening retrofit demand across existing installed bases. Fort Wayne, Indiana hosts vertically integrated fiberglass production campuses controlling shell quality through captive supply.
Canada
Cold-climate provinces show elevated hot tub penetration where indoor installation extends usable seasons beyond traditional pool construction windows. Health Canada and PMRA regulate sanitizer chemical approvals and equipment safety standards for cross-border product entry. Ontario's Greater Toronto Area concentrates distribution infrastructure serving the Quebec and Prairie province markets.
Germany
European F-Gas Regulation deadlines are pulling forward OEM engineering roadmaps for heat pump heater redesign toward R32 and CO2 alternatives. The KBA and federal environmental agencies coordinate refrigerant phase-down enforcement compressing equipment availability timelines. Bavaria and Baden-Württemberg host specialized component fabricators supplying low-GWP heat pump technology.
Australia
New South Wales and Queensland coastal markets demonstrate sustained demand for salt-chlorine generation systems as sanitization preference shifts toward reduced chemical handling. The TGA and state-level building regulators govern structural safety and barrier fence compliance for residential installations. Sydney and Melbourne metro areas concentrate dealer network density capturing premium positioning in high-property-value corridors.
Brazil
São Paulo and Rio de Janeiro metropolitan regions anchor commercial hospitality procurement for multi-user pool facilities requiring ADA-equivalent accessibility compliance. ANVISA regulates sanitizer chemical imports and equipment safety certifications for the Mercosur trade zone. Southeastern manufacturing clusters are emerging as fiberglass shell assembly points serving the Argentine and Chilean export markets.
Swimming Pool and Spa Market Competitive Landscape
Global majors compete with regional champions across dealer network density and factory-controlled production quality. The vendor base organizes into three tiers: vertically integrated manufacturers with captive fiberglass capacity, specialist spa fabricators emphasizing hydrotherapy engineering, and price-positioned assemblers sourcing standardized components. Consolidation pressure concentrates volume with suppliers bundling shell delivery, excavation coordination, and startup commissioning. Dominant competitive moves include backward integration into gelcoat application and geographic expansion through authorized dealer recruitment.
Within the vertically integrated tier, Master Spas and Jacuzzi exemplify archetypes controlling production quality through in-house fiberglass operations. Catalina Spas occupies a position within the price-positioned segment targeting entry-level residential configurations. Bullfrog Spas represents the specialist archetype emphasizing modular jetpack technology differentiation. These three anchors illustrate how competitive positioning stratifies across premium, standard, and economy tiers based on manufacturing control depth and service bundling intensity.
| Leading Market Players |
|---|
| Master Spas |
| Catalina Spas |
| Jacuzzi |
| Bullfrog Spas |
| Cal Spas |
| Hot Spring |
| PDC Spas |
| Endless Pools |
| Sundance Spas |
| Others |
Pricing and Supply Chain Analysis
Chlorine feedstock price volatility cascades through vinyl liner manufacturing into three-tier pricing structure across premium, standard, and economy levels, with factory-controlled fiberglass gelcoat production commanding premium positioning while entry-level steel-frame configurations absorb chemical cost compression.
Pricing Analysis
Warranty and service bundling separates turnkey dealer packages from unbundled equipment-only transactions. Premium fiberglass shell installations incorporate multi-year gelcoat warranties and startup commissioning, while economy vinyl liner configurations compete on stripped first-cost with optional maintenance contracts. Price differentiation hinges on factory-controlled quality certification and geographic delivery radius from southeastern US production clusters. Pricing pressure stems from chlorine supply volatility squeezing margin on entry-level chemical service bundles. First-time suburban buyers in Texas and Florida exhibit highest price sensitivity; coastal California property-value-driven buyers show lowest.
Supply Chain Analysis
Gelcoat technician scarcity in Fort Wayne and southeastern US factory zones constrains fiberglass shell throughput below demand absorption capacity. Manufacturing concentrates in the United States, China, and Mexico, with raw material dependencies spanning petroleum-derived vinyl resins, limestone-based gelcoat compounds, and copper-nickel alloy heat exchangers. Supply chain risk centers on single-source vulnerability for specialized spray application equipment. Distribution runs through authorized dealer networks bundling shell delivery, excavation coordination, and startup commissioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Swimming Pool and Spa Market sits in a technology-transition phase as variable-speed pump architectures displace single-speed legacy motors under EPA Energy Star mandates.
For Market Incumbents: Extend captive fiberglass production capacity to control gelcoat quality consistency and compress warranty exposure. Deepen backward integration into welded seam vinyl liner manufacturing to offset chlorine cost volatility. Prioritize EPA Energy Star certification investment to capture mandatory motor replacement cycles across existing installed bases.
For New Entrants and Emerging Players: Capture salt-chlorine generation retrofit demand in Arizona and Texas where chemical handling labor costs drive conversion preference. Target entry-level portable spa configurations in cold-climate Canadian provinces where indoor installation extends usable seasons beyond pool feasibility. Pursue direct-to-contractor distribution bypassing established dealer networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated fiberglass manufacturers with captive gelcoat operations in the southeastern United States. Long-term viability rests on positioning ahead of low-GWP refrigerant transition deadlines compressing heat pump heater availability. Monitor EPA SNAP enforcement timelines as inflection indicator for equipment procurement pattern shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gelcoat Application | Captive supply of factory-controlled shell quality reduces on-site curing variability for fiberglass producers. |
| Salt-Chlorine Generation Retrofit Program | Conversion targeting in Texas and Arizona reduces chemical handling labor and extends service contract attachment. |
| Low-GWP Heat Pump Heater Redesign | R32 and CO2 alternative positioning ahead of EPA SNAP phase-down deadlines secures equipment availability. |
| Dealer Network Densification in Coastal California | Localized service coverage captures premium positioning in high-property-value corridors with turnkey bundling. |
| Welded Seam Vinyl Technology Transition | Thermally bonded thicker gauge materials displace traditional overlap liners in southeastern manufacturing capacity. |
Research Methodology
Multi-period observation of permit filing velocity, equipment shipment data, and sanitizer chemical pricing anchored the trend analysis, supplemented by interviews with fiberglass plant managers, pool contractor operations heads, municipal building inspectors, and dealer network principals. Secondary validation drew from EPA Energy Star certification databases, ANSI/APSP standards documentation, state-level barrier fence ordinance compilations, and customs records of vinyl resin imports. Bottom-up project pipeline aggregation and top-down macroeconomic factor weighting provided triangulation across estimation approaches.
Input-output matrices mapped fiberglass shell production capacity, motor replacement cycle timing, and regional permit approval rates against residential construction spend and property value indices across the analysis window. Segmentation modeling captured product type, material, installation permanence, and service attachment dimensions. CAGRs derived from regression-weighted historical trajectory projection with scenario-adjusted regulatory compliance cost overlays. Industry-specific forecast inputs included EPA refrigerant phase-down schedules and F-Gas Regulation enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chlorine feedstock availability, gelcoat technician training pipeline output, and municipal barrier ordinance harmonization. Assumptions reflect current regulatory trajectories and installed base replacement cycle patterns. Material deviation in EPA enforcement intensity or chemical supply chain disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Kids Scooter Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Kayak Accessories Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
Portable Kayaks Market