
 Aquatic Fins Market | 2026-2036
Aquatic Fins Market Size, Share, and Industry Trends Forecast 2026-2036
Aquatic Fins Market Analytics
Silicone is broadening its share against natural rubber in mid-range aquatic fins, cutting unit costs while improving chlorine resistance and color stability. Speedo USA leverages vertical integration across Asian manufacturing partnerships to sustain margin control on competitive swim lines. Cressi anchors its position in European dive shops through specialized distribution of full-foot and open-heel configurations. FINIS Inc differentiates via R&D intensity in competitive swimming, where hydrodynamic blade designs command premium positioning.
Aquatic fins are propulsion devices worn on the feet to amplify thrust and maneuverability during submerged or surface water activities, typically molded from rubber, thermoplastic elastomers, or silicone compounds with stiffness gradients calibrated to stroke mechanics and depth ratings. Dive fins lead value contribution due to higher material volumes and technical certification requirements, while silicone swim fins represent the fastest-growing material-product intersection as competitive programs upgrade from basic rubber models. Recreational swimming occupies the largest volume tier though professional diving captures disproportionate margin pools through specialized channel access and replacement part cycles.
REACH in Europe restricts phthalate content in thermoplastic formulations, pushing manufacturers toward medical-grade silicone alternatives that satisfy both ECHA migration limits and extended saltwater exposure standards. China's GB standards and NMPA oversight for diving equipment imports create dual compliance burdens for brands sourcing across multiple Asian production bases. The US Consumer Product Safety Commission maintains recall authority over fin strap and blade separation failures, shaping warranty and liability structures for distributors. Stakeholders must monitor how diver certification agencies revise equipment standards, as these private protocols often pre-empt regulatory action and redirect procurement specifications before formal rulemaking completes.
Market Dynamics
REACH migration limits and China's GB standards are bifurcating raw material sourcing, forcing manufacturers to dual-certify silicone formulations or abandon cross-regional product lines entirely.
Growth Catalysts
- Competitive swimming program expansion:North American and Asian athletic federations are standardizing high-performance silicone fins for age-group development pipelines, institutionalizing replacement cycles.
- Medical-grade silicone substitution:ECHA phthalate restrictions under REACH are accelerating thermoplastic-to-silicone conversion in European recreational and competitive channels.
- Coastal tourism infrastructure investment:Australian state governments are bundling lifeguard certification with bulk fin procurement, creating anchored institutional demand.
Market Restraints
- Petrochemical input volatility:Silicone precursor costs fluctuate with methanol and silicon metal pricing, compressing margin predictability for mid-range product lines.
- Dual compliance burden:Manufacturers sourcing across Thailand, Vietnam, and China face conflicting GB standards and NMPA oversight requirements for diving equipment imports.
- Natural rubber legacy substitution ceiling:Professional diving segments retain rubber preference for deep-rated blade stiffness, limiting silicone penetration in high-margin categories.
Strategic Opportunities
- Adaptive tourism recovery in Southeast Asia:Indonesia and Philippines dive resort clusters are rebuilding equipment rental fleets, creating white space for certified open-heel configurations.
- EU Green Deal material circularity:Ecodesign requirements are incentivizing recyclable thermoplastic elastomer development for rental and institutional channels.
- Direct-to-consumer channel maturation:Specialized e-commerce platforms are disintermediating dive shop distribution for replacement blades and straps.
Industry Challenges
- Hydrodynamic design talent scarcity:Computational fluid dynamics expertise for competitive swim blade optimization concentrates in a handful of specialized engineering consultancies.
- Diver certification agency standard lag:PADI and SSI equipment protocol revisions often pre-empt formal regulatory action, forcing manufacturers to track multiple private standard drafts simultaneously.
- Supply chain reconfiguration friction:Relocating molding operations from China to Vietnam or Indonesia requires re-qualifying medical-grade silicone suppliers under divergent national pharmaceutical oversight frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aquatic Fins Market |
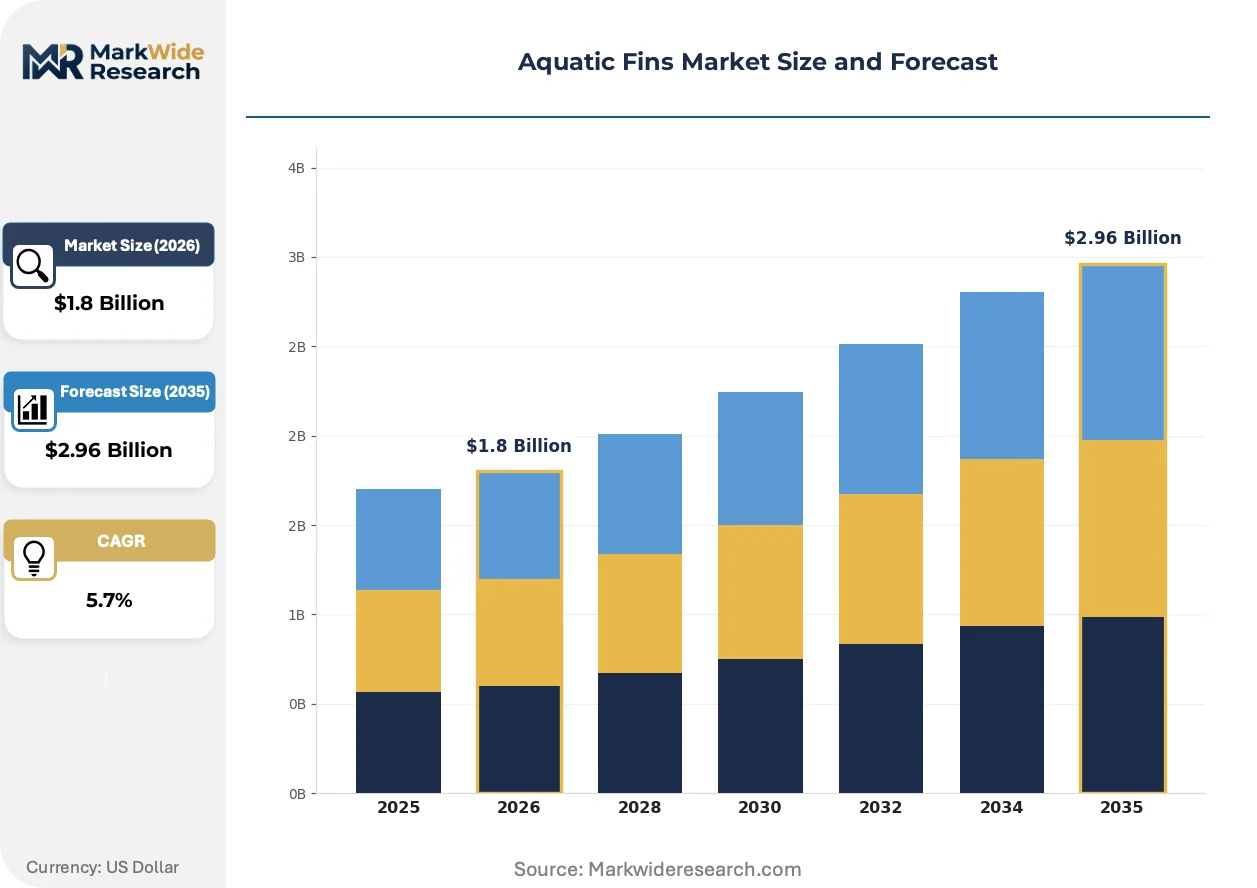
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Swim Fins, Dive Fins, Surf Fins, Bodyboard Fins Material: Rubber, Thermoplastic, Silicone, Plastic Application: Recreational Swimming, Professional Diving, Competitive Swimming, Water Sports Size: Small, Medium, Large, Extra Large |
| Companies Covered | Speedo USA, Cressi, FINIS Inc, Aqua Lung International, TYR Sport Inc, Arena, Mares, Beuchat, IST Sports Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aquatic Fins Market Evolving Landscape
Material science convergence and procurement digitization are compressing product development cycles while fragmenting traditional distribution hierarchies across recreational and professional channels.
Computer-aided blade topology optimization is unifying stiffness gradient engineering with mass-customization capabilities. Competitive swimming programs in Australia and the United States are adopting athlete-specific molded fin geometries at accelerating cadence. This technology is unifying performance differentiation with reduced inventory SKU complexity for institutional buyers.
ECHA's evolving REACH Annex XVII restrictions on phthalate plasticizers are redirecting thermoplastic compound R&D toward medical-grade silicone alternatives. Formulation houses serving European dive equipment manufacturers are retiring legacy PVC-based recipes ahead of enforcement deadlines. Dive fin value chains serving EU markets are absorbing reformulation costs through selective premium positioning rather than economy-tier volume plays.
Certification-driven procurement consolidation is compressing replacement cycles among institutional buyers. Australian surf lifesaving clubs and North American collegiate swimming programs are mandating equipment refresh schedules tied to liability insurance requirements. This pattern is most visible in coastal municipalities where litigation exposure has elevated equipment standardization above cost minimization in vendor selection criteria.
Aquatic Fins Market Segmentation
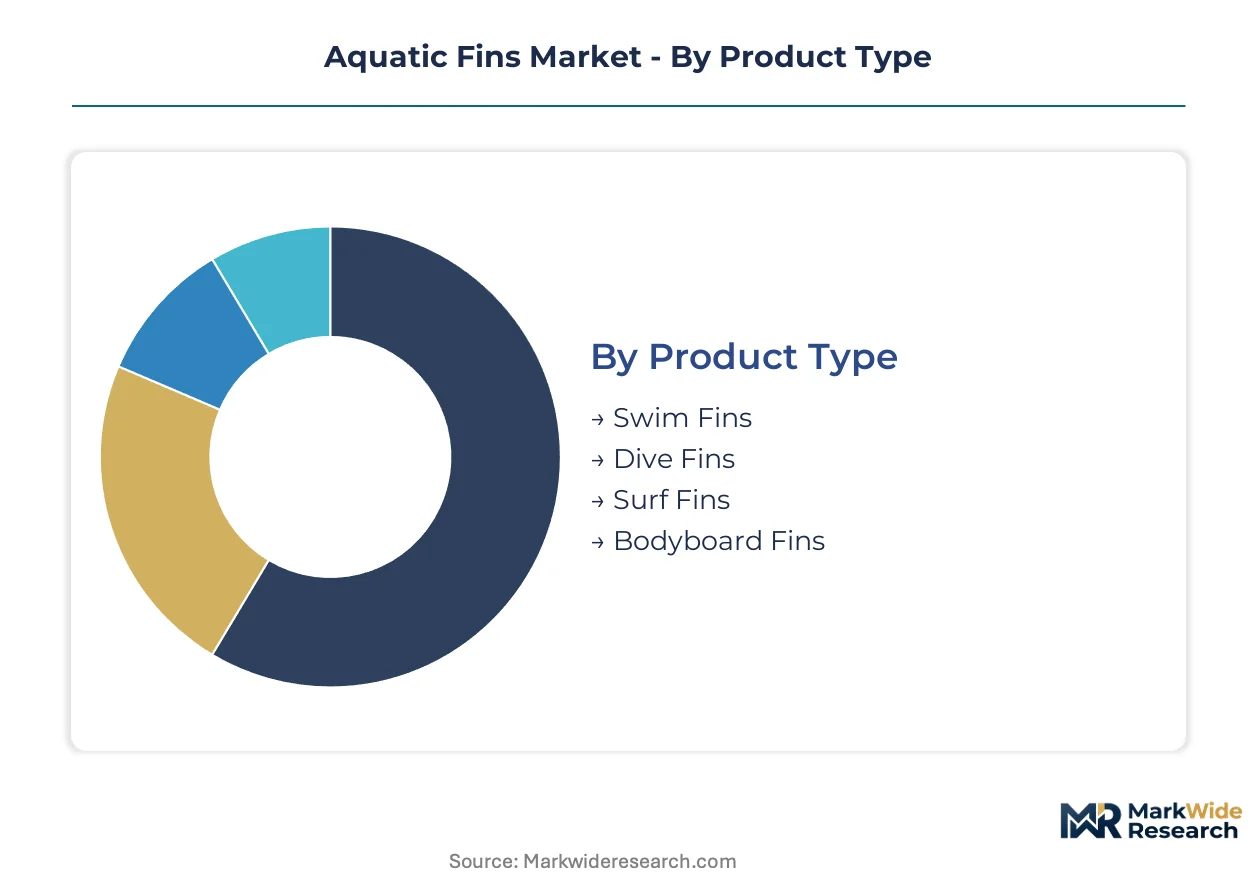
Segmentation in aquatic fins reveals divergent margin structures across material grades and certification tiers. Product architecture and procurement channel access vary sharply between institutional competitive programs and recreational retail.
Product Type:
Standalone propulsion systems dominate professional use, while recreational segments favor embedded compatibility with rental infrastructure and standardized training programs.
- Dive Fins:Open-heel and full-foot configurations engineered for depth-rated stiffness gradients and extended saltwater exposure. Demand concentrates in Australian coastal municipalities and Indonesian resort clusters, where PADI certification protocols mandate equipment refresh cycles tied to liability coverage.
- Swim Fins:Short-blade silicone designs calibrated to competitive stroke mechanics, with hydrodynamic optimization for flutter and dolphin kicks. North American and Asian athletic federations are institutionalizing procurement through age-group development pipelines, standardizing replacement intervals.
- Surf Fins:Removable and fixed configurations for board propulsion, with stiffness profiles matched to wave conditions and rider weight.
- Bodyboard Fins:Compact asymmetric designs prioritizing maneuverability in shore-break conditions, with tether systems for wave impact retention.
Volume placements concentrate in Swim Fins; the faster expansion belongs to Dive Fins.
Material:
Cost tier stratification separates medical-grade formulations from commodity compounds, with certification requirements driving substitution patterns.
- Silicone:Medical-grade formulations displacing thermoplastic alternatives under ECHA REACH phthalate restrictions. European recreational channels and competitive swimming programs are absorbing premium positioning to satisfy migration limits and extended chlorine exposure standards.
- Rubber:Natural and synthetic compounds retaining preference in deep-rated dive applications for blade stiffness and cold-water flexibility. Professional diving segments in Australia and Southeast Asia maintain rubber specifications for technical certification compliance.
- Thermoplastic:TPU and TPE compounds facing reformulation pressure from Ecodesign circularity requirements in EU rental channels.
- Plastic:Commodity polypropylene and PVC formulations concentrated in entry-level recreational segments with shorter replacement cycles.
Procurement volume sits with Rubber; Silicone climbs the fastest on regulatory substitution.
Application:
Customer type fragmentation separates institutional buyers with mandated refresh schedules from discretionary retail purchasers.
- Recreational Swimming:Largest volume tier encompassing casual pool use and beach entry, with procurement through mass retail and seasonal rental operations. Australian surf lifesaving clubs bundle lifeguard certification with bulk fin orders, creating anchored institutional demand.
- Professional Diving:Technical and commercial diving applications requiring depth certification and replacement part availability. Specialized distribution through dive shops captures disproportionate margin pools despite lower unit volumes.
- Competitive Swimming:Age-group through elite performance tiers with federation-standardized equipment specifications.
- Water Sports:Surfing, bodyboarding, and paddle-sport applications with board-specific compatibility requirements.
Recreational Swimming holds volume concentration; Professional Diving gains share fastest on certification-driven replacement.
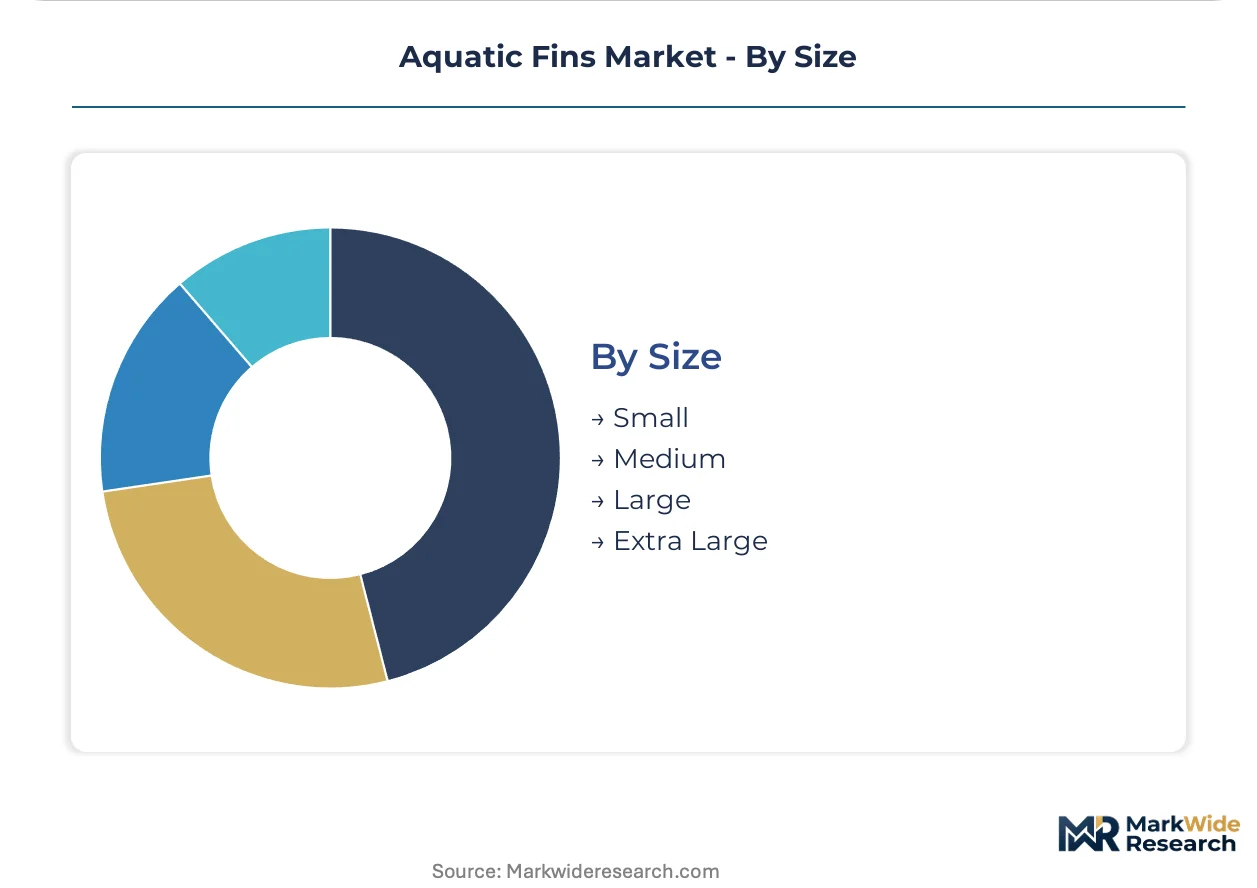
Size:
Volume distribution follows demographic concentration in core adult segments, with institutional procurement standardizing on medium and large configurations.
- Medium:Core adult demographic coverage for institutional procurement in North American collegiate programs and Australian lifeguard certification.
- Large:Adult male concentration in dive applications, with open-heel adjustability accommodating boot integration.
- Small:Youth competitive swimming and junior dive certification markets.
- Extra Large:Niche coverage for specialized commercial diving and adaptive equipment requirements.
Medium and Large dominate volume placements; Small shows steepest expansion trajectory on youth program development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Australia, where coastal tourism infrastructure and professional lifeguard certification programs sustain bulk institutional orders for dive and swim fins.
Australia
Surf lifesaving clubs and state-level lifeguard certification programs generate anchored institutional procurement volumes. The country's national pharmaceutical regulator oversees medical-grade silicone imports for competitive swimming equipment. Queensland and New South Wales coastal municipalities bundle equipment refresh schedules with liability insurance requirements.
United States
North American collegiate swimming programs and age-group athletic federations standardize high-performance silicone fin procurement. The US Consumer Product Safety Commission maintains recall authority over fin strap and blade separation failures. California and Florida coastal clusters drive replacement blade demand through year-round aquatic training facilities.
China
GB standards and NMPA oversight for diving equipment imports create compliance burdens for manufacturers sourcing across multiple Asian production bases. The country's dual carbon goals pressure petrochemical-intensive thermoplastic formulations. Yangtze River Delta molding operations face re-qualification requirements under divergent pharmaceutical oversight frameworks.
Germany
ECHA REACH Annex XVII phthalate restrictions accelerate thermoplastic-to-silicone conversion in recreational channels. The EU Green Deal Ecodesign requirements incentivize recyclable thermoplastic elastomer development for rental fleets. Bavaria and Baden-Württemberg serve as formulation house clusters retiring legacy PVC-based recipes.
Indonesia
Dive resort clusters in Bali and Lombok are rebuilding equipment rental fleets following tourism recovery patterns. The country's national pharmaceutical regulator oversees import certification for diving equipment. Open-heel configuration demand concentrates in the Komodo and Raja Ampat live-aboard operator networks.
Aquatic Fins Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reconfigure molding operations across Vietnam and Indonesia to escape dual compliance burdens. The vendor base separates into three tiers: multinational sporting goods conglomerates with captive silicone supply, European dive equipment specialists with certified distribution networks, and Asian contract manufacturers serving private-label programs. Strategic archetypes include vertically integrated performance brands, certification-heavy dive specialists, and volume-focused recreational suppliers. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players adding regional warehousing to bypass import certification delays.
Among US-based sporting goods operators, Speedo USA exemplifies the vertically integrated archetype through Asian manufacturing partnerships. Cressi anchors the European specialist tier with full-foot and open-heel distribution through dive shop networks. FINIS Inc occupies a position within the R&D-intensive competitive swimming segment where hydrodynamic blade development commands premium positioning.
| Leading Market Players |
|---|
| Speedo USA |
| Cressi |
| FINIS Inc |
| Aqua Lung International |
| TYR Sport Inc |
| Arena |
| Mares |
| Beuchat |
| IST Sports Corp |
| Others |
Value Network & Pricing Analysis
Computational fluid dynamics talent concentration in Bavaria and Baden-Württemberg feeds labor-cost differentials that widen pricing-tier spreads between mass-market recreational fins and athlete-molded competitive geometries. Silicone precursor volatility from methanol and silicon metal pricing compresses margin predictability for mid-range product lines while premium hydrodynamic designs absorb reformulation costs through selective positioning.
Pricing Analysis
Volume placements concentrate in recreational rubber fins while disproportionate margin pools sit with professional diving configurations. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade silicone certified under ECHA REACH from commodity thermoplastic alternatives. Price differentiation hinges on certification grade and volume scale, with institutional buyers in Australian surf lifesaving clubs showing lowest sensitivity due to liability insurance bundling. Cost compression in mid-range swim fins is intensifying because petrochemical input volatility outpaces brand premium capture.
Supply Chain Analysis
Certification/qualification gating through divergent pharmaceutical oversight frameworks fragments molding operations across Thailand, Vietnam, and Indonesia. Medical-grade silicone supply draws from Yangtze River Delta formulation houses and Bavaria-based compounders, with raw material dependencies on silicon metal, methanol, and specialized thermoplastic elastomers. Single-source vulnerability concentrates in ECHA-compliant silicone precursor supply serving European recreational channels. Distribution runs through dive shop networks for professional configurations and direct-to-consumer platforms for replacement blades and straps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone formulation capacity constraints prop pricing power for certified suppliers, as ECHA REACH enforcement deadlines outstrip qualified compounder expansion across European and Asian production bases.
For Market Incumbents: Lock in captive silicone supply through backward integration into Yangtze River Delta or Bavaria formulation clusters before ECHA migration limits tighten further. Deepen channel control in Australian institutional procurement by bundling equipment refresh schedules with liability insurance requirements, defending against direct-to-consumer disintermediation in replacement part cycles. For New Entrants and Emerging Players: Begin with Indonesian dive resort cluster recovery, where open-heel configuration demand concentrates in Komodo and Raja Ampat live-aboard networks lacking certified local supply. Target Southeast Asian rental fleet rebuilding through NMPA-compliant manufacturing partnerships, leveraging white space in certified equipment procurement left by incumbents prioritizing European compliance burdens. For Investors and Strategic Acquirers: Re-rating potential sits with R&D-intensive competitive swimming specialists given institutional procurement standardization across North American collegiate programs and Asian athletic federations. Long-term viability favors acquisition targets with captive hydrodynamic design capabilities and established PADI/SSI certification agency relationships. The signal to watch is diver certification agency protocol revision timing, as private standard drafts often pre-empt formal regulatory action and redirect procurement specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Formulation | Captures margin from ECHA REACH-compliant medical-grade compound supply serving European recreational channels. |
| Australian Institutional Procurement Bundling | Locks replacement cycle revenue through surf lifesaving club equipment refresh mandates tied to liability coverage. |
| Indonesian Dive Resort Fleet Certification | Secures first-mover position in Komodo and Raja Ampat live-aboard operator networks rebuilding post-tourism recovery. |
| Direct-to-Consumer Replacement Platform | Disintermediates dive shop distribution for blades and straps in North American year-round training facility clusters. |
| Hydrodynamic Design Talent Acquisition | Consolidates scarce computational fluid dynamics expertise for athlete-molded fin geometry development in competitive swimming. |
Research Methodology
Document review covered customs and trade data, SEC filings from sporting goods conglomerates, ECHA REACH enforcement documentation, and PADI/SSI certification protocol archives, complemented by interviews with dive equipment procurement managers, competitive swimming program directors, silicone formulation R&D leads, and institutional buyers at Australian surf lifesaving clubs. Bottom-up triangulation across product-level volume estimates and top-down validation against aggregate trade flows anchored market sizing.
Segment-level outputs across material grade, product architecture, certification tier, and regional regulatory cluster were generated through the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating petrochemical input cost trajectories and institutional procurement cycle standardization. Industry-specific forecast inputs included ECHA Annex XVII enforcement phase-in schedules and diver certification agency equipment protocol revision timelines.
Underlying measurement precision varies by segment; medical-grade silicone substitution rates in European recreational channels carry tighter precision than emerging market rental fleet recovery trajectories. Forecasts reflect assumptions around regulatory enforcement timing and tourism infrastructure investment cadence. A model refresh is warranted upon material change in ECHA migration limit amendments or PADI/SSI equipment standard pre-emption patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Mexico Fishing Reels Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Fishing Reels Market
Outdoor & Sports
Global Canoe and Kayak Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Artificial Turf Market
Outdoor & Sports
Lawn Roller Market
Outdoor & Sports
Global Sailing Dinghy Masts Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Global Paintball Equipment Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Global Artificial Grass Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
North America Fire Pits Market
Outdoor & Sports
Fish Hunting Equipment Market