
 Australia Horse Riding Equipment Market | 2026-2036
Australia Horse Riding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Horse Riding Equipment Market Insights
Buyer fragmentation across amateur riders and boutique equestrian centers is recalibrating procurement patterns throughout the supply chain. Ariat International leverages its heritage boot craftsmanship to anchor premium positioning in rural Victoria. Pikeur sustains dominance through specialized competition apparel with exacting German tailoring standards. Decathlon S.A. competes on accessible price points while extending broad retail coverage across Australian suburbs.
Horse riding equipment encompasses protective headgear, saddlery, footwear, and apparel engineered to ASTM F1163 or EN 1384 impact standards, with leather and synthetic polymer construction designed to manage rider safety and equine control during training or competition. Saddles and helmets capture the deepest margin pools due to certification requirements and replacement cycles tied to wear patterns. Synthetic materials represent the fastest-growing material segment as riders seek weather-resistant alternatives to traditional leather across Queensland's humid coastal circuits. Specialty stores retain channel leadership for fitting services, though online retail accelerates among price-sensitive amateurs purchasing standardized sizes.
Standards Australia governs AS/NZS 3838 for equestrian headgear, while the Australian Competition and Consumer Commission enforces product safety recalls that shape manufacturer liability exposure. Biosecurity regulations under the Department of Agriculture, Fisheries and Forestry constrain leather sourcing and cross-state equipment movement following equine influenza protocols. Stakeholders must monitor evolving helmet certification harmonization between Australian and European standards to anticipate redesign costs and inventory transitions.
Market Dynamics
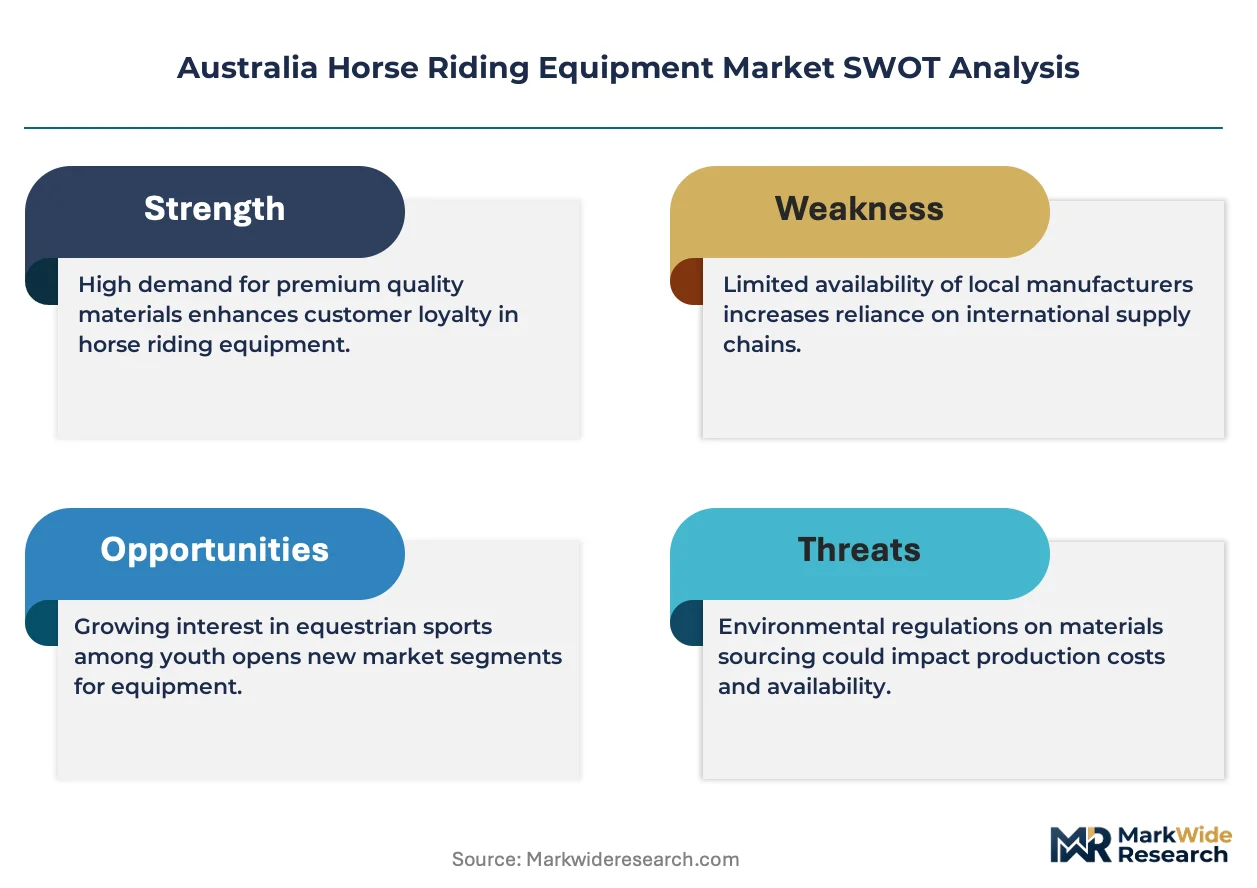
Standards Australia's AS/NZS 3838 revision is compressing design cycles for equestrian headgear manufacturers while elevating certification costs across the supply chain. This regulatory pressure is reshaping procurement relationships between importers and domestic testing facilities.
Growth Catalysts
- Biosecurity compliance infrastructure:The Department of Agriculture, Fisheries and Forestry's post-equine influenza protocols have created permanent demand for traceable leather sourcing and documented equipment sterilization, favoring suppliers with integrated quality systems.
- Professional competitor density:Sydney's elite training precincts in New South Wales generate concentrated demand for certified competition-grade helmets and saddlery, pulling premium inventory toward coastal metropolitan clusters.
- Synthetic polymer R&D:Advances in weather-resistant polymer composites are enabling year-round training schedules across Queensland's humid coastal circuits, reducing leather maintenance burdens for amateur riders.
Market Restraints
- Leather input volatility:Australian tannery capacity constraints and biosecurity documentation requirements inflate raw material costs for traditional saddlery, compressing margins for mid-tier manufacturers dependent on full-grain construction.
- Testing facility concentration:Helmet certification capacity concentrates in Melbourne and Sydney, creating geographic bottlenecks for interstate manufacturers seeking AS/NZS 3838 compliance.
- Substitution pressure from recreational motorsports:Adventure tourism operators in regional Victoria are diverting discretionary spending toward ATV and motorcycle experiences, fragmenting rural equestrian participation rates.
Strategic Opportunities
- Western Australia underpenetration:Perth's isolated equestrian community lacks dedicated premium retail infrastructure, creating white space for specialty store expansion with integrated fitting services.
- Online channel infrastructure:Standardized sizing for synthetic riding boots is enabling direct-to-consumer fulfillment, bypassing specialty store markups for price-sensitive amateurs in suburban Adelaide.
- Helmet certification harmonization:Anticipated alignment between AS/NZS 3838 and EN 1384 standards would reduce redesign costs for European manufacturers, expanding import competition into the Australian market.
Industry Challenges
- Master saddler skill scarcity:Traditional leather craftsmanship training programs have contracted, limiting custom saddle production capacity for competitive riders requiring precision fitting.
- Certification timeline compression:Revised AS/NZS 3838 testing protocols extend approval cycles, straining working capital for small-batch helmet manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Horse Riding Equipment Market |
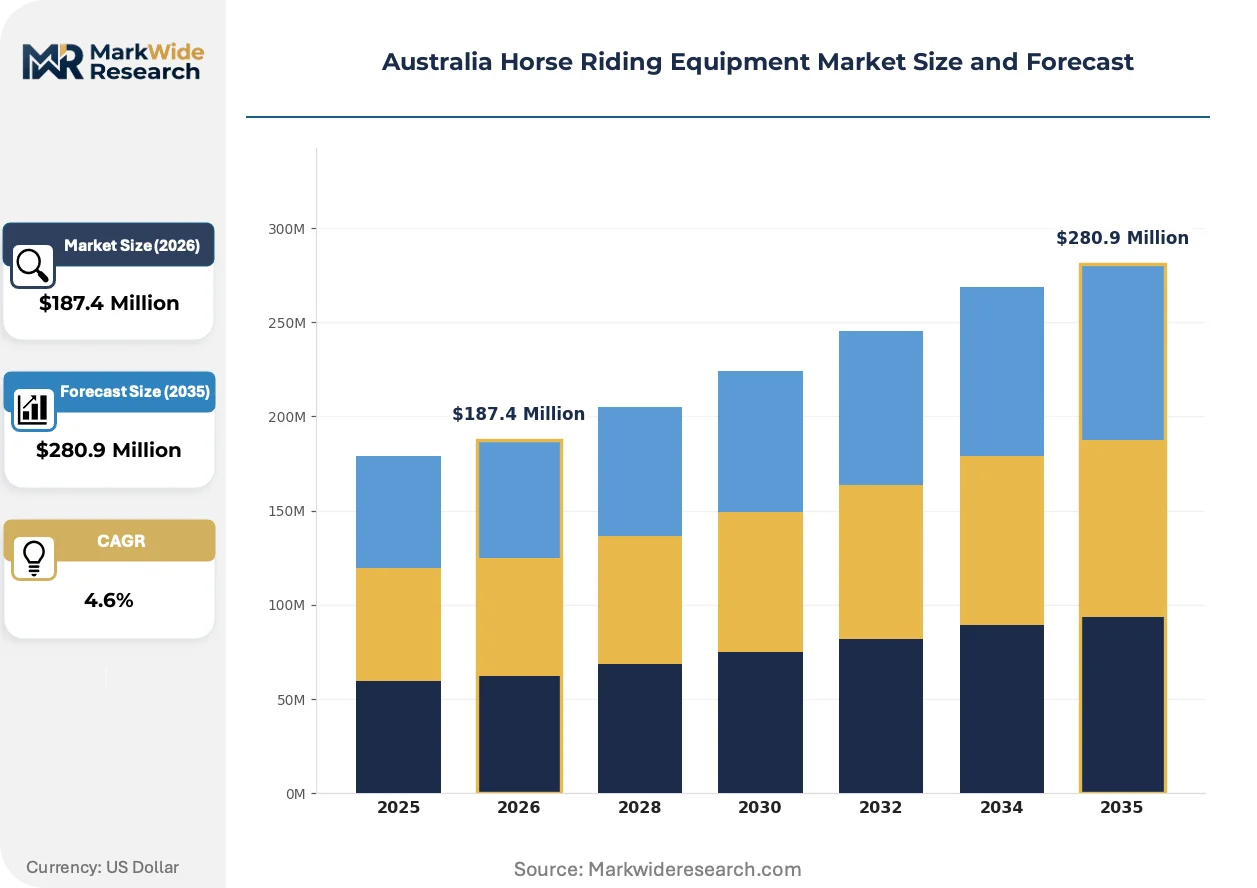
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saddles, Bridles, Helmets, Boots End User: Amateurs, Professionals, Trainers, Equestrian Centers Material: Leather, Synthetic, Rubber, Fabric Distribution Channel: Online Retail, Specialty Stores, Trade Shows, Direct Sales |
| Companies Covered | Horseware Ireland, Pikeur, Ariat International, Inc., HKM Sports Equipment GmbH, Mountain Horse International AB, Decathlon S.A., Shires Equestrian, Dover Saddlery, Dainese S.p.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Horse Riding Equipment Market Trends and Innovations
Material science advances and regulatory tightening are converging to reshape product development priorities across Australian equestrian equipment. Manufacturers are repositioning around durability claims and compliance speed rather than heritage branding alone.
Advanced synthetic polymer blends with moisture-wicking and UV-stabilized properties are expanding into helmet shell construction and boot uppers. Amateur riders in Queensland's tropical climate zones are adopting these materials at accelerating rates to reduce replacement frequency. This shift is expanding into margin structures previously captured by premium leather suppliers, forcing tanneries to differentiate through customization rather than baseline performance.
The Australian Competition and Consumer Commission's enhanced product safety recall authority is elevating manufacturer liability exposure for headgear failures. Importers now face mandatory incident reporting and accelerated market withdrawal timelines. Competition-grade helmet suppliers are responding by integrating Australian testing into early design phases rather than treating certification as a final-stage formality.
Specialty store channel dominance is eroding as suburban amateurs consolidate purchases through general sporting goods retailers with extended size ranges. Decathlon's broad suburban coverage is capturing standardized apparel and entry-level protective gear previously sold through equestrian-exclusive outlets. This behavioral shift is most visible in Melbourne's outer metropolitan zones where dedicated riding facilities are sparse and convenience purchasing overrides fitting service preferences.
Australia Horse Riding Equipment Market Segmentation
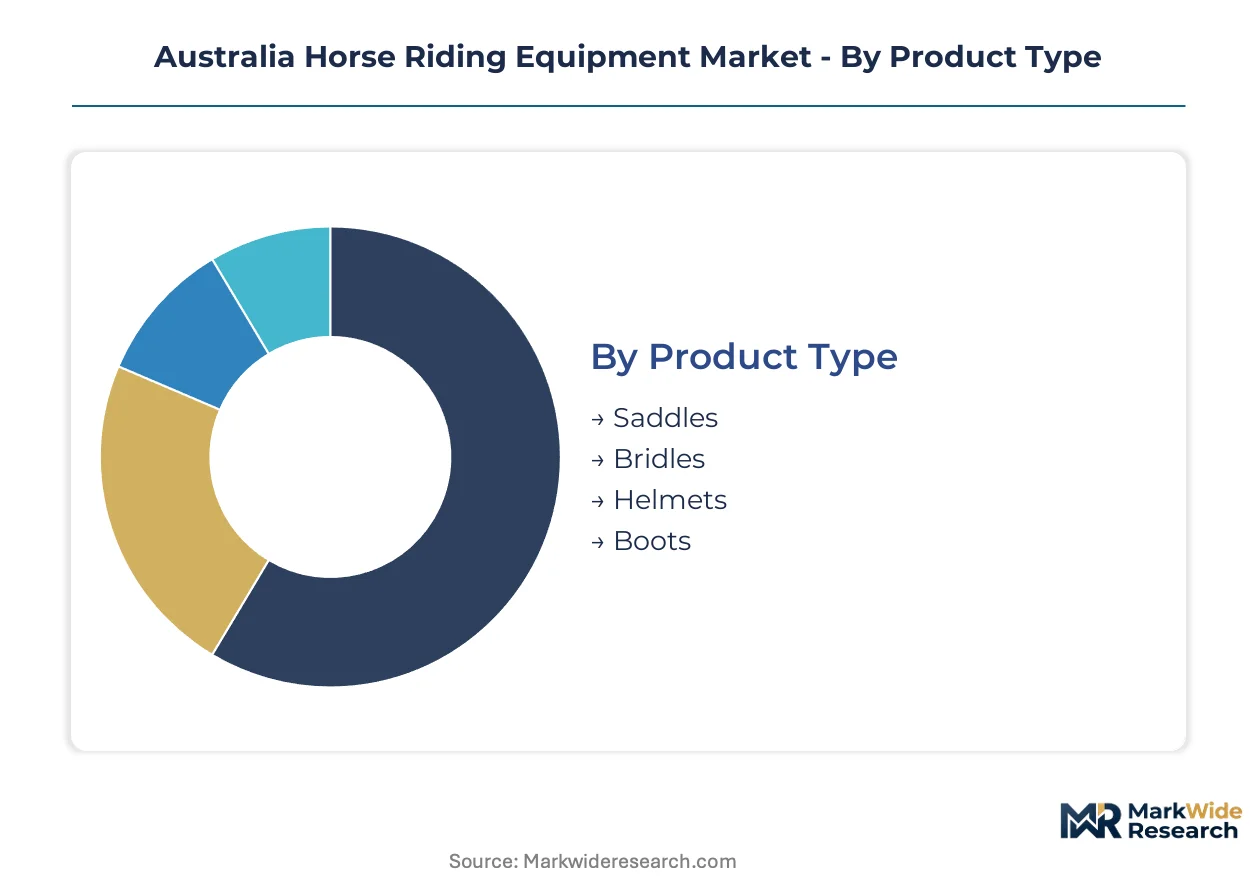
Procurement patterns across Australian equestrian equipment diverge sharply between competitive riders seeking certified performance gear and suburban amateurs prioritizing accessibility. Understanding these fault lines enables suppliers to align inventory, certification investment, and channel presence with distinct buyer economics.
Product Type:
Buyers segment first by safety-critical versus performance-enhancing equipment, with certification requirements and replacement cycles driving divergent margin structures.
- Saddles:Custom-fitted leather or synthetic seats engineered for rider weight distribution and equine biomechanics. Sydney's elite training precincts pull premium inventory toward New South Wales, where competitive riders demand precision fitting from master saddlers whose training programs have contracted nationally.
- Helmets:Impact-resistant headgear constructed to AS/NZS 3838 standards with ABS or polycarbonate shells and energy-absorbing liners. Certification bottlenecks in Melbourne and Sydney testing facilities constrain supply for interstate manufacturers, compressing availability during peak competition seasons.
- Bridles:Leather or biothane headstalls with bit attachments for directional control.
- Boots:Tall leather or synthetic polymer riding footwear with reinforced toe caps and heel counters.
Volume sits with saddles and helmets; growth tilts toward synthetic-construction alternatives in Queensland's humid coastal circuits.
End User:
Skill level determines price sensitivity, fitting service requirements, and brand loyalty intensity across the customer base.
- Professionals:Competition-grade athletes requiring certified helmets, custom saddlery, and apparel meeting exacting tailoring standards. These riders concentrate in New South Wales and Victoria, generating concentrated demand that pulls premium inventory toward coastal metropolitan clusters.
- Amateurs:Recreational riders purchasing standardized sizes through suburban retail channels. Decathlon's broad coverage across Australian suburbs captures this segment with accessible price points, displacing specialty store relationships in Melbourne's outer metropolitan zones.
- Trainers:Instruction professionals sourcing durable equipment for high-frequency daily use across multiple mounts.
- Equestrian Centers:Commercial operations procuring bulk inventory with biosecurity documentation for cross-state equipment movement.
Revenue concentrates with professionals; amateur participation is expanding most quickly through online channel migration.
Material:
Climate exposure and maintenance burden reshape material selection, particularly across Queensland's tropical training environments.
- Synthetic:Weather-resistant polymer composites with UV stabilization and moisture-wicking properties for helmet shells and boot uppers. Queensland's humid coastal circuits drive accelerating adoption as riders seek year-round training schedules without leather degradation.
- Leather:Full-grain or top-grain hides requiring conditioned maintenance, constrained by Australian tannery capacity and biosecurity documentation under Department of Agriculture protocols. Traditional construction retains preference among competitive riders for customization and heritage performance claims.
- Rubber:Molded compounds for grip surfaces and weather sealing in boot soles and rein coatings.
- Fabric:Technical textiles for breeches, gloves, and protective layers with stretch and breathability engineering.
Margins remain deepest in leather; synthetic materials are gaining share fastest through amateur adoption and reduced replacement frequency.
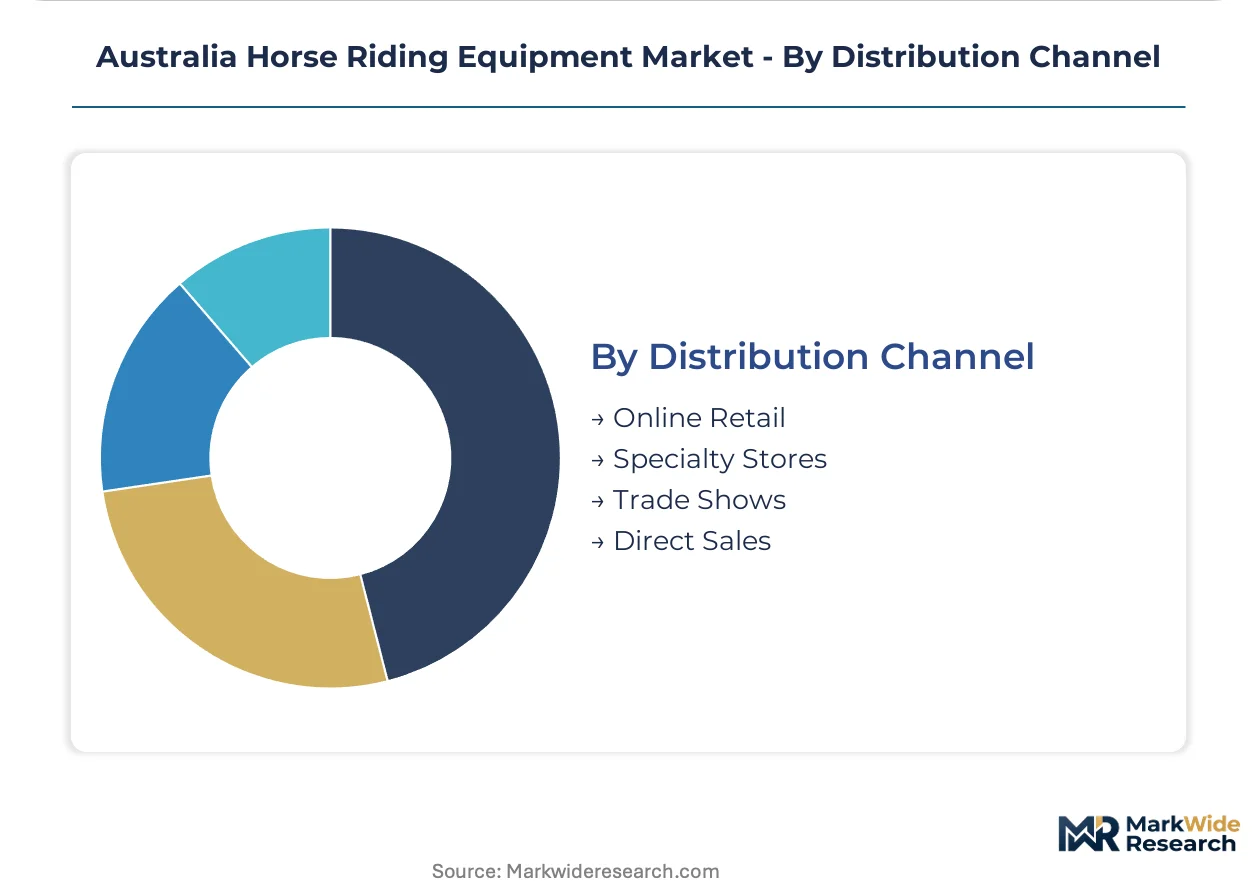
Distribution Channel:
Channel selection balances fitting precision against convenience and price transparency, with geography determining viable options.
- Specialty Stores:Equestrian-exclusive retailers providing custom fitting services, particularly for saddles and helmets requiring precise measurement. These outlets retain leadership in competitive rider segments but erode in suburban zones where dedicated facilities are sparse.
- Online Retail:Direct-to-consumer platforms capturing standardized apparel and entry-level protective gear, accelerating among price-sensitive amateurs in suburban Adelaide where standardized sizing enables fulfillment without fitting overhead.
- Trade Shows:Seasonal exhibition channels for bulk procurement by equestrian centers and professional stables.
- Direct Sales:Manufacturer-controlled relationships with elite training facilities and competitive teams.
Transaction volume flows through specialty stores; online retail is climbing the fastest through suburban amateur consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional competitor density concentrates demand along Australia's eastern seaboard, with New South Wales and Victoria generating the majority of certified equipment procurement. Metropolitan training clusters pull premium inventory toward coastal cities while regional markets exhibit fragmented purchasing patterns.
New South Wales
Sydney's elite training precincts generate concentrated demand for AS/NZS 3838 certified helmets and custom saddlery from master saddlers. Standards Australia's headquarters in Sydney accelerates regulatory consultation access for local manufacturers. The Hawkesbury region hosts dense competition stables that sustain year-round premium equipment turnover.
Victoria
Rural Victoria maintains heritage leather craftsmanship traditions that anchor Ariat International's premium boot positioning. Melbourne testing facilities concentrate AS/NZS 3838 certification capacity, creating geographic bottlenecks for interstate suppliers. The Mornington Peninsula equestrian corridor sustains specialty store relationships through integrated fitting services.
Queensland
Humid coastal circuits drive accelerating synthetic polymer adoption for weather-resistant helmet shells and boot construction. Biosecurity documentation requirements under Department of Agriculture protocols constrain cross-state leather equipment movement. The Gold Coast hinterland training facilities generate replacement demand for moisture-wicking technical apparel.
Western Australia
Perth's isolated equestrian community lacks dedicated premium retail infrastructure, creating white space for specialty store expansion. The state's distance from eastern certification facilities extends compliance timelines for helmet manufacturers. Regional amateur riders in the Swan Valley corridor consolidate purchases through general sporting goods retailers.
South Australia
Suburban Adelaide amateurs migrate toward online retail channels for standardized synthetic boot sizing, bypassing specialty markups. The Adelaide Hills competition circuit sustains modest demand for certified competition-grade helmets. Local retailers face margin compression from Melbourne-based distributors with scale advantages.
Australia Horse Riding Equipment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue synthetic material specialization and direct-to-consumer fulfillment. The market exhibits moderate concentration with heritage European brands commanding premium positioning while mass retailers capture suburban amateur volume. Three archetypes dominate: heritage craftsmanship specialists, synthetic technology innovators, and broad-coverage sporting goods retailers. Competitive moves center on certification speed advantages and biosecurity-compliant supply chain documentation.
Within the heritage tier, Pikeur and Ariat International exemplify premium positioning through specialized competition apparel and boot craftsmanship respectively. Mountain Horse International AB occupies a position bridging technical performance with Scandinavian design heritage. Decathlon S.A. anchors the accessible-price vector, capturing standardized equipment demand across Australian suburbs through broad retail coverage. These three players represent divergent strategic bets on certification investment, material science, and channel convenience.
| Leading Market Players |
|---|
| Horseware Ireland |
| Pikeur |
| Ariat International, Inc. |
| HKM Sports Equipment GmbH |
| Mountain Horse International AB |
| Decathlon S.A. |
| Shires Equestrian |
| Dover Saddlery |
| Dainese S.p.A |
| Others |
Pricing and Supply Chain Analysis
Biosecurity documentation requirements under the Department of Agriculture, Fisheries and Forestry's post-equine influenza protocols gate both qualified supply and premium-tier pricing access, compressing margins for uncertified leather suppliers while elevating certified equipment premiums. Manufacturers with integrated traceability systems capture pricing power; those without face exclusion from professional procurement channels.
Pricing Analysis
Volume concentrates in standardized synthetic boots and entry-level helmets sold through Decathlon's suburban network, while margins pool in custom-fitted leather saddles and AS/NZS 3838 certified competition headgear. Price differentiation hinges on certification grade and master saddler craftsmanship, with Sydney's elite training precincts paying substantial premiums for precision fitting. Pricing pressure stems from tannery capacity constraints and extended certification timelines, compressing mid-tier manufacturer returns. Amateurs purchasing through online channels exhibit highest price sensitivity; professional competitors in New South Wales and Victoria demonstrate lowest sensitivity due to performance requirements.
Supply Chain Analysis
Full-grain leather supply rests on Australian tanneries constrained by biosecurity documentation and Italian heritage processors serving premium custom saddle demand. Synthetic polymer feedstocks draw from Chinese specialty chemical producers and German engineering resin suppliers, with helmet shell components sourcing from Taiwanese precision molders. Single-source vulnerability concentrates in Melbourne and Sydney testing facilities for AS/NZS 3838 certification, creating geographic chokepoints for interstate manufacturers. Distribution runs through specialty stores with integrated fitting services for competitive riders, while suburban amateurs consolidate through general sporting goods retailers with broad size ranges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia horse riding equipment market functions as a cost-of-compliance story where AS/NZS 3838 certification creates a barrier-to-entry moat, rewarding players with established testing relationships and certified supply chains while marginalizing uncertified competitors.
For Market Incumbents: Extend certification speed advantages by securing dedicated testing slots at Melbourne and Sydney facilities before peak competition seasons, insulating against timeline compression that strains smaller rivals. Deepen backward integration into traceable leather sourcing with biosecurity documentation to defend against tannery capacity constraints and input cost volatility. Channel control through specialty store relationships in Mornington Peninsula and Hawkesbury corridors remains essential for competitive rider retention. For New Entrants and Emerging Players: Anticipated harmonization between AS/NZS 3838 and EN 1384 standards opens a window for European manufacturers with existing European certification to enter without full Australian redesign costs. Target Perth's isolated equestrian community where premium retail infrastructure gaps create white space for specialty store expansion with integrated fitting services. Pursue direct-to-consumer fulfillment for standardized synthetic boots in suburban Adelaide, bypassing specialty markups through precise sizing algorithms. For Investors and Strategic Acquirers: Master saddler apprenticeship program contraction is the leading indicator that custom saddle production capacity will tighten, elevating scarcity value for precision-fitting capabilities. Long-term viability favors vertically integrated players controlling certified supply chains from material sourcing through testing completion. Acquisition targets should demonstrate established AS/NZS 3838 testing relationships and biosecurity-compliant leather documentation. Watch synthetic polymer R&D pipelines as the signal for material substitution acceleration that could reshape margin pools away from traditional tanneries.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Positioning | Securing AS/NZS 3838 testing slots before seasonal peaks captures professional competitor demand in Sydney. |
| Biosecurity-Compliant Sourcing | Integrated traceability systems satisfy Department of Agriculture protocols and unlock premium-tier pricing access. |
| Synthetic Material R&D | UV-stabilized polymer development targets Queensland's humid coastal circuits with reduced maintenance burdens. |
| Direct-to-Consumer Launch | Standardized sizing algorithms enable suburban Adelaide fulfillment without specialty store fitting overhead. |
| Specialty Store Expansion | Perth's retail infrastructure gaps create white space for integrated fitting services in Western Australia. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across equipment manufacturers, master saddlers, equestrian center procurement managers, and specialty store operators. Standards Australia documentation, Australian Competition and Consumer Commission recall databases, and Department of Agriculture biosecurity protocols provided regulatory validation. Bottom-up triangulation across product-level shipment data and top-down reconciliation against aggregate customs trade statistics ensured cross-verified outputs.
Segmentation granularity modeled product type at the equipment category level, material at the construction substrate level, end user at the skill-tier level, and distribution channel at the fulfillment mechanism level across the analysis window. CAGRs derived from regression analysis against historical certification timeline trends, synthetic adoption curves in Queensland, and professional competitor density metrics in New South Wales and Victoria. Forecast inputs incorporated master saddler training program contraction rates and anticipated AS/NZS 3838 harmonization timelines with European standards.
The model assumes a particular technology adoption path; alternative pathways for synthetic polymer substitution would alter the outlook if leather craftsmanship training programs expand or biosecurity documentation requirements relax. Forecasts reflect assumptions regarding certification timeline stability, tannery capacity constraints, and competitive rider concentration patterns. A small set of named triggers—helmet standard harmonization announcements, master saddler apprenticeship program funding changes, and equine disease outbreak protocols—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Garden Solar Lights Market
Outdoor & Sports
Europe Swimming Pools and Spas Market
Outdoor & Sports
Global Slingshot Market
Outdoor & Sports
Hunting Blinds Market
Outdoor & Sports
Australia Kids Scooter Market
Outdoor & Sports
Fishing Tackle Box Market
Outdoor & Sports
Fire Pits Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Freshwater Fishing Rod Market
Outdoor & Sports
Autonomous Golf Caddy Market
Outdoor & Sports
Golf Trolley Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Camping Cookware Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Kids Scooter Market