
 Cold Plunge Pools Market | 2026-2036
Cold Plunge Pools Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Plunge Pools Market Analysis
Stainless steel is consolidating its position as the dominant shell material across premium cold plunge pools, displacing traditional acrylic in commercial installations where durability and thermal conductivity command priority. Plunge leverages direct-to-consumer distribution to sustain brand velocity in the residential segment. Morozko Forge anchors its competitive stance through in-house production of ice-bath systems with integrated filtration. Diamond Spas Inc. specializes in bespoke concrete and stainless-steel configurations for luxury hospitality clients.
A cold plunge pool is a temperature-controlled immersion vessel engineered to maintain water between 3°C and 15°C through mechanical refrigeration or ice-based cooling, designed to trigger vasoconstriction and accelerate post-exercise recovery. Residential installations dominate unit volume, yet commercial wellness centers and spa deployments capture disproportionate margin pools due to specification complexity and service contracts. Above-ground and portable configurations are expanding fastest among urban consumers constrained by installation logistics, while in-ground custom builds retain pricing power in the luxury segment.
The EPA regulates energy consumption standards for water-chilling equipment, compelling manufacturers to redesign compressor systems and insulation packages. In the United States, OSHA guidelines for workplace wellness amenities influence commercial procurement specifications, while ISO standards for recreational water quality shape filtration and sanitation requirements across export markets. Stakeholders must weigh capital allocation between connected automation features and compliance-driven efficiency upgrades as regulatory thresholds tighten.
Market Dynamics
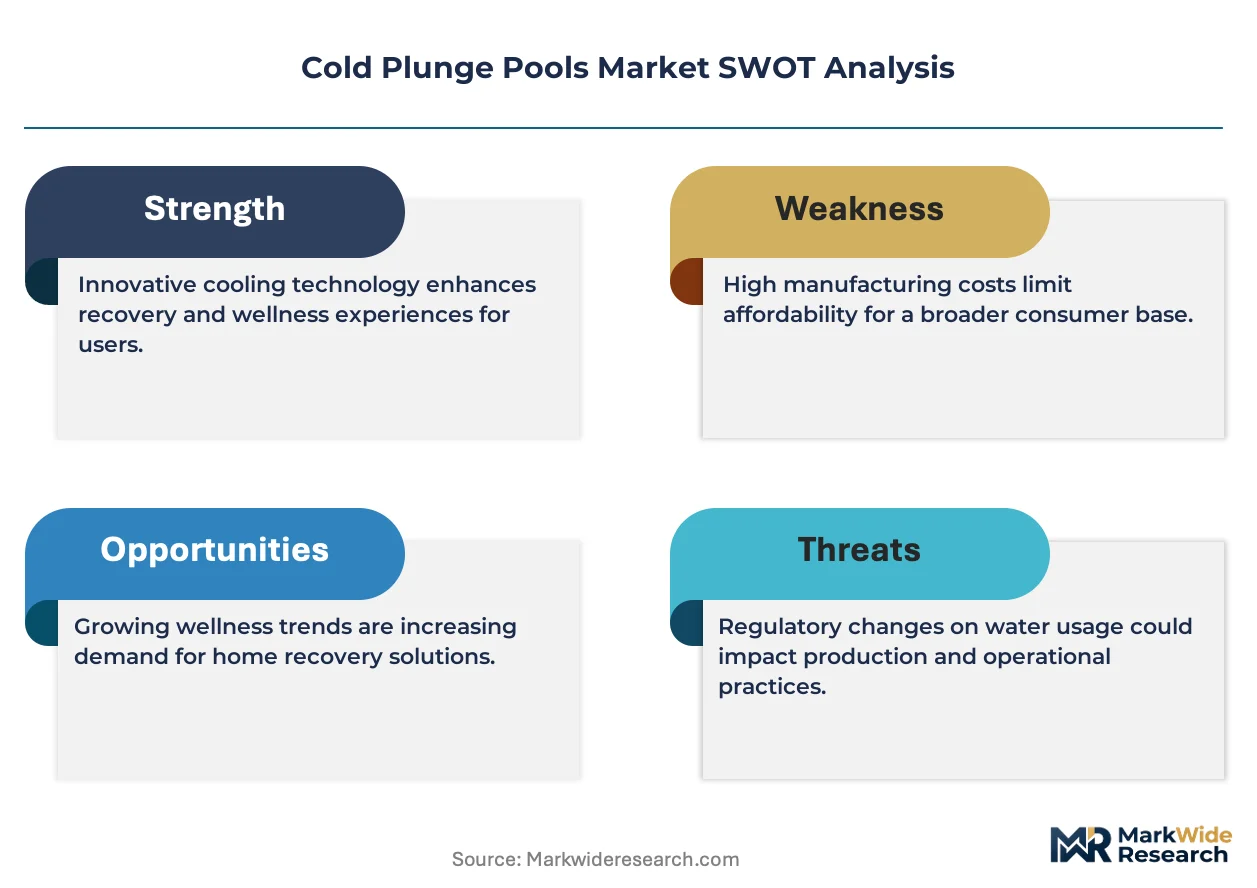
EPA energy-efficiency mandates for water-chilling equipment are forcing manufacturers to redesign compressor architectures and insulation systems, compressing margins for legacy chiller suppliers while rewarding firms with captive R&D capabilities.
Growth Catalysts
- Recovery-focused athletes:Biohacking enthusiasts in boutique fitness studios are driving unit volume expansion across California and Texas wellness corridors.
- OSHA workplace wellness guidelines:Commercial procurement specifications in the United States now prioritize cold plunge amenities, accelerating hospitality and corporate gym deployments.
- Portable configuration innovation:Above-ground and mobile units are resolving installation logistics constraints for urban residential buyers.
Market Restraints
- Compressor supply concentration:Advanced refrigeration components concentrate among Japanese and German industrial suppliers, creating input bottlenecks.
- Copper and aluminum price volatility:Thermal exchange materials expose manufacturers to commodity swings that compress working capital cycles.
- ISO recreational water quality standards:Export-market filtration and sanitation compliance adds certification overhead for mid-tier producers.
Strategic Opportunities
- Connected automation convergence:Integration of IoT sensors with chiller management systems enables remote temperature monitoring and predictive maintenance contracts.
- Service contract unbundling:Commercial wellness centers are separating hardware procurement from ongoing filtration and sanitation service agreements.
- Urban residential density:Apartment and condominium markets in New York and Chicago remain underpenetrated for compact portable units.
Industry Challenges
- Refrigeration technician scarcity:Specialized chiller maintenance skills lag installation growth, extending service response times for commercial clients.
- Legacy HVAC integration complexity:Building management system compatibility issues delay deployment in retrofitted hospitality properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Plunge Pools Market |
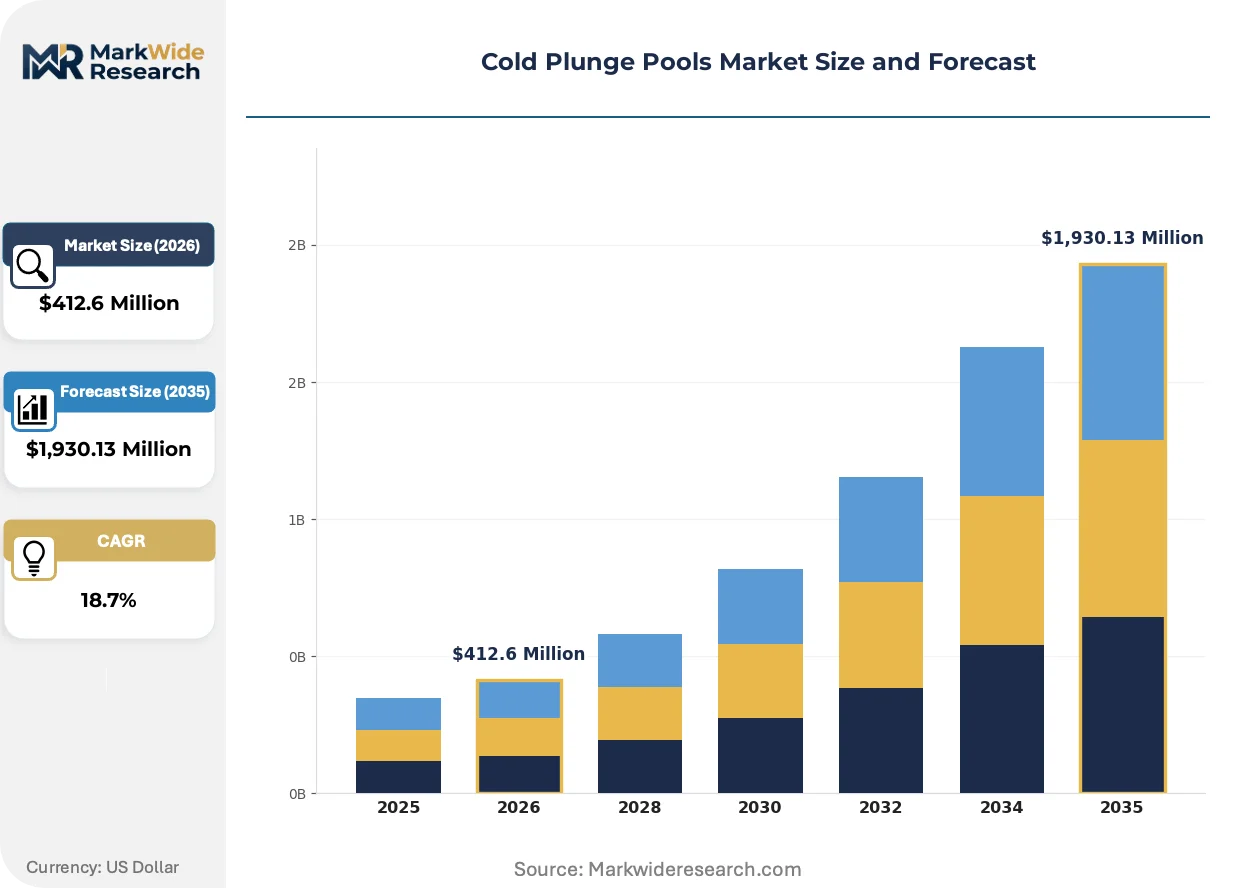
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ground, Above-Ground, Portable, Custom Material: Acrylic, Stainless Steel, Fiberglass, Concrete Installation Type: Residential, Commercial, Wellness Center, Spa Connectivity: Automated, Manual, Bluetooth, Wi-Fi |
| Companies Covered | Plunge, Ice Barrel Inc., ColdTub, Renu Therapy, BlueCube Cold Plunge Tubs & BlueCube Wellness LLC, Morozko Forge, The Ice Bath Co., Brass Monkey Health Ltd, Diamond Spas Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Plunge Pools Market Emerging Trajectories
Electrification of thermal management systems is compressing the performance gap between residential and commercial-grade cold plunge pools, while regulatory pressure on refrigerant chemistry and buyer demand for remote monitoring are reshaping product architecture decisions.
Inverter-driven compressor technology is electrifying cold plunge pool energy profiles by replacing fixed-speed refrigeration cycles with variable-load systems that modulate cooling intensity based on real-time thermal load. Boutique fitness operators in Texas and Florida are adopting these units fastest, drawn by utility rebate eligibility and reduced peak-demand charges. This electrification is compressing the total cost of ownership differential between premium and mid-tier product tiers.
The EPA's phasedown of hydrofluorocarbon refrigerants under AIM Act mandates is compelling chiller manufacturers to transition to hydrofluoroolefin and natural refrigerant alternatives. Commercial installations face the steepest compliance timelines, with new construction projects in California and New York already specifying A2L-classified low-global-warming-potential systems. Manufacturers with in-house refrigerant engineering capabilities are capturing specification authority from component assemblers.
Subscription-based equipment access is displacing outright purchase models among urban residential buyers constrained by space and capital. Cold plunge pools are following the peloton model, with monthly fee structures bundling hardware, filtration consumables, and maintenance dispatch. This shift concentrates most visibly in Los Angeles and Miami, where wellness-as-a-service platforms are aggregating demand across apartment buildings and co-living developments.
Cold Plunge Pools Market Segmentation
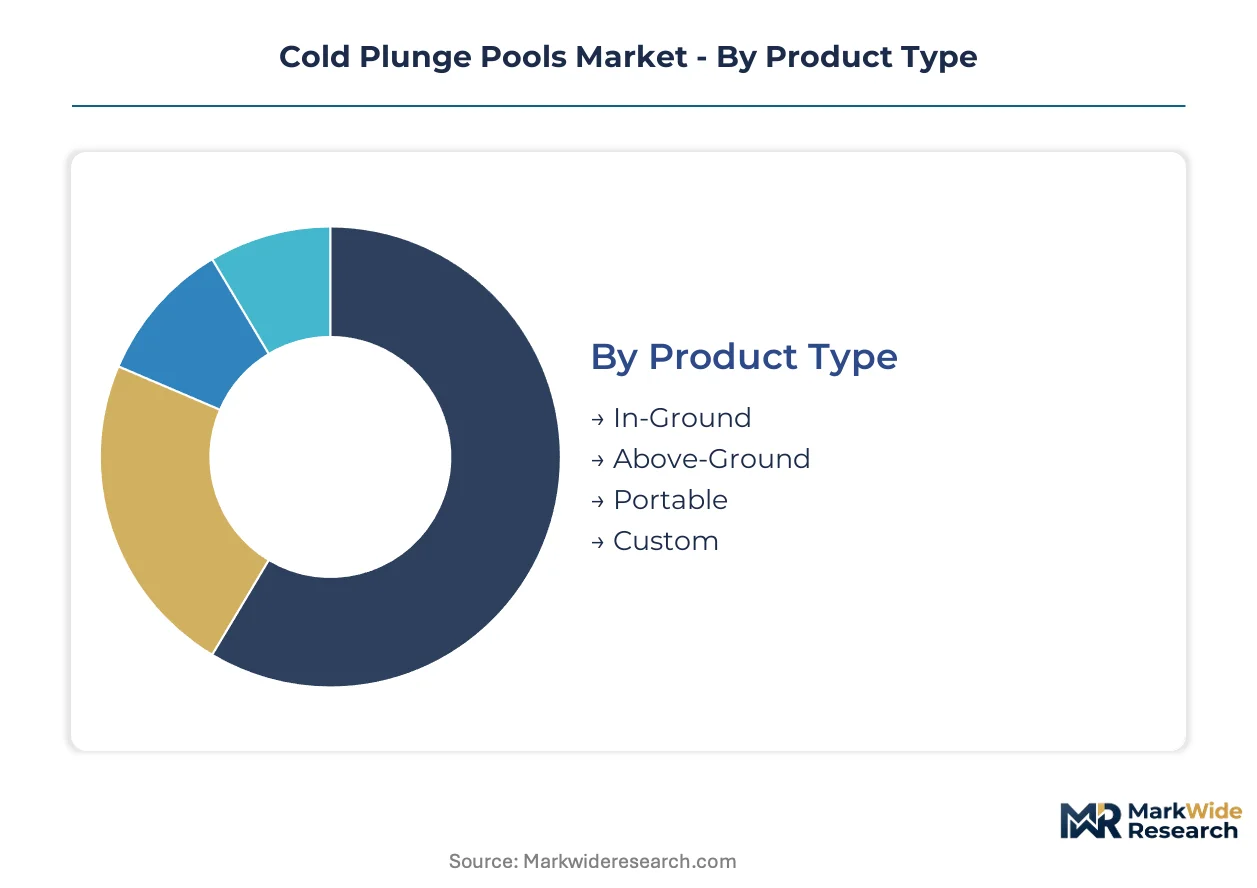
Cold plunge pool manufacturers configure product portfolios around installation constraints and buyer sophistication tiers. Material selection and connectivity integration determine margin capture across residential and commercial deployment channels.
Product Type:
Volume concentration favors plug-and-play formats, while premium pricing accrues to permanent installations requiring construction coordination.
- Above-Ground:Freestanding vessels with integrated chiller systems require no excavation or plumbing rough-in. Demand clusters in Texas and Florida residential markets where slab-on-grade construction simplifies placement. Urban apartment buyers in Los Angeles and Miami select these units for lease-friendly mobility.
- Portable:Collapsible or wheeled configurations with self-contained cooling and filtration target fitness enthusiasts requiring transport between locations. Boutique gym operators in California wellness corridors deploy these for pop-up recovery stations. This segment is expanding most quickly among renters and co-living developments.
- In-Ground:Permanent excavated vessels with hard-plumbed drainage and custom decking integration.
- Custom:Bespoke dimensional and aesthetic specifications for luxury hospitality and residential estates.
Mature deployment sits with In-Ground installations. Newer deployment is concentrated in Portable configurations.
Material:
Cost tier separation runs from commodity polymers to architectural-grade metals with thermal conductivity premiums.
- Stainless Steel:304 and 316-grade shells deliver superior thermal transfer efficiency and impact resistance for high-traffic commercial environments. Wellness centers in California and Texas specify these for durability under continuous cycling. EPA energy-efficiency mandates amplify demand for conductive materials that reduce chiller load.
- Concrete:Poured or shotcrete vessels with waterproofing membranes enable unlimited dimensional customization. Luxury hospitality properties in Florida and Arizona integrate these with landscape architecture for aesthetic cohesion. This segment commands the steepest price premiums and longest lead times.
- Acrylic:Vacuum-formed shells with gelcoat finishes offering color consistency and repairability.
- Fiberglass:Reinforced composite shells balancing weight reduction with structural integrity for above-ground applications.
Specification authority concentrates with Stainless Steel for commercial procurement. Concrete dominates bespoke residential commissions.
Installation Type:
Customer type determines service contract attachment rates and equipment specification complexity.
- Commercial:Corporate wellness facilities and multi-tenant fitness centers require OSHA-compliant sanitation protocols and redundant chiller capacity. Procurement in the United States prioritizes connected monitoring for liability documentation. Service contract unbundling is standard, with separate agreements for filtration consumables and preventive maintenance.
- Wellness Center:Dedicated recovery facilities and biohacking studios demand precise temperature stability and rapid recovery between users. California and Texas operators specify inverter-driven compressors for utility rebate eligibility. This segment shows the fastest adoption of subscription-based equipment access models.
- Residential:Single-family home installations with discretionary usage patterns and space constraints.
- Spa:Hospitality-integrated amenities emphasizing aesthetic integration and guest experience choreography.
Equipment standardization is highest in Residential procurement. Operational complexity peaks in Wellness Center deployments.
Connectivity:
Maturity gradient separates basic electromechanical controls from cloud-integrated telemetry platforms.
- Wi-Fi:Full-stack IoT architecture enabling remote temperature scheduling, usage logging, and predictive maintenance alerts. Commercial operators in the United States deploy these for building management system integration and energy demand response. EPA compliance documentation benefits from automated performance data capture.
- Bluetooth:Local wireless pairing for smartphone-based control without internet dependency. Residential buyers in urban markets with connectivity concerns prefer this intermediate tier. Cost positioning sits between manual electromechanical and full cloud-native systems.
- Automated:Programmable logic controllers with preset temperature profiles and filtration cycling.
- Manual:Basic thermostat and timer interfaces with no digital connectivity.
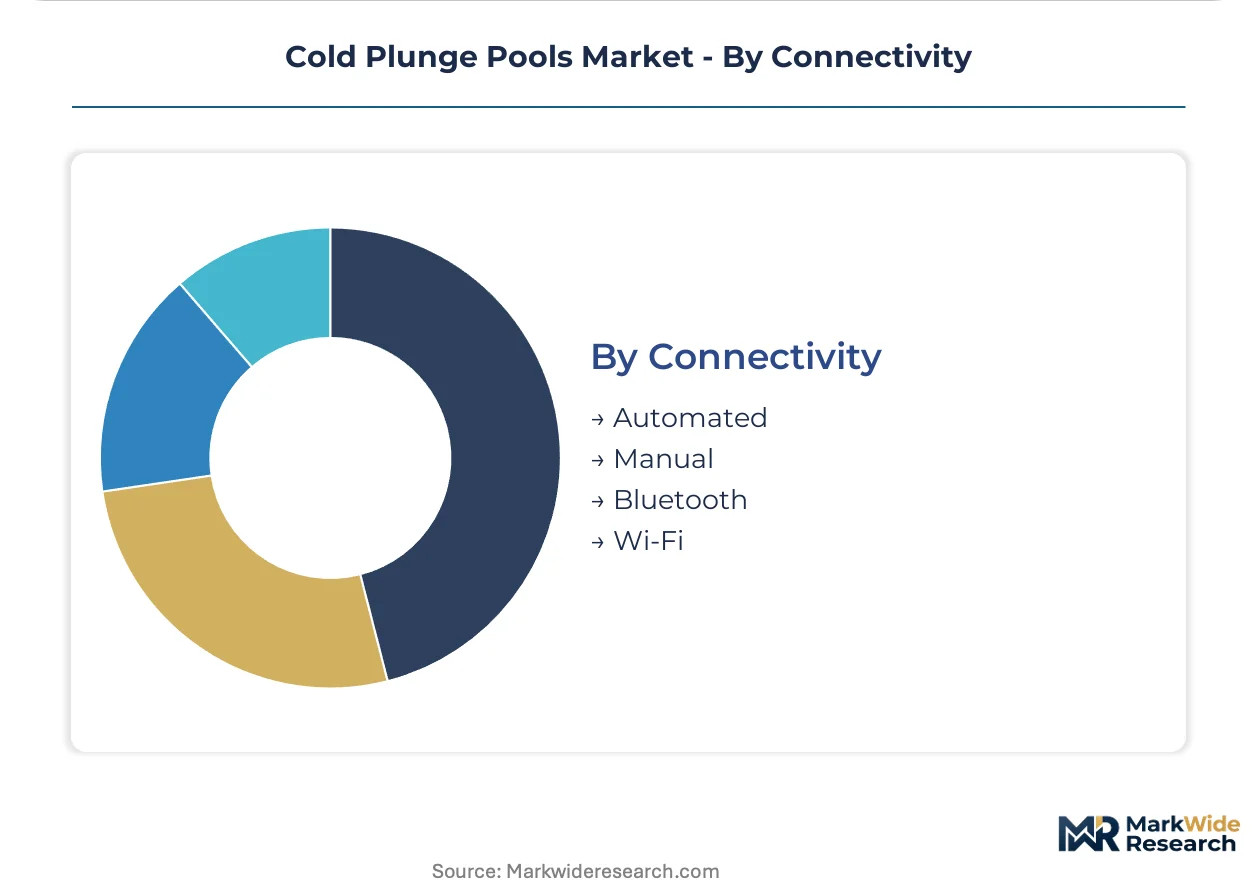
Control sophistication concentrates in Wi-Fi-enabled systems for commercial specification. Bluetooth adoption is climbing fastest among residential upgraders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Texas and California wellness corridors concentrate capital deployment for cold plunge infrastructure. Federal tax incentives accelerate facility buildouts in designated census tracts. State-level energy rebates amplify manufacturer site selection toward these zones.
United States
Recovery-focused athletes in boutique fitness studios drive unit volume across California and Texas wellness corridors. EPA energy-efficiency mandates for water-chilling equipment compel compressor redesigns and insulation upgrades. Los Angeles and Miami lead subscription-based equipment access models for urban residential buyers.
Canada
Corporate wellness procurement prioritizes OSHA-aligned amenities for liability documentation in multi-tenant fitness centers. Health Canada guidelines for recreational water quality shape filtration specifications for imported systems. Toronto and Vancouver concentrate hospitality-integrated cold plunge deployments in luxury hotel renovations.
Germany
Commercial wellness operators specify inverter-driven compressors for utility rebate eligibility under national efficiency programs. ECHA REACH regulations govern refrigerant chemistry transitions for low-global-warming-potential alternatives. Bavaria anchors precision engineering for chiller component supply to export markets.
United Kingdom
Biohacking studios in London prioritize connected automation for building management system integration. CE marking requirements for electrical safety and electromagnetic compatibility extend certification timelines for mid-tier producers. Southeast England concentrates service contract unbundling for filtration and preventive maintenance agreements.
Australia
Luxury hospitality properties in Queensland and New South Wales integrate custom concrete vessels with landscape architecture. TGA guidelines for therapeutic device classification influence product registration pathways for recovery-focused claims. Sydney anchors demand for stainless-steel commercial installations in high-traffic wellness centers.
Cold Plunge Pools Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer velocity concentrating in residential procurement and specification authority accruing to firms with captive R&D capabilities. The vendor base organizes around three archetypes: stainless-steel fabricators with thermal conductivity advantages, integrated chiller engineers with refrigerant expertise, and wellness-as-a-service platforms aggregating urban demand. Competitive moves center on backward integration into compressor technologies and geographic expansion through subscription-based equipment access models.
Among US-based branded specialists, Plunge occupies a position exemplifying direct-to-consumer distribution velocity, while Morozko Forge anchors the integrated manufacturing archetype through in-house production capabilities. Diamond Spas Inc. represents the bespoke fabrication tier for luxury hospitality specifications.
| Leading Market Players |
|---|
| Plunge |
| Ice Barrel Inc. |
| ColdTub |
| Renu Therapy |
| BlueCube Cold Plunge Tubs & BlueCube Wellness LLC |
| Morozko Forge |
| The Ice Bath Co. |
| Brass Monkey Health Ltd |
| Diamond Spas Inc. |
| Others |
Supply Flow & Price Mechanics
EPA refrigerant phase-down mandates under the AIM Act gate qualified supply and premium-tier pricing access, compressing margins for assemblers lacking in-house refrigerant engineering while rewarding integrated manufacturers with specification authority and pricing power.
Pricing Analysis
Lead-time premiums separate pricing tiers, with stainless-steel commercial installations commanding 40-60 percent markups over spot acrylic inventory for expedited delivery. Pricing stratifies across custom concrete, premium stainless-steel, and commodity fiberglass tiers, with certification grade (ISO recreational water quality, UL electrical safety) and after-sales service bundling as primary differentiation drivers. Cost compression in mid-tier portable units is intensifying because Japanese and German compressor supply bottlenecks extend fulfillment windows. Residential buyers in urban markets show highest price sensitivity, while luxury hospitality clients demonstrate lowest elasticity.
Supply Chain Analysis
Compressor supply rests on Japanese and German industrial specialists, with secondary concentration in Chinese aluminum extrusion and copper tubing fabrication. Raw material dependencies include hydrofluoroolefin refrigerants, 304/316-grade stainless steel, and thermal exchange copper. Single-source vulnerability in advanced chiller components exposes manufacturers to extended lead times when Japanese suppliers allocate capacity to HVAC OEMs. Distribution runs through direct-to-consumer platforms for residential velocity, commercial specification channels for hospitality, and wellness-as-a-service aggregators for urban apartment deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cold plunge pool sector sits in a technology-transition phase, with inverter-driven compressor electrification displacing fixed-speed refrigeration cycles and compressing total cost-of-ownership differentials across product tiers.
For Market Incumbents: Hedge against refrigerant chemistry obsolescence by accelerating backward integration into chiller engineering capabilities before EPA AIM Act compliance timelines tighten. Prioritize captive R&D investment over component assembly to defend specification authority from integrated rivals like Morozko Forge.
For New Entrants and Emerging Players: Capture underpenetrated urban residential density in New York and Chicago apartment markets through subscription-based equipment access models that bundle hardware, filtration consumables, and maintenance dispatch. Lead with compact portable configurations resolving installation logistics constraints for renters.
For Investors and Strategic Acquirers: Wellness-as-a-service platform consolidation in Los Angeles and Miami is the leading indicator that recurring revenue models are achieving scale economics superior to transactional hardware sales. Target firms with IoT-enabled telemetry architectures and established service contract unbundling capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Engineering Investment | In-house HFO and natural refrigerant capabilities capture specification authority from assemblers under EPA AIM Act mandates. |
| Subscription Model Launch | Monthly fee structures bundling hardware and service aggregate urban demand across apartment buildings and co-living developments. |
| Connected Automation Integration | Wi-Fi-enabled IoT architectures enable building management system compatibility and predictive maintenance contract attachment. |
| Stainless-Steel Fabrication Scale-Up | 304 and 316-grade shell production secures thermal conductivity advantages for commercial wellness center procurement. |
| Service Contract Unbundling | Separate agreements for filtration consumables and preventive maintenance generate recurring revenue streams from commercial deployments. |
Methodological Framework
Document review covered EPA regulatory filings, ISO recreational water quality standards, and customs trade data for thermal exchange materials, complemented by interviews with chiller engineering directors, wellness center procurement managers, boutique fitness studio operators, and hospitality amenities executives. Primary fieldwork with stainless-steel fabricators and refrigerant suppliers cross-checked against secondary sources including SEC filings from HVAC component manufacturers and state-level energy rebate program disclosures. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Segment-level outputs across product type, material grade, installation category, and connectivity tier were generated through structured demand modeling. CAGRs were derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost impacts. Key forecast inputs included EPA refrigerant phase-down schedules, copper and aluminum price volatility indices, and utility rebate program expansion trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to compressor supply allocation shifts and refrigerant chemistry transition costs. Assumptions underlying projections reflect current regulatory trajectories and documented buyer procurement patterns. A small set of triggers—including Japanese supplier capacity reallocation and California A2L refrigerant mandate acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor & Sports
Skateboard Ramp Market
Outdoor & Sports
Camping Beds and Mats Market
Outdoor & Sports
Australia Horse Riding Equipment Market
Outdoor & Sports
Golf Stand Bag Market
Outdoor & Sports
Riding Multi-Purpose Lawn Mower Market
Outdoor & Sports
Walkbehind Lawnmower Market
Outdoor & Sports
LED Fishing Light Market
Outdoor & Sports
Global Pool Floats Market
Outdoor & Sports
Skimboard Market
Outdoor & Sports
China Fishing Reels Market
Outdoor & Sports
Swimming Pool Accessories Market
Outdoor & Sports
Aquatic Fins Market
Outdoor & Sports
Global Scuba Diving Equipment Market
Outdoor & Sports
Fishing Line Market
Outdoor & Sports
Global Baseball Gloves Market
Outdoor & Sports
Mexico Fishing Reels Market