
 North America Dog Food Market | 2026-2036
North America Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Dog Food Market Intelligence
Millennial and Gen Z pet owners is unwinding the historical dominance of price-driven bulk purchasing in the North America dog food sector. Mars Incorporated leverages its vertical integration from ingredient sourcing to veterinary channels across the United States and Canada. Nestlé Purina PetCare anchors its position through R&D intensity in clinical nutrition formulations. Hill's Pet Nutrition Inc specializes in prescription-tier diets distributed through veterinary clinics.
North America dog food comprises nutritionally formulated products manufactured through extrusion, canning, or cold-pressing processes, designed to meet AAFCO nutrient profiles for canine maintenance, growth, or therapeutic conditions. Dry food occupies the largest volume share due to shelf stability and cost efficiency in mass retail channels. Wet food commands premium pricing and stronger margins, particularly in specialty and veterinary segments. Grain-free formulations have receded from peak demand following FDA investigations into canine dilated cardiomyopathy associations.
The FDA's Center for Veterinary Medicine enforces ingredient safety standards and facility registration under the Food Safety Modernization Act, while AAFCO model regulations govern nutrient adequacy claims across US states. Health Canada and the Canadian Food Inspection Agency administer parallel safety frameworks for products distributed north of the border. Stakeholders must monitor evolving state-level raw food regulations and the trajectory of sustainability-linked ingredient sourcing requirements.
Market Dynamics
Millennial pet owner premiumization is unwinding legacy mass-market purchasing patterns across the North America dog food sector, forcing reformulation transparency and channel restructuring from California's urban corridors through the Pacific Northwest.
Growth Catalysts
- AAFCO Nutrient Profile Updates:The Association of American Feed Control Officials' revised model regulations are compelling manufacturers to disclose ingredient sourcing and nutritional adequacy claims, accelerating clean-label product development.
- Veterinary Channel Expansion:Prescription-tier therapeutic diets distributed through veterinary clinics are capturing margin-rich segments as pet humanization drives clinical nutrition demand.
- California Urban Corridor Concentration:Dense metropolitan pet ownership in Los Angeles and San Francisco is concentrating demand for fresh, refrigerated, and subscription-delivered formulations.
Market Restraints
- Protein Input Cost Volatility:Fluctuations in chicken, beef, and fish meal prices squeeze formulation economics, particularly for mid-tier manufacturers lacking long-term supply contracts.
- FDA Canine DCM Investigation Fallout:The Food and Drug Administration's ongoing examination of grain-free formulations and dilated cardiomyopathy associations has depressed consumer confidence in legume-heavy recipes.
- Midwest Manufacturing Concentration:Production gravity centers on Kansas, Iowa, and Nebraska render supply chains vulnerable to regional weather disruptions and transportation bottlenecks.
Strategic Opportunities
- Canadian Regulatory Arbitrage:Health Canada's parallel but distinct pet food safety framework offers pathways for US manufacturers to test novel ingredients before FDA submission.
- Insect Protein Convergence:Black soldier fly larvae and cricket meal technologies are converging with precision fermentation to create novel sustainable protein streams exempt from traditional livestock supply chains.
- Direct-to-Consumer Subscription Channels:Fresh-cooked and raw formulations bypassing mass retail are capturing lifetime value through automated replenishment and personalized nutrition algorithms.
Industry Challenges
- Raw Material Traceability Systems:Implementing blockchain-enabled ingredient provenance tracking requires substantial IT infrastructure investment beyond mid-cap manufacturer capabilities.
- Veterinary Nutritionist Talent Scarcity:Board-certified veterinary nutritionists capable of formulating therapeutic diets remain concentrated at academic institutions, constraining R&D pipeline velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Dog Food Market |
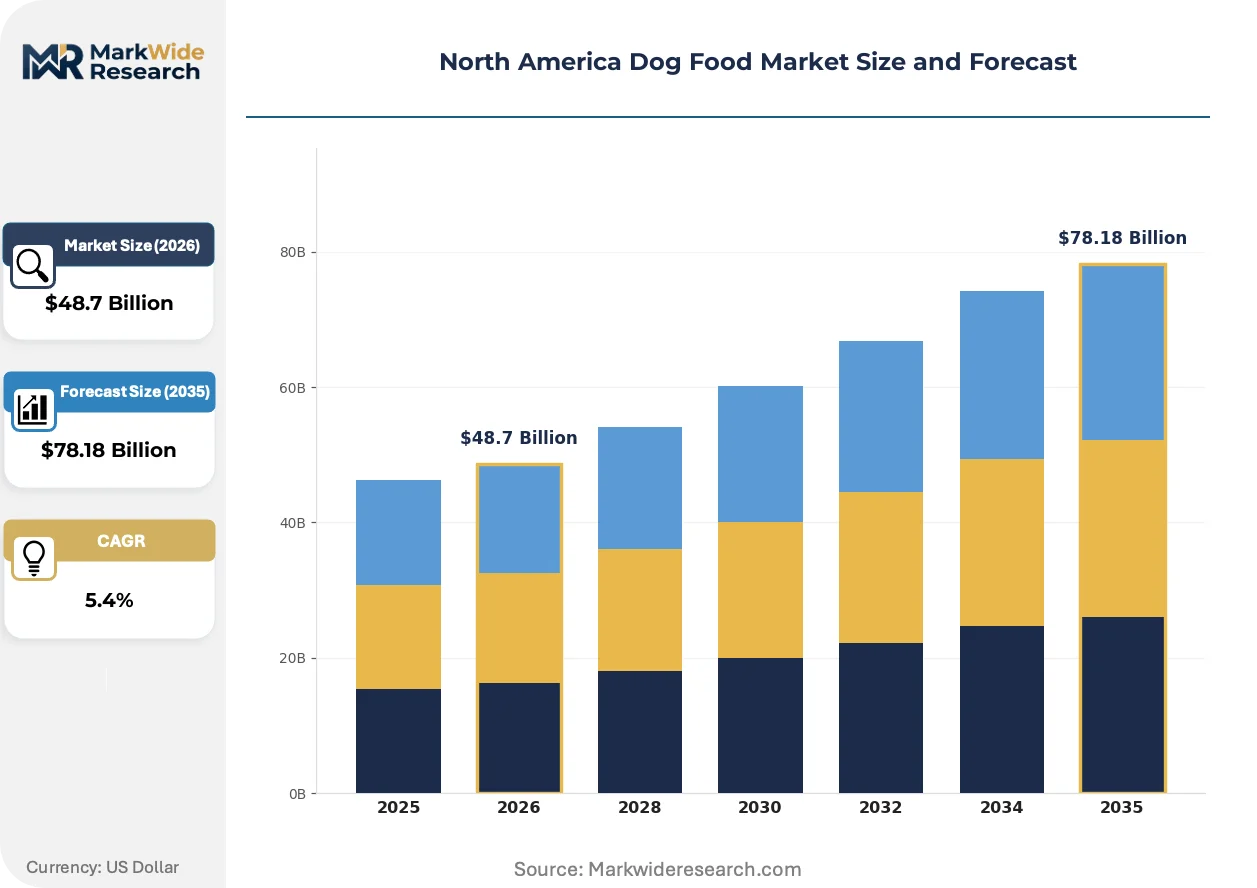
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $78.18 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Organic, Vegetarian Distribution Channel: Supermarkets, Online Retail, Pet Stores, Specialty Shops Customer Segment: First-Time Pet Owners, Experienced Owners, Rescue Organizations, Breeders |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, Hill’s Pet Nutrition Inc, The J.M. Smucker Company, General Mills Inc, Blue Buffalo Co. Ltd, Diamond Pet Foods, WellPet LLC, Champion Petfoods LP, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Dog Food Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reshape competitive positioning across the North America dog food landscape, with transparency mandates and sustainability pressures accelerating product lifecycle compression.
Cold-pressed and gently cooked manufacturing is miniaturizing production economics for regional micro-breweries. Small-batch operators in Portland, Austin, and Toronto are adopting scaled-down extrusion and retort systems previously viable only at industrial scale. This equipment democratization is enabling 10,000-ton annual output facilities to achieve unit economics competitive with legacy mass-market plants, compressing minimum efficient scale thresholds and fragmenting manufacturing geography.
The FDA's updated pet food labeling requirements under the Food Safety Modernization Act are mandating calorie content statements and species-specific ingredient identification. Manufacturers must now declare whether "meat meal" derives from bovine, porcine, or avian sources. Wet food and treat segments face the steepest compliance costs due to complex multi-ingredient formulations, driving consolidation among regional co-packers unable to absorb analytical testing burdens.
Subscription-based fresh food purchasing is displacing stock-up shopping at mass retail. Millennial and Gen Z pet owners in Seattle, Vancouver, and Denver are abandoning 40-pound kibble bags for weekly delivered portions matched to individual dog metabolic profiles. This behavior concentrates customer lifetime value with direct brands while eroding shelf space leverage for legacy packaged goods players dependent on Costco and Walmart rotation.
North America Dog Food Market Segmentation
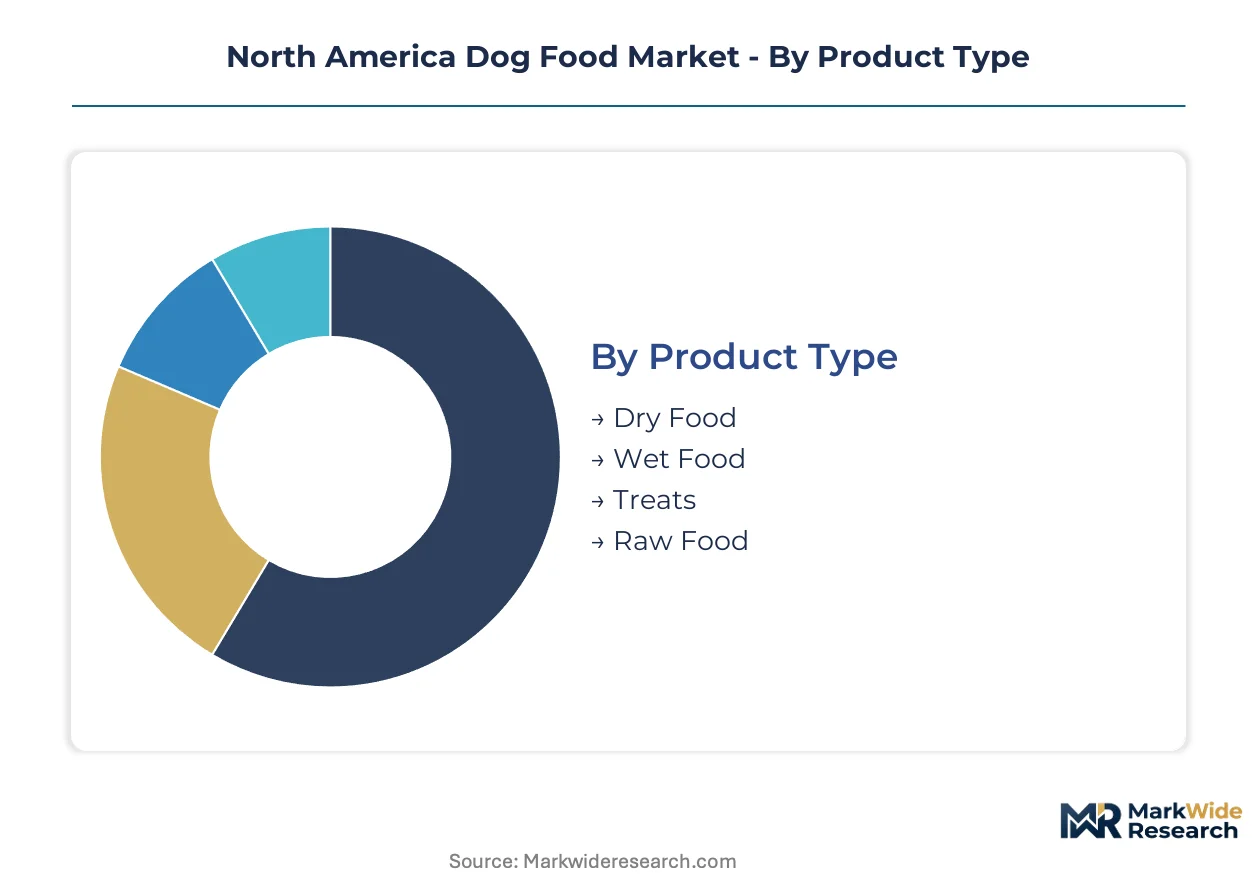
North America dog food segmentation reflects divergent purchasing behaviors between urban premium adopters and price-sensitive suburban households. Channel fragmentation and ingredient transparency mandates are compressing traditional category boundaries across the United States and Canada.
Product Type:
Dry formulations dominate domestic manufacturing volumes from Kansas through Nebraska, while wet and fresh categories concentrate demand in coastal metropolitan corridors.
- Dry Food:Extruded kibble formulations achieve shelf stability through moisture reduction below 10 percent. Midwest production clusters supply mass retail channels across the United States and Canada, with Costco and Walmart rotation driving volume economics.
- Wet Food:Retort-processed canned products deliver higher moisture content and palatability for senior dogs. California urban corridors and Pacific Northwest metropolitan areas concentrate demand for premium gravy and pate formulations.
- Treats:Functional and dental categories span training rewards to veterinary-distributed therapeutic chews.
- Raw Food:Frozen and freeze-dried formulations bypass traditional retail through veterinary and direct-to-consumer channels.
Dry food commands the established base. The steepest expansion runs through raw and fresh-cooked formulations.
Ingredient Type:
Formulation costs stratify sharply between commodity protein inputs and certified organic supply chains, with regulatory scrutiny compressing grain-free positioning.
- Meat-Based:Conventional poultry, beef, and fish meal formulations remain the volume standard across mass retail. AAFCO labeling mandates now require species-specific identification of rendered protein meals.
- Grain-Free:Legume and potato-based carbohydrate substitutes face depressed consumer confidence following FDA investigations into canine dilated cardiomyopathy associations.
- Organic:USDA-certified ingredients command 40-60 percent price premiums in specialty channels.
- Vegetarian:Plant-protein formulations address environmental positioning and limited protein allergy management.
Meat-based formulations anchor volume production. Organic certification delivers the steepest margin expansion trajectory.
Distribution Channel:
Channel economics fragment between high-velocity mass retail and subscription-driven lifetime value capture in direct-to-consumer models.
- Supermarkets:Kroger, Safeway, and Loblaws networks provide shelf access for mid-tier national brands. Slotting fees and promotional calendars favor manufacturers with marketing budgets exceeding 15 million dollars annually.
- Online Retail:Amazon, Chewy, and direct brand websites concentrate subscription replenishment for premium and fresh formulations. Automated delivery algorithms match portion sizing to individual dog metabolic profiles.
- Pet Stores:PetSmart and Petco operate 2,800-plus combined locations with private label expansion compressing third-party margins.
- Specialty Shops:Independent retailers in Portland, Austin, and Toronto curate regional micro-brewery and limited-ingredient portfolios.
Supermarket and pet store channels defend the volume base. Online retail exhibits the fastest share gain.
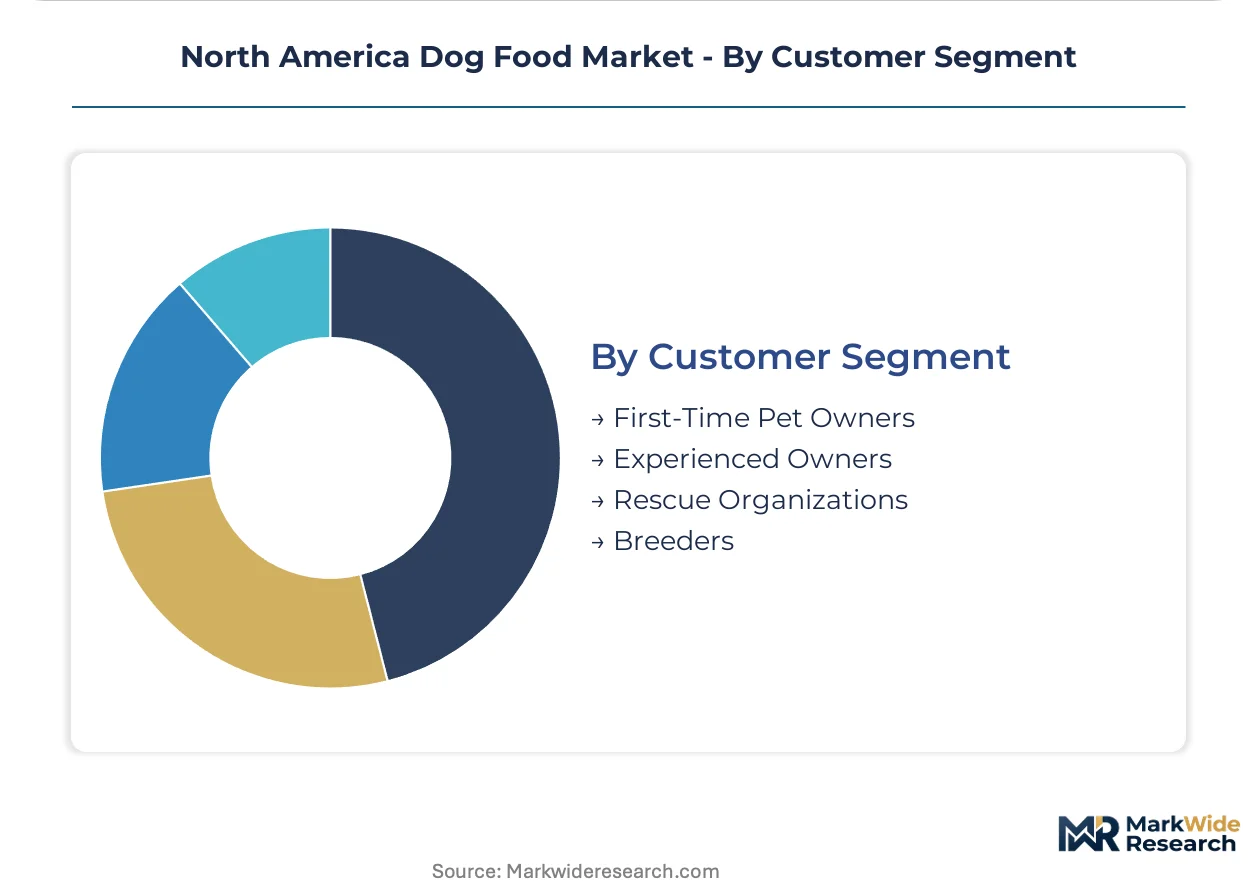
Customer Segment:
Purchasing sophistication varies dramatically between transactional first-time adopters and clinically engaged experienced owners.
- First-Time Pet Owners:Millennial and Gen Z entrants favor subscription fresh food and veterinary-recommended brands. Customer acquisition costs run highest for this cohort through social media and influencer channels.
- Experienced Owners:Multi-dog households and breed-specific communities drive prescription diet demand and ingredient provenance scrutiny.
- Rescue Organizations:Nonprofit shelters and foster networks prioritize cost efficiency in bulk dry food procurement.
- Breeders:Professional kennel operations require growth-stage formulations and puppy starter programs with volume pricing structures.
Experienced owners concentrate margin-rich therapeutic demand. First-time pet owners are expanding most quickly through digital-native purchasing patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z pet owners concentrate in coastal metropolitan corridors, driving premiumization across the United States, Canada, and Mexico. Urban density in California, Pacific Northwest cities, and Toronto accelerates demand for fresh, subscription-delivered formulations. Regulatory divergence between FDA and Health Canada frameworks creates distinct compliance pathways for manufacturers operating across borders.
United States
California's urban corridors and the Pacific Northwest concentrate subscription fresh-food demand among digital-native pet owners. The FDA's Center for Veterinary Medicine enforces updated labeling requirements under the Food Safety Modernization Act, mandating calorie content statements and species-specific ingredient identification. Kansas, Iowa, and Nebraska host dense manufacturing clusters supplying mass retail channels nationwide.
Canada
Toronto and Vancouver metropolitan areas mirror US coastal premiumization patterns with strong adoption of refrigerated and raw formulations. Health Canada and the Canadian Food Inspection Agency administer parallel safety frameworks that occasionally permit novel ingredient testing ahead of FDA submission. Ontario and Quebec manufacturing bases serve domestic demand while exporting specialty products southward.
Mexico
Mexico City and Monterrey anchor growing middle-class pet ownership expanding beyond traditional economy-tier purchasing. The country's national food safety regulator maintains evolving standards for imported pet food products, particularly from US manufacturing clusters. Northern border states concentrate distribution infrastructure facilitating cross-border supply chain integration with Texas and California hubs.
Pacific Northwest Corridor
Seattle and Portland metropolitan statistical areas exhibit the highest per-household pet food expenditure rates across North America. State-level raw food regulations in Washington and Oregon vary from federal guidelines, creating compliance complexity for direct-to-consumer brands. Regional micro-brewery facilities in Portland leverage scaled-down extrusion technology to serve local specialty channels.
Southwest United States
Texas urban centers including Dallas-Fort Worth and Houston concentrate demand for large-breed formulations among suburban multi-dog households. The state's central logistics position enables distribution optimization for manufacturers serving both US and Mexican markets. Austin emerges as a specialty retail hub curating limited-ingredient and regional micro-brewery portfolios.
North America Dog Food Market Key Industry Players
Player mix skews toward diversified consumer packaged goods conglomerates with captive pet care divisions. Three multinational food manufacturers anchor the premium and mass-market tiers through veterinary channel penetration and R&D-intensive clinical nutrition portfolios. Mid-cap specialists occupy the grain-free, limited-ingredient, and raw food segments through direct-to-consumer subscription models. Dominant competitive moves include backward integration into ingredient sourcing and strategic partnerships with veterinary clinic networks.
Within the conglomerate tier, Mars Incorporated, Nestlé Purina PetCare, and Hill's Pet Nutrition Inc represent distinct strategic archetypes. Mars exemplifies vertical control from ingredient sourcing through veterinary distribution channels across the United States and Canada. Nestlé Purina occupies a position anchored by R&D intensity in clinical nutrition formulations. Hill's sits within the prescription-tier therapeutic diet segment distributed through veterinary clinics. These three entities collectively shape pricing benchmarks and formulation standards that cascade through mid-tier and specialty competitors.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition Inc |
| The J.M. Smucker Company |
| General Mills Inc |
| Blue Buffalo Co. Ltd |
| Diamond Pet Foods |
| WellPet LLC |
| Champion Petfoods LP |
| Others |
Cost & Logistics Intelligence
Insect protein substitution for conventional poultry and fish meal is redrawing procurement geography across the North America dog food sector while compressing formulation economics for mid-tier manufacturers locked into legacy livestock supply contracts.
Pricing Analysis
Cost-plus contracts indexed to Chicago Mercantile Exchange livestock futures dominate protein procurement for mass-market manufacturers. Pricing stratifies across premium, standard, and economy tiers with USDA organic certification and veterinary prescription status as primary differentiation drivers. Cost compression in the standard tier is intensifying because of black soldier fly larvae meal adoption by coastal micro-breweries. Rescue organizations and bulk-buying suburban households exhibit highest price sensitivity, while subscription fresh-food adopters in Seattle and Vancouver show lowest elasticity.
Supply Chain Analysis
Midwest rail corridor bottlenecks through Kansas and Nebraska threaten just-in-time delivery schedules for extruded kibble manufacturers serving Costco and Walmart rotation cycles. Production draws from concentrated rendering facilities in Iowa, Nebraska, and Missouri with protein meal inputs sourced from Tyson, Cargill, and JBS slaughterhouse operations. Single-source vulnerability runs through the Omaha protein rendering cluster. Distribution runs through regional distribution centers in Chicago, Dallas-Fort Worth, and Ontario serving mass retail and veterinary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millennial and Gen Z pet owner fragmentation across subscription fresh-food, veterinary clinical nutrition, and mass-market bulk purchasing creates multiple defendable niche positions for differentiated competitors.
For Market Incumbents: Fortify veterinary channel control through exclusive prescription diet distribution agreements and captive supply of novel protein ingredients. Mars Incorporated and Nestlé Purina PetCare should deepen backward integration into insect protein farming to offset livestock futures volatility. Certification investment in AAFCO feeding trial protocols remains essential for therapeutic tier defense against emerging precision-nutrition challengers. For New Entrants and Emerging Players: AAFCO fast-track approval for novel ingredients through Health Canada's parallel framework offers regulatory arbitrage before FDA submission. The Pacific Northwest corridor presents the most penetrable geography with highest per-household pet food expenditure and tolerant state-level raw food regulations. Direct-to-consumer subscription algorithms matched to individual dog metabolic profiles provide the strongest go-to-market angle against shelf-dependent incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward regional micro-brewery operators with scaled-down extrusion capabilities and established specialty retail relationships in Portland, Austin, and Toronto. Long-term viability hinges on subscription retention metrics exceeding mass retail churn rates. The signal to monitor is FDA clearance timelines for precision-fermented protein ingredients as inflection indicator for sustainable supply chain economics.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Exclusive Distribution | Locks prescription-tier margins through Hill's Pet Nutrition Inc's clinic network model. |
| Insect Protein Supply Agreement | Secures black soldier fly larvae meal exempt from Chicago Mercantile Exchange livestock futures. |
| Direct-to-Consumer Subscription Launch | Captures lifetime value through Chewy and Amazon automated replenishment algorithms. |
| AAFCO Fast-Track Certification Investment | Accelerates novel ingredient approval via Health Canada parallel submission pathway. |
| Regional Micro-Brewery Acquisition | Deploys scaled-down extrusion technology for Portland and Austin specialty retail channels. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with veterinary nutritionists at academic institutions, procurement directors at Midwest rendering facilities, category buyers at PetSmart and Petco, and subscription brand founders in Seattle and Vancouver. Secondary validation drew from FDA Center for Veterinary Medicine enforcement reports, AAFCO model regulation updates, Health Canada pet food safety advisories, and Nielsen retail audit data. Bottom-up volume estimates from individual manufacturing facilities were triangulated against top-down category spend analysis.
Across the analysis window, forecasts incorporate product type segmentation by dry, wet, and raw formulations alongside distribution channel splits between mass retail, online subscription, and veterinary clinic networks. CAGRs were derived from trend extrapolation of millennial pet owner premiumization rates and protein input cost trajectories. Modeled inputs include FDA labeling compliance cost burdens and Health Canada novel ingredient approval timelines.
Decision-makers should treat outputs as directional under assumptions of sustained millennial pet ownership growth and stable FDA regulatory enforcement; material deviation in grain-free consumer confidence or raw food state-level restrictions would warrant model refresh. Practitioners should keep alternative scenarios live as insect protein scale economics and precision fermentation cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Cat Nail Clippers Market
Pet Care Products
Italy Pet Food Market
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Cat Massage Comb Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Dog Collars Market
Pet Care Products
Netherlands Pet Food Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Dog Brush Market
Pet Care Products
Global Pet Supplies Market
Pet Care Products
Taiwan Pet Food Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
Dog Dental Chews Market