
 US Pet Daycare Market | 2026-2036
US Pet Daycare Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Daycare Market Intelligence
Buyer concentration among urban millennial and Gen Z pet owners without children is rebalancing the customer mix away from traditional suburban families. Dogtopia Enterprises leverages its franchise model to sustain national footprint expansion. Paradise 4 Paws, LLC anchors its position through airport-adjacent luxury facilities targeting traveling professionals. Camp Bow Wow competes via its gym-style membership structure and standardized playgroup protocols.
US pet daycare encompasses supervised daytime care, socialization, exercise, and basic wellness monitoring for companion animals in licensed commercial facilities, typically requiring climate-controlled indoor play areas, outdoor relief zones, and staff-to-animal ratios governed by local ordinances. The primary commercial purpose centers on enabling pet owners to maintain full-time employment while ensuring animal welfare and behavioral enrichment during unattended hours. Daycare services command the largest revenue share among service type segments, while luxury facilities extract premium pricing through webcam access, personalized activity reporting, and spa-style amenities. Dogs dominate animal type demand, though cat-specific daycare represents an emerging margin pool as feline ownership rises in dense urban apartments.
USDA licensing under the Animal Welfare Act, state-level Department of Agriculture facility inspections, and municipal zoning boards collectively shape market access, with non-compliance risks forcing exit or costly retrofit among smaller operators. OSHA workplace safety standards and state-specific kennel technician certification requirements further elevate operational barriers. Stakeholders must monitor evolving service animal versus companion animal regulatory distinctions and anticipate zoning liberalization pressures in housing-constrained cities.
Market Dynamics
Dual-income millennial households without children are compressing demand cycles and forcing facility operators to extend operating hours while adding behavioral enrichment services beyond basic supervision.
Growth Catalysts
- USDA Animal Welfare Act licensing:Federal facility standards elevate consumer trust in commercial daycare over informal neighborhood arrangements, accelerating licensed facility penetration in suburban corridors.
- Airport-adjacent facilities:Business travel resumption concentrates demand for extended-stay boarding and luxury daycare services near Dallas-Fort Worth, Houston, and Atlanta aviation hubs.
- Behavioral enrichment protocols:Structured socialization programs reduce canine anxiety disorders, generating veterinary referrals and repeat customer lock-in for facilities with certified training staff.
Market Restraints
- California municipal zoning:Local ordinances in Los Angeles and San Francisco restrict facility square footage and outdoor relief zone proximity to residential districts, capping expansion velocity.
- Veterinary technician wage inflation:Licensed kennel staff command premium compensation in tight labor markets, compressing operating margins for mid-tier operators without membership volume.
- Home-based pet sitting platforms:Gig-economy alternatives undercut pricing for basic daycare, fragmenting price-sensitive demand away from brick-and-mortar facilities.
Strategic Opportunities
- Feline-specific daycare suites:Cat ownership density in Manhattan, Chicago, and Seattle apartment markets remains underserved by dog-centric facility designs.
- OSHA workplace safety compliance:Proactive investment in staff injury prevention protocols differentiates operators for corporate partnership programs and insurance premium reductions.
- Telemedicine integration:Remote veterinary triage during daycare hours reduces emergency transport costs and extends service continuity into evening hours.
Industry Challenges
- Certified kennel technician recruitment:State-level licensing requirements in New York and Texas outpace vocational program graduation rates, constraining facility staffing ratios.
- Climate control capex:HVAC upgrades for indoor play area temperature regulation absorb disproportionate capital allocation relative to revenue-generating square footage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Daycare Market |
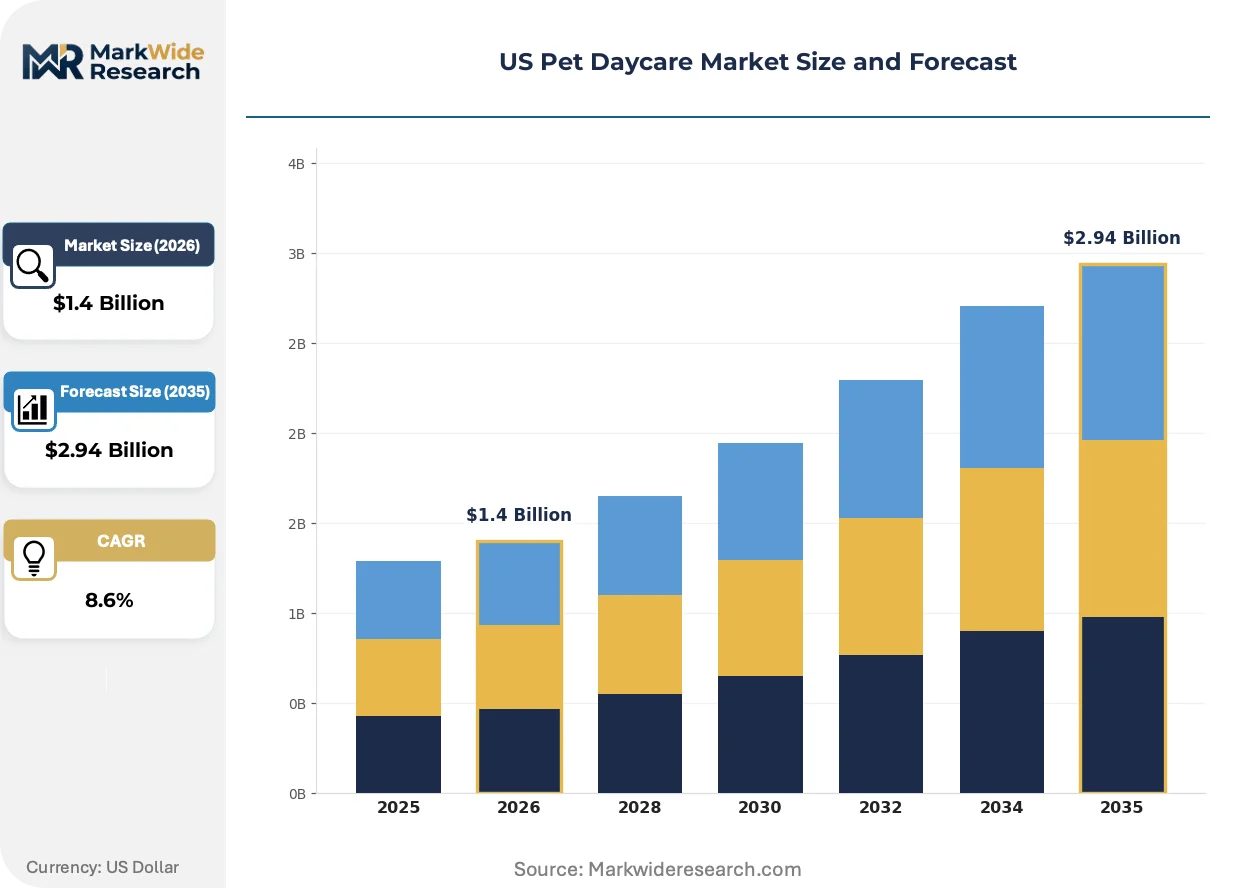
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daycare Services, Overnight Boarding, Grooming Services, Training Sessions Animal Type: Dogs, Cats, Birds, Others Facility Size: Small Facilities, Medium Facilities, Large Facilities, Luxury Facilities Pricing Model: Hourly Rates, Daily Packages, Membership Plans, Premium Services |
| Companies Covered | A Place for Rover, Inc., Paradise 4 Paws, LLC, Dogtopia Enterprises, Come Sit Stay, Camp Run-A-Mutt Entrepreneurial Resources, Camp Bow Wow, Fetch! Pet Care, Barkley Ventures, Inc., PetSmart LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Daycare Market Strategic Shifts & Innovations
Facility operators are deploying sensor networks and automated monitoring systems to replace manual wellness checks, compressing labor intensity while generating data assets for owner engagement platforms.
Livestream webcam infrastructure is integrating with mobile application interfaces, enabling real-time visual access for traveling professionals. Urban millennial buyers in Boston and Washington D.C. now expect continuous video availability as a standard amenity rather than premium upsell. This technology compression is forcing independent operators to absorb connectivity costs or cede market position to franchise networks with centralized IT platforms.
New York and California municipal animal welfare boards are tightening staff-to-animal ratio mandates and mandating outdoor relief zone minimums. Facility operators in Brooklyn and Oakland face retrofit timelines under eighteen months or license non-renewal. Premium-positioned facilities are responding by consolidating smaller locations into larger compliant campuses, accelerating geographic concentration among multi-site operators.
Subscription membership structures are displacing per-day transactional pricing among frequent users. Dog owners in Austin and Denver metro corridors increasingly prefer unlimited monthly access with guaranteed reservation priority over à la carte booking. This behavioral shift rewards facilities with capacity planning sophistication and penalizes operators dependent on walk-in volume volatility.
US Pet Daycare Market Segmentation
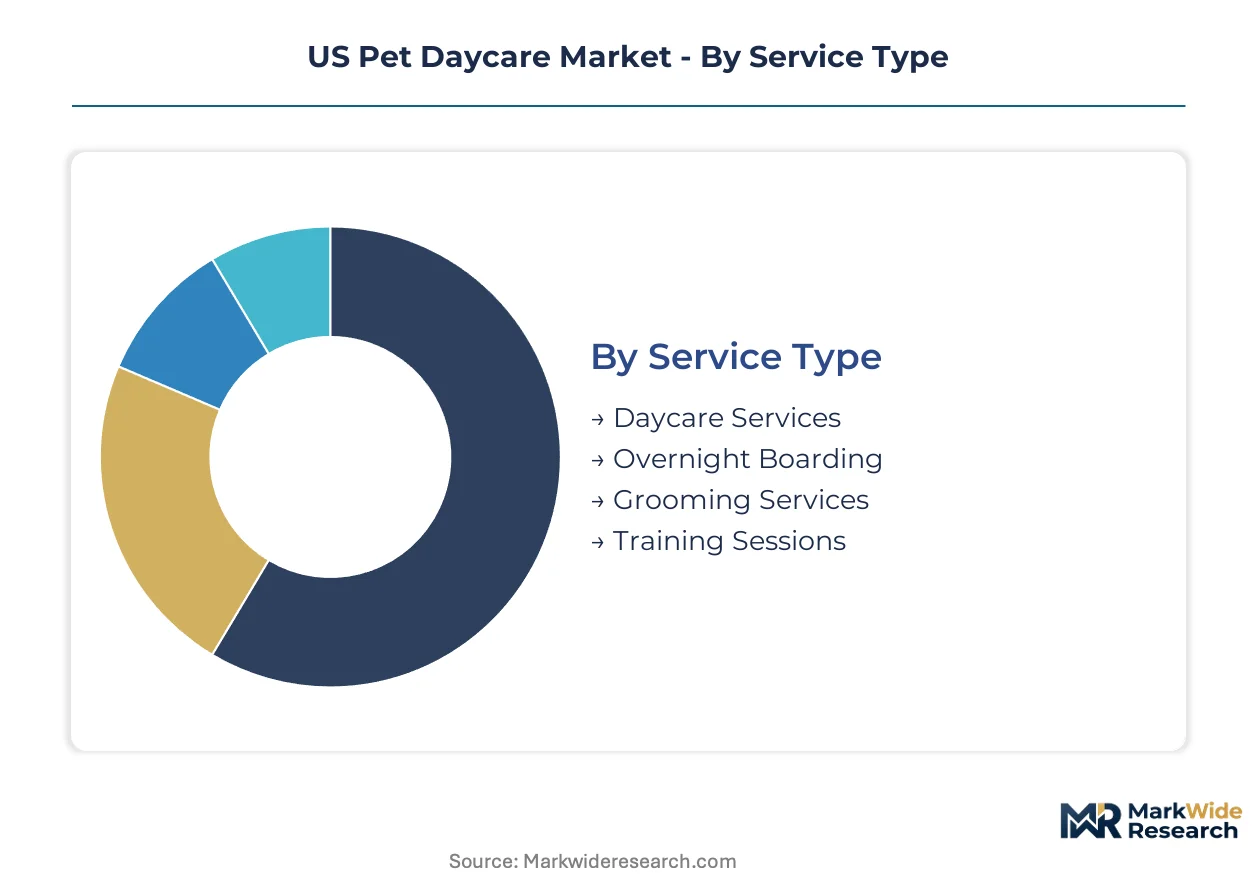
Segmentation in US pet daycare reveals how owner lifestyle constraints and animal welfare expectations fragment demand across service tiers. Operators must align facility configuration, staffing protocols, and pricing architecture to specific buyer profiles or risk margin erosion from mismatched capacity investments.
Service Type:
Owner work schedules and travel frequency determine which service combination locks in recurring revenue versus transactional spend.
- Daycare Services:Supervised daytime care with structured socialization and exercise protocols dominates facility throughput. Demand concentrates in Dallas-Fort Worth and Houston metro corridors where dual-income households without children seek behavioral enrichment during standard business hours. USDA Animal Welfare Act licensing elevates consumer trust in commercial facilities over informal neighborhood arrangements.
- Overnight Boarding:Extended-stay accommodation with 24-hour staffing and overnight monitoring commands premium pricing near airport-adjacent locations. Business travel resumption around Atlanta and Dallas aviation hubs concentrates demand for luxury boarding with webcam access and personalized activity reporting.
- Grooming Services:Spa-style bathing, coat maintenance, and nail care bundled with daycare visits.
- Training Sessions:Certified staff-led behavioral modification and obedience instruction.
Volume sits with Daycare Services; growth tilts toward Overnight Boarding.
Animal Type:
Species-specific facility design requirements and owner demographic density shape addressable market per animal category.
- Dogs:Canine daycare infrastructure—climate-controlled indoor play areas, outdoor relief zones, and group socialization protocols—absorbs the majority of industry capex. Urban millennial and Gen Z ownership in Boston and Washington D.C. now expects livestream webcam availability as standard amenity rather than premium upsell.
- Cats:Feline-specific suites with vertical climbing structures and separate ventilation systems represent an emerging margin pool. Cat ownership density in Manhattan, Chicago, and Seattle apartment markets remains underserved by dog-centric facility designs.
- Birds:Avian boarding requiring specialized cage configurations and noise isolation.
- Others:Small mammal and reptile accommodation in limited specialized facilities.
Dogs anchor current revenue; cats are climbing the fastest as urban apartment living rises.
Facility Size:
Capital intensity and regulatory compliance burden scale disproportionately with square footage and animal capacity.
- Small Facilities:Under 2,500 square feet with limited outdoor access and minimal staff specialization. Municipal zoning in Los Angeles and San Francisco restricts facility square footage and outdoor relief zone proximity to residential districts.
- Medium Facilities:Mid-scale operations balancing capacity planning sophistication with walk-in volume flexibility.
- Large Facilities:Campus-style locations consolidating multiple smaller sites to meet New York and California tightening staff-to-animal ratio mandates.
- Luxury Facilities:Premium-positioned campuses with spa amenities, telemedicine integration, and guaranteed reservation priority. Paradise 4 Paws anchors this tier through airport-adjacent locations targeting traveling professionals.
Medium facilities hold volume concentration; luxury campuses gain share fastest through consolidation.
Pricing Model:
Predictability preference among frequent users is displacing transactional flexibility across urban markets.
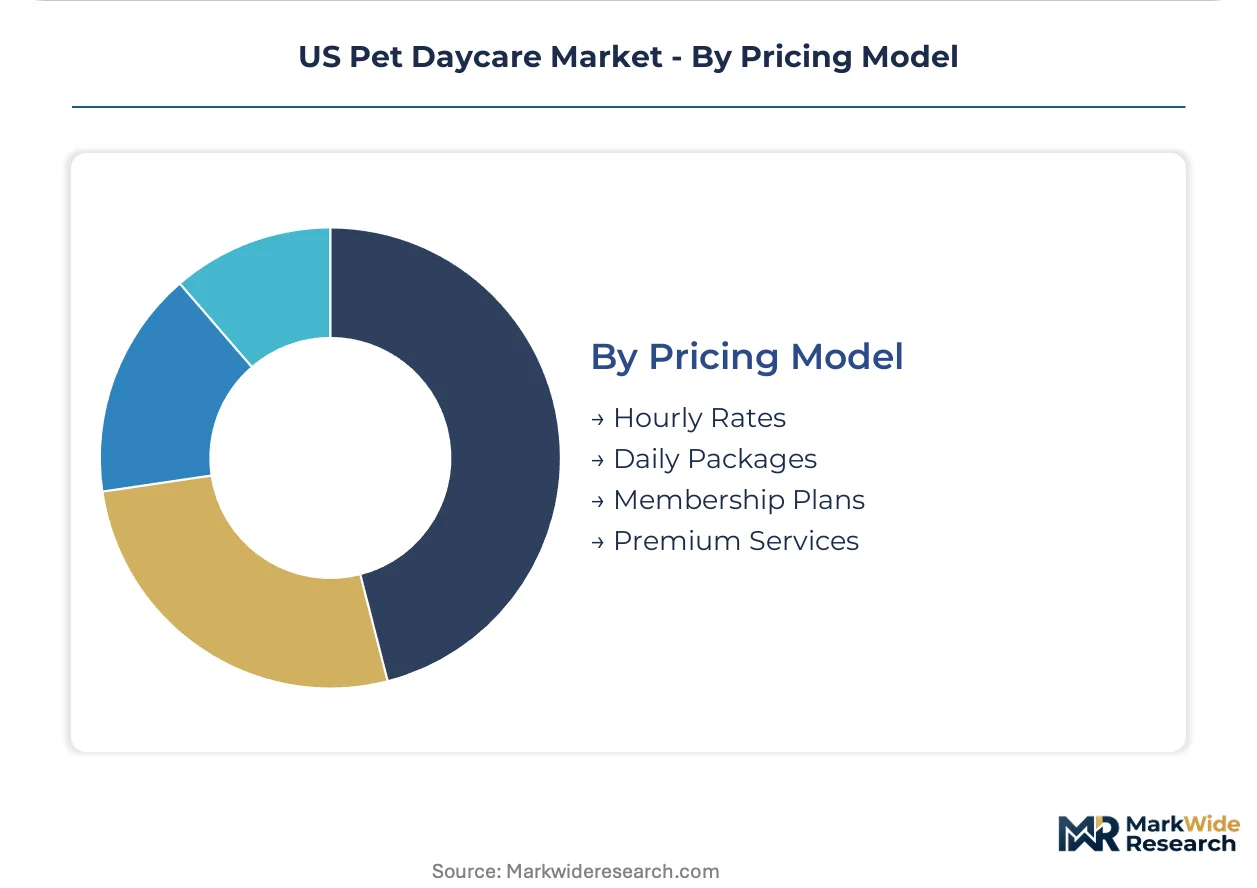
- Hourly Rates:À la carte pricing for sporadic users with volatile scheduling needs. Gig-economy pet sitting platforms undercut this tier on price, fragmenting demand away from brick-and-mortar facilities.
- Daily Packages:Bundled per-day pricing for intermittent but planned usage.
- Membership Plans:Unlimited monthly access with guaranteed reservation priority. Dog owners in Austin and Denver increasingly prefer this structure over à la carte booking, rewarding operators with capacity planning sophistication.
- Premium Services:Upsold amenities including webcam access, personalized reporting, and spa treatments.
Daily packages retain volume leadership; membership plans show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dual-income households without children concentrate demand in Texas metro corridors and coastal urban centers, while regulatory tightening in California and New York reshapes facility economics across state lines.
Texas
Dallas-Fort Worth and Houston anchor the fastest-expanding customer base among dual-income millennial households. Municipal zoning in Austin permits higher facility density than coastal counterparts, enabling faster permit acquisition. Airport-adjacent luxury campuses near Dallas Love Field and Houston Hobby concentrate extended-stay boarding demand from business travelers.
California
Los Angeles and San Francisco municipal ordinances restrict facility square footage and outdoor relief zone proximity to residential districts. The state's Department of Agriculture enforces facility inspection protocols that elevate compliance costs. Premium operators in Brooklyn and Oakland face eighteen-month retrofit timelines or license non-renewal.
New York
Manhattan apartment density drives emerging demand for feline-specific daycare suites underserved by dog-centric designs. State-level kennel technician certification requirements outpace vocational program graduation rates. Brooklyn facility operators consolidate smaller locations into larger compliant campuses to meet tightening staff-to-animal ratio mandates.
Colorado
Denver metro corridors show steep expansion in subscription membership structures over à la carte booking. Denver and Boulder facilities reward capacity planning sophistication with unlimited monthly access models. Mountain West migration patterns concentrate pet ownership among remote-working professionals seeking behavioral enrichment services.
Massachusetts
Greater Boston urban millennial buyers now expect livestream webcam availability as standard amenity rather than premium upsell. Massachusetts municipal animal welfare boards monitor staff-to-animal ratios with increasing scrutiny. Cambridge and Somerville facilities absorb connectivity costs or cede position to franchise networks with centralized IT platforms.
US Pet Daycare Market Key Industry Players
Texas-based operators anchor one tier; coastal specialists hold premium positioning through airport-adjacency and technology integration. The market exhibits tiered concentration with franchise networks commanding national footprint against independent single-site operators. Three archetypes dominate: membership-model franchises, luxury airport-adjacent campuses, and gig-economy platform intermediaries. Consolidation accelerates through multi-site acquisition and centralized IT platform deployment.
Within the franchise tier, Dogtopia Enterprises and Camp Bow Wow exemplify scale-driven national expansion through standardized protocols. Paradise 4 Paws, LLC occupies a position among luxury airport-adjacent specialists targeting traveling professionals with extended-stay boarding and webcam infrastructure. These three entities represent divergent strategic vectors: membership volume, premium location, and technology-enabled owner engagement.
| Leading Market Players |
|---|
| A Place for Rover, Inc. |
| Paradise 4 Paws, LLC |
| Dogtopia Enterprises |
| Come Sit Stay |
| Camp Run-A-Mutt Entrepreneurial Resources |
| Camp Bow Wow |
| Fetch! Pet Care |
| Barkley Ventures, Inc. |
| PetSmart LLC |
| Others |
Cost & Logistics Intelligence
Licensed kennel technician wages absorb disproportionate facility operating budgets, cascading from labor recruitment markets through membership-model pricing tiers to compress margins at mid-scale operators lacking volume scale.
Pricing Analysis
Volume concentrates in daily package transactions while margin expansion tilts toward unlimited monthly membership structures. Pricing stratifies across luxury campuses with webcam infrastructure, standard facilities with basic supervision, and economy tiers vulnerable to gig-economy pet sitting platforms. Cost compression in mid-tier operations is intensifying because veterinary technician wage inflation outpaces revenue per animal. Price-sensitive sporadic users fragment toward hourly-rate alternatives, while least-sensitive frequent buyers lock in subscription priority.
Supply Chain Analysis
USDA Animal Welfare Act certification gates facility licensing and shapes upstream equipment procurement standards. HVAC system manufacturers in Texas, Illinois, and Georgia dominate climate-control hardware supply for indoor play areas. Construction materials and specialized animal welfare fixtures draw from regional building supply networks concentrated in Sun Belt metro corridors. Single-source vulnerability sits with certified kennel technician training programs in New York and Texas, where vocational graduation rates lag facility expansion. Distribution runs through direct equipment vendor relationships and franchise-network centralized procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as operators pursue captive control over certified staffing pipelines to defend margin position against wage inflation.
For Market Incumbents: Acquire vocational training program partnerships or in-house certification academies to secure licensed kennel technician supply. Consolidate smaller non-compliant locations into larger campus-style facilities before California and New York retrofit deadlines force exit. Home-based pet sitting platforms threaten price-sensitive demand tiers; membership volume and guaranteed reservation priority defend retention against gig-economy alternatives. For New Entrants and Emerging Players: Launch via feline-specific daycare suites in Manhattan, Chicago, and Seattle apartment corridors where cat ownership density outpaces dog-centric facility supply. Target airport-adjacent luxury positioning near Dallas-Fort Worth and Houston aviation hubs where business travel resumption concentrates extended-stay boarding demand. White-space penetration favors telemedicine-integrated operations that reduce emergency transport costs and extend service continuity. For Investors and Strategic Acquirers: Municipal zoning liberalization in housing-constrained cities is the leading indicator that facility density constraints will ease, unlocking greenfield expansion velocity. Over a multi-year horizon, acquisition targets center on multi-site operators with centralized IT platforms and compliance-ready campuses in Texas metro corridors. Watch for staff-to-animal ratio mandate tightening in additional states as the signal for accelerated consolidation among sub-scale independents.| Strategic Initiative | Industry Significance |
|---|---|
| Campus Consolidation | Combines smaller locations into compliant facilities meeting California and New York outdoor relief zone mandates. |
| Membership Model Deployment | Replaces transactional pricing with unlimited monthly access and guaranteed reservation priority in Austin and Denver corridors. |
| Telemedicine Integration | Enables remote veterinary triage during daycare hours, reducing emergency transport costs for facilities. |
| Feline-Specific Suite Development | Captures emerging margin pool in Manhattan, Chicago, and Seattle apartment markets underserved by dog-centric designs. |
| OSHA Compliance Investment | Differentiates operators for corporate partnership programs and insurance premium reductions through staff injury prevention protocols. |
Research Approach
USDA Animal Welfare Act licensing databases, state Department of Agriculture inspection records, and municipal zoning filings formed the secondary backbone for facility count and compliance status verification. Primary interviews with franchise operations directors, independent facility owners, certified kennel technicians, and veterinary behaviorists supplied operating cost structures and staffing constraint data. Bottom-up facility-by-facility capacity modeling triangulated against top-down metro corridor demand estimates derived from dual-income household demographics.
Bottom-up segmentation modeling across service type, animal type, facility size, and pricing model dimensions generated volume and value outputs across the projection horizon. CAGRs were derived from regression analysis of historical facility penetration rates against demographic and regulatory trend vectors. Forecast inputs incorporated veterinary technician wage trajectory assumptions and municipal zoning liberalization probability assessments for housing-constrained cities.
Labor market tightening in certified kennel technician pools, accelerated municipal animal welfare mandate adoption, and gig-economy platform pricing erosion are the dominant revision risks that could compress facility expansion assumptions. A model refresh is warranted upon material change in state-level kennel technician certification requirements or federal Animal Welfare Act enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Hats Market
Pet Care Products
Netherlands Pet Boarding Market
Pet Care Products
Mink Oil Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Pet Food Nutraceutical Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Household Pet Water Dispenser Market
Pet Care Products
Dog Boot for Winters Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Pet Cups Market
Pet Care Products
Pet Transporting Service Market
Pet Care Products
United States Organic and Natural Pet Food Market
Pet Care Products
Therapeutic Diet for Pet Market