
 Netherlands Pet Food Market | 2026-2036
Netherlands Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Pet Food Market Insights
Urban millennial pet owners are reorganizing the Netherlands pet food landscape by shifting volume toward premium nutrition and subscription-based replenishment. Royal Canin leverages its veterinary channel dominance to sustain prescription diet loyalty across Dutch clinics and specialty retailers. Prins Petfoods anchors local production capacity with a focus on cold-pressed manufacturing and domestic sourcing protocols. Yarrah Organic Petfood differentiates through certified organic positioning and transparent supply chain credentials that resonate with Dutch sustainability expectations.
Netherlands pet food encompasses formulated nutritional products manufactured to meet species-specific dietary requirements through extrusion, baking, or wet-cooking processes, with formulations governed by FEDIAF nutritional guidelines and EU feed hygiene standards. Dry food occupies the largest volume share due to shelf stability and cost efficiency in mass retail channels, while wet food commands margin concentration among aging pet demographics with palatability sensitivities. The super premium tier within price-based segmentation records the fastest value expansion as functional ingredients and veterinary endorsement reshape purchasing criteria.
The Netherlands Food and Consumer Product Safety Authority enforces EU Regulation 183/2005 on feed hygiene, mandating HACCP protocols and ingredient traceability that elevate compliance costs for imported brands. Dutch implementation of the EU Green Deal targets carbon footprint reduction in pet food protein sourcing, pressuring manufacturers toward alternative protein transitions. Stakeholders must monitor evolving NVWA enforcement patterns on novel ingredient approvals and assess whether local production investments or third-party certification partnerships offer more durable competitive insulation.
Market Dynamics
Urban millennial pet owners in the Randstad corridor are compressing purchase cycles toward subscription-based replenishment, forcing manufacturers to reconfigure distribution infrastructure around direct-to-consumer fulfillment rather than traditional retail stocking.
Growth Catalysts
- NVWA traceability mandates:The Netherlands Food and Consumer Product Safety Authority enforces EU Regulation 183/2005 feed hygiene standards, compelling domestic manufacturers to upgrade HACCP protocols and creating compliance barriers that favor established local producers over importers.
- Cold-pressed manufacturing:This nutrient-preservation process is gaining traction among Dutch specialty producers seeking differentiation from mass-market extrusion, attracting premium-seeking owners of aging companion animals with digestive sensitivities.
- Amsterdam-Rotterdam urban corridor:Concentrated millennial pet ownership in these Randstad cities generates disproportionate demand for veterinary-endorsed prescription diets and organic-certified formulations.
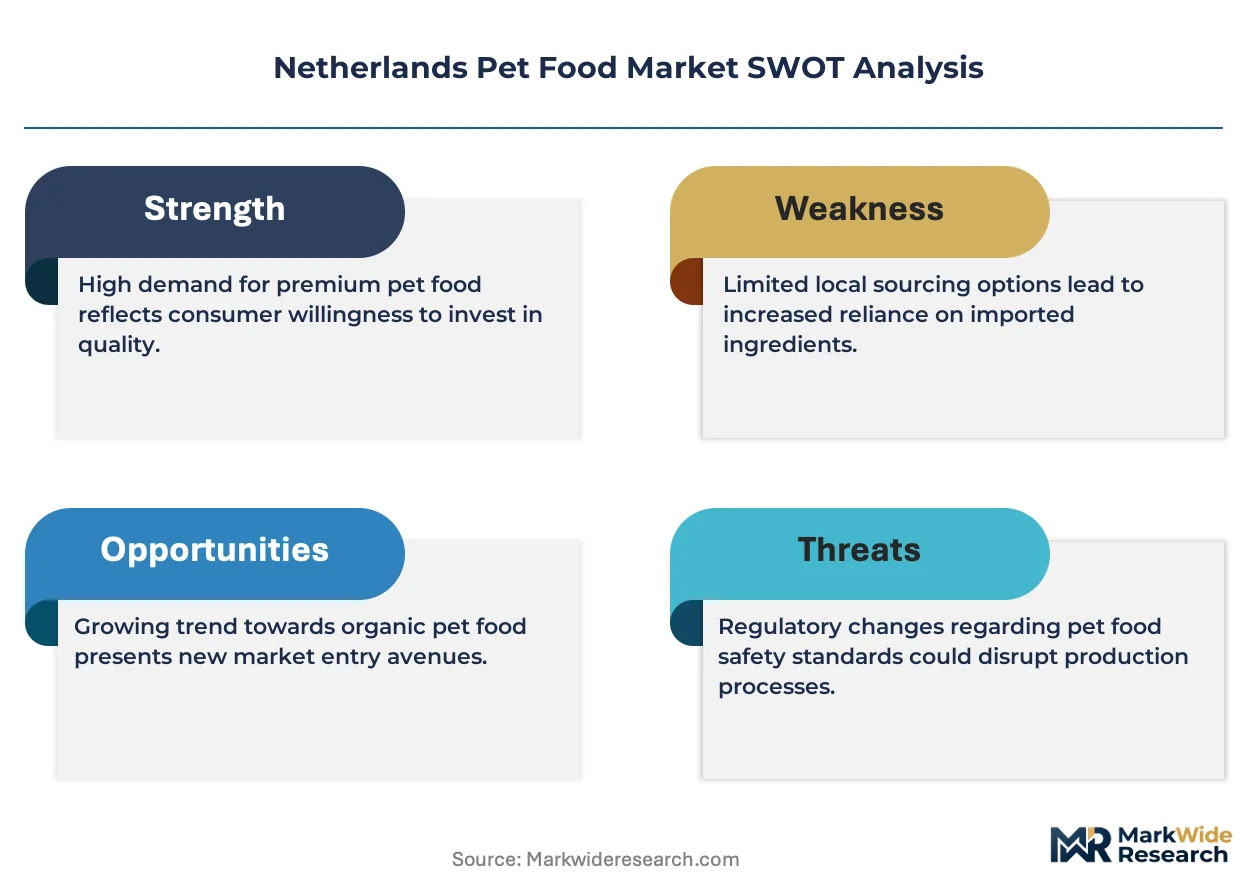
Market Restraints
- Protein input cost volatility:Dutch manufacturers face margin pressure from fluctuating poultry and fish meal prices, compounded by EU Green Deal carbon footprint reduction targets that constrain conventional livestock sourcing.
- Ingredient import dependency:Limited domestic production of novel proteins like insect meal forces reliance on Belgian and German suppliers, creating supply concentration risk.
- Regulatory friction from novel ingredient approvals:NVWA evaluation timelines for alternative proteins delay product launches, extending time-to-market for innovative formulations.
Strategic Opportunities
- Underpenetrated Utrecht satellite municipalities:Peripheral Randstad communities show lower premium pet food penetration than Amsterdam or Rotterdam, presenting whitespace for localized subscription services.
- EU Green Deal protein transition incentives:Carbon reduction mandates create regulatory tailwinds for manufacturers investing in cultivated or plant-based protein research.
- Veterinary clinic channel integration:Direct partnerships with Dutch companion animal practices enable bypass of mass retail markup structures.
Industry Challenges
- Specialized nutrition formulation talent scarcity:Dutch universities produce insufficient veterinary nutritionists to staff expanding R&D functions across domestic manufacturers.
- Legacy ERP integration with subscription platforms:Established producers struggle to retrofit batch-manufacturing systems for direct-to-consumer demand forecasting.
- Organic certification timeline compression:SKAL Biocontrol evaluation backlogs delay product launches for brands pursuing certified organic positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Pet Food Market |
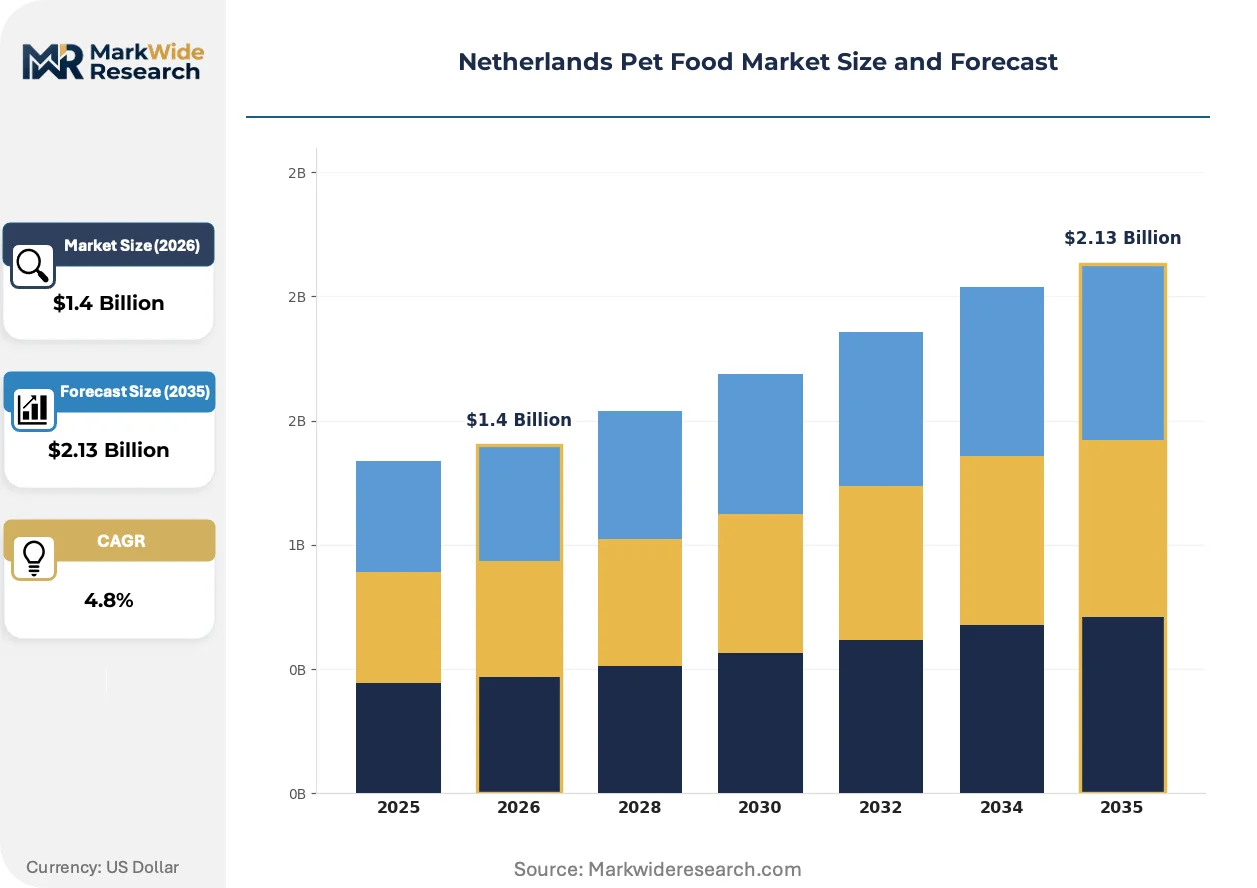
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Snacks Animal Type: Dogs, Cats, Birds, Small Mammals Distribution Channel: Supermarkets, Pet Stores, Online Retailers, Specialty Shops Price Tier: Premium, Mid-range, Economy, Super Premium |
| Companies Covered | Royal Canin, Pedigree, Hill's Pet Nutrition, Nestlé Purina, Mars Petcare, Prins Petfoods, Farmina Pet Foods, Yarrah Organic Petfood, Bonzo, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Pet Food Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel transformation as Dutch pet food manufacturers respond to compressed consumer purchase cycles and tightening ingredient provenance requirements.
Cold-pressed manufacturing technology preserves heat-sensitive nutrients through low-temperature processing below 45 degrees Celsius. Dutch specialty producers are adopting this method to serve aging pet populations with compromised digestive efficiency. The technology is fragmenting production scale economics, enabling smaller regional facilities to compete with centralized extrusion plants on quality metrics rather than volume.
EU Green Deal carbon footprint reduction mandates are reshaping protein sourcing protocols across Dutch manufacturing. The regulation requires documented lifecycle assessments for feed ingredients, elevating compliance costs for imported conventional proteins. Wet food formulations with alternative protein bases face accelerated NVWA scrutiny, prompting domestic producers to accelerate in-house cultivation research.
Subscription-based replenishment is displacing periodic retail purchasing among Randstad millennial owners. Direct-to-consumer platforms capture recurring revenue through automated portion-calibrated deliveries, compressing traditional supermarket and specialty store volume. This shift concentrates most visibly in Amsterdam and The Hague, where urban density supports efficient last-mile logistics.
Netherlands Pet Food Market Segmentation
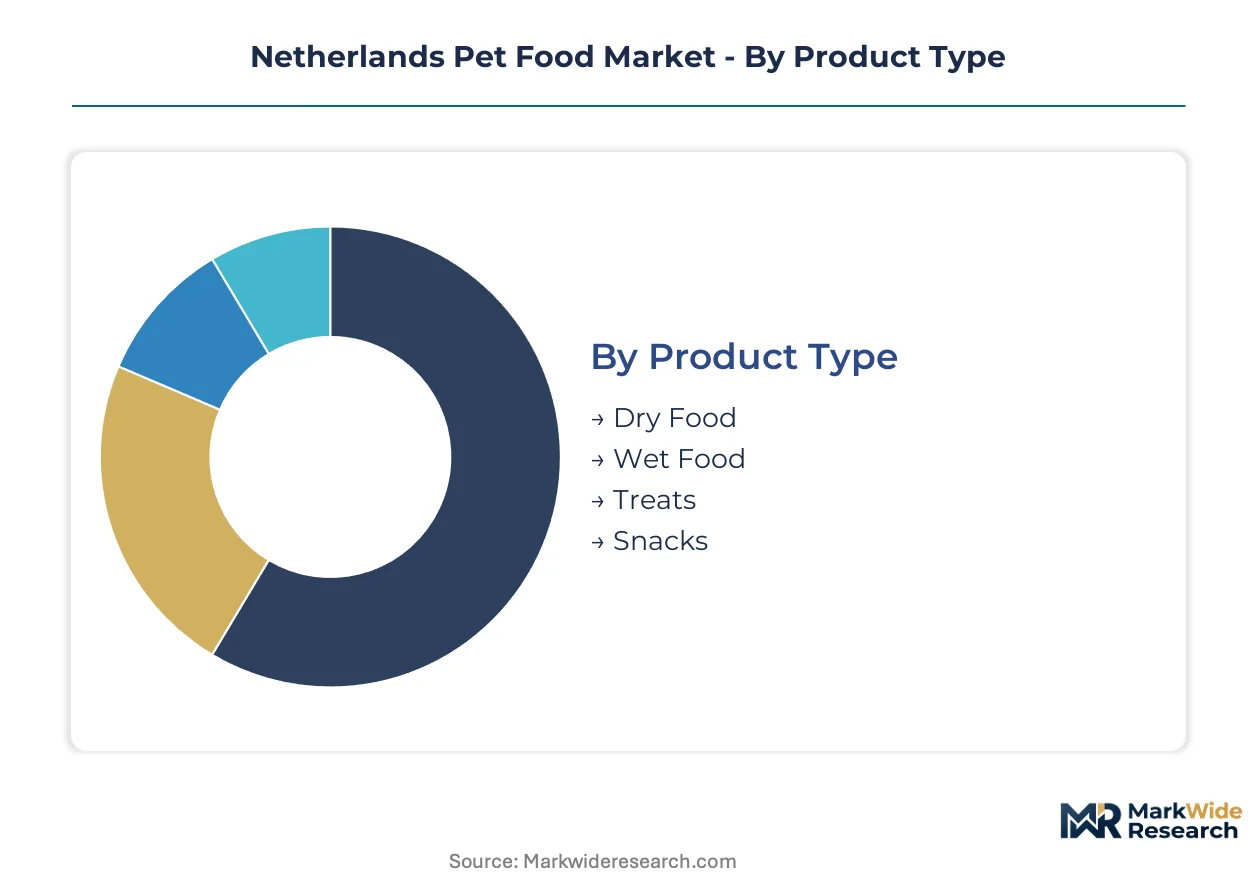
Segmentation in the Netherlands pet food market reveals how NVWA compliance costs, Randstad urban density, and millennial purchasing patterns reshape profitability across product tiers and channels. Manufacturers must align formulation investments with the specific margin structures each segment rewards.
Product Type:
Margin pools concentrate in formats where processing complexity creates defensible differentiation against mass-market competition.
- Dry Food:Extruded kibble formulations deliver shelf-stable nutrition through high-temperature processing above 90 degrees Celsius. Randstad supermarkets move the largest absolute volumes, though margin compression from private-label competition limits profitability for non-specialized producers.
- Wet Food:Moisture-rich formulations preserved through retort canning or aseptic pouch filling command substantial premiums among aging pet populations in The Hague and Utrecht. NVWA thermal processing documentation requirements elevate compliance costs that smaller importers struggle to absorb.
- Treats:Functional reward products incorporating dental or joint-support ingredients attract discretionary spending from Amsterdam millennial owners seeking training reinforcement tools.
- Snacks:Air-dried meat strips and freeze-dried protein pieces serve intermittent indulgence occasions with minimal nutritional claim overhead.
The dominant share belongs to Dry Food, while Wet Food is closing the gap fastest.
Animal Type:
Species-specific formulation requirements determine where R&D investment generates sustainable returns versus commodity competition.
- Dogs:Canine nutrition spans size-specific life-stage formulations from puppy growth diets to senior joint-support recipes. Amsterdam and Rotterdam generate disproportionate demand for fresh-frozen raw alternatives that bypass conventional extrusion economics.
- Cats:Obligate carnivore physiology mandates higher protein minimums and taurine fortification, creating formulation barriers that reward specialized manufacturers. Utrecht satellite municipalities show accelerating premium cat food adoption as remote-work pet ownership rises.
- Birds:Seed blends and pellet formulations for psittacines and passerines occupy niche volumes concentrated in specialty retail channels.
- Small Mammals:Rodent and lagomorph nutrition requires fiber-optimized formulations with limited margin expansion potential relative to companion carnivores.
Canine nutrition commands the largest revenue base, though feline formulations are expanding most quickly as single-person households proliferate across Randstad cities.
Distribution Channel:
Channel selection determines whether manufacturers capture recurring subscription revenue or compete on periodic promotional pricing.
- Supermarkets:Albert Heijn and Jumbo dominate mass-market volume through private-label and national brand shelf placement, though slotting fees and promotional depth erode net margins for suppliers without scale.
- Pet Stores:Specialized retailers including Pets Place and independent shops provide consultative selling environments where veterinary-endorsed and organic-certified SKUs achieve price realization unavailable in grocery.
- Online Retailers:Bol.com and dedicated pet platforms enable direct-to-consumer subscription models with automated replenishment algorithms calibrated to individual pet consumption rates.
- Specialty Shops:Independent boutiques in Amsterdam Jordaan and Rotterdam Kralingen curate super-premium and raw-frozen assortments for discerning urban owners.
Supermarket volume leadership persists, yet Online Retailers are gaining share fastest as millennial purchasing migrates to subscription platforms.
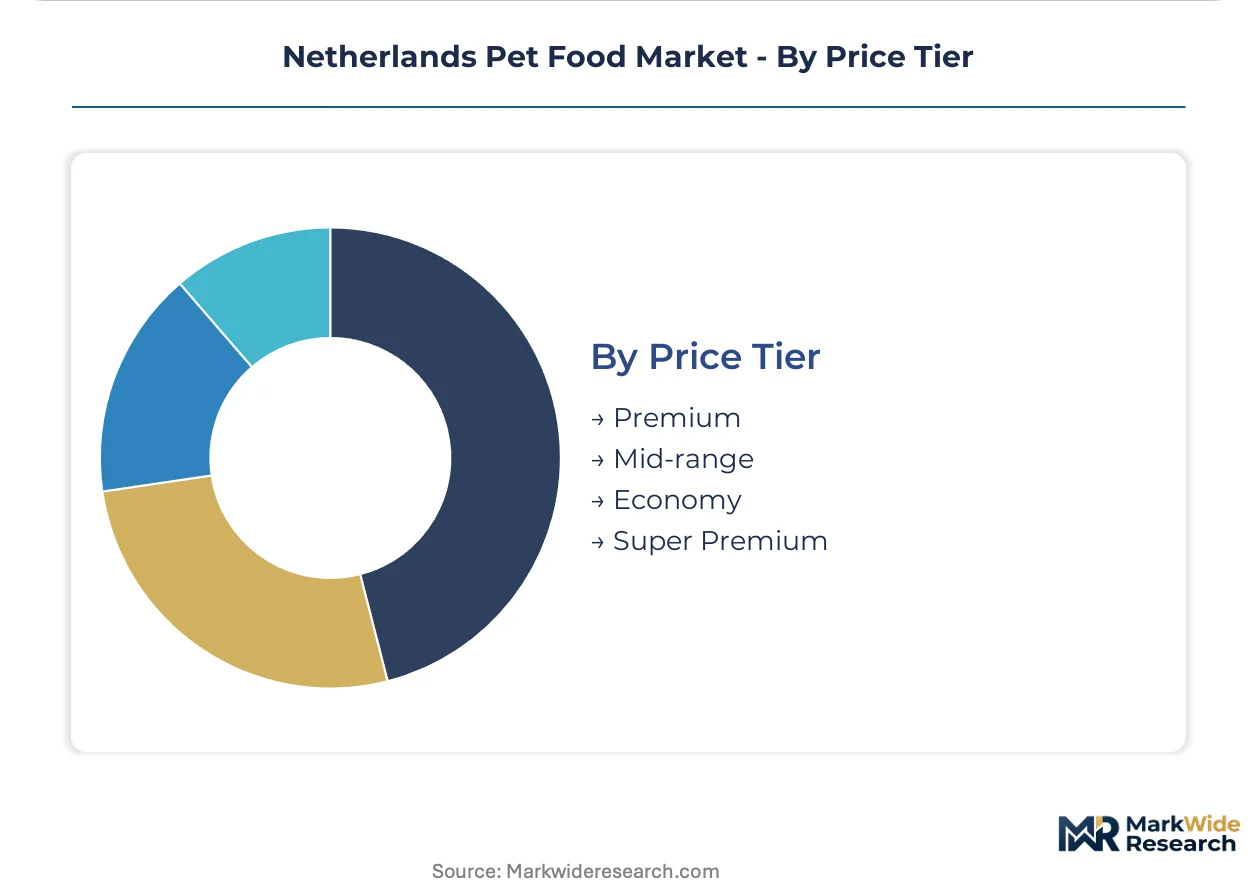
Price Tier:
Premiumization dynamics concentrate value creation at tier extremes while mid-range positioning faces squeeze from above and below.
- Premium:Veterinary-endorsed formulations with functional ingredient claims achieve price premiums through clinic channel authorization and retail recommendation programs.
- Mid-range:National brand extruded products compete primarily on promotional intensity with limited differentiation beyond packaging recognition.
- Economy:Private-label offerings from supermarket chains capture price-sensitive volume with minimal marketing investment and standardized formulations.
- Super Premium:Cold-pressed, organic-certified, and alternative-protein formulations target Amsterdam and The Hague owners prioritizing ingredient provenance over cost efficiency. SKAL Biocontrol certification timelines and NVWA novel ingredient approvals create supply constraints that sustain pricing power for qualified entrants.
Premium tier volume remains largest, though Super Premium is climbing the fastest as sustainability credentials reshape purchasing criteria among Randstad millennials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial pet owners in Randstad urban centers concentrate disproportionate purchasing power toward premium nutrition and subscription-based replenishment models.
Randstad Urban Corridor
Amsterdam, Rotterdam, The Hague, and Utrecht generate the densest concentration of premium pet food demand in the Netherlands. NVWA enforcement of EU Regulation 183/2005 elevates compliance costs for imported formulations. Amsterdam Jordaan boutiques curate super-premium organic assortments that bypass conventional retail economics.
Brabant Manufacturing Belt
Eindhoven and Tilburg host specialized cold-pressed production facilities serving aging pet populations with digestive sensitivities. SKAL Biocontrol certification protocols create supply constraints for organic positioning. Regional manufacturers leverage proximity to Belgian ingredient suppliers to reduce novel protein procurement lead times.
Northern Netherlands
Groningen and Friesland exhibit lower premium penetration but accelerating e-commerce adoption among remote-work households. EU Green Deal carbon footprint mandates pressure conventional livestock sourcing from regional agricultural networks. Local distributors test subscription fulfillment models targeting underpenetrated satellite municipalities.
Netherlands Pet Food Market Competitive Landscape
Player mix skews toward multinational nutrition specialists with veterinary channel dominance and domestic organic-certified specialists with localized production footprints. Market structure exhibits tiered consolidation where prescription diet authorization creates defensive moats for clinic-anchored brands. Two strategic archetypes predominate: multinational pharmaceutical-nutrition hybrids leveraging veterinary endorsement networks, and domestic cold-pressed specialists emphasizing ingredient traceability. Dominant competitive moves include vertical integration into alternative protein cultivation and direct-to-consumer platform development bypassing retail markup structures.
Among veterinary-anchored multinationals, Royal Canin and Hill's Pet Nutrition exemplify prescription diet authorization models that sustain clinic channel loyalty. Within the domestic specialist tier, Prins Petfoods and Yarrah Organic Petfood occupy positions defined by manufacturing method differentiation and certified organic supply chain credentials respectively. These four anchors illustrate how competitive positioning fragments across authorization-based versus provenance-based value propositions.
| Leading Market Players |
|---|
| Royal Canin |
| Pedigree |
| Hill's Pet Nutrition |
| Nestlé Purina |
| Mars Petcare |
| Prins Petfoods |
| Farmina Pet Foods |
| Yarrah Organic Petfood |
| Bonzo |
| Others |
Pricing and Supply Chain Analysis
Insect meal substitution for conventional poultry and fish proteins is simultaneously redrawing procurement geography toward Belgian and German suppliers and compressing margin structures across Dutch manufacturing tiers as NVWA novel ingredient approval timelines extend cost recovery horizons.
Pricing Analysis
Extrusion-generation pricing gaps separate mass-market kibble from cold-pressed premium tiers and emerging alternative-protein next-generation formulations. Three-tier pricing structure across premium, standard, and economy levels dominates, with SKAL Biocontrol certification and veterinary endorsement serving as primary price differentiation drivers. Cost compression in mid-range extruded products is intensifying because private-label competition from Albert Heijn and Jumbo erodes brand premiums. Economy-tier buyers in peripheral Randstad municipalities exhibit highest price sensitivity, while Amsterdam and The Hague owners of aging pets show lowest sensitivity to super-premium positioning.
Supply Chain Analysis
Just-in-time raw material sourcing prevails among Dutch extrusion plants serving supermarket channels, while strategic stockpiling of certified organic ingredients characterizes cold-pressed specialists managing SKAL Biocontrol audit windows. Geographic supply concentration centers on Belgium and Germany for insect meal and novel proteins, with domestic Dutch rendering facilities providing conventional poultry by-products. Raw material dependencies include fish meal from North Sea fisheries, poultry meal from regional agricultural networks, and imported plant protein isolates. Single-source vulnerability in Belgian insect meal suppliers creates supply chain risk. Distribution runs through Albert Heijn and Jumbo for mass-market volume, with dedicated pet platforms capturing subscription-based replenishment in urban corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Netherlands pet food represents an early-cycle expansion story where subscription-based replenishment penetration among Randstad millennials creates durable recurring revenue pools that traditional retail channels cannot replicate.
For Market Incumbents: Compound veterinary channel loyalty through exclusive prescription diet formulations that NVWA traceability mandates make difficult for importers to replicate. Deepen backward integration into alternative protein cultivation to reduce Belgian supplier concentration risk. Prioritize SKAL Biocontrol certification investments that create supply-constrained pricing power in organic segments.
For New Entrants and Emerging Players: Lead with direct-to-consumer subscription platforms targeting underpenetrated Utrecht satellite municipalities where premium pet food adoption lags Amsterdam and Rotterdam. Capture whitespace in fresh-frozen raw alternatives for aging canine populations. Deploy veterinary clinic partnerships as primary go-to-market angle to bypass mass retail slotting fee barriers.
For Investors and Strategic Acquirers: The market sits at a premiumization phase that favors domestic cold-pressed specialists with captive organic certification pipelines over multinational commodity players. Long-term viability over the next decade hinges on regulatory navigation capabilities around NVWA novel ingredient approvals and EU Green Deal protein transition compliance. Monitor SKAL Biocontrol evaluation backlog durations as inflection indicator for organic segment supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Manufacturing Scale-Up | Prins Petfoods and regional specialists preserve nutrient integrity for aging pet digestive sensitivities. |
| Alternative Protein Cultivation Investment | In-house insect meal production reduces dependency on Belgian suppliers and accelerates NVWA approval timelines. |
| Direct-to-Consumer Platform Launch | Subscription algorithms calibrated to individual pet consumption rates capture recurring revenue from Randstad millennials. |
| Veterinary Clinic Channel Integration | Royal Canin and Hill's sustain prescription diet loyalty through exclusive clinic authorization networks. |
| SKAL Biocontrol Certification Program | Yarrah Organic Petfood leverages transparent supply chain credentials to command pricing premiums in Amsterdam boutiques. |
Research Methodology
Operator-level perspectives from pet food manufacturing executives, veterinary clinic procurement managers, SKAL Biocontrol certification officers, and Albert Heijn category buyers anchored the qualitative base. Secondary validation drew from NVWA enforcement bulletins, EU Regulation 183/2005 implementation guidance, FEDIAF nutritional guideline updates, and Dutch customs trade data on feed ingredient imports. Bottom-up volume modeling across manufacturing facilities triangulated with top-down expenditure estimates from household pet ownership surveys.
Sensitivity analysis tested alternative protein adoption curves and NVWA approval timeline scenarios across the projection horizon. Segmentation dimensions modeled include product format, animal species, distribution channel, and price tier, with regional density patterns across Randstad urban corridors serving as an additional geographic dimension. CAGRs were derived from trend extrapolation of premiumization rates and subscription penetration patterns, incorporating EU Green Deal carbon footprint mandate compliance costs as industry-specific forecast inputs.
Forecasts assume regulatory continuity in NVWA enforcement patterns and EU feed hygiene standards; material policy shifts would require re-modeling. Specific risk factors include SKAL Biocontrol evaluation backlog extensions, Belgian supplier concentration disruptions, and millennial household formation rate variations. Revision becomes warranted when alternative protein approval timelines exceed baseline assumptions or subscription churn rates cross thresholds that invalidate recurring revenue models.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Sunglasses Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Canada Pet Boarding Market
Pet Care Products
Pet Collar Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
USA Bird Food Market
Pet Care Products
Pet Treats Market
Pet Care Products
Dog Food for Small Breeds Dogs Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
Aquarium Market
Pet Care Products
Frozen and Freeze-Dried Pet Food Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
Insulated Dog House Market
Pet Care Products
North America Pet Food Market