
 Global Pet Supplies Market | 2026-2036
Global Pet Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Supplies Market Outlook
AAFCO nutritional adequacy protocols is collapsing the window for new entrants lacking verified feeding-trial data or laboratory analysis credentials. Mars Petcare leverages captive ingredient sourcing and in-house veterinary research centers to sustain formulation leadership across therapeutic and premium tiers. Nestlé Purina PetCare anchors North American production scale with vertically integrated protein rendering and extrusion assets. Hill's Pet Nutrition differentiates through prescription diet exclusivity and veterinary channel control.
Pet supplies encompass formulated nutrition, containment systems, hygiene implements, and prophylactic health inputs engineered to species-specific metabolic profiles, behavioral needs, and life-stage requirements. The category serves commercial breeders, veterinary clinics, and individual households maintaining companion animal welfare standards. Food commands the dominant value pool as fresh and raw formats displace conventional kibble, while health supplements represent the fastest-expanding margin segment driven by functional ingredient positioning around joint, digestive, and cognitive health. E-commerce displaces supermarket and specialty store volumes as subscription auto-ship models capture recurring purchase behavior and reduce customer acquisition costs.
FDA Center for Veterinary Medicine oversight, AAFCO model feed regulations, and EU F-Gas packaging directives collectively elevate compliance burdens for ingredient traceability, therapeutic claim substantiation, and sustainable material transitions. The EU Green Deal and emerging state-level extended producer responsibility laws in California and New York further tighten packaging recyclability mandates. Stakeholders must monitor regulatory divergence between jurisdictions while calibrating R&D allocation toward clinically validated functional nutrition and circular packaging solutions.
Market Dynamics
Pet humanization is compressing purchase cycles and elevating ingredient scrutiny beyond AAFCO minimums, forcing manufacturers to rebuild formulation pipelines around fresh proteins and clinically validated functional additives.
Growth Catalysts
- EU F-Gas packaging mandates:Refrigeration-dependent fresh pet food formats gain shelf space as sustainable cold-chain infrastructure expands under regulatory pressure.
- Veterinary channel consolidation:Prescription diet authorization through clinic networks locks in recurring revenue streams for therapeutic nutrition suppliers.
- China's dual carbon goals:Domestic manufacturers accelerate plant-based protein trials to align with national emissions reduction frameworks.
Market Restraints
- Animal protein cost volatility:Rendering supply tightness and feed-grade competition from human food processing squeeze margin stability.
- Single-source supplier concentration:Specialty amino acid and omega-3 ingredient production clusters in coastal Chinese chemical parks.
- AAFCO feeding-trial requirements:New entrants lacking verified laboratory analysis credentials face extended time-to-market for complete diet claims.
Strategic Opportunities
- Brazilian veterinary service underpenetration:Clinic density in secondary cities remains below saturation thresholds for prescription diet distribution.
- Cell-cultured protein convergence:Bioreactor technology intersects with pet food formulation to bypass conventional rendering entirely.
- India PLI scheme for food processing:Central government incentives reduce capital barriers for domestic extrusion and packaging capacity.
Industry Challenges
- Veterinary nutritionist talent scarcity:Board-certified specialists command premium compensation, constraining in-house R&D scaling.
- Legacy ERP integration friction:Batch traceability systems struggle to interface with e-commerce fulfillment platforms for subscription auto-ship models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Supplies Market |
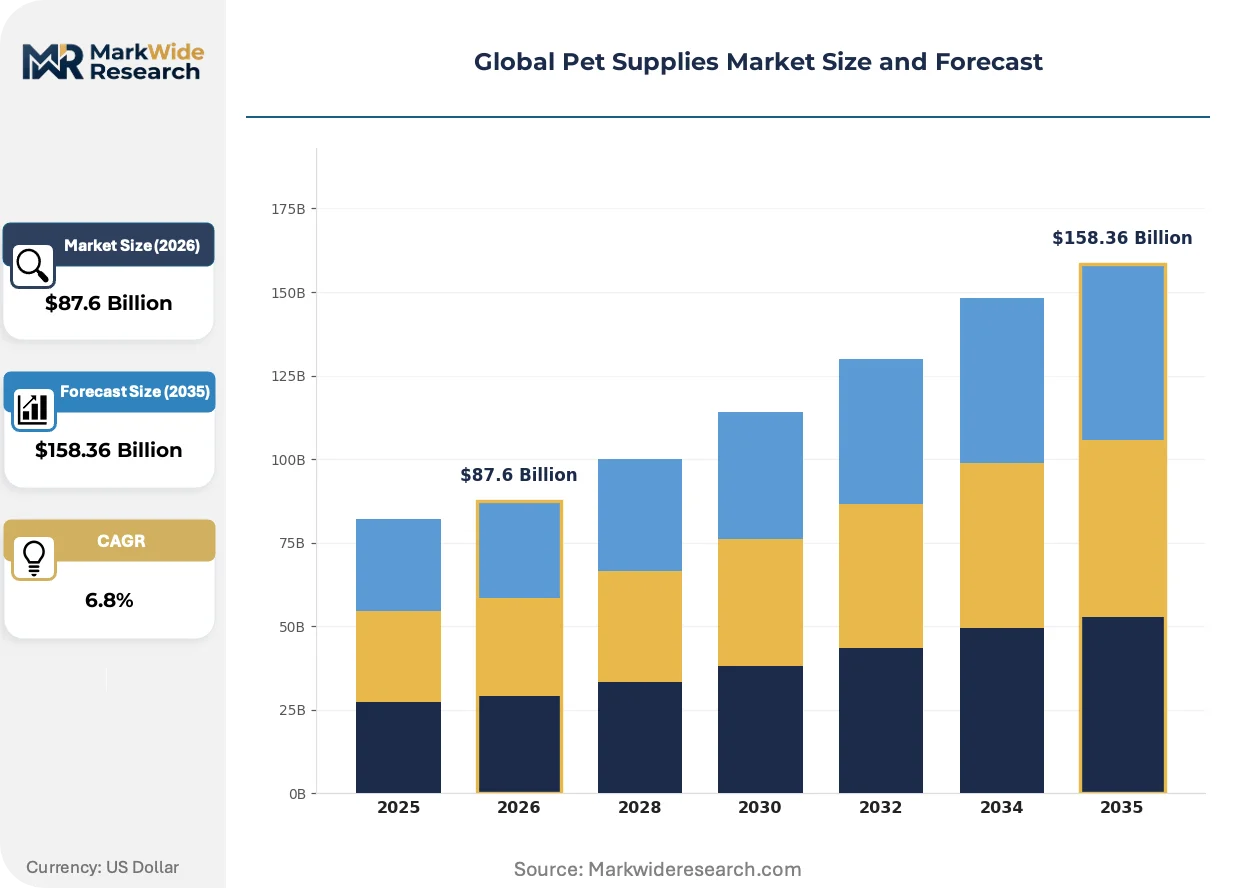
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food, Accessories, Grooming Products, Health Supplements Customer Type: Pet Owners, Retailers, Veterinarians, Online Shoppers Distribution Channel: Supermarkets, E-Commerce, Specialty Stores, Wholesalers End User: Dogs, Cats, Birds, Small Animals |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, Central Garden & Pet, Chewy, PetSmart, KONG Company, Coastal Pet Products, Spectrum Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Supplies Market Strategic Shifts
Formulation science and distribution infrastructure are diverging from commodity kibble economics toward precision nutrition and direct-to-consumer logistics. Three forces are compressing the traditional value chain.
High-pressure processing (HPP) is supplanting thermal extrusion for raw and fresh pet food categories. Premium-positioned manufacturers in the United States and Germany deploy HPP lines to eliminate pathogens without nutrient degradation. This technology is enabling refrigerated retail placement and subscription delivery models that bypass conventional dry-grocery shelf negotiation entirely.
REACH chemical registration requirements in Europe are forcing reformulation of synthetic preservatives and artificial colorants. Manufacturers serving EU export markets accelerate natural antioxidant sourcing from tocopherol and rosemary extract suppliers. Wet food and treat segments face the steepest compliance timelines as existing stock-keeping units require label revision.
Subscription auto-ship procurement is consolidating purchase decisions away from impulse supermarket browsing. Millennial and Gen Z households in the United States and United Kingdom pre-commit to 4-8 week replenishment cycles, compressing brand-switching opportunities. Direct-to-consumer platforms capture lifetime value data that informs predictive formulation and personalized supplement bundling.
Global Pet Supplies Market Segmentation
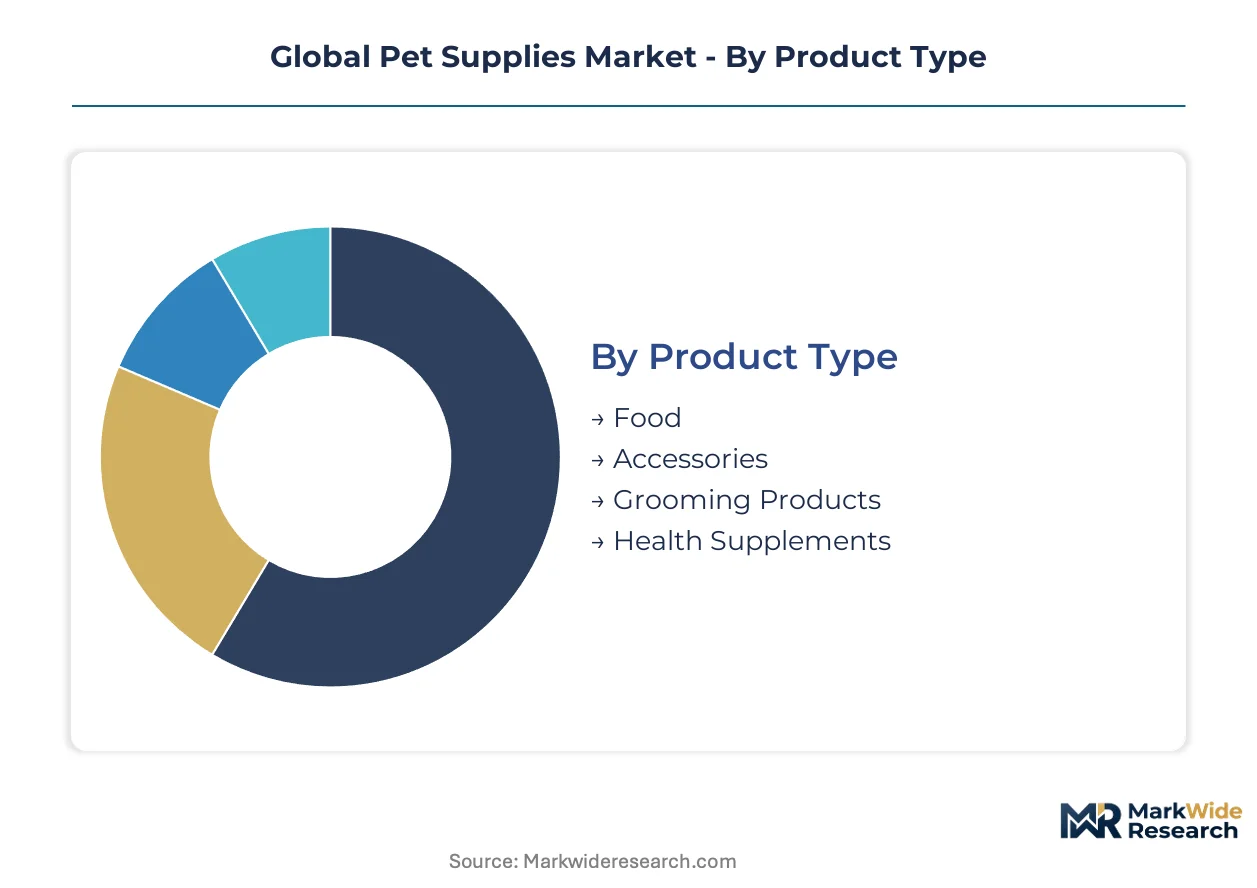
Segmentation in pet supplies determines margin capture and channel strategy. Product format dictates regulatory pathway, while distribution choice locks in customer acquisition cost structures. Understanding where each segment concentrates geographically exposes sourcing vulnerabilities and growth vectors.
Product Type:
Domestic production dominates shelf-stable categories across developed markets. Export-led growth concentrates in premium fresh formats and functional nutrition targeting affluent Asian households.
- Food:Formulated nutrition spans dry extruded kibble, wet retorted cans, and refrigerated fresh formats. Demand concentrates in the United States and Germany where AAFCO and EU F-Gas regulations respectively elevate cold-chain infrastructure investment. FDA feeding-trial requirements compress time-to-market for therapeutic claims.
- Health Supplements:Functional inputs targeting joint mobility, digestive microbiome balance, and cognitive preservation in aging animals. Veterinary channel authorization in the United States and United Kingdom drives prescription-grade positioning. REACH chemical registration in Europe forces natural antioxidant substitution.
- Accessories:Containment systems, bedding, and behavioral enrichment implements. Chinese manufacturing clusters supply global private-label programs.
- Grooming Products:Coat conditioners, dental implements, and hygiene solutions. Specialty store distribution in Japan and South Korea sustains premium positioning.
Food commands the established base. The steepest expansion runs through Health Supplements.
Customer Type:
Cost tier stratification separates mass-market volume from premium-margin relationships. Direct-to-consumer platforms capture lifetime value data that wholesale relationships cannot access.
- Pet Owners:Individual households purchasing for companion animal welfare. Subscription auto-ship adoption among Millennial and Gen Z demographics in the United States and United Kingdom compresses brand-switching behavior.
- Veterinarians:Clinic networks prescribing therapeutic nutrition and prophylactic health inputs. Prescription diet exclusivity agreements in the United States lock in recurring revenue streams.
- Online Shoppers:Platform-native consumers prioritizing convenience and personalized bundling. Predictive algorithms inform formulation adjustments.
- Retailers:Supermarket and specialty store buyers negotiating shelf placement and promotional calendars. Private-label pressure intensifies in German and French mass-market channels.
Pet Owners generate the volume foundation. Veterinarians deliver the margin expansion trajectory.
Distribution Channel:
Volume concentration shifts from physical retail toward digital fulfillment. E-commerce penetration rates diverge sharply between urban China and rural United States markets.
- E-Commerce:Direct-to-consumer platforms and marketplace aggregators. Subscription auto-ship models in the United States capture recurring purchase behavior and reduce customer acquisition expenditure.
- Supermarkets:Mass-market dry grocery placement for conventional kibble formats. Shelf negotiation concentrates purchasing power among Walmart, Tesco, and Carrefour networks.
- Specialty Stores:Independent and chain retailers emphasizing premium positioning and staff expertise. German Fressnapf and United States Petco networks sustain specialty nutrition authority.
- Wholesalers:Bulk distribution to commercial breeders and multi-site veterinary groups. Brazilian secondary cities remain underpenetrated relative to saturation thresholds.
Supermarkets retain the volume base. E-Commerce posts the steepest share gain.
End User:
Species-specific metabolic requirements dictate formulation complexity and regulatory scrutiny. Canine and feline nutrition attracts disproportionate R&D allocation relative to volume share.
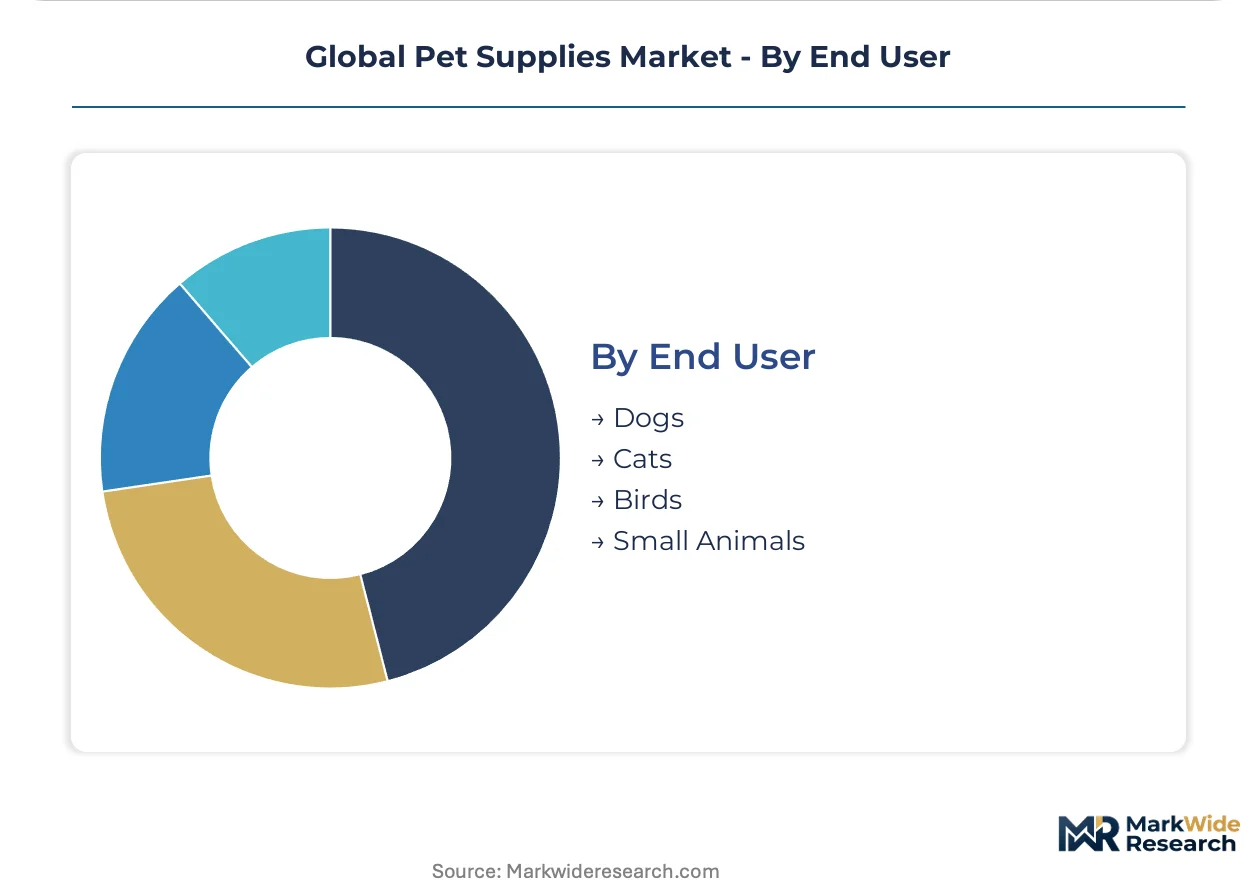
- Dogs:Omnivore-adapted formulations spanning life-stage and activity-level variations. Large-breed joint health positioning drives supplement attachment in the United States.
- Cats:Obligate carnivore protein requirements elevating fresh and raw format adoption. Taurine and arachidonic acid fortification mandates under AAFCO protocols.
- Birds:Seed, pellet, and foraging enrichment categories. Avian veterinary specialization scarcity constrains clinical claim substantiation.
- Small Animals:Rabbit, rodent, and reptile categories. Niche volume limits dedicated manufacturing infrastructure investment.
Dogs anchor the revenue base. Cats deliver the fastest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy frameworks and carbon reduction mandates are redirecting manufacturing investment toward domestic capacity expansion in major consumption centers. Veterinary channel density and cold-chain infrastructure quality now separate high-margin markets from volume-driven regions.
United States
Millennial and Gen Z pet owners compress purchase cycles through subscription auto-ship platforms while demanding fresh protein formats. FDA Center for Veterinary Medicine oversight elevates compliance costs for therapeutic claim substantiation. Kansas and Iowa host concentrated extrusion and rendering infrastructure serving North American distribution networks.
China
Affluent urban households in Shanghai and Beijing drive premium nutrition adoption alongside rapid e-commerce penetration. Dual carbon goals under national emissions frameworks accelerate plant-based protein trials among domestic manufacturers. Yangtze River Delta chemical parks concentrate specialty amino acid and omega-3 ingredient production.
Germany
EU F-Gas packaging mandates and Green Deal recyclability requirements reshape cold-chain infrastructure investment for refrigerated formats. REACH chemical registration forces natural antioxidant substitution in synthetic preservative formulations. Bavaria and North Rhine-Westphalia anchor specialty retail networks including Fressnapf's vertically integrated distribution.
Brazil
Veterinary service underpenetration in secondary cities creates whitespace for prescription diet distribution expansion. ANVISA regulatory alignment with international standards accelerates import substitution for therapeutic nutrition. São Paulo state concentrates commercial breeding operations and wholesale distribution hubs.
India
Central government PLI scheme for food processing reduces capital barriers for domestic extrusion and packaging capacity expansion. FSSAI nutritional labeling requirements tighten as premium formats gain traction in metropolitan markets. Maharashtra and Gujarat host emerging manufacturing clusters serving domestic and export demand.
Global Pet Supplies Market Competitive Environment
Player mix skews toward multinational nutrition conglomerates with captive ingredient sourcing and veterinary channel control. Tiered competition separates prescription-authorized therapeutic suppliers from mass-market private-label operators. Strategic archetypes include vertically integrated protein renderers, direct-to-consumer subscription platforms, and specialty retail consolidators. Dominant competitive moves center on veterinary clinic network acquisition and high-pressure processing line deployment for fresh format expansion.
Within the multinational nutrition tier, Mars Petcare and Nestlé Purina PetCare exemplify scale-driven archetypes with in-house research infrastructure. Hill's Pet Nutrition occupies a position emphasizing prescription diet exclusivity. Among platform-native distributors, Chewy represents the subscription auto-ship model capturing recurring purchase behavior. Central Garden & Pet anchors diversified portfolio positioning across supplies and live goods categories.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Central Garden & Pet |
| Chewy |
| PetSmart |
| KONG Company |
| Coastal Pet Products |
| Spectrum Brands |
| Others |
Value Chain & Pricing Dynamics
AAFCO feeding-trial certification gates both supplier qualification and price stratification in therapeutic nutrition tiers. Manufacturers lacking verified laboratory analysis credentials face extended time-to-market, compressing margin capture for non-compliant entrants while concentrating pricing power among established players with captive veterinary research infrastructure.
Pricing Analysis
Certification level creates the primary spread between prescription-grade therapeutic diets and mass-market private-label alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects AAFCO protocol adherence, veterinary channel authorization, and cold-chain infrastructure investment. Pricing pressure stems from rendering supply tightness and feed-grade competition from human food processing squeezing margin stability in conventional kibble tiers. Mass-market retailers exhibit highest price sensitivity, while veterinary clinic networks accept premium positioning for clinically validated functional formulations.
Supply Chain Analysis
China and the United States anchor global supply for specialty amino acids and extrusion equipment respectively. Yangtze River Delta chemical parks concentrate omega-3 and taurine production, while Kansas and Iowa host rendering and extrusion infrastructure serving North American distribution. Raw material dependencies include animal protein render, plant-based protein isolates, and synthetic vitamin premixes. Single-source supplier concentration in coastal Chinese chemical parks creates tariff exposure and logistics chokepoint vulnerability. Distribution runs through veterinary clinic networks for therapeutic tiers and direct-to-consumer subscription platforms for fresh format categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-pressure processing technology convergence with cold-chain regulatory mandates is compressing traditional extrusion economics and opening white-space for precision nutrition platforms.
For Market Incumbents: Compound formulation leadership through captive high-pressure processing line deployment and veterinary clinic network acquisition. Mars Petcare and Nestlé Purina PetCare should accelerate in-house rendering capacity to offset animal protein cost volatility threatening margin stability in conventional kibble tiers. Prescription diet exclusivity agreements lock in recurring revenue streams against emerging cell-cultured protein substitutes. For New Entrants and Emerging Players: Differentiate on subscription auto-ship personalization and Brazilian veterinary service underpenetration. Secondary cities in São Paulo state remain below saturation thresholds for prescription diet distribution, creating whitespace for clinic network partnerships. Direct-to-consumer platforms capturing lifetime value data inform predictive formulation adjustments that bypass incumbent wholesale relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed direct-to-consumer subscription platforms and regional rendering cooperatives. Five-to-ten year viability hinges on cold-chain infrastructure scalability and regulatory alignment with EU F-Gas packaging mandates. Watch for cell-cultured protein cost parity signals as inflection indicator for conventional rendering asset obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Deployment | Enables refrigerated retail placement and subscription delivery models bypassing conventional shelf negotiation. |
| Veterinary Clinic Network Acquisition | Locks in prescription diet authorization and recurring revenue streams through therapeutic nutrition exclusivity. |
| Natural Antioxidant Sourcing Transition | Addresses REACH chemical registration requirements forcing tocopherol and rosemary extract substitution in EU markets. |
| Plant-Based Protein Trial Acceleration | Aligns domestic Chinese manufacturing with national dual carbon goals under tightening emissions frameworks. |
| Subscription Auto-Ship Platform Buildout | Captures Millennial and Gen Z recurring purchase behavior while reducing customer acquisition expenditure. |
Study Parameters
A spread of perspectives from veterinary nutritionists, pet food manufacturing executives, retail category buyers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with AAFCO committee members and FDA Center for Veterinary Medicine officials alongside secondary validation through EU F-Gas regulatory filings, SEC 10-K disclosures from publicly traded pet care conglomerates, and customs trade data on amino acid imports. Bottom-up volume modeling from individual product formats triangulated against top-down macroeconomic indicators.
Segmentation dimensions modeled span product type, customer archetype, distribution channel, and end-user species across the projection horizon. CAGRs derive from regression analysis against pet ownership demographic shifts, e-commerce penetration trajectories, and regulatory compliance cost escalations. Forecast inputs incorporate veterinary channel consolidation rates and cold-chain infrastructure investment cycles specific to refrigerated fresh format adoption.
Material uncertainties — animal protein cost volatility, REACH chemical registration timeline extensions, and veterinary nutritionist talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory alignment between FDA and EU frameworks without anticipating divergence. Recalibration cycles align with material shifts in dual carbon goal implementation and cell-cultured protein commercialization milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Hoodies Market
Pet Care Products
Brazil Cat Litter Market
Pet Care Products
Bird Toy Market
Pet Care Products
Dog Clippers Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Global Kennel Software Market
Pet Care Products
Thunder Jacket for Dogs Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Pet Supplement Market
Pet Care Products
Dog Vest Market
Pet Care Products
South America Pet Treats Market