
 North America Deodorants Market | 2026-2036
North America Deodorants Market Size, Share, and Industry Trends Forecast 2026-2036
North America Deodorants Market Outlook
REACH compliance obligations for imported fragrance precursors is rebalancing the cost-of-entry calculus for new entrants seeking shelf space in Canadian and US retail channels. Unilever PLC leverages its North American manufacturing footprint to sustain cost advantages across mass-market stick formats. The Procter & Gamble Company anchors premium positioning through clinical-strength variants with extended protection claims. Beiersdorf AG differentiates via dermatological testing protocols that command placement in drugstore therapeutic aisles.
Deodorants are topical formulations containing antimicrobial agents, fragrance compounds, and moisture-absorbing bases designed to inhibit bacterial growth and mask body odor, typically delivered through aerosol propellant systems or solid wax-based carriers. Spray formats retain volume leadership in the United States due to consumer familiarity and rapid dry-down properties, though stick applications gain ground among travelers seeking TSA-compliant personal care items. Natural ingredient positioning captures accelerating shelf space in Whole Foods Market and Sprouts Farmers Market locations, while aluminum-free claims increasingly influence purchase decisions among pregnant consumers and breast health advocates. Online retailers now represent the fastest-growing distribution vector, with subscription models capturing recurring revenue from brand-loyal households.
The US FDA regulates antiperspirant-drug claims under monograph standards, while Health Canada's Natural and Non-prescription Health Products Directorate oversees cosmetic-therapeutic boundary classifications; California's Proposition 65 enforcement actions on phthalate content have forced reformulation timelines across multiple suppliers. The EPA's volatile organic compound limits on aerosol propellants constrain spray format innovation in California and northeastern states with adopted ozone standards. Stakeholders must monitor state-level chemical disclosure mandates that could fragment labeling requirements beyond federal harmonization.
Market Dynamics
The US FDA's evolving scrutiny of aluminum-based active ingredients is forcing reformulation investments across antiperspirant portfolios, while male grooming routines now embed deodorants as daily essentials rather than occasional purchases. This regulatory pressure intersects with generational demand shifts among millennial and Gen Z consumers in urban centers.
Growth Catalysts
- REACH compliance obligations:Imported fragrance precursors face stricter documentation requirements, rebalancing cost-of-entry calculus for new entrants seeking shelf space in Canadian and US retail channels.
- Natural ingredient positioning:Whole Foods Market and Sprouts Farmers Market locations now allocate accelerating shelf space to aluminum-free and plant-based formulations.
- TSA-compliant stick formats:Travelers increasingly favor solid wax-based carriers over aerosol propellant systems, driving format diversification among frequent flyers.
Market Restraints
- EPA volatile organic compound limits:Aerosol propellant constraints in California and northeastern states with adopted ozone standards fragment spray format innovation timelines.
- Propylene glycol supply concentration:Moisture-absorbing base ingredients depend on concentrated petrochemical feedstock suppliers, exposing margins to upstream volatility.
- Antimicrobial efficacy thresholds:Health Canada's Natural and Non-prescription Health Products Directorate maintains stringent cosmetic-therapeutic boundary classifications that delay product launches.
Strategic Opportunities
- Subscription commerce penetration:Online retailers now represent the fastest-growing distribution vector, with recurring revenue models capturing brand-loyal households.
- Dermatological aisle placement:Therapeutic positioning in drugstore channels commands premium pricing through clinical testing protocols.
- California Proposition 65 compliance:Phthalate-free reformulation investments create first-mover advantages among suppliers serving breast health advocates and pregnant consumers.
Industry Challenges
- Reformulation timeline compression:State-level chemical disclosure mandates threaten to fragment labeling requirements beyond federal harmonization, forcing parallel compliance tracks.
- Fragrance chemist talent scarcity:Specialized formulation expertise for natural antimicrobial alternatives commands premium compensation, constraining mid-tier brand innovation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Deodorants Market |
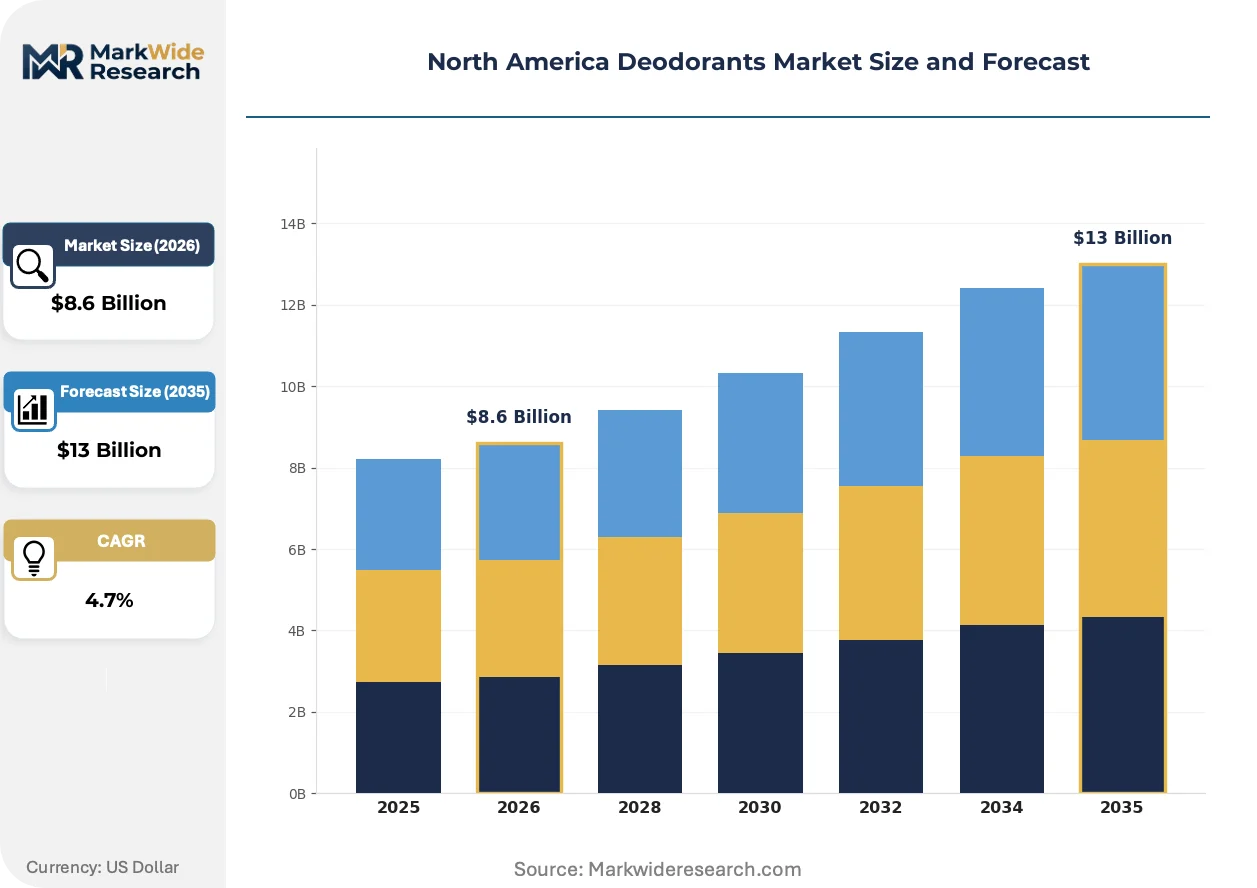
| Market Size in 2026 | $8.6 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spray, Stick, Roll-On, Gel Ingredient Type: Natural, Synthetic, Aluminum-Free, Fragrance-Free Distribution Channel: Supermarkets, Drugstores, Online Retailers, Convenience Stores End User: Women, Men, Unisex, Teens |
| Companies Covered | The Procter & Gamble Company, Unilever PLC, Colgate-Palmolive Company, Beiersdorf AG, L'Oréal S.A., Henkel AG & Co. KGaA, Johnson & Johnson, Church & Dwight Co., Inc., Reckitt Benckiser, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Deodorants Market Strategic Shifts
Reformulation science is pivoting toward microbiome-friendly actives as consumer skepticism of traditional antimicrobials deepens. This shift is compressing legacy product lifecycles while opening white space for biotechnology-derived alternatives.
Encapsulated fragrance release technology is modularizing scent delivery across stick and roll-on formats. Premium brands adopt microsphere systems for extended wear claims. The structural consequence is compressing differentiation timelines between mass and prestige tiers as manufacturing know-how diffuses.
California's Proposition 65 enforcement actions on phthalate content have forced accelerated reformulation timelines across multiple suppliers. Industrial consequence includes supplier qualification bottlenecks for fragrance houses. Aerosol and spray formats face the steepest compliance costs, driving portfolio rationalization toward solid carriers.
Millennial and Gen Z buyers now research ingredient transparency through mobile apps before in-store purchase. Drugstore and mass retail channels lose traffic to direct-to-consumer platforms with full formulation disclosure. Urban centers in the United States show the steepest channel shift velocity, particularly among consumers with household incomes above median thresholds.
North America Deodorants Market Segmentation
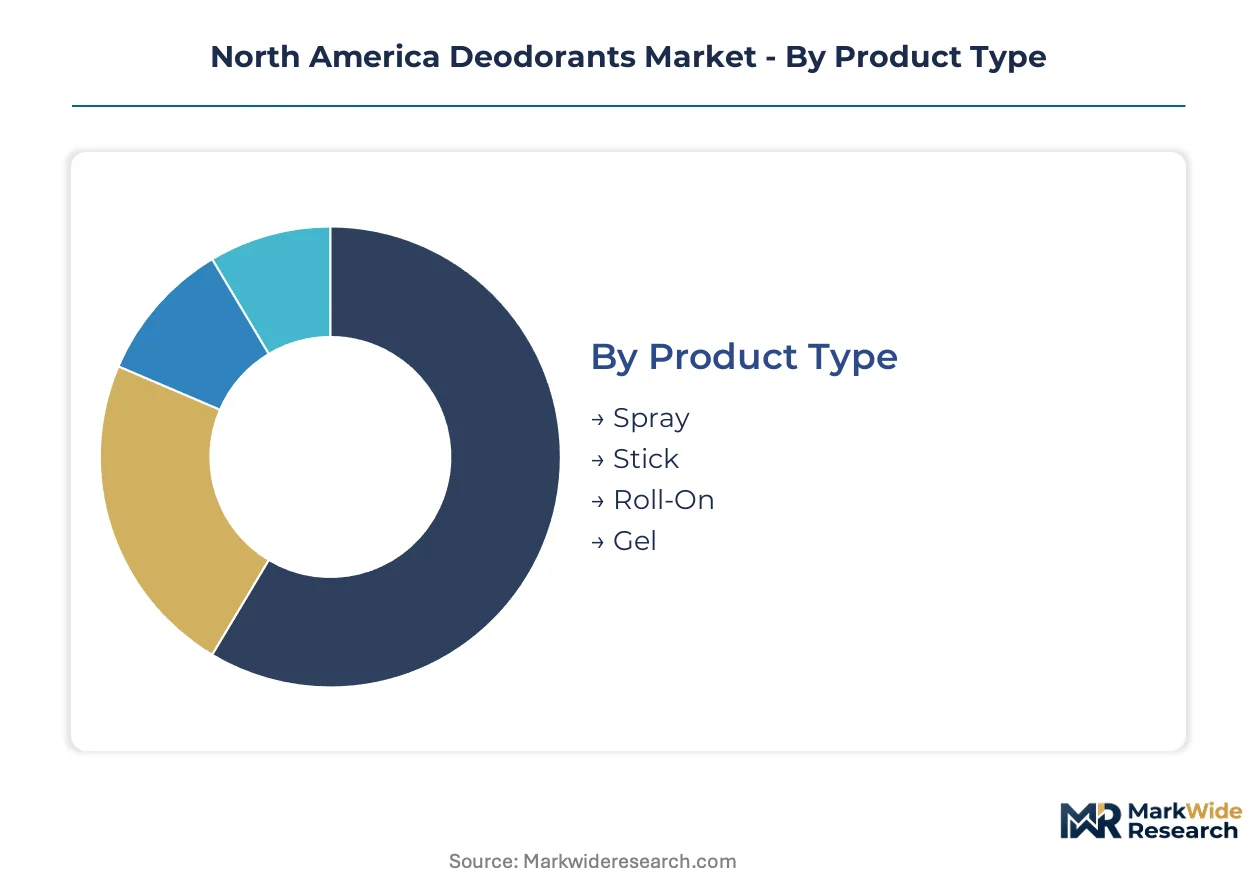
Deodorant manufacturers in North America navigate distinct demand profiles across formulation chemistry, delivery mechanism, and channel access. Segmentation clarity determines pricing architecture and regulatory compliance pathways for portfolio managers.
Product Type:
Spray formats operate as standalone daily-use items with established consumer habits, while stick and gel variants embed into travel and specialized grooming routines.
- Spray:Aerosol propellant systems deliver rapid dry-down through aluminum-based or aluminum-free actives suspended in volatile carriers. Demand concentrates in United States suburban households where application speed outweighs TSA restrictions; EPA volatile organic compound limits in California and northeastern states constrain new product development timelines.
- Stick:Solid wax-based carriers containing antimicrobial agents and moisture-absorbing bases provide portable, leak-resistant application. Travelers in United States urban centers favor this format for carry-on compliance, driving placement in airport retail and subscription commerce channels.
- Roll-On:Liquid formulations in ball-applicator packaging offer precise dosage control with lower propellant exposure.
- Gel:Transparent water-based suspensions that dry clear without residue, appealing to dark clothing preferences.
Volume placements concentrate in Spray; the faster expansion belongs to Stick.
Ingredient Type:
Cost tier stratification separates premium-positioned natural formulations from mass-market synthetic chemistry, with aluminum-free claims commanding shelf space premiums.
- Natural:Plant-derived antimicrobial extracts and essential oil fragrance systems replace petrochemical bases. Whole Foods Market and Sprouts Farmers Market locations in United States metropolitan areas allocate accelerating shelf space; FDA scrutiny of traditional actives accelerates reformulation investment toward botanical alternatives.
- Synthetic:Laboratory-engineered fragrance compounds and petrochemical-derived moisture absorbers dominate mass-market production economics. United States drugstore channels rely on synthetic chemistry for price-accessible daily use, though California Proposition 65 enforcement on phthalate content forces supplier qualification bottlenecks.
- Aluminum-Free:Formulations omitting aluminum salts target pregnant consumers and breast health advocates seeking to avoid antiperspirant drug claims.
- Fragrance-Free:Unscented variants serving sensitive skin populations and workplace scent policies.
Revenue concentrates in Synthetic; Natural climbs the fastest among ingredient-positioned segments.
Distribution Channel:
Channel selection determines margin structure, with direct-to-consumer platforms capturing subscription recurrence while mass retail sustains volume throughput.
- Supermarkets:High-frequency foot traffic drives impulse replenishment of familiar spray and stick formats. United States suburban and exurban locations maintain deodorant within personal care aisle adjacencies to shampoo and body wash; slotting fees favor established suppliers with manufacturing scale.
- Drugstores:Therapeutic positioning enables clinical-strength and dermatologically tested variants at premium price points. United States urban centers with concentrated millennial and Gen Z populations show steepest traffic migration toward mobile-enabled price comparison.
- Online Retailers:Subscription models capture recurring revenue from brand-loyal households with full formulation disclosure.
- Convenience Stores:Emergency replenishment and travel-size formats serve immediate-need occasions.
Transaction volume concentrates in Supermarkets; Online Retailers gain share fastest.
End User:
Gendered positioning is fragmenting as unisex formulations capture shelf space, though distinct scent profiles and packaging aesthetics maintain segment boundaries.
- Women:Fragrance-forward formulations with floral and fresh scent families, often combined with skin-conditioning additives. United States millennial consumers in urban centers research ingredient transparency through mobile applications before purchase, shifting traffic toward direct-to-consumer platforms.
- Men:Woody and aromatic scent profiles with sport and outdoor activity positioning. Male grooming routines in United States metropolitan areas now embed deodorants as daily essentials rather than occasional purchases, expanding usage frequency and premium willingness.
- Unisex:Neutral scent families and minimalist packaging appeal to household consolidation and shared consumption.
- Teens:Entry-price positioning with playful fragrance variants and social-media-influenced packaging.
Current revenue concentrates in Women; Men shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in Texas and California concentrate deodorant manufacturing assets through duty-deferred raw material processing, anchoring North American production capacity near petrochemical feedstock corridors and Pacific Rim fragrance ingredient gateways.
United States
Millennial and Gen Z consumers in New York, Los Angeles, and Chicago metro areas drive aluminum-free and natural formulation demand through mobile-enabled ingredient research. The FDA's ongoing monograph review of antiperspirant drug claims forces reformulation timelines across Cincinnati and Chicago manufacturing clusters. New Jersey's concentration of fragrance houses and compounding facilities supplies formulation expertise to mass-market and prestige brands.
Canada
Urban centers in Toronto and Vancouver show accelerating preference for TSA-compliant stick formats among cross-border business travelers. Health Canada's Natural and Non-prescription Health Products Directorate maintains stringent cosmetic-therapeutic boundary classifications that delay product launches for imported formulations. Quebec's personal care manufacturing base serves domestic distribution while exporting to US Northeast retail channels.
Mexico
Rising middle-class consumption in Mexico City and Monterrey expands mass-market spray format penetration through supermarket and convenience store channels. The country's national consumer protection regulator enforces labeling standards that align with US EPA volatile organic compound limits for cross-border product consistency. Baja California manufacturing facilities supply California and Southwest US markets with cost-competitive aerosol production.
North America Deodorants Market Competitive Environment
United States producers anchor the mass-market tier through integrated manufacturing and established retail slotting arrangements; European-headquartered specialists hold premium positioning through dermatological testing protocols and clinical-strength claims. The vendor structure concentrates around multinational consumer goods conglomerates with backward integration into fragrance compounding and propellant systems. Three strategic archetypes dominate: scale-driven mass-market suppliers, clinically positioned therapeutic brands, and natural-ingredient challengers accessing shelf space through specialty retail. Competitive dynamics center on reformulation speed to meet state-level chemical disclosure mandates and subscription commerce capacity to capture recurring revenue.
Within the scale-driven tier, Unilever PLC and The Procter & Gamble Company exemplify manufacturing footprint advantages and clinical-strength variant positioning respectively. Beiersdorf AG occupies a position in the therapeutic archetype through dermatological testing protocols that command drugstore aisle placement. These three entities represent the structural concentration defining competitive intensity across North American deodorant channels.
| Leading Market Players |
|---|
| The Procter & Gamble Company |
| Unilever PLC |
| Colgate-Palmolive Company |
| Beiersdorf AG |
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Johnson & Johnson |
| Church & Dwight Co., Inc. |
| Reckitt Benckiser |
| Others |
Value Chain & Pricing Dynamics
Propylene glycol spot prices on the US Gulf Coast feed directly into formulation cost structures, compressing margins for mid-tier brands while enabling scale players to absorb volatility through backward integration into petrochemical feedstock corridors.
Pricing Analysis
Lead-time premiums separate clinical-strength variants commanding drugstore placement from economy spray formats stocked for impulse replenishment. Three-tier pricing structure across premium dermatological, standard mass-market, and economy private-label levels reflects certification investment and channel slotting fee differentials. Cost compression in aluminum-free segments is intensifying as FDA scrutiny forces parallel reformulation tracks. Price-sensitive buyers cluster in supermarket channels, while subscription-loyal households show lowest sensitivity to per-unit increases.
Supply Chain Analysis
FDA and Health Canada qualification protocols gate fragrance precursor imports, creating supplier qualification bottlenecks that extend procurement timelines for natural antimicrobial alternatives. Manufacturing concentrates in the United States, Mexico, and Canada, with Baja California facilities serving California markets and New Jersey fragrance houses anchoring formulation expertise. Raw material dependencies rest on propylene glycol from Gulf Coast petrochemical corridors, aluminum salts from domestic mining operations, and encapsulated fragrance microspheres from European specialty suppliers. Tariff exposure on imported botanical extracts threatens natural-positioned portfolios. Distribution runs through mass retail slotting arrangements, direct-to-consumer subscription platforms, and airport travel retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where state-level chemical disclosure mandates and reformulation timeline compression force weaker capitalized players toward exit or acquisition.
For Market Incumbents: Anchor manufacturing scale advantages through captive supply of propylene glycol and aluminum salt precursors in Texas and Louisiana corridors. Defend shelf position by accelerating FDA-compliant reformulation pipelines before state disclosure mandates fragment labeling requirements. Prioritize subscription commerce infrastructure to lock recurring revenue against direct-to-consumer challengers.
For New Entrants and Emerging Players: The mid-market price-point gap between Unilever's mass-market sticks and Beiersdorf's therapeutic premiums opens white space for aluminum-free challengers with microbiome-friendly positioning. Target Sprouts Farmers Market and Whole Foods Market locations in Denver and Austin metros where natural ingredient velocity outpaces national averages. Pursue influencer-driven direct-to-consumer launches with full formulation disclosure to bypass slotting fee barriers.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap natural-positioned brands in California facing Proposition 65 compliance cost overruns but holding loyal subscription bases. Long-term viability hinges on reformulation agility across the 5-10 year regulatory evolution window. Watch for FDA monograph finalization on aluminum-based actives as the definitive margin compression inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Pipeline Acceleration | FDA monograph compliance ahead of state disclosure mandates protects shelf access in California and New York. |
| Subscription Commerce Infrastructure | Recurring revenue capture from brand-loyal households offsets slotting fee pressure in mass retail channels. |
| Backward Integration into Propylene Glycol | Gulf Coast petrochemical corridor control insulates margins from upstream volatility in moisture-absorbing bases. |
| Natural Ingredient Certification Investment | Whole Foods Market and Sprouts Farmers Market placement commands premium positioning in aluminum-free segments. |
| Dermatological Testing Protocol Expansion | Drugstore therapeutic aisle access enables pricing premiums through clinical-strength protection claims. |
Study Parameters
Multi-period observation of EPA volatile organic compound enforcement patterns and FDA monograph comment periods anchored the trend analysis, supplemented by interviews with brand managers at mass-market suppliers, category buyers at drugstore chains, supply planners at fragrance houses, and regulatory affairs leads at personal care manufacturers. Secondary validation drew from FDA docket filings, Health Canada Natural and Non-prescription Health Products Directorate guidance documents, California Proposition 65 enforcement actions, and Nielsen retail audit data. Bottom-up segment sizing triangulated against top-down market value estimates.
Input-output matrices mapped formulation chemistry, delivery mechanism, and channel access dimensions across the projection horizon, with CAGRs derived from regression analysis of historical volume trends and elasticity-adjusted demand drivers. Modeled inputs included millennial and Gen Z urban consumption velocity, TSA travel volume recovery patterns, and state-level regulatory adoption timelines for chemical disclosure mandates.
Inputs from EPA enforcement databases and FDA docket records were available through the study window; gaps in real-time subscription commerce transaction data introduce uncertainty bands around direct-to-consumer growth trajectories. Forecasts reflect documented assumptions regarding regulatory timeline continuity and consumer preference stability. A model refresh is warranted upon material change in FDA aluminum-based active ingredient classification.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Global Facial Cleanser Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
Asia-Pacific Face Compact Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Face Cream Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Cosmetic Mirror Market