
 Global Facial Cleanser Market | 2026-2036
Global Facial Cleanser Market Size, Share, and Industry Trends Forecast 2026-2036
Global Facial Cleanser Market Analysis
The male grooming vertical is consolidating into facial cleanser portfolios as men expand beyond basic soap routines into dedicated skincare regimens. L'Oréal dominates this transition through its mass-market men's lines, while Unilever competes with purpose-driven brands emphasizing sustainability credentials. Beiersdorf AG anchors its position in Central Europe through dermatologist-endorsed formulations, and Shiseido Company leads in Asia-Pacific with texture innovations tailored to humid climates.
A facial cleanser is a surfactant-based preparation designed to remove sebum, environmental pollutants, and cosmetic residues from skin surfaces, typically formulated at pH 4.5–6.5 to preserve the acid mantle. Foam formats command the largest volume share due to their sensory appeal and rinsing efficiency, though gel segments are gaining traction among oily-skin consumers seeking non-comedogenic options. Organic formulations carry premium positioning but face margin pressure from certification costs, while online retail channels are capturing share from pharmacies among repeat purchasers who bypass consultation needs.
The FDA regulates cosmetic labeling claims in the United States, restricting drug-like assertions without clinical substantiation, while REACH governs chemical safety assessments for European formulations. China's SAMR enforces pre-market registration for imported cosmetics, creating compliance barriers that favor local manufacturing partnerships. Stakeholders must monitor evolving microbiome-related claim regulations, as science-backed positioning in this area will determine next-generation product differentiation.
Market Dynamics
The male grooming segment is pulling formulation innovation toward pH-balanced surfactant systems that address sebum regulation without stripping barrier function. This demand pivot is restructuring R&D allocation across the competitive set.
Growth Catalysts
- EU Green Deal disclosure mandates:Ingredient transparency requirements are accelerating clean-label reformulation cycles as brands pre-empt compliance deadlines across member states.
- Microbiome science maturation:Clinical substantiation for skin flora claims is expanding into premium positioning, with dermatology clinics validating proprietary strain combinations.
- China domestic brand aggression:Local manufacturers leveraging SAMR registration familiarity are compressing multinational incumbents' shelf space in tier-one cities.
Market Restraints
- Organic certification cost inflation:Third-party verification fees for COSMOS and USDA Organic labels are squeezing margin structures for mid-tier producers.
- Surfactant feedstock volatility:Palm-derived and petrochemical-based cleansing agents face input price instability tied to Malaysian export policy fluctuations.
- SAMR import registration friction:Pre-market approval timelines for foreign cosmetics create working capital intensity that favors local manufacturing partnerships over direct export models.
Strategic Opportunities
- India tier-two urban penetration:Underdeveloped organized retail presence in cities like Indore and Lucknow offers first-mover positioning for mass-market gel formats.
- Subscription channel economics:Direct-to-consumer replenishment models are capturing repeat purchase loyalty that bypasses pharmacy consultation dependencies.
- ISO 16128 natural origin standards:Harmonized global frameworks for natural and organic content claims are reducing multi-market certification redundancy costs.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in mild surfactant synergy and preservative-free stability is concentrating among a limited pool of contract manufacturers.
- Clinical claim substantiation timelines:FDA scrutiny of drug-like assertions for acne-control cleansers extends product development cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Facial Cleanser Market |
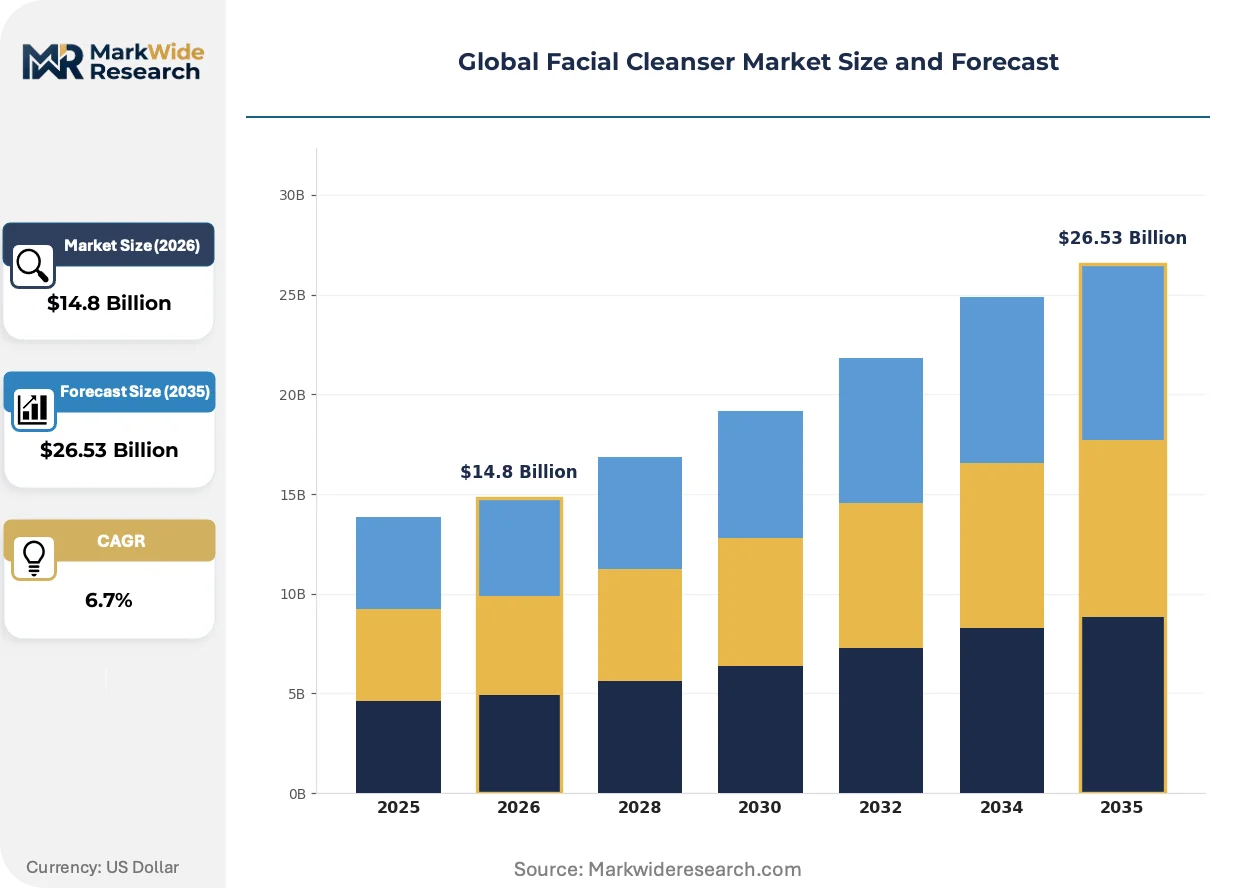
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam, Gel, Cream, Lotion Formulation: Organic, Paraben-Free, Exfoliating, Hydrating Target Audience: Teenagers, Adults, Seniors, Sensitive Skin Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal, Procter & Gamble, Unilever, Estée Lauder Companies, Johnson & Johnson, Beiersdorf AG, Shiseido Company, Kao Corporation, Coty Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Facial Cleanser Market Emerging Trajectories
Texture engineering and microbiome-targeted actives are displacing commodity surfactant formulations as the primary basis for competitive differentiation. These shifts are compressing legacy foam-format dominance while opening premium positioning vectors.
Postbiotic lysate technology is expanding into facial cleanser formulations as brands seek clinical credibility without live culture stability challenges. Dermatology-backed brands in Germany and South Korea are adopting these heat-stable ferments at accelerated pace. This convergence of cosmetic and therapeutic positioning is expanding into professional channel distribution that bypasses mass retail gatekeepers.
REACH Annex XVII restrictions on microplastic-containing rinse-off cosmetics are forcing reformulation of exfoliating bead systems across European manufacturing. The industrial consequence is a pivot toward cellulose, jojoba ester, and mineral-based physical exfoliants that require new supply chain qualification. Color cosmetic crossover brands with existing mineral sourcing relationships are responding fastest to this compliance-driven specification change.
Repeat purchasers in China and the United States are consolidating buying decisions onto platform-native flagship stores that bundle replenishment with personalized skin diagnostics. Pharmacy and department store counters are losing traffic to algorithmic recommendation engines that reduce consultation friction. This channel rotation is most visible among consumers aged 25-34 seeking non-comedogenic and sensitive-skin positioned products without in-person trial requirements.
Global Facial Cleanser Market Segmentation
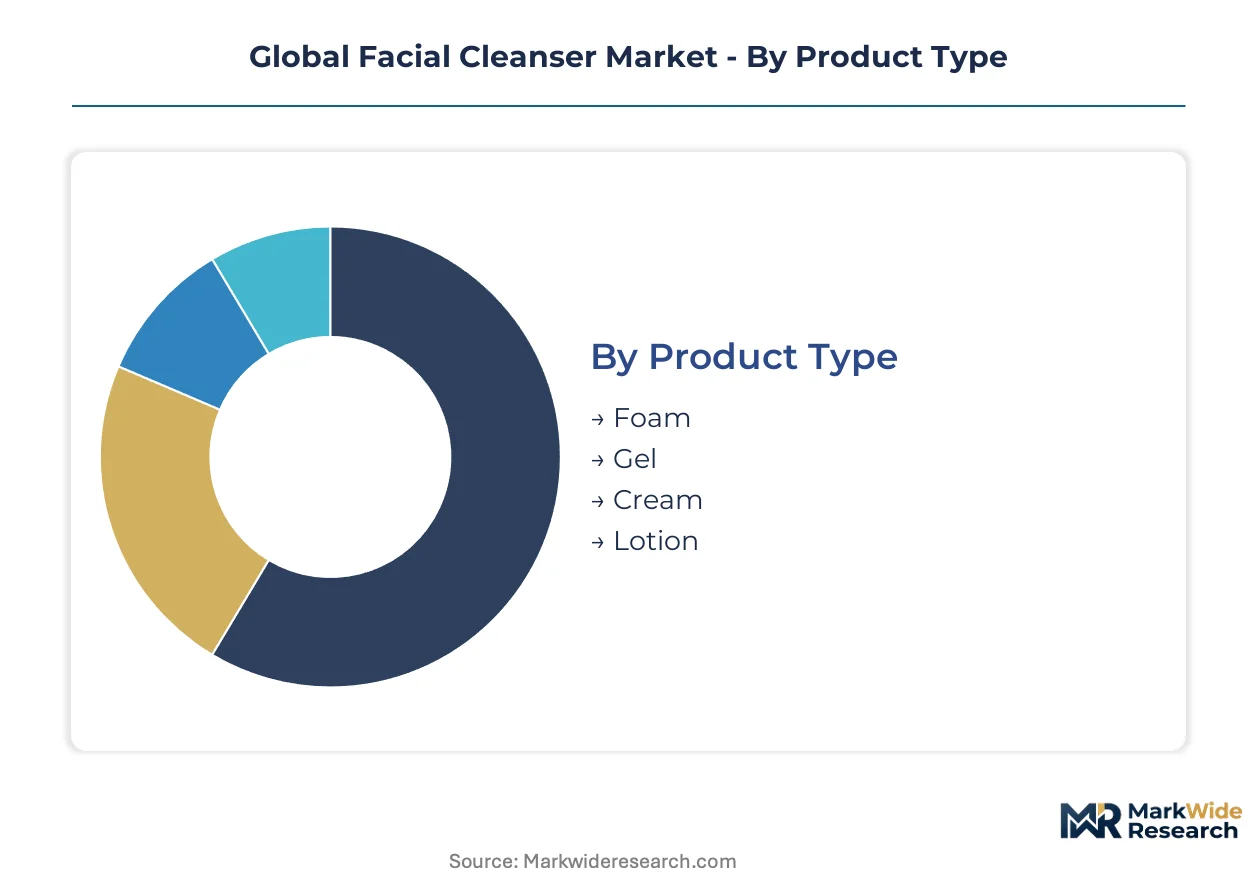
Facial cleanser segmentation reflects divergent consumer priorities across sensory experience, ingredient philosophy, and purchase context. Manufacturers configure product portfolios around these divides to capture repeat purchase loyalty and premium positioning.
Product Type:
Foam formats dominate mass-market volume while gel structures command oily-skin premiums.
- Foam:Surfactant-rich aqueous systems whipped with propellant or pump mechanisms deliver dense lather and rapid rinsing. Demand concentrates in Japan and South Korea, where double-cleansing rituals drive daily consumption frequency.
- Gel:Carbomer-thickened aqueous bases with non-ionic surfactants provide residue-free cleansing for sebum-heavy skin. Urban male consumers in Shanghai and São Paulo are adopting these formats fastest for post-gym and travel use.
- Cream:Emulsion-based cleansers with elevated lipid content preserve barrier function in dry climates. Mature deployment sits with cream formats in European pharmacy channels. Newer deployment is concentrated in gel structures across Asia-Pacific e-commerce.
- Lotion:Fluid milk-texture preparations requiring cotton pad application, prevalent in French dermocosmetic traditions and aging-skin regimens.
Formulation:
Ingredient philosophy splits between certification-driven premiums and safety-claim accessibility.
- Organic:COSMOS or USDA-certified compositions with restricted synthetic inputs and botanical surfactant bases. German and French consumers absorb the highest per-capita volumes, though certification cost inflation compresses mid-tier producer margins.
- Paraben-Free:Phenoxyethanol and sodium benzoate preservation systems replacing traditional esters. This category captures the broadest mass-market penetration as retailers mandate clean-label compliance ahead of regulatory deadlines.
- Exfoliating:Physical or chemical desquamation agents including cellulose beads, jojoba esters, or low-concentration AHAs. REACH Annex XVII microplastic bans are forcing rapid reformulation across European manufacturing.
- Hydrating:Glycerin, hyaluronic acid, and ceramide-fortified bases that deposit rather than strip lipids. Deployment concentrates in North American dermatology clinic channels and Japanese drugstore chains.
Target Audience:
Life-stage segmentation determines texture preference, fragrance tolerance, and clinical positioning intensity.
- Teenagers:Acne-targeted salicylic acid and benzoyl peroxide formulations with oil-control marketing. Demand clusters in US drugstore aisles and Indonesian convenience retail.
- Adults:Anti-aging and pollution-defense claims with antioxidant fortification. This segment captures the steepest expansion trajectory as twenty-five to forty-year-old consumers in China and India expand routine steps beyond basic cleansing.
- Seniors:Barrier-repair focused creams and lotions addressing xerosis and epidermal thinning. Mature deployment sits with senior-targeted SKUs in Japanese and Western European pharmacy networks. Newer deployment is concentrated in adult segments across emerging Asian e-commerce.
- Sensitive Skin:Fragrance-free, minimal-ingredient compositions validated through patch testing. Dermatologist endorsement requirements in Germany and South Korea create channel concentration in professional retail.
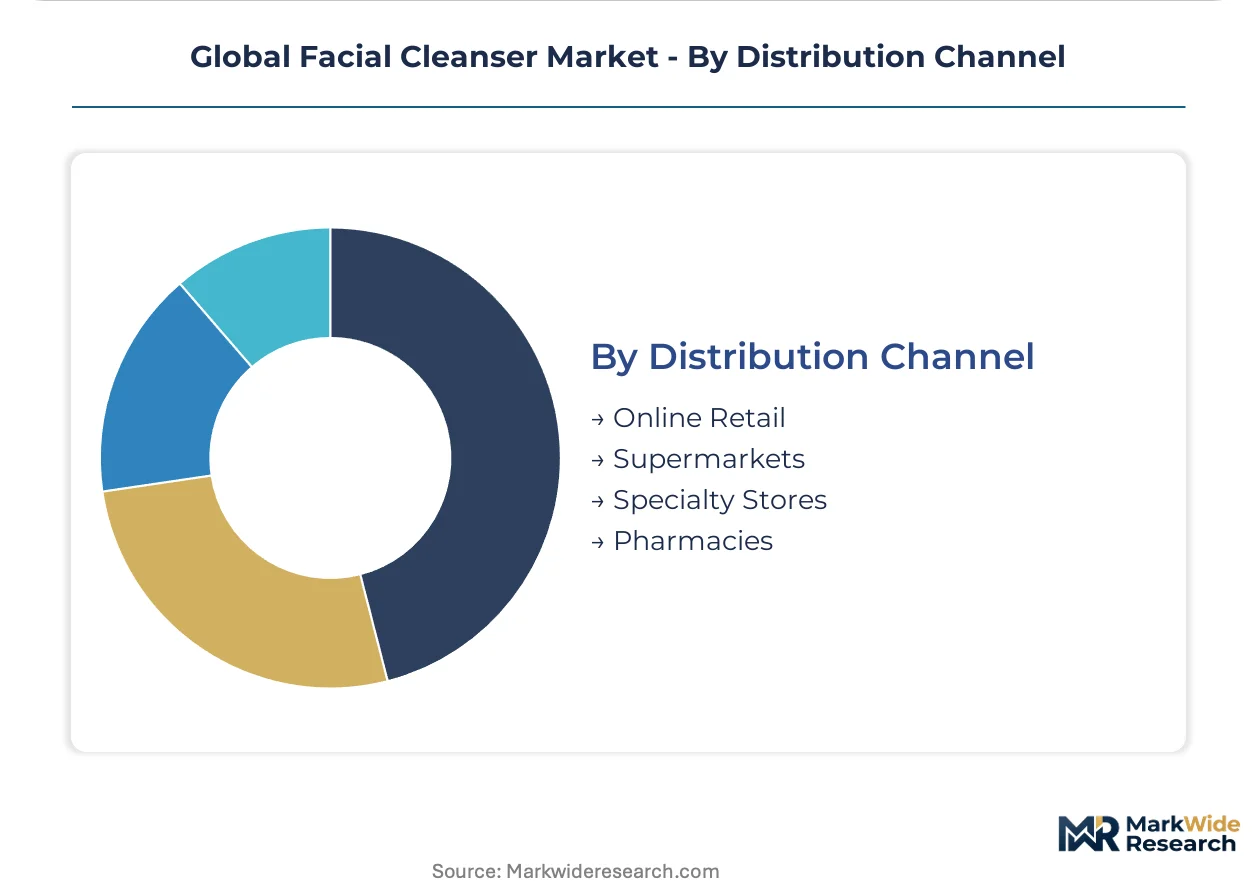
Distribution Channel:
Channel selection reflects consultation need, replenishment urgency, and trial willingness.
- Online Retail:Platform-native flagship stores bundling subscription replenishment with algorithmic skin diagnostics. Tmall and Amazon capture the highest repeat purchase loyalty among consumers aged twenty-five to thirty-four.
- Supermarkets:Mass-market foam and gel formats in high-visibility placements with promotional pricing. Volume concentrates in Brazilian and Mexican urban retail chains.
- Specialty Stores:Sephora and Douglas-type beauty retailers offering texture sampling and staff consultation. Mature deployment sits with specialty retail in Western European capitals. Newer deployment is concentrated in online channels across Chinese tier-two cities.
- Pharmacies:Dermocosmetic and sensitive-skin positioned products with pharmacist endorsement. Regulatory familiarity with national pharmaceutical regulators in Italy and Spain sustains this channel's resilience against e-commerce erosion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hainan Free Trade Port tax incentives are accelerating multinational manufacturing relocation. Domestic brands leverage SAMR registration speed advantages against import timelines. Manufacturing clusters in Shanghai and Guangzhou now serve pan-Asian distribution networks.
United States
FDA cosmetic labeling enforcement is tightening substantiation requirements for acne-control claims. Male grooming adoption in Austin and Miami metro areas is outpacing national averages. California's Proposition 65 disclosure mandates are forcing reformulation of fragrance compounds across West Coast manufacturing.
Germany
ECHA REACH Annex XVII microplastic bans are eliminating polyethylene bead systems from exfoliating cleansers. Dermatology clinic channels in Munich and Hamburg concentrate premium sensitive-skin positioning. Berlin-based contract manufacturers are capturing reformulation demand from French and Dutch brands.
Japan
METI cosmetic quality standards are harmonizing with ASEAN regulatory frameworks to ease export pathways. Double-cleansing ritual frequency in Tokyo and Osaka sustains foam-format volume leadership. Osaka-based surfactant suppliers are verticalizing into finished goods to capture margin.
South Korea
MFDS fast-track approval pathways for functional cosmetics are accelerating microbiome claim products to market. Texture innovation clusters in Seoul's Gangnam district export formulation IP to Chinese and Southeast Asian partners. Busan port logistics support raw material import efficiency for Jeju Island botanical sourcing.
India
BIS cosmetic standards alignment with ASEAN MRA protocols is reducing multi-market certification burden. Tier-two city demand in Pune and Ahmedabad is shifting from soap to gel cleanser formats. Gujarat-based contract manufacturers are scaling paraben-free production for Middle East export.
Global Facial Cleanser Market Vendor Landscape
Top-tier vendors anchor mass-market shelf presence, while mid-tier specialists compete through certification-driven premiums. The competitive set fragments across dermatology-endorsed positioning, sustainability credentialing, and texture innovation vectors. Three archetypes dominate: multinational FMCG conglomerates with men's grooming extensions, regional dermocosmetic specialists with pharmacy channel lock-in, and domestic Chinese brands leveraging platform-native distribution. Capacity expansion and clean-label reformulation represent the dominant competitive moves.
Within the mass-market tier, L'Oréal and Unilever exemplify scale-driven portfolio breadth across foam and gel formats. Beiersdorf AG occupies a position bridging dermatology endorsement with Central European pharmacy channel concentration. Shiseido Company anchors Asia-Pacific texture innovation, particularly in humid-climate formulation adaptation.
| Leading Market Players |
|---|
| L'Oréal |
| Procter & Gamble |
| Unilever |
| Estée Lauder Companies |
| Johnson & Johnson |
| Beiersdorf AG |
| Shiseido Company |
| Kao Corporation |
| Coty Inc. |
| Others |
Supply Flow & Price Mechanics
Specialized formulation chemists concentrated in Germany's Rhine-Ruhr corridor and Japan's Osaka-Kobe manufacturing belt command wage premiums that widen spreads between mass-market foam cleansers and microbiome-positioned premium tiers. Labor-cost differentials between these technical hubs and emerging production zones in Gujarat and Guangzhou enable three-tier pricing architecture that segments buyers by certification tolerance and consultation dependency.
Pricing Analysis
Short lead-time premiums apply to SAMR-fast-tracked microbiome claim products, while spot inventory of conventional surfactant systems trades at discount. The dominant model runs contract-based long-term offtake between platform-native flagship stores and toll manufacturers. Price differentiation hinges on COSMOS certification grade and after-sales bundling with algorithmic skin diagnostics. Cost compression in mid-tier paraben-free segments is intensifying because organic verification fee inflation outpaces formulation cost declines. Mass-market supermarket buyers exhibit highest price sensitivity; dermatology clinic channel purchasers show least.
Supply Chain Analysis
Ocean freight cost volatility between Malaysian palm kernel oil ports and Shanghai formulation hubs is reshaping raw material sourcing calculus. Supply concentrates in China, Germany, and Japan, with surfactant feedstock dependencies on Malaysian palm derivatives, Jeju Island botanical extracts, and petrochemical bases from South Korean crackers. Single-source vulnerability sits with Osaka-based carbomer suppliers serving texture-engineered gel formats. Distribution runs through platform-native flagship stores bundling replenishment with personalized diagnostics, bypassing traditional pharmacy gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU Green Deal disclosure mandates and SAMR registration friction force sub-scale organic certifiers and import-dependent distributors toward exit or acquisition.
For Market Incumbents: Lock in dermatologist endorsement networks in Munich and Seoul before domestic Chinese brands replicate professional channel credibility. Acquire backward integration into Jeju Island botanical sourcing to defend margin position against feedstock volatility. Prioritize COSMOS certification investment as retailer clean-label mandates accelerate.
For New Entrants and Emerging Players: REACH Annex XVII microplastic bans in Europe open a window for cellulose bead exfoliating formats that legacy incumbents must reformulate. Target tier-two Indian cities like Indore and Lucknow where organized retail presence remains underdeveloped. Pursue direct-to-consumer subscription economics that capture repeat purchase loyalty without pharmacy consultation costs.
For Investors and Strategic Acquirers: Re-rating potential sits with Berlin-based contract manufacturers possessing mild surfactant synergy expertise given formulation chemist scarcity concentration. Long-term viability favors specialists with ISO 16128 natural origin certification capabilities across multi-market regulatory convergence. Watch MFDS fast-track approval velocity for microbiome claim products as inflection indicator for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation | EU Green Deal disclosure mandates accelerate COSMOS-certified surfactant system deployment across member states. |
| Microbiome Claim Substantiation | MFDS fast-track pathways in South Korea validate postbiotic lysate positioning for professional channel distribution. |
| Platform-Native Distribution | Tmall and Amazon flagship stores capture repeat purchase loyalty among algorithmic-diagnostic-adopting consumers aged twenty-five to thirty-four. |
| Backward Integration into Botanicals | Jeju Island sourcing control secures margin against Korean and Southeast Asian competitor expansion. |
| Tier-Two Geographic Penetration | Indore and Lucknow mass-market gel deployment captures first-mover positioning before organized retail consolidation. |
Methodological Framework
Independent corroboration across brand managers at L'Oréal and Unilever, category buyers at Sephora and Douglas, and supply planners at Shanghai-based toll manufacturers underwrites the qualitative findings. Secondary validation draws from SAMR cosmetic registration databases, REACH Annex XVII compliance filings, Nielsen retail audit data, and customs records of surfactant feedstock imports. Bottom-up segmentation modeling triangulates against top-down macroeconomic anchors across the analysis window.
Comparable-period anchoring to historical foam-format volume leadership in Japan and gel-format adoption trajectories in Brazil establishes baseline growth coefficients. The analytical framework segments by product type, formulation philosophy, target life-stage, and distribution channel across the projection horizon. CAGRs derive from surfactant input cost indices, platform-native channel penetration curves, and dermatology clinic channel expansion rates.
The model assumes a particular technology adoption path; alternative pathways for postbiotic lysate stability would alter the outlook. Forecasts reflect assumptions about regulatory harmonization velocity and microbiome claim substantiation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Moisturizing Spray Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Herbal Soap Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Japan Organic Cosmetics Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Tinted Cosmetics Market