
 Organic Color Cosmetics Products Market | 2026-2036
Organic Color Cosmetics Products Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Color Cosmetics Products Market Analytics
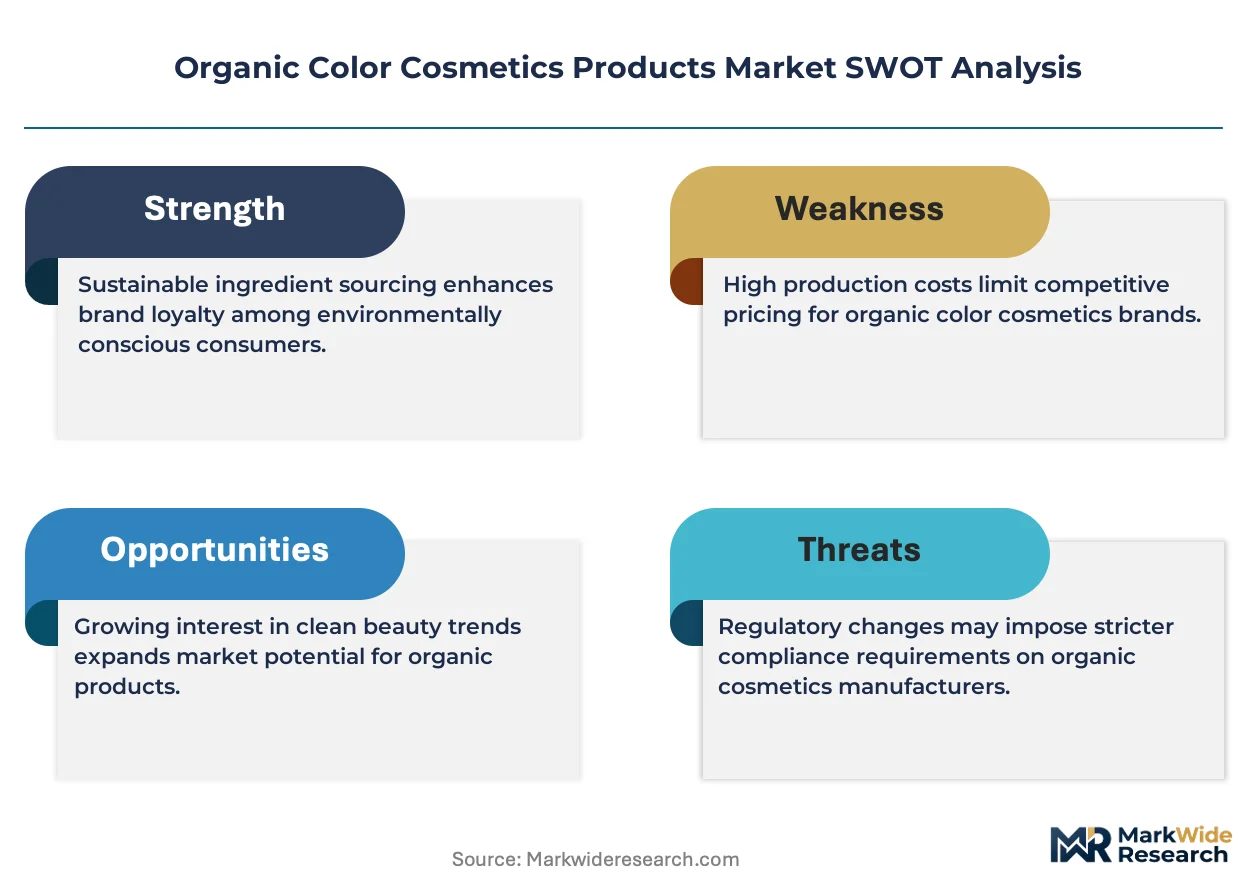
The EU Green Deal's chemical substitution targets is shifting procurement priorities across European beauty supply chains. L'Oréal S.A. leverages its integrated R&D campus in France to sustain leadership in plant-derived pigment stabilization. Estée Lauder Companies Inc. anchors its premium positioning through controlled distribution in department store and travel retail channels. Weleda AG differentiates via biodynamic cultivation standards that exceed conventional organic certification requirements.
Organic color cosmetics products are formulated formulations containing certified organic ingredients, typically comprising minimum organic content thresholds with restricted synthetic preservatives, and rely on mineral pigments, plant-derived oils, and natural waxes as functional bases for color payoff and skin adhesion. Foundation and lipstick categories dominate current revenue pools due to higher purchase frequency and premium pricing tolerance among professional makeup artists. Liquid formulations lead volume production while powder segments compete on shelf stability and transport efficiency across diverse climate conditions.
REACH in Europe, FDA cosmetic labeling requirements in the United States, and ECHA substance restriction protocols collectively define permissible ingredient thresholds and disclosure obligations that manufacturers must navigate for market access. These frameworks shape reformulation timelines, testing expenditures, and cross-border shipment documentation burdens. Stakeholders must monitor evolving state-level cosmetic safety legislation in the United States and pending EU microplastic restrictions that could affect glitter and long-wear polymer systems.
Market Dynamics
Clean beauty mandates from film and television production studios are restructuring procurement standards across professional makeup supply chains, forcing reformulation investments and certification upgrades throughout the value chain.
Growth Catalysts
- EU Green Deal chemical substitution targets:Manufacturers accelerate plant-derived pigment R&D to meet binding reduction schedules for synthetic colorants.
- Professional makeup artist procurement standards:Studio sustainability departments now require organic certification for on-set cosmetics, expanding addressable demand.
- Biodynamic cultivation protocols:Raw material suppliers adopt stricter agricultural standards that command premium positioning in luxury channels.
Market Restraints
- Mineral pigment supply concentration:Mica processing clusters in India and Madagascar create geopolitical exposure and ethical sourcing verification burdens.
- Plant oil price volatility:Weather-dependent yields for jojoba, argan, and castor oils compress margin predictability for formulators.
- Preservative efficacy limitations:Restricted synthetic preservative lists under REACH reduce shelf stability versus conventional alternatives.
Strategic Opportunities
- Travel retail channel expansion:Duty-free operators seek certified organic assortments to differentiate premium beauty zones in Dubai, Singapore, and Paris airports.
- Men's grooming color cosmetics:Underserved male demographic shows rising acceptance of concealers and brow products with clean ingredient positioning.
- Refillable packaging mandates:France's anti-waste law creates first-mover advantage for brands with modular, returnable component systems.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging natural ingredient behavior with performance benchmarks remains concentrated among senior practitioners.
- Multi-certification coordination:Simultaneous pursuit of COSMOS, USDA Organic, and Natrue labels strains documentation and audit resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Color Cosmetics Products Market |
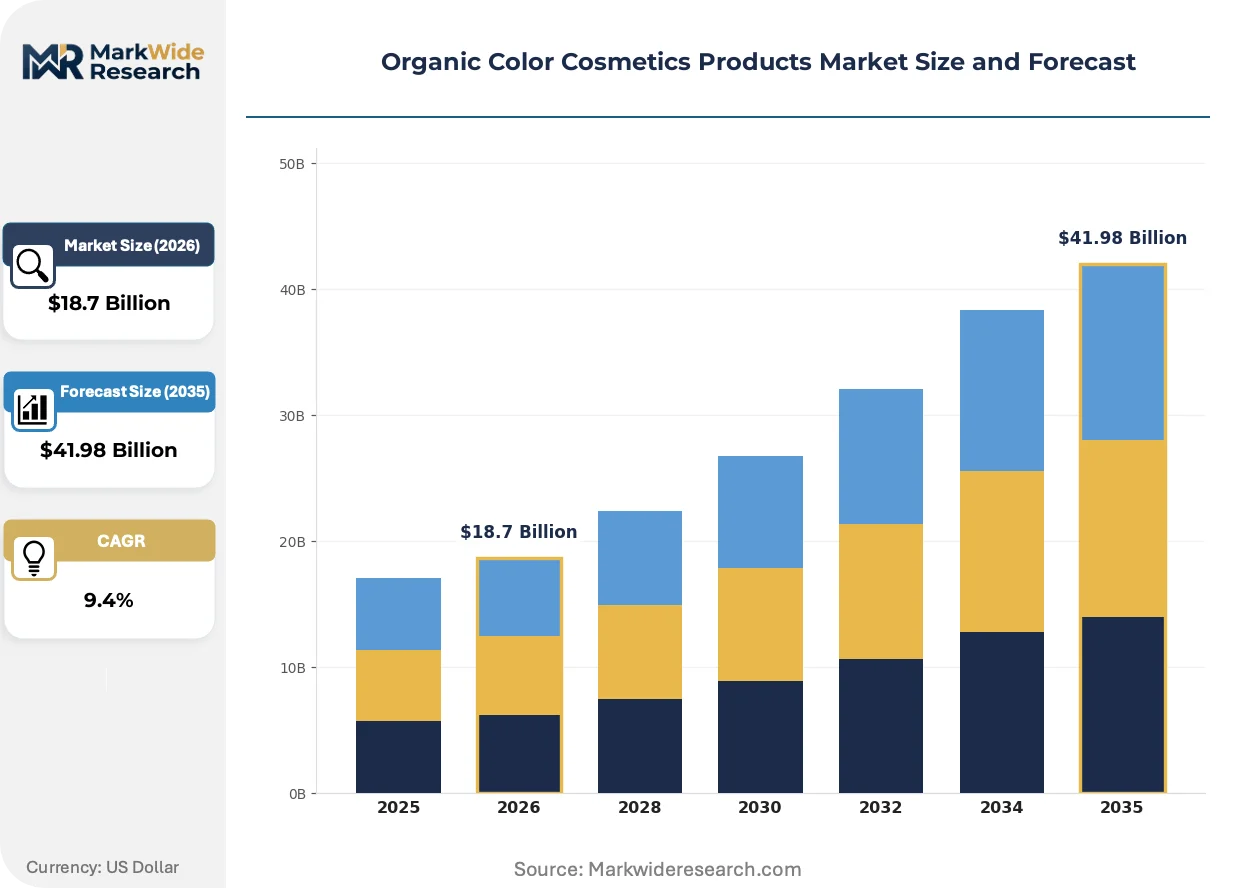
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation, Lipstick, Eyeshadow, Blush Ingredient: Natural Oils, Mineral Pigments, Plant Extracts, Waxes Formulation: Liquid, Powder, Cream, Stick End User: Professional Makeup Artists, Consumers, Retail Chains, Salons |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Burt’s Bees, Weleda AG, Unilever PLC, 100% PURE, KORRES S.A., Dr. Hauschka, Aveda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Color Cosmetics Products Market Evolving Landscape
Formulation science is advancing beyond simple ingredient substitution toward engineered natural systems that replicate synthetic performance. Biotechnology-derived colorants and fermentation-based emollients are entering commercial scale.
Fermentation-derived squalane and hemisqualane are overtaking plant-extracted alternatives in mid-tier formulations. Professional makeup artists in Los Angeles and London studios specify these ingredients for consistent texture across climate conditions. The technology is compressing reliance on olive and sugarcane feedstocks that face agricultural constraints.
REACH Annex XVII substance restrictions are tightening thresholds for residual heavy metals in mineral pigments. German and French testing laboratories report extended validation timelines as manufacturers adapt analytical methods. Lipstick and eye shadow categories bear the heaviest compliance burden due to color intensity requirements.
Ingredient transparency apps are reshaping pre-purchase verification habits among professional buyers. Makeup artists scan QR codes on set to access batch-level certification data, bypassing traditional distributor claims. This behavior concentrates most visibly in Nordic markets where digital literacy intersects with stringent clean beauty expectations.
Organic Color Cosmetics Products Market Segmentation
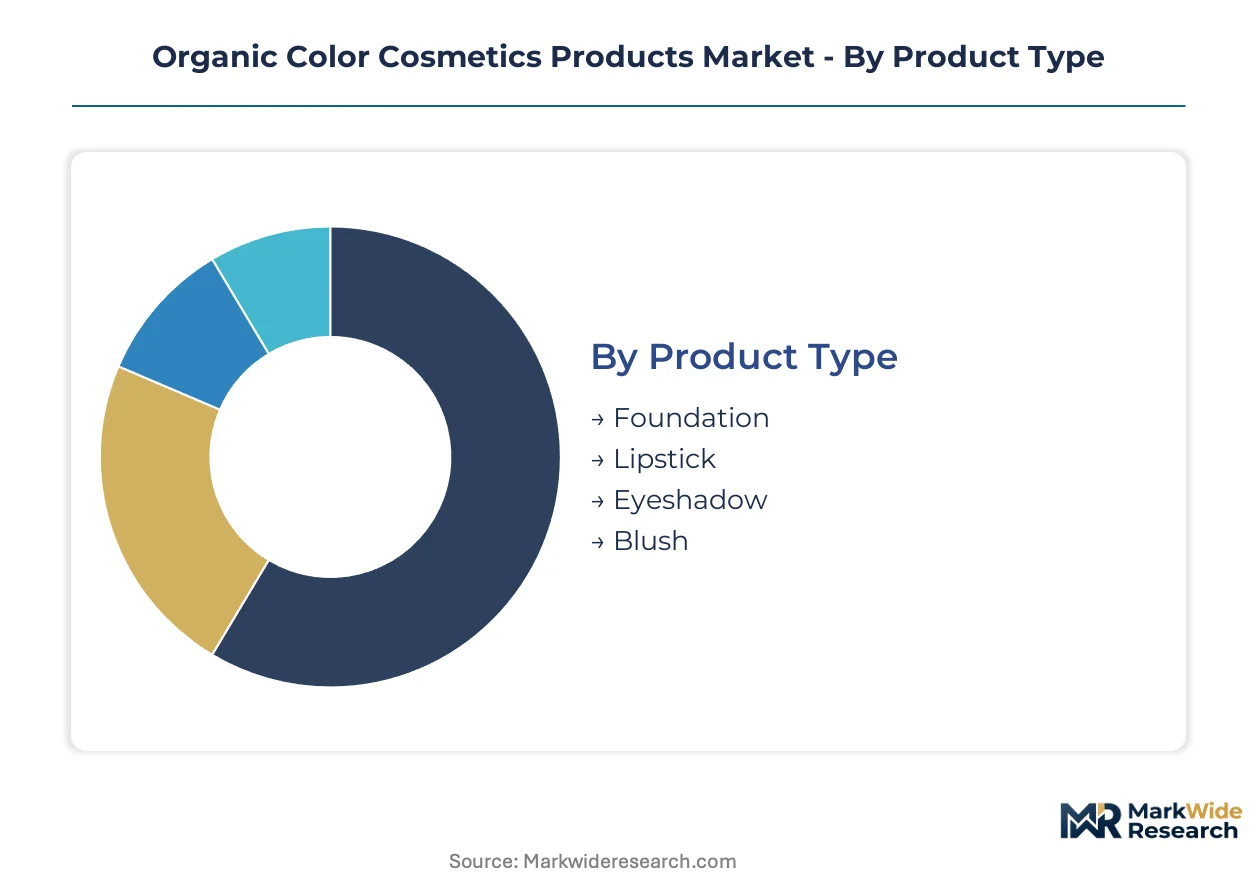
Segmentation in organic color cosmetics reveals distinct capital requirements across product categories, with formulation complexity and certification burden varying sharply by segment. Professional procurement standards and regulatory thresholds reshape profitability profiles within each slice.
Product Type:
Foundation and lipstick command the heaviest upfront investment due to extended stability testing and pigment dispersion R&D requirements.
- Foundation:Complex emulsion systems combining mineral pigments with plant-derived oils require sophisticated stabilization chemistry. Professional makeup artists in Los Angeles and London studios drive specification intensity for climate-consistent performance. REACH Annex XVII heavy metal thresholds impose extended validation timelines for color intensity compliance.
- Lipstick:Wax-oil-pigment matrices demand precise melting point engineering and long-wear polymer alternatives. Paris-based luxury houses anchor premium positioning through biodynamic oil sourcing and modular refillable formats. France's anti-waste law accelerates packaging innovation investment.
- Eyeshadow:Pressed powder and cream variants compete on pigment load and blendability.
- Blush:Powder dominance persists in professional kits; liquid formats gain share in direct-to-consumer channels.
Foundation absorbs the bulk of installed capacity; lipstick is expanding most quickly.
Ingredient:
Raw material sourcing strategy divides segments by agricultural exposure and geopolitical risk concentration.
- Natural Oils:Jojoba, argan, and castor oil supply chains face weather-dependent yield volatility. Biodynamic cultivation protocols in Germany and France command premium positioning through stricter agricultural standards than conventional organic certification.
- Mineral Pigments:Mica processing clusters in India and Madagascar create ethical sourcing verification burdens and geopolitical exposure. ECHA substance restrictions tighten residual heavy metal thresholds, extending analytical validation timelines at German and French testing laboratories.
- Plant Extracts:Fermentation-derived alternatives compress reliance on agricultural feedstocks.
- Waxes:Carnauba and candelilla supply concentrates in specific climatic zones.
Mineral pigments dominate input volumes; fermentation-derived substitutes are gaining share fastest.
Formulation:
Manufacturing equipment and shelf stability requirements create divergent margin structures across physical states.
- Liquid:Emulsion processing lines and preservative efficacy challenges elevate technical barriers. Biotechnology-derived emollients and fermentation-based squalane enter commercial scale, overtaking plant-extracted alternatives in mid-tier production.
- Powder:Pressed compact manufacturing offers transport efficiency and climate resilience. Nordic professional buyers leverage ingredient transparency apps for batch-level certification verification, reshaping distributor claims validation.
- Cream:Hybrid positioning between liquid payoff and powder stability.
- Stick:Solid format reduces packaging complexity and travel retail leakage.
Liquid formulations anchor volume production; powder segments lead shelf stability metrics.
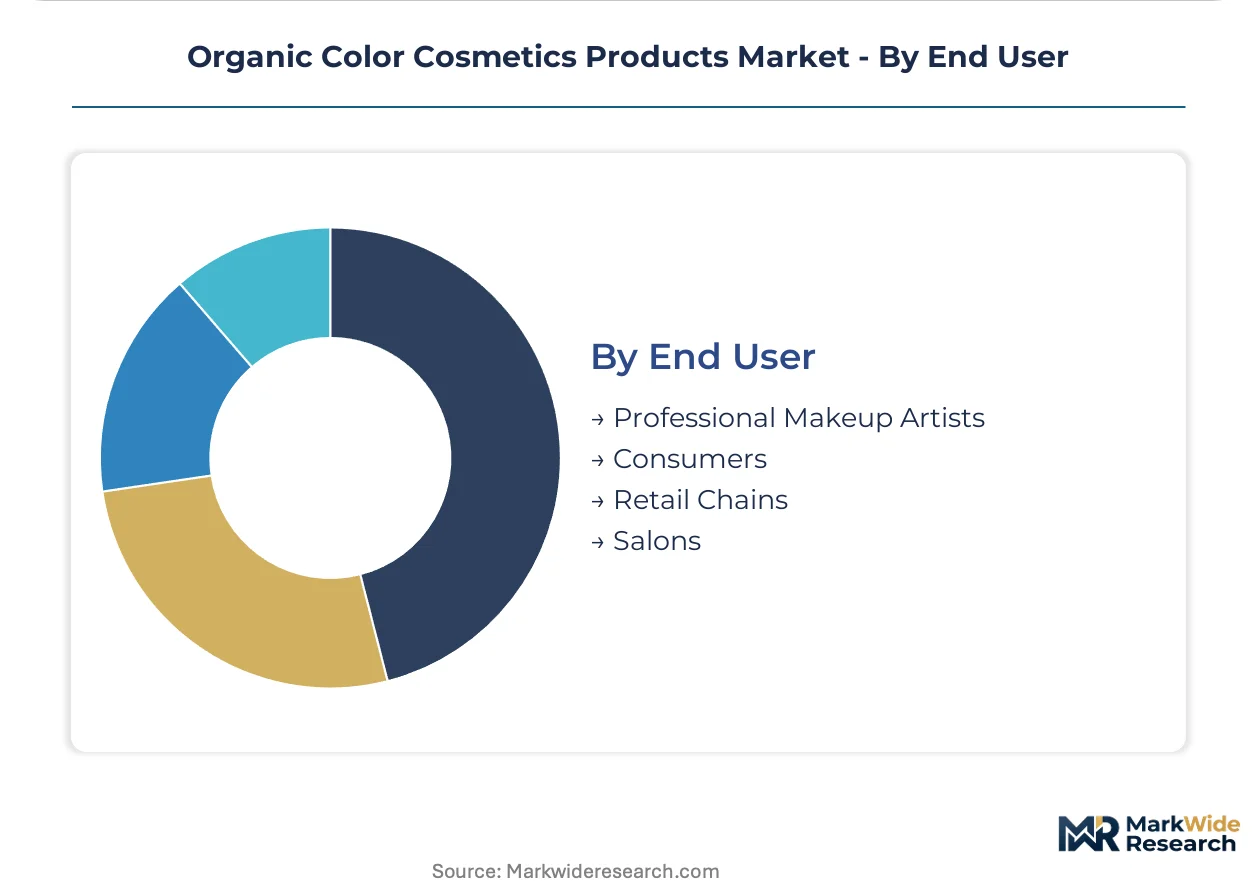
End User:
Procurement authority and certification requirements stratify customer economics sharply.
- Professional Makeup Artists:Studio sustainability departments now mandate organic certification for on-set cosmetics, expanding addressable demand. Clean beauty mandates from film and television production studios in Los Angeles and London restructure supply chain qualification.
- Consumers:Direct-to-consumer channels leverage digital verification tools for pre-purchase ingredient scrutiny. QR code scanning for batch-level certification data concentrates in Nordic markets with intersecting digital literacy and clean beauty expectations.
- Retail Chains:Department store and travel retail operators seek certified organic assortments for premium beauty zone differentiation.
- Salons:Service-based consumption models with lower purchase frequency than professional kit replenishment.
Professional makeup artists concentrate the highest per-capita spending; consumer direct channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paris anchors premium organic color cosmetic development through luxury house concentration and biodynamic sourcing protocols that command formulation premiums across European supply chains.
France
Paris-based luxury houses drive premium organic color cosmetic R&D through integrated campuses and controlled distribution networks. The country's anti-waste law mandates refillable packaging systems, accelerating modular component innovation. Île-de-France concentrates biodynamic cultivation certification that exceeds conventional organic thresholds for raw material suppliers.
Germany
German testing laboratories validate REACH Annex XVII compliance for residual heavy metals in mineral pigments, extending analytical timelines for lipstick and eye shadow categories. ECHA substance restrictions tighten permissible thresholds, forcing reformulation investments. Baden-Württemberg hosts specialized cosmetic chemistry talent clusters addressing natural preservative efficacy limitations.
United States
Los Angeles studio sustainability departments mandate organic certification for on-set cosmetics, expanding professional makeup artist procurement standards. FDA cosmetic labeling requirements shape disclosure obligations and cross-border documentation burdens. California's clean beauty legislation accelerates state-level regulatory fragmentation beyond federal baselines.
United Kingdom
London professional makeup artists specify fermentation-derived emollients for climate-consistent performance across film and television production. The UK's post-EU regulatory divergence creates parallel compliance pathways for ingredient disclosure. British retailers leverage ingredient transparency apps for batch-level verification among Nordic-influenced consumer segments.
India
Mica processing clusters in Jharkhand and Bihar create ethical sourcing verification burdens and geopolitical exposure for mineral pigment supply chains. Indian manufacturers face compressed margin predictability from weather-dependent jojoba and castor oil yield volatility. Mumbai-based formulators navigate multi-certification coordination across COSMOS, USDA Organic, and Natrue label requirements.
Organic Color Cosmetics Products Market Competitive Landscape
The competitive structure tilts toward diversified beauty conglomerates with captive R&D infrastructure and controlled distribution networks. French and American multinational groups anchor premium positioning through integrated formulation campuses and department store channel dominance. Three archetypes populate the field: luxury heritage houses with biodynamic sourcing protocols, mid-tier natural specialists with direct-to-consumer scale, and mass-market players retrofitting conventional portfolios with organic SKUs. Capacity expansion in fermentation-derived ingredients and strategic partnerships for mica supply chain verification represent dominant competitive moves.
Among diversified beauty conglomerates, L'Oréal S.A. and Estée Lauder Companies Inc. occupy positions exemplifying integrated R&D and controlled distribution archetypes, while Weleda AG represents the biodynamic cultivation specialist tier with standards exceeding conventional organic certification requirements.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Burt's Bees |
| Weleda AG |
| Unilever PLC |
| 100% PURE |
| KORRES S.A. |
| Dr. Hauschka |
| Aveda |
| Others |
Value Network & Pricing Analysis
Studio sustainability departments mandating organic certification for on-set cosmetics are compressing procurement flexibility and forcing supply chains toward verified biodynamic sourcing that commands premium positioning across European and North American markets.
Pricing Analysis
Value-based pricing anchored to certification grade and performance consistency under professional use conditions dominates transaction structures. Three-tier pricing structure across premium, standard, and economy levels separates biodynamic-certified formulations from conventional organic and mass-market natural alternatives. Cost compression in mid-tier segments is intensifying because fermentation-derived ingredient substitutes are overtaking plant-extracted alternatives at scale. Professional makeup artists demonstrate the lowest price sensitivity due to client-billable cost recovery, while direct-to-consumer channels show highest elasticity to promotional positioning.
Supply Chain Analysis
Freight cost volatility from climate-dependent agricultural zones in Morocco, India, and Madagascar is elevating landed cost unpredictability for critical inputs. Mica processing clusters in Jharkhand and Bihar, jojoba cultivation in Arizona and Argentina, and argan cooperatives in southwestern Morocco anchor upstream concentration. Single-source vulnerability in Indian mica supply creates ethical sourcing verification burdens that extend lead times. Distribution runs through department store beauty halls, professional supply houses in Los Angeles and London, and duty-free operators in Dubai and Singapore airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH Annex XVII substance restrictions and EU Green Deal chemical substitution targets erect barrier-to-entry moats favoring incumbent players with captive testing infrastructure and established ECHA relationships.
For Market Incumbents: Lock in supply security through backward integration into biodynamic cultivation networks in France and Germany, securing feedstock priority as weather volatility intensifies. Deepen analytical capabilities at German and French testing laboratories to compress REACH validation timelines and defend margin position against mid-tier competitors facing extended compliance cycles.
For New Entrants and Emerging Players: Direct-to-consumer subscription models targeting Nordic professional makeup artists offer the most penetrable entry vector, leveraging ingredient transparency apps for batch-level verification that bypasses traditional distributor gatekeepers. Men's grooming color cosmetics represent adjacent white space with minimal incumbent positioning and rising clean ingredient acceptance.
For Investors and Strategic Acquirers: The window for entry favors fermentation-technology specialists with scalable squalane and hemisqualane production platforms. Long-term viability hinges on substituting agricultural feedstock exposure with biotechnology-derived alternatives. Watch ECHA microplastic restriction timelines as the inflection signal for polymer-dependent long-wear formulation valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodynamic Sourcing | Secures supply priority from Île-de-France cultivation clusters exceeding conventional organic thresholds. |
| Fermentation-Derived Ingredient Scale-Up | Compresses reliance on weather-exposed jojoba and argan agricultural yields across North African supply zones. |
| Refillable Packaging System Launch | Aligns modular component design with France's anti-waste law mandates for returnable cosmetic formats. |
| Professional Channel Certification Partnership | Locks studio procurement standards through Los Angeles and London production sustainability departments. |
| Multi-Label Certification Coordination | Simultaneous COSMOS, USDA Organic, and Natrue pursuit opens access to fragmented European premium retail. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with cosmetic chemists, professional makeup artists, biodynamic cultivation coordinators, department store beauty buyers, and ECHA compliance consultants. FDA cosmetic labeling submissions, REACH registration dossiers, COSMOS and Natrue certification databases, and French anti-waste law implementation reports supplied validation layers. Bottom-up production capacity estimates triangulated against top-down consumption modeling across professional kit replenishment and direct-to-consumer channels.
Segment-level granularity modeled product type, ingredient sourcing strategy, formulation physical state, and end-user procurement authority across the analysis window. CAGRs derived from slope-consistency checks against historical certification adoption curves and professional channel penetration rates. Input assumptions incorporated REACH Annex XVII heavy metal threshold evolution, fermentation technology cost curves, and studio sustainability mandate diffusion patterns.
The model holds under stable regulatory enforcement timelines; deviation in ECHA microplastic restriction implementation or sudden mica supply disruption would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context and regional compliance exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
China Cosmetic Products Market
Cosmetics & Skincare
Global Cosmetic Shea Butter Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Liquid Lipstick Market
Cosmetics & Skincare
Essential Oil Soap Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Herbal Soap Market