
 Red Yeast Rice Market | 2026-2036
Red Yeast Rice Market Size, Share, and Industry Trends Forecast 2026-2036
Red Yeast Rice Market Analytics
Buyer concentration among healthcare providers and fitness centers is hardening as institutional purchasers consolidate supplement sourcing contracts. SunWay Biotech Co., Ltd. anchors its position through captive fermentation capabilities in Taiwan. NOW Health Group, Inc. differentiates via rigorous third-party testing protocols that satisfy pharmacy channel requirements. Nature's Bounty leverages retail scale to control shelf placement across North American supermarket chains.
Red yeast rice consists of fermented rice inoculated with Monascus purpureus, yielding bioactive monacolins including monacolin K, which shares structural homology with lovastatin and functions as an HMG-CoA reductase inhibitor for cholesterol modulation. Capsules dominate volume due to dosing precision and consumer familiarity, while extracts command premium positioning in functional food formulations targeting cholesterol management. The dietary supplements application sustains the broadest revenue base, though nutraceuticals directed at health enthusiasts represent the fastest-expanding margin pool.
FDA oversight of monacolin K levels classifies certain red yeast rice products as unapproved drugs, constraining label claims and channel access in the United States. EFSA evaluations under EU novel food frameworks shape import acceptance for Asian-manufactured powders and extracts. China's NMPA and SAMR enforce GB standards on fermentation purity and aflatoxin limits that determine export eligibility. Stakeholders must monitor evolving pharmacological reclassification risks that could redraw competitive boundaries between supplement and pharmaceutical positioning.
Market Dynamics
Regulatory bifurcation between supplement and pharmaceutical classification is forcing manufacturers to reconfigure fermentation protocols and label claims across every major jurisdiction.
Growth Catalysts
- EFSA Novel Food Framework:Streamlined safety assessments for Asian-manufactured extracts are accelerating EU market entry for compliant suppliers.
- Cardiovascular Health Protocols:Hospital wellness programs in Germany and France are integrating red yeast rice into preventive care pathways for statin-intolerant patients.
- Precision Fermentation:Controlled bioreactor systems are stabilizing monacolin K yields, reducing batch-to-batch variation that previously triggered regulatory rejection.
Market Restraints
- FDA Unapproved Drug Designation:Products exceeding trace monacolin K thresholds face seizure and import detention, constraining US channel access.
- Input Concentration Risk:Premium indica rice supply for fermentation concentrates in Hubei and Hunan provinces, exposing processors to climate-driven harvest volatility.
- Statin Substitution Threat:Generic atorvastatin price compression in Medicare Part D plans is narrowing the cost gap with premium supplement positioning.
Strategic Opportunities
- India Preventive Cardiology:Underpenetrated urban markets present whitespace for pharmacy-distributed formulations targeting rising LDL management demand.
- Functional Food Integration:Beverage and fortified dairy applications in Japan are opening new consumption occasions beyond capsule formats.
- CSRD Supply Chain Disclosure:EU sustainability reporting mandates favor fermentation facilities with verified carbon accounting, rewarding early compliance investments.
Industry Challenges
- Analytical Chemist Scarcity:Specialized HPLC-MS technicians capable of monacolin K quantification at ppb levels command premium compensation, constraining QA throughput.
- Dual-Use Facility Certification:CGMP compliance for pharmaceutical-grade production requires 18-24 month validation timelines that delay revenue conversion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Red Yeast Rice Market |
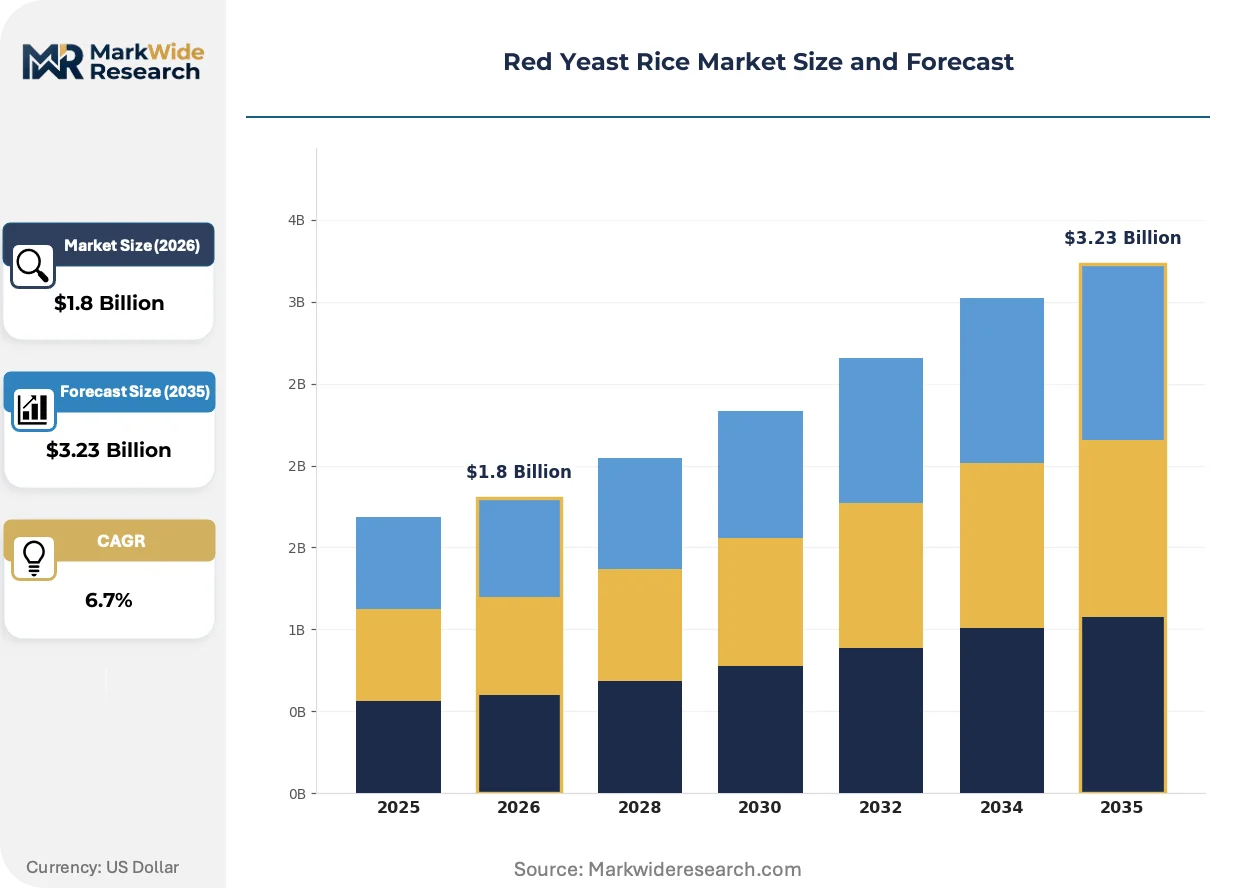
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Extracts, Tablets Application: Cholesterol Management, Dietary Supplements, Nutraceuticals, Functional Foods End User: Individuals, Health Enthusiasts, Fitness Centers, Healthcare Providers Distribution Channel: Online Retailers, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Nature's Bounty, NOW Health Group, Inc., SunWay Biotech Co., Ltd., Jarrow Formulas, Inc., The Bountiful Company, Alesco S.r.l., Natures Plus, Amazing Nutrition, Xi'an Sost Biotech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Red Yeast Rice Market Evolving Landscape
Bioprocess engineering advances are decoupling monacolin K production from traditional solid-state fermentation, enabling scale and standardization previously unattainable in natural product manufacturing.
Strain engineering of Monascus purpureus through CRISPR-guided metabolic pathway optimization is rewriting yield economics for commercial fermentation. Contract manufacturers in Taiwan and South Korea are adopting these platforms to secure pharmacy-grade supply contracts. The technology is compressing the cost structure gap between natural extract and semi-synthetic lovastatin, forcing positioning decisions across the value chain.
China's SAMR enforcement of GB 1886.19-2015 purity standards is tightening aflatoxin and citrinin limits for export-bound powders. Domestic facilities are retrofitting chromatographic purification trains to maintain EU and US market access. Small-batch artisan producers without capital reserves are exiting export channels, consolidating supply among industrial-scale operators.
Direct-to-clinic subscription models are displacing retail shelf reliance for cholesterol management protocols. Functional medicine practitioners in California and Texas are sourcing tested extracts through verified supplier portals, bypassing traditional supplement distribution. This channel shift is most visible in concierge cardiology practices where patient compliance monitoring justifies premium pricing over mass-market alternatives.
Red Yeast Rice Market Segmentation
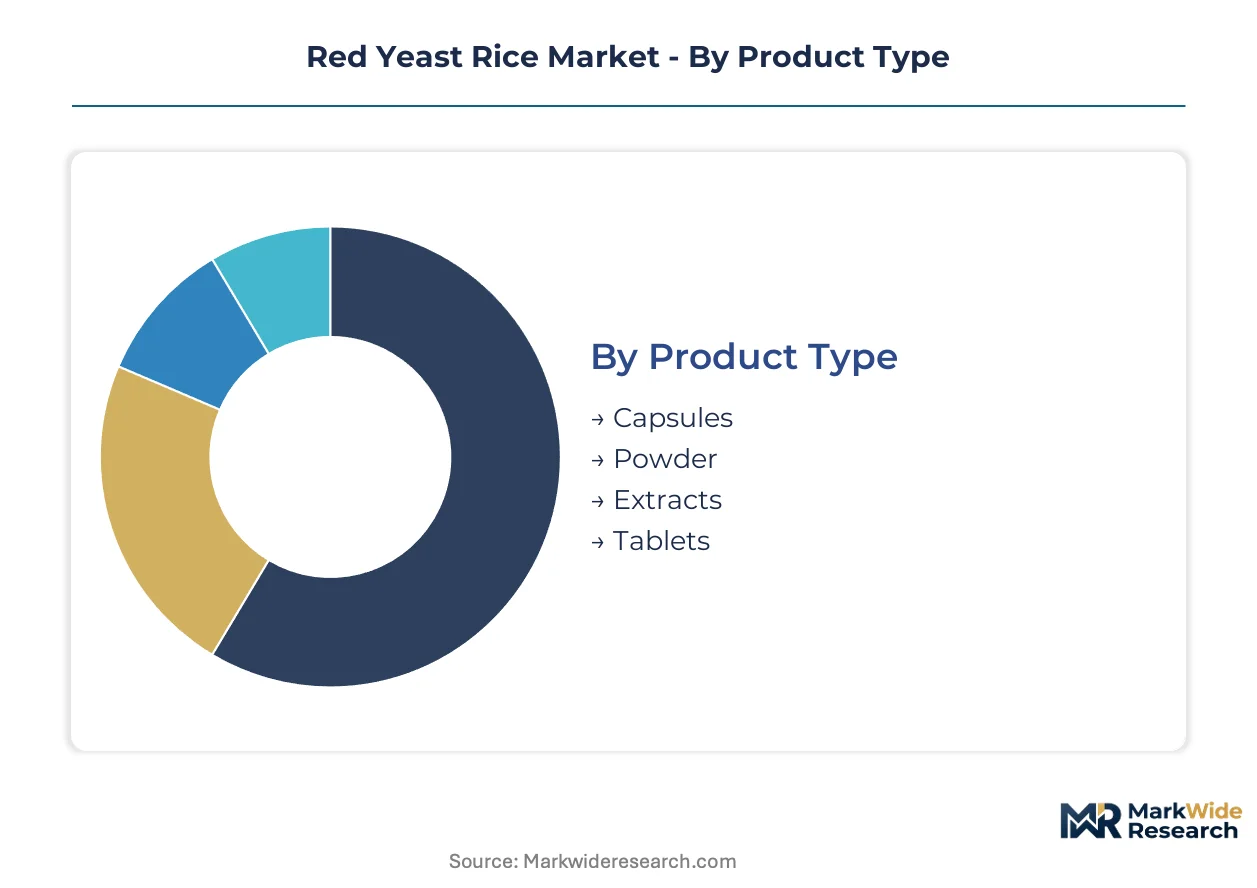
Red yeast rice procurement decisions split across formulation requirements, regulatory compliance tiers, and channel access constraints. Manufacturers must align product architecture with end-user risk profiles and testing standards that vary by jurisdiction.
Product Type:
Buyers prioritize dosing precision and stability characteristics when selecting formulation formats.
- Capsules:Gelatin or vegetable-based shells deliver standardized monacolin K doses with shelf stability exceeding 24 months. Hospital wellness programs in Germany and France specify capsule formats for statin-intolerant patient protocols due to measurable active content.
- Extracts:Concentrated monacolin K fractions undergo chromatographic purification to meet EFSA novel food thresholds. Functional food manufacturers in Japan pay premium multiples for extract grades that integrate into beverage matrices without precipitation.
- Powder:Bulk fermentation output serves contract manufacturers blending into composite supplement formulations.
- Tablets:Compressed formulations compete on cost but face slower dissolution scrutiny from pharmacy buyers.
Volume sits with capsules; growth tilts toward extracts.
Application:
Margin structure diverges sharply between clinical positioning and mass-market wellness positioning.
- Dietary Supplements:The broadest revenue base spans direct-to-consumer capsules and tablets with cholesterol management claims. NOW Health Group and Nature's Bounty dominate shelf placement across North American retail channels.
- Nutraceuticals:Health enthusiast segments command premium positioning through verified third-party testing and subscription direct-to-clinic models. California functional medicine practices source tested extracts through verified supplier portals.
- Cholesterol Management:Clinical protocols in German hospital systems require batch-specific monacolin K certificates.
- Functional Foods:Fortified dairy and beverage applications in Japan create new consumption occasions beyond traditional supplement formats.
Revenue concentrates in dietary supplements; nutraceuticals climb the fastest.
End User:
Procurement authority is consolidating among institutional purchasers with compliance verification capabilities.
- Healthcare Providers:Hospital systems and concierge cardiology practices in Texas and California mandate COA documentation for every lot. These buyers displace retail reliance through direct supplier relationships.
- Individuals:Mass-market consumers select based on price-per-capsule and brand recognition at supermarket shelves.
- Health Enthusiasts:Biohacker communities drive demand for fermented transparency and strain-specific sourcing.
- Fitness Centers:Corporate wellness contracts consolidate supplement sourcing for member benefit programs.
Transaction volume favors individuals; contract value expands most quickly with healthcare providers.
Distribution Channel:
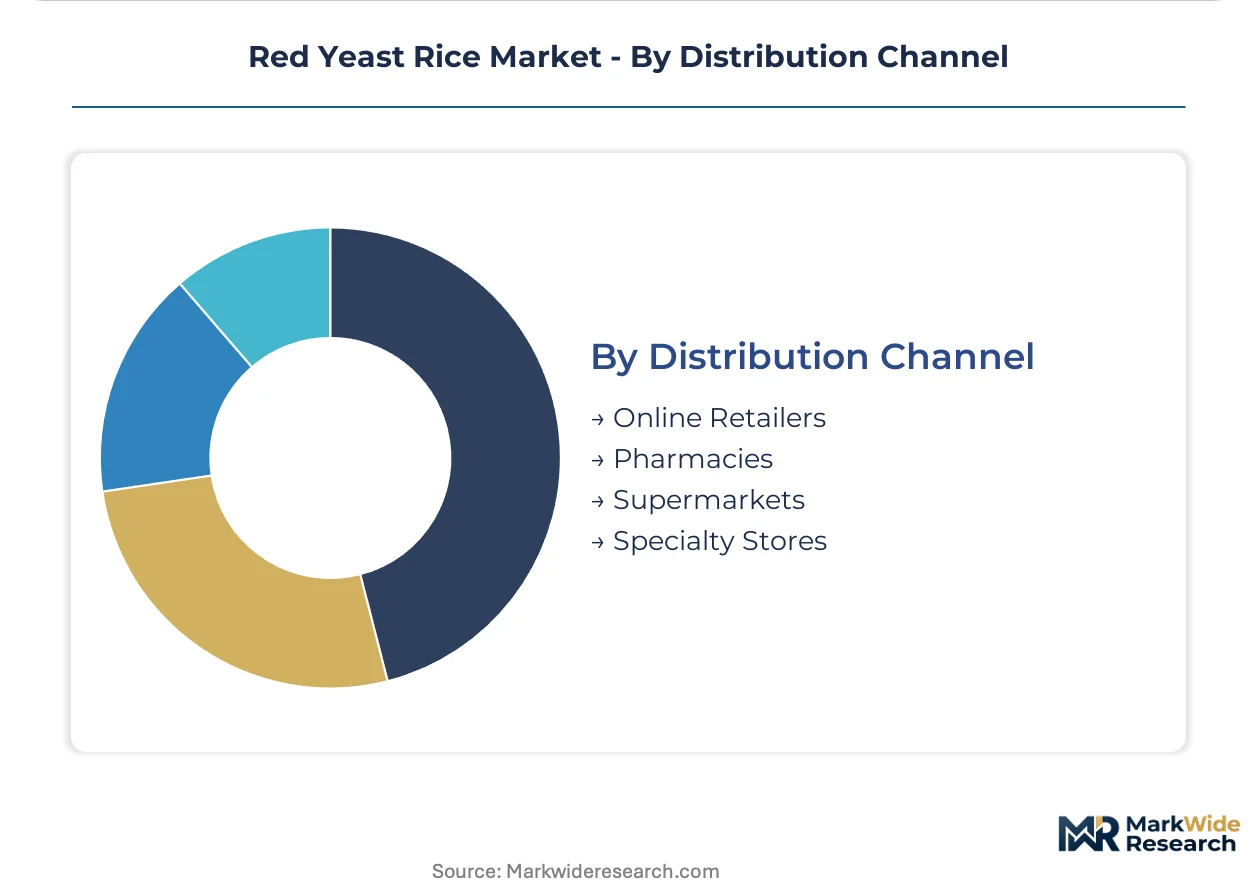
Channel selection determines regulatory exposure and margin capture simultaneously.
- Pharmacies:German and French pharmacy chains require EFSA-compliant documentation and HPLC-MS verification. SunWay Biotech anchors supply through Taiwan-based fermentation with EU import clearance.
- Online Retailers:Direct-to-consumer platforms bypass shelf slotting fees but face FDA scrutiny on monacolin K claims.
- Supermarkets:North American chains control placement through annual vendor negotiations favoring retail-scale suppliers.
- Specialty Stores:Natural product retailers emphasize artisan fermentation stories and small-batch provenance.
Supermarkets move the most units; pharmacies deliver the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the bulk of fermentation capacity and traditional medicine demand, while Germany and the United States anchor clinical adoption through hospital wellness protocols. Regulatory divergence between FDA drug classification and EFSA novel food frameworks is fragmenting market access patterns across jurisdictions.
China
Domestic consumption of red yeast rice as both food coloring and traditional cholesterol remedy sustains massive fermentation throughput in Hubei and Hunan provinces. SAMR enforces GB 1886.19-2015 purity standards that determine export eligibility for aflatoxin and citrinin limits. Wuhan-based industrial clusters are retrofitting chromatographic purification trains to maintain EU and US market access as small-batch artisan producers exit export channels.
Germany
Hospital wellness programs in Bavaria and North Rhine-Westphalia integrate red yeast rice into preventive cardiology pathways for statin-intolerant patients. Pharmacy chains require EFSA-compliant documentation and HPLC-MS verification for every lot distributed. Berlin-Brandenburg serves as the regulatory interpretation hub where novel food assessments shape import acceptance for Asian-manufactured extracts.
United States
Concierge cardiology practices in California and Texas mandate COA documentation and source tested extracts through verified supplier portals, bypassing traditional retail distribution. FDA oversight classifies products exceeding trace monacolin K thresholds as unapproved drugs, triggering seizure and import detention. The Pacific Northwest hosts quality verification laboratories that batch-test imports for pharmacy channel compliance.
Japan
Functional food manufacturers in the Kanto region pay premium multiples for extract grades that integrate into beverage and fortified dairy matrices without precipitation. METI guidelines on fermented food safety create a parallel compliance track distinct from pharmaceutical frameworks. Osaka-based nutraceutical formulators are expanding red yeast rice applications beyond traditional capsule formats into new consumption occasions.
India
Underpenetrated urban markets in Maharashtra and Karnataka present whitespace for pharmacy-distributed formulations targeting rising LDL management demand among preventive cardiology patients. CDSCO and FSSAI jointly regulate the boundary between dietary supplement and drug classification for monacolin-containing products. Mumbai pharmaceutical distributors are negotiating exclusive supply arrangements with Taiwanese fermentation houses to secure compliant inventory.
Red Yeast Rice Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmacy-grade certification and direct-to-clinic subscription channels. The vendor base stratifies between industrial-scale fermentation operators with captive supply chains and contract manufacturers dependent on third-party rice sourcing. Two dominant archetypes anchor positioning: Taiwan-based biotech specialists with integrated fermentation-to-extraction capabilities, and North American retail-scale brands controlling supermarket shelf placement through annual vendor negotiations. Competitive moves concentrate on CGMP facility validation timelines and strategic partnerships with functional medicine practitioner networks.
Within the pharmacy-grade tier, SunWay Biotech Co., Ltd. anchors Taiwan-based fermentation capabilities that satisfy EU import clearance requirements. NOW Health Group, Inc. and Nature's Bounty occupy distinct positioning vectors—one through rigorous third-party testing protocols that satisfy pharmacy channel requirements, the other through retail scale controlling shelf placement across North American supermarket chains. These three exemplify how regulatory compliance depth and channel access breadth define competitive boundaries.
| Leading Market Players |
|---|
| Nature's Bounty |
| NOW Health Group, Inc. |
| SunWay Biotech Co., Ltd. |
| Jarrow Formulas, Inc. |
| The Bountiful Company |
| Alesco S.r.l. |
| Natures Plus |
| Amazing Nutrition |
| Xi'an Sost Biotech Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Healthcare provider consolidation in Germany and France is hardening procurement leverage, forcing extract suppliers toward subscription-based pricing models anchored by batch-specific COA documentation. This buyer concentration compresses margins on standard-grade capsules while amplifying premium capture for pharmacy-certified extracts.
Pricing Analysis
Volume concentrates in economy-grade capsules sold through North American supermarket chains, while margin pools shift toward premium extract grades for Japanese functional food integration. Price differentiation hinges on EFSA novel food certification status and HPLC-MS verification depth, with pharmacy-channel buyers commanding steepest discounts at volume. Pricing pressure stems from generic atorvastatin price compression in Medicare Part D, eroding the cost advantage of mass-market supplement positioning. Individual consumers at retail shelves exhibit highest price sensitivity; hospital wellness programs and concierge cardiology practices demonstrate lowest sensitivity due to protocol-driven procurement authority.
Supply Chain Analysis
Freight cost volatility on Asia-Europe routes is compressing landed margins for Taiwan and South Korean fermentation houses serving EU pharmacy chains. Geographic supply concentrates in China's Hubei and Hunan provinces for premium indica rice substrate, Taiwan for integrated fermentation-to-extraction capabilities, and South Korea for CRISPR-engineered strain platforms. Raw material dependencies include indica rice cultivars, pharmaceutical-grade fermentation nutrients, and chromatographic purification resins. Single-source vulnerability concentrates in Hubei's rice belt, where climate-driven harvest variability exposes processors to input cost spikes. Distribution runs through pharmacy chains in Germany and France, direct-to-clinic portals in California and Texas, and supermarket retail across North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The red yeast rice market functions as a cost-of-compliance story where FDA unapproved drug designation and EFSA novel food frameworks erect barrier-to-entry moats favoring capitalized incumbents with validated CGMP facilities.
For Market Incumbents: Extend fermentation capacity in Taiwan and South Korea to secure pharmacy-grade supply contracts before CGMP validation timelines lengthen. Deepen backward integration into indica rice cultivation in Hubei province to buffer climate-driven harvest volatility. Invest in CRISPR-guided strain engineering to compress yield economics against semi-synthetic lovastatin substitution threats. For New Entrants and Emerging Players: Functional medicine practitioner networks in Texas and California offer the most penetrable channel whitespace, bypassing retail shelf slotting fees through direct-to-clinic subscription models. Target underpenetrated urban markets in India's Maharashtra and Karnataka states where pharmacy-distributed formulations face limited incumbent presence. Pursue white-label partnerships with established Taiwanese fermentation houses to circumvent 18-24 month CGMP facility validation requirements. For Investors and Strategic Acquirers: The window for entry favors industrial-scale fermentation operators with captive supply chains and verified EU import clearance. Long-term viability rests on pharmacy-grade certification depth rather than retail brand equity. Monitor EFSA novel food framework evolution as the critical inflection signal—streamlined safety assessments could accelerate competitive entry, while tightened citrinin limits would consolidate supply among chromatographic purification-capable facilities.| Strategic Initiative | Industry Significance |
|---|---|
| CGMP Facility Validation | Pharmacy channel access in Germany and France requires 18-24 month certification timelines that delay revenue conversion. |
| Strain Engineering Investment | CRISPR-guided metabolic pathway optimization rewrites yield economics against semi-synthetic lovastatin cost compression. |
| Backward Integration | In-house indica rice cultivation in Hubei province buffers climate-driven harvest volatility and input cost spikes. |
| Direct-to-Clinic Portal Launch | California functional medicine practices source tested extracts through verified supplier portals, bypassing traditional distribution. |
| EFSA Novel Food Compliance | Streamlined safety assessments accelerate EU market entry for Asian-manufactured extracts with chromatographic purification. |
Research Methodology
Trade databases, regulatory filings with FDA and EFSA, and fermentation industry technical literature formed the secondary backbone of this analysis. Primary interviews with fermentation plant managers, pharmacy procurement leads at German hospital systems, regulatory affairs specialists, and functional medicine practitioners combined with secondary validation to construct demand-side assessments. Bottom-up and top-down triangulation reconciled production capacity data from Hubei and Hunan provinces with end-user consumption patterns across North American retail channels and EU pharmacy chains.
Bottom-up modeling anchored volume projections to fermentation facility throughput and extraction capacity expansion timelines, while top-down analysis cross-checked against cardiovascular health protocol adoption rates in hospital wellness programs. Segmentation dimensions included product format (capsules, extracts, powders, tablets), application tier (dietary supplements, nutraceuticals, functional foods), and distribution channel (pharmacies, online retail, supermarkets, specialty stores). CAGRs derived from regression analysis of historical procurement data and regulatory approval velocity across the projection horizon. Industry-specific forecast inputs incorporated SAMR enforcement patterns on GB 1886.19-2015 purity standards and CDSCO-FSSAI joint regulatory evolution in India.
Several conditions sit outside the modeled scope, including abrupt FDA reclassification of monacolin K thresholds, trade policy disruptions affecting Asia-Europe freight routes, and breakthrough generic statin formulations that compress substitution economics. Forecasts reflect assumptions about regulatory stability and fermentation yield continuity that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Collagen Supplements Market
Nutritional Supplements
Dhea Supplement Market
Nutritional Supplements
Europe Beta-Glucan Market
Nutritional Supplements
Algae Omega Market
Nutritional Supplements
Europe Digestive Health Supplements Market
Nutritional Supplements
Argentina Nutraceuticals Market
Nutritional Supplements
Bone Supplements Market
Nutritional Supplements
Europe Nutrition and Supplements Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Health Supplementary Food OEM and ODM Market
Nutritional Supplements
Sea Moss Supplements Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Liquid Dietary Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market