
 Italy Cloud Computing Market | 2026-2036
Italy Cloud Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Cloud Computing Market Insights
Italian manufacturing is realigning its IT infrastructure mix toward cloud-native platforms as automotive and industrial machinery producers modernize supply chain visibility. Microsoft Corporation leverages its Azure sovereign cloud architecture to anchor enterprise contracts with data residency requirements. SAP SE competes through S/4HANA Cloud deployments tailored to mid-market manufacturers in Northern Italy. Amazon Web Services (AWS) dominates the public cloud tier with Milan region availability zones that sustain low-latency workloads for financial services clients.
Cloud computing denotes on-demand delivery of compute, storage, and networking resources via internet-accessible data centers operating on virtualization and container orchestration layers with service-level agreements guaranteeing uptime thresholds. The technology enables scalable IT consumption without capital-intensive on-premises infrastructure ownership. Hybrid Cloud deployments lead Italian enterprise adoption as organizations balance legacy system integration with elastic public capacity. SaaS applications capture recurring revenue pools across BFSI and retail verticals where subscription models displace perpetual licensing. IaaS growth accelerates fastest among SMEs migrating from colocation facilities to managed cloud stacks.
Italy's cloud market operates under GDPR data protection mandates enforced by the Garante per la Protezione dei Dati Personali alongside EU Cybersecurity Act certification requirements for critical service providers. The Italian Agency for National Cybersecurity (ACN) imposes additional security protocols for public sector cloud procurement that shape vendor qualification criteria. Stakeholders must monitor evolving EU Data Act interoperability rules and their impact on cross-border data portability obligations.
Market Dynamics
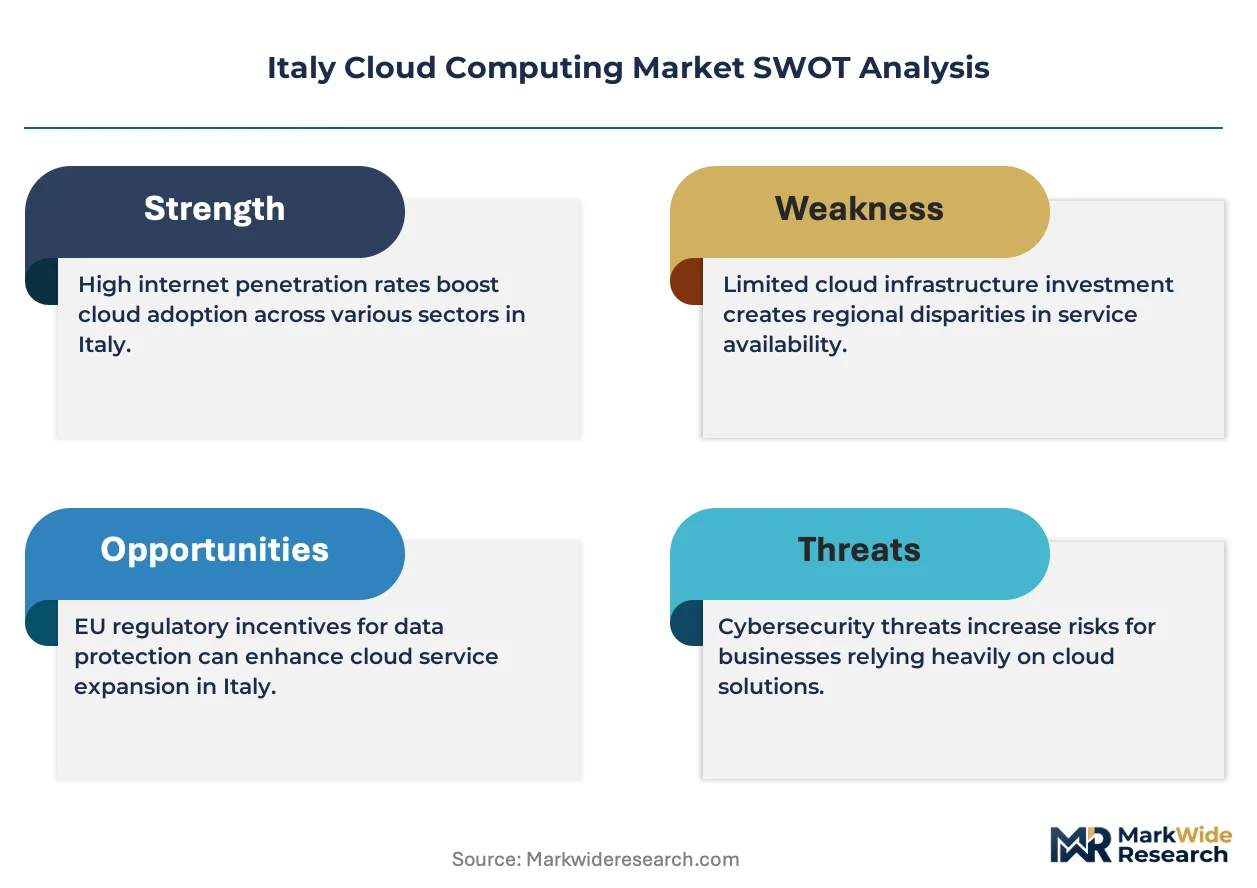
Italian cloud infrastructure is experiencing structural compression between GDPR-mandated data sovereignty requirements and manufacturing demand for real-time supply chain visibility. The EU AI Act accelerates compliance investments while legacy ERP fragmentation slows migration timelines.
Growth Catalysts
- EU AI Act Compliance:Risk classification mandates for high-stakes AI systems are forcing financial services and automotive manufacturers toward certified sovereign cloud architectures.
- Manufacturing ERP Modernization:Automotive and industrial machinery producers are abandoning on-premises SAP ECC systems for cloud-native supply chain orchestration platforms.
- Lombardy Tech Corridor Concentration:Milan-Turin data center clustering creates network effects that attract latency-sensitive financial services and autonomous vehicle development workloads.
Market Restraints
- Data Residency Cost Premium:Sovereign cloud deployments require dedicated infrastructure within Italian borders, inflating compute costs versus pan-European public cloud alternatives.
- Legacy System Technical Debt:Mid-market manufacturers operate heterogeneous on-premises ERP environments that resist API-based integration with modern cloud platforms.
- ACN Certification Bottlenecks:Italian Agency for National Cybersecurity security protocol approvals for public sector vendors extend procurement cycles beyond private sector norms.
Strategic Opportunities
- Southern Italy Underpenetration:Campania and Sicily SME manufacturing bases remain below 15 percent cloud adoption, presenting greenfield infrastructure deployment potential.
- Edge-Cloud Convergence:Industrial IoT sensor networks at automotive plants are converging with centralized cloud analytics to enable predictive maintenance revenue models.
- EU Data Act Interoperability:Emerging portability mandates will create switching-cost reduction services and multi-cloud orchestration tool demand among compliance-conscious enterprises.
Industry Challenges
- Cloud Architecture Skill Scarcity:Kubernetes and Terraform expertise shortages in Northern Italy's labor market inflate implementation timelines and consulting dependency.
- Hybrid Integration Complexity:Manufacturers struggle to maintain synchronous data flows between legacy AS/400 systems and modern containerized microservices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Cloud Computing Market |
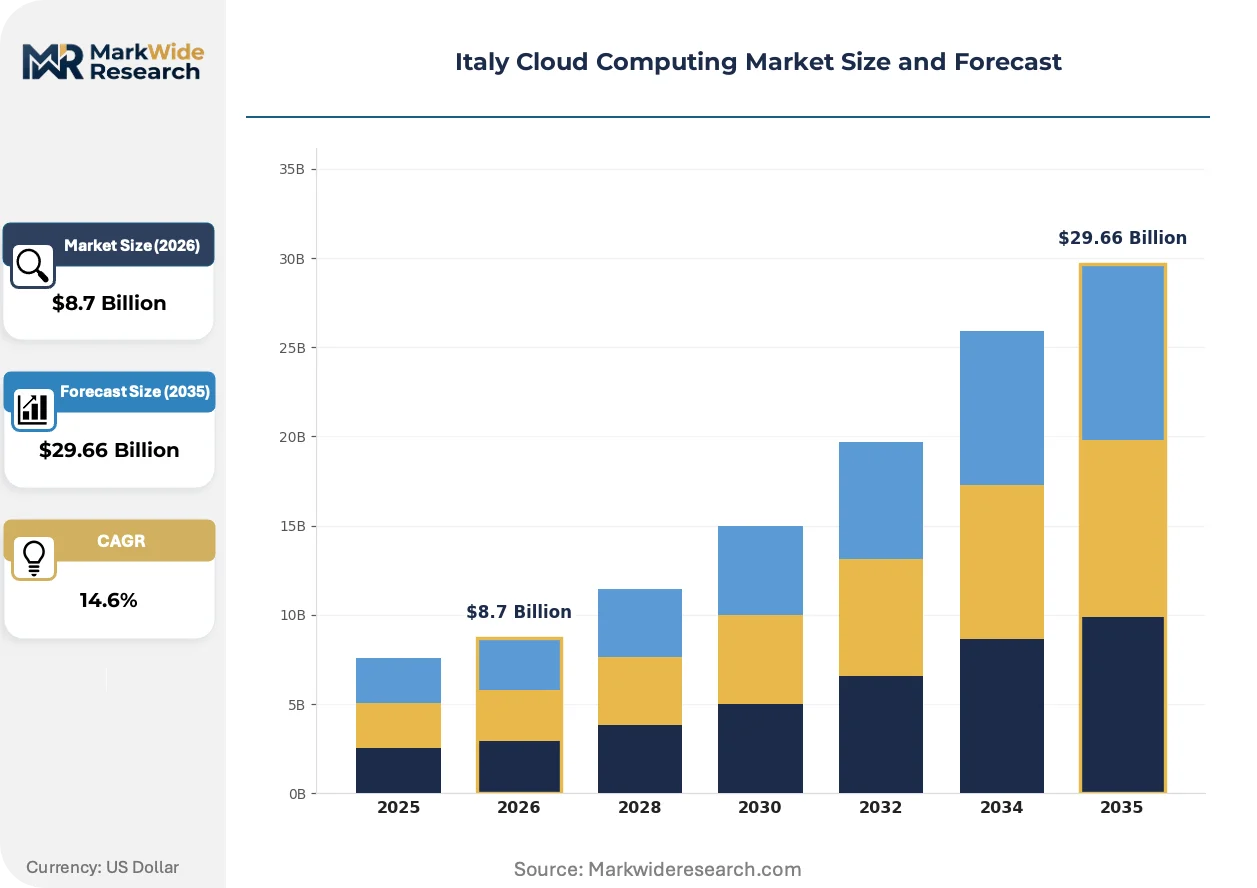
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud Service Type: IaaS, PaaS, SaaS, FaaS End User: SMEs, Large Enterprises, Government, Educational Institutions Industry Vertical: Healthcare, Retail, BFSI, Manufacturing |
| Companies Covered | IBM Corporation, SEEWEB srl, Microsoft Corporation, WIIT, Retelit SpA, Amazon Web Services (AWS), Oracle Corporation, SAP SE, Google LLC (Alphabet Inc.), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Cloud Computing Market Trends and Innovations
Container orchestration and sovereign data architectures are compressing traditional infrastructure procurement cycles. Italian enterprises now demand cloud platforms that satisfy both performance requirements and regulatory data localization mandates.
Serverless computing architectures are overtaking provisioned virtual machine deployments for event-driven manufacturing workloads. Tier-one automotive suppliers in Emilia-Romagna are migrating quality control image processing to function-as-a-service platforms. This shift is overtaking capital-intensive on-premises GPU clusters while reducing time-to-insight for defect detection pipelines.
GDPR Article 44 cross-border transfer restrictions are reshaping vendor qualification criteria for multinational enterprises operating Italian subsidiaries. Data localization requirements now disqualify non-EU cloud regions for sensitive personal data processing. Financial services institutions in Lombardy are responding by mandating EU-only data residency clauses in all new procurement agreements.
Consumption-based pricing models are displacing committed-use discount structures among mid-market manufacturing buyers. CFOs at industrial machinery firms now prioritize pay-per-query analytics over fixed-capacity data warehouse contracts. This behavioral shift is most visible in Veneto's textile automation sector, where seasonal demand volatility makes elastic scaling economically decisive.
Italy Cloud Computing Market Segmentation
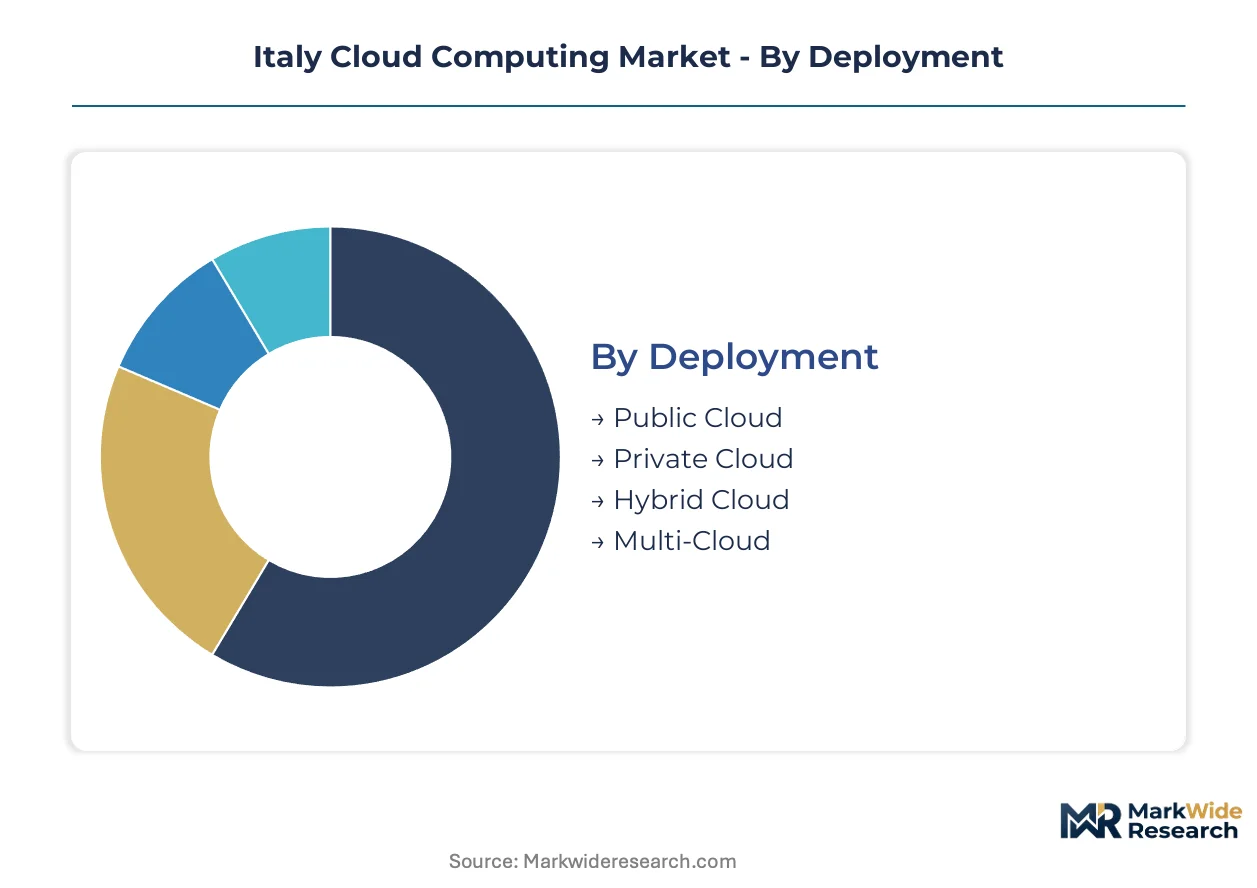
Italian cloud procurement patterns reveal distinct workload-to-infrastructure matching where regulatory pressure and legacy system constraints determine deployment architecture selection. Understanding segment boundaries exposes where vendor switching costs concentrate and where greenfield displacement opportunities emerge.
Deployment:
Upgrade cycles from colocation facilities and aging on-premises data centers are forcing infrastructure decisions around sovereignty, latency, and capital efficiency trade-offs.
- Public Cloud:Shared infrastructure delivers elastic compute and storage via internet-accessible APIs with consumption-based billing. Milan-based financial services firms dominate demand as they seek millisecond-latency connectivity to trading venues without data center capital expenditure.
- Hybrid Cloud:Orchestrated workloads span on-premises private infrastructure and public cloud capacity through unified management planes. Northern Italian manufacturers favor this architecture to maintain ERP core systems locally while bursting analytics workloads to public capacity during quarterly reporting cycles.
- Private Cloud:Dedicated single-tenant infrastructure operates within organizational boundaries or exclusive third-party facilities. ACN certification requirements for public sector agencies in Rome and Florence mandate this deployment for sensitive citizen data processing.
- Multi-Cloud:Distributed workloads across two or more independent cloud providers reduce vendor lock-in and improve resilience. Large enterprises in Lombardy are adopting this approach to satisfy GDPR Article 44 transfer mechanism diversification requirements.
Hybrid Cloud sits at the top of the volume ranking, with Multi-Cloud climbing the fastest.
Service Type:
Customer sophistication and internal IT capability determine abstraction layer preference, with procurement patterns tracking DevOps maturity across Italian industry verticals.
- SaaS:Fully managed application software delivered via subscription eliminates infrastructure management overhead. BFSI institutions in Milan-Turin corridor are displacing perpetual license ERP systems with cloud-native financial planning tools.
- IaaS:Virtualized compute, storage, and networking resources provisioned through self-service portals enable infrastructure-as-code practices. Emilia-Romagna automotive suppliers leverage IaaS for simulation workload burst capacity during vehicle platform development cycles.
- PaaS:Managed development and deployment environments abstract underlying infrastructure to accelerate application lifecycle velocity. Veneto textile automation firms adopt container platforms to modernize legacy inventory management systems without full rewrites.
- FaaS:Event-driven compute execution charges only for actual processing time, eliminating idle resource costs. Quality control image processing at Tier-one automotive plants is migrating from capital-intensive GPU clusters to serverless inference pipelines.
SaaS captures the largest revenue pool, while FaaS demonstrates the steepest expansion trajectory among manufacturing buyers.
End User:
Procurement authority and compliance burden vary sharply across organizational scale, with public sector acquisition cycles extending well beyond private sector norms.
- Large Enterprises:Centralized IT governance and established vendor relationships enable complex multi-year cloud transformation programs. Turin-based automotive OEMs negotiate enterprise agreements spanning hybrid infrastructure, productivity software, and AI development platforms.
- SMEs:Limited internal technical staff and capital constraints favor managed service wrappers around core cloud consumption. Campania and Sicily manufacturing bases below 500 employees remain underpenetrated, presenting infrastructure deployment opportunities.
- Government:ACN security protocol mandates and public procurement law create extended qualification timelines for vendor participation. National and regional agencies in Rome require EU sovereign cloud certification for all sensitive data processing contracts.
- Educational Institutions:Research computing and administrative system modernization drive demand for grant-funded cloud capacity. University consortia in Northern Italy aggregate procurement to negotiate educational pricing tiers.
Large Enterprises dominate absolute spending, with SMEs gaining share fastest as managed service providers reduce adoption friction.
Industry Vertical:
Regulatory intensity and supply chain digitization urgency create divergent cloud investment priorities across Italian economic sectors.
- Manufacturing:Industrial IoT integration and predictive maintenance analytics are displacing on-premises MES systems. Automotive and machinery producers in Lombardy and Emilia-Romagna anchor cloud-native ERP migration demand.
- BFSI:EU AI Act risk classification mandates and GDPR data residency requirements accelerate sovereign cloud investment. Milan-based banks and insurers mandate EU-only data processing clauses in all new procurement agreements.
- Healthcare:Electronic health record interoperability and telemedicine expansion drive secure cloud storage demand. Regional health authorities in Northern Italy evaluate ACN-certified platforms for patient data processing.
- Retail:Omnichannel inventory synchronization and seasonal demand volatility favor elastic infrastructure scaling. Fashion and luxury goods distributors in Tuscany leverage cloud analytics for demand forecasting across global distribution networks.
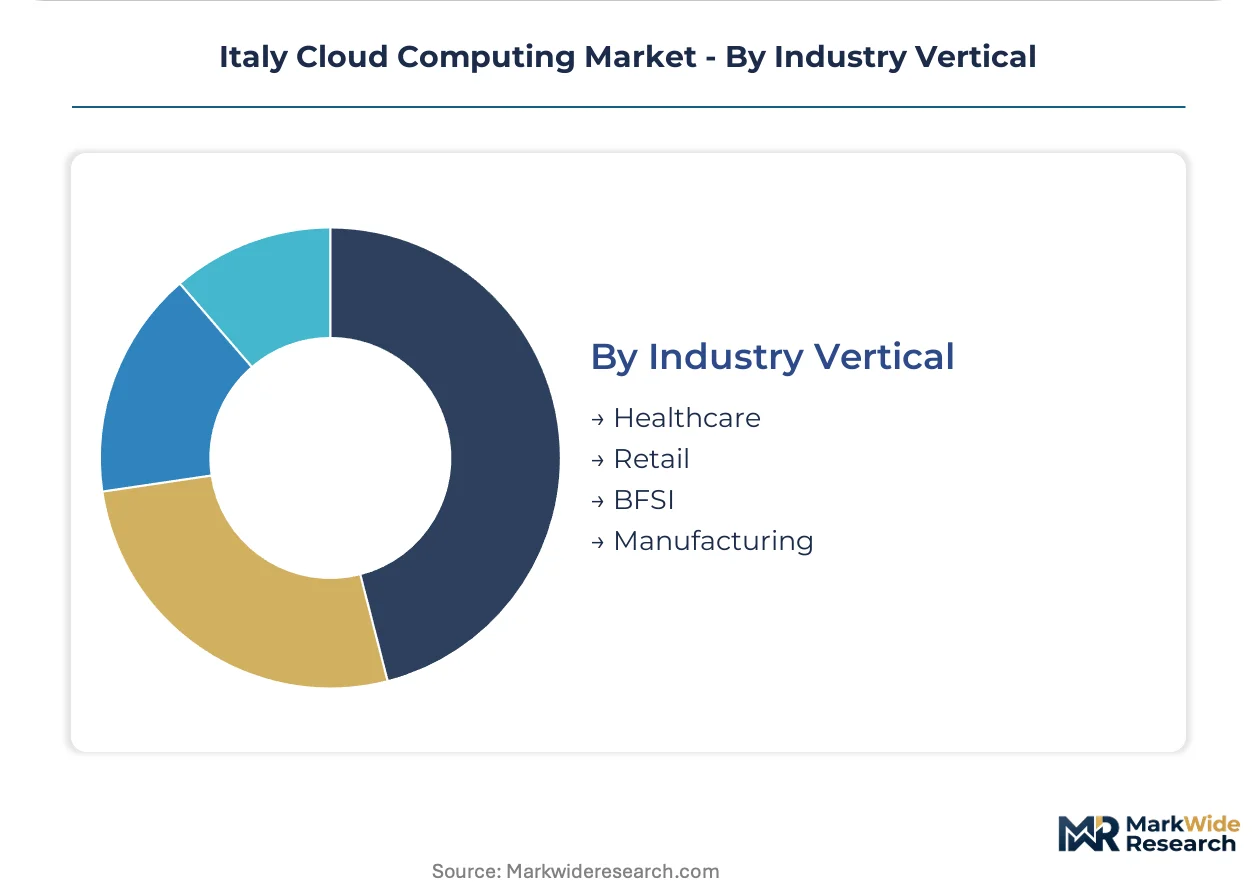
Manufacturing leads vertical spending, with BFSI expanding most quickly as compliance investments compound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are compressing cloud procurement cycles as data residency mandates force infrastructure localization within Italian borders, inflating sovereign deployment costs relative to pan-European alternatives.
Lombardy
Milan-based financial services institutions and automotive OEMs drive demand for millisecond-latency cloud connectivity to trading venues and manufacturing execution systems. Garante per la Protezione dei Dati Personali enforcement of GDPR Article 44 cross-border transfer restrictions shapes vendor qualification criteria. The Milan-Turin tech corridor concentrates sovereign cloud investments from BFSI buyers mandating EU-only data processing clauses.
Piedmont
Turin-headquartered automotive manufacturers anchor enterprise cloud transformation programs spanning hybrid infrastructure and AI development platforms. EU AI Act risk classification mandates for high-stakes autonomous vehicle systems accelerate certified sovereign cloud procurement. The metropolitan area sustains low-latency workload demand for connected vehicle development and supply chain orchestration platforms.
Emilia-Romagna
Tier-one automotive suppliers leverage cloud burst capacity for simulation workloads during vehicle platform development cycles. ACN security protocol requirements for public sector vendors extend procurement timelines beyond private sector norms. Bologna and Modena industrial clusters exhibit fastest serverless computing adoption for quality control image processing pipelines.
Veneto
Textile automation firms prioritize pay-per-query analytics over fixed-capacity data warehouse contracts to manage seasonal demand volatility. GDPR data protection mandates enforced by national regulators shape subscription software procurement patterns. Vicenza and Treviso manufacturing bases demonstrate highest consumption-based pricing model adoption among mid-market industrial machinery producers.
Lazio
Rome-based public sector agencies mandate ACN-certified private cloud deployments for sensitive citizen data processing. Italian Agency for National Cybersecurity security protocols create extended vendor qualification timelines distinct from private sector procurement cycles. The capital region concentrates government cloud spending as national agencies modernize administrative systems under grant-funded capacity arrangements.
Italy Cloud Computing Market Competitive Landscape
Strategic partnerships dominate the current landscape as hyperscale providers anchor enterprise contracts through local system integrator relationships. The vendor base stratifies across three tiers: global hyperscalers with sovereign cloud architectures, regional Italian operators with ACN-certified facilities, and European managed service providers wrapping consumption layers around foreign infrastructure. Two archetypes define positioning: compliance-first specialists capturing public sector mandates, and performance-optimized platforms serving latency-sensitive financial workloads. Competitive intensity centers on data residency certification and edge location density.
Among global hyperscalers, Microsoft Corporation exemplifies the compliance-first archetype through Azure sovereign cloud deployments, while Amazon Web Services anchors the performance-optimized tier with Milan region availability zones. SAP SE occupies a position bridging ERP modernization demand with cloud-native platform migration. These three entities represent distinct strategic postures: infrastructure ownership, application-layer stickiness, and vertical workflow integration.
| Leading Market Players |
|---|
| IBM Corporation |
| SEEWEB srl |
| Microsoft Corporation |
| WIIT |
| Retelit SpA |
| Amazon Web Services (AWS) |
| Oracle Corporation |
| SAP SE |
| Google LLC (Alphabet Inc.) |
| Others |
Pricing and Supply Chain Analysis
ACN certification tiers create a three-tier pricing structure across premium, standard, and economy levels that bifurcates Italian cloud procurement between sovereign-compliant deployments and pan-European alternatives. Premium sovereign cloud capacity commands substantial cost premiums over standard public cloud offerings, while supply chain configurations concentrate certified infrastructure buildout in Northern Italy's Milan-Turin corridor.
Pricing Analysis
Distributor margins on managed cloud services compress as hyperscale direct sales teams displace traditional channel relationships for enterprise accounts above five-hundred-thousand-euro annual contract value. Consumption-based billing dominates mid-market manufacturing adoption, while committed-use discounts anchor large enterprise agreements in Lombardy. Price differentiation rests on data residency certification status, with ACN-certified sovereign deployments carrying forty-to-sixty percent premiums over uncertified alternatives. Pricing pressure stems from AWS and Microsoft direct engagement programs that bypass Italian systems integrators for core infrastructure contracts. SMEs exhibit highest price sensitivity, driving demand for white-label managed service wrappers that abstract underlying infrastructure costs.
Supply Chain Analysis
Multi-supplier qualification mandates from BFSI procurement teams in Milan require simultaneous certification across at least two hyperscale providers plus one regional operator. Geographic supply concentrates in Ireland, Germany, and the Netherlands for pan-European capacity, with Italian sovereign infrastructure drawing from domestic data center developments in Lombardy and Lazio. Raw material dependencies span specialized cooling systems, high-density power distribution units, and fiber-optic interconnect hardware. Single-source vulnerability runs through submarine cable landing stations connecting Italian peninsula to broader European networks. Distribution runs through systems integrator partnerships that bundle professional services with raw infrastructure consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian cloud infrastructure represents a late-cycle quality story where compliance certification supersedes raw performance specifications. Demand shifts decisively toward ACN-certified sovereign architectures as public sector procurement mandates harden data residency requirements.
For Market Incumbents: Acquire Kubernetes and Terraform consulting capabilities to address Northern Italy's cloud architecture skill scarcity. Defensive consolidation should prioritize backward integration into edge data center assets across Emilia-Romagna manufacturing clusters. Threat from emerging European sovereign cloud specialists demands pre-emptive certification investments ahead of ACN protocol expansions. Channel control through exclusive systems integrator relationships remains the critical defensive lever against hyperscale direct sales encroachment.
For New Entrants and Emerging Players: Southern Italy SME manufacturing bases present the most penetrable white-space target, with Campania and Sicily cloud adoption below fifteen percent. Greenfield infrastructure deployment in these regions bypasses entrenched Northern Italy vendor relationships. Go-to-market execution should emphasize consumption-based pricing models that align with seasonal demand volatility in textile and agricultural processing verticals.
For Investors and Strategic Acquirers: Consolidation pressure builds where ACN certification bottlenecks create extended procurement cycles that favor scaled operators with dedicated compliance teams. Long-term viability centers on sovereign cloud specialization rather than commodity public cloud resale. Acquisition target archetype: regional Italian operators with certified facilities and existing public sector contract vehicles. Signal to watch is EU Data Act interoperability rule finalization, which would trigger multi-cloud orchestration tooling demand and reshape vendor switching cost economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | ACN protocol compliance unlocks public sector procurement channels in Rome and Florence. |
| Edge Data Center Expansion | Proximity to Emilia-Romagna automotive plants reduces latency for industrial IoT workloads. |
| Managed Service Wrapper Development | Abstraction layers reduce SME adoption friction in underpenetrated Southern regions. |
| Multi-Cloud Orchestration Platform | EU Data Act portability mandates create switching-cost reduction service demand. |
| Kubernetes Talent Acquisition | Container expertise scarcity in Northern Italy inflates implementation timelines and consulting dependency. |
Research Methodology
Multiple input streams — primary interviews with cloud procurement officers and platform engineers, secondary validation through hyperscaler capex disclosures and ACN certification registries, and trade data from European data center development trackers — were reconciled through bottom-up and top-down triangulation. Stakeholder engagement encompassed CTOs at Lombardy manufacturing firms, IT procurement officers at Milan-based financial institutions, channel partners in systems integrator ecosystems, and regulatory affairs specialists monitoring Garante enforcement patterns. Secondary sources included SEC filings from listed cloud providers, European Data Centre Association capacity reports, and Italian public procurement contract databases.
Historical spending patterns were cross-referenced against panel input from infrastructure deployment specialists to anchor projection assumptions across the analysis window. Segmentation dimensions modeled encompass deployment architecture, service abstraction layer, organizational scale, and industry vertical compliance intensity. CAGRs were derived from elasticity-adjusted adoption curves that weight regulatory mandate timelines against legacy system replacement cycles. Forecast inputs incorporated EU AI Act implementation phases and GDPR Article 44 enforcement trajectory assumptions.
Underlying measurement precision varies by segment; public cloud consumption metrics carry tighter precision than emerging sovereign cloud deployments where certification status creates definitional ambiguity. Forecasts reflect documented assumptions regarding regulatory timeline adherence and hyperscale capacity expansion commitments. Deviation in ACN certification protocol scope or EU Data Act interoperability implementation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
Containers As a Service (Caas) Market
Cloud Computing
Cloud Services Brokerage (CSB) Market
Cloud Computing
Cloud-Based Workload Scheduling Software Market
Cloud Computing
Bare Metal Cloud Service Market
Cloud Computing
Global Cloud Computing in Healthcare Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Cloud Calling Market
Cloud Computing
VM Service Market
Cloud Computing
UK Cloud Computing Market
Cloud Computing
Cloud Systems Management Software Market
Cloud Computing
Global Cloud Dictation Solution Market
Cloud Computing
Global Cloud Migration Market
Cloud Computing
Global Cloud High-Performance Computing Market
Cloud Computing
Global Public Cloud Service Market
Cloud Computing
Cloud Management Market
Cloud Computing
SME Cloud Market