
 South Korea Beauty and Personal Care Products Market | 2026-2036
South Korea Beauty and Personal Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Beauty and Personal Care Products Market Analytics
Young male consumers are rotating into skincare and grooming categories, shifting demand away from historically female-centric positioning. Amorepacific leverages its multi-brand architecture to capture this demographic across price tiers. Olive Young anchors offline discovery through its dense urban store network. LG Household and Health Care competes via pharmacy-channel penetration and dermocosmetic credibility.
Beauty and personal care products encompass topical formulations for skin health, hair maintenance, color cosmetics, and scent application, typically manufactured through emulsification, fermentation, or extraction processes yielding pH-balanced, stability-tested outputs for consumer hygiene and aesthetic enhancement. Skincare dominates value generation due to multi-step regimen adherence and premium essence and serum pricing, while online retail captures the fastest volume growth through live commerce and algorithm-driven replenishment. Natural and organic formulation types attract margin concentration as MFDS disclosure rules and consumer ingredient literacy intensify.
MFDS cosmetic safety regulations, K-beauty export certification frameworks, and Seoul Metropolitan Government beauty industry cluster policies collectively elevate compliance thresholds and shape product registration pathways for domestic and foreign entrants. The MFDS mandates pre-market ingredient review and adverse event reporting, tightening market access for unverified suppliers. Stakeholders must monitor regulatory alignment between domestic MFDS standards and destination-market requirements as K-beauty export volumes expand.
Market Dynamics
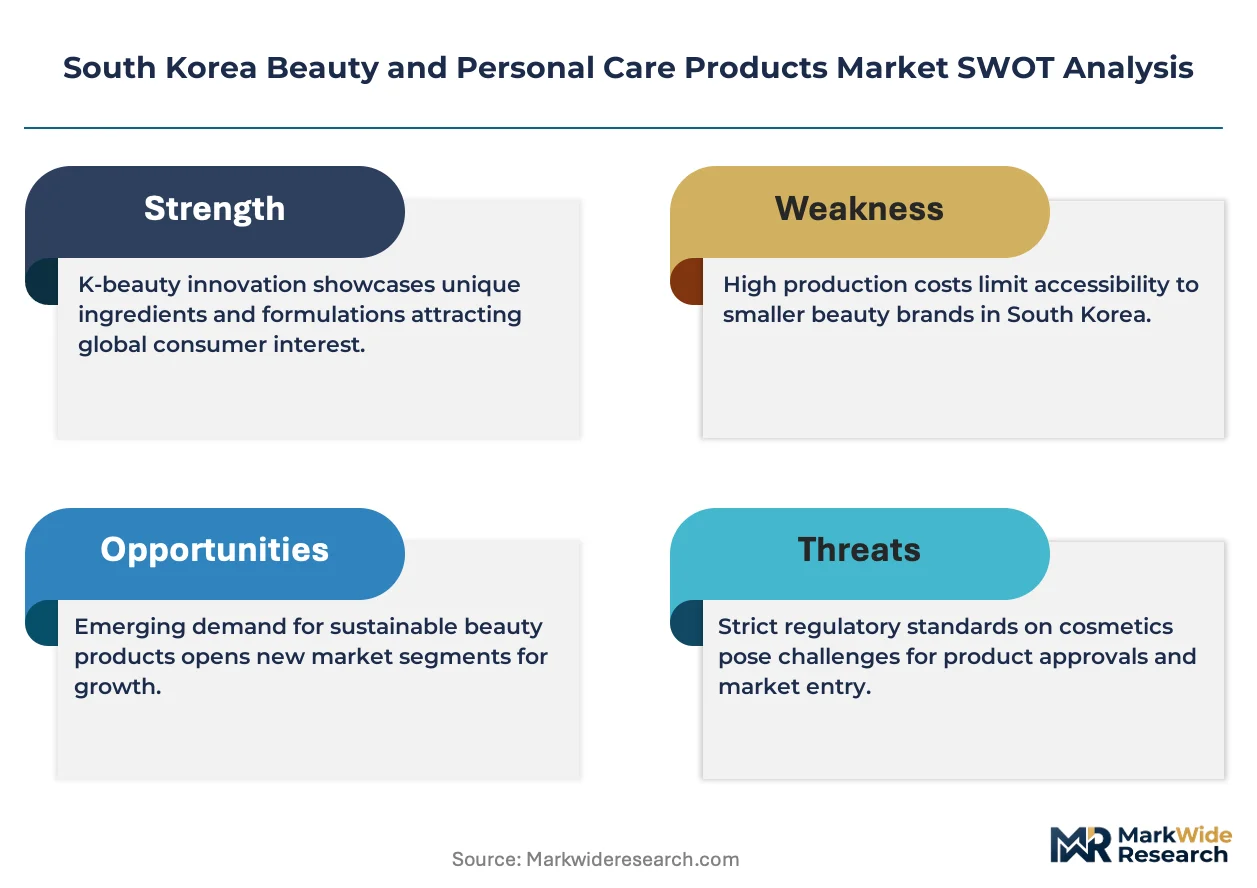
MFDS cosmetic safety regulations are compressing product development timelines while elevating compliance costs, forcing domestic manufacturers to restructure formulation pipelines and accelerate ingredient verification protocols.
Growth Catalysts
- Live commerce infrastructure:Real-time video shopping platforms are converting discovery into immediate purchase across skincare and color cosmetics categories, shortening the traditional retail funnel.
- MFDS pre-market ingredient review:Streamlined safety assessment pathways for domestic manufacturers are accelerating new product registration compared to foreign entrants facing extended documentation requirements.
- Seoul Metropolitan Government cluster policies:Concentrated R&D incentives in Gangnam and Hongdae districts are drawing formulation labs and brand headquarters into proximity, amplifying talent density and cross-firm knowledge spillovers.
Market Restraints
- Raw material import concentration:Specialty active ingredients and fermentation-derived compounds rely heavily on suppliers in China and Japan, exposing margins to currency volatility and cross-border logistics friction.
- MFDS adverse event reporting mandates:Expanded post-market surveillance obligations are extending liability windows and requiring sustained pharmacovigilance investment across product lifecycles.
- Natural formulation cost premiums:Organic certification requirements and clean-label ingredient sourcing are compressing gross margins by fifteen to twenty-five percentage points versus conventional synthetic alternatives.
Strategic Opportunities
- Busan mass-market distribution expansion:Secondary city retail corridors remain underpenetrated by premium domestic brands, creating whitespace for tier-two positioning and localized marketing.
- Dermocosmetic pharmacy channel convergence:Cross-selling between skincare and clinical aesthetic services is opening institutional procurement pathways previously dominated by pharmaceutical distributors.
- Algorithm-driven replenishment:Subscription models powered by skin-type data and usage tracking are locking in recurring revenue and reducing customer acquisition costs for direct-to-consumer brands.
Industry Challenges
- Formulation chemist talent scarcity:Specialized expertise in fermentation-based active development and pH-stable emulsion systems commands premium compensation, constraining mid-tier manufacturer R&D scaling.
- Legacy ERP integration with e-commerce stacks:Inventory synchronization between physical retail networks and live commerce platforms requires substantial middleware investment and real-time data pipeline reconstruction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Beauty and Personal Care Products Market |
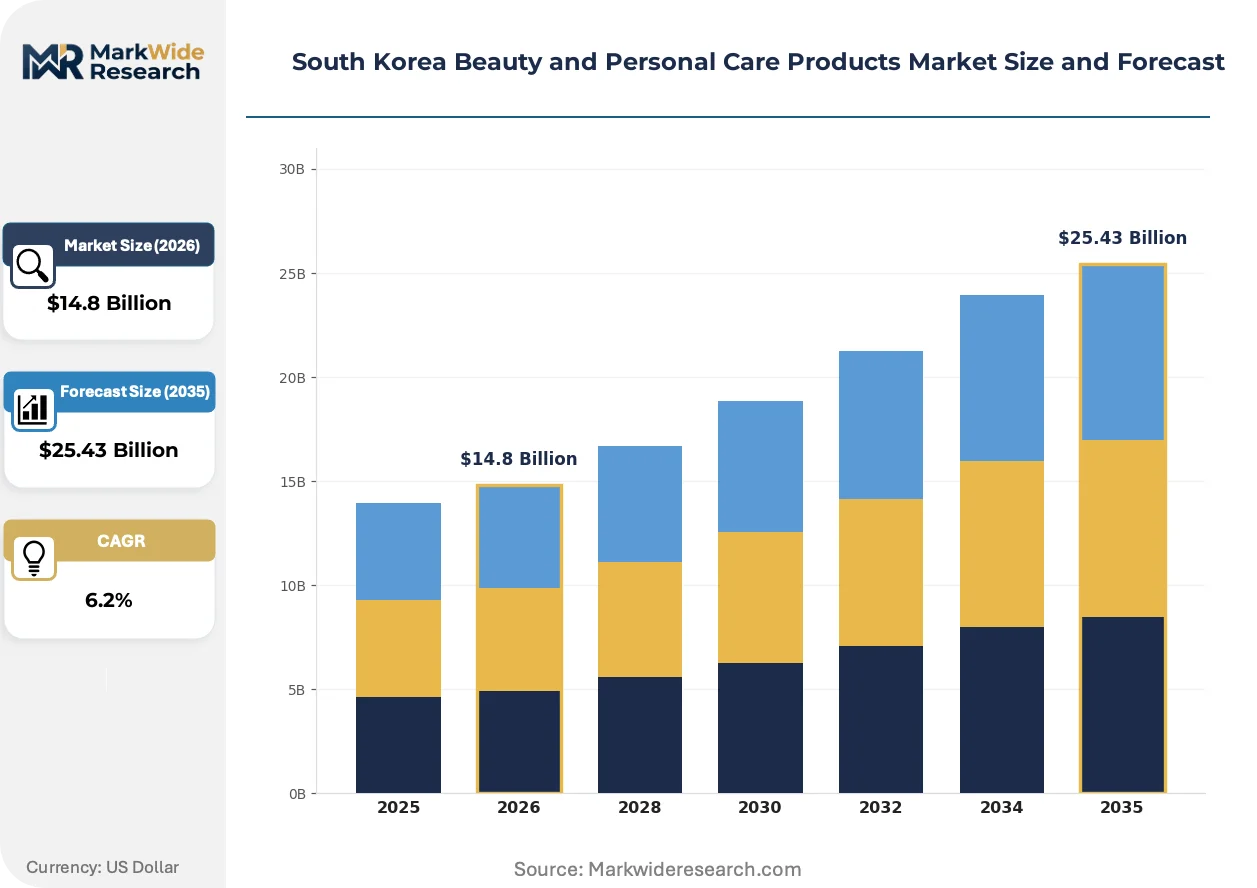
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies Customer Type: Millennials, Gen Z, Professionals, Seniors Formulation Type: Natural, Organic, Chemical-based, Vegan |
| Companies Covered | Innisfree, Olive Young, Amorepacific, Blup, Sephora, LG Household and Health Care, The Face Shop, CJ CheilJedang, Cosmax, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Beauty and Personal Care Products Market Evolving Landscape
Biotechnology-derived actives and digital-first distribution are compressing traditional product lifecycles while fragmenting consumer loyalty across micro-brands and private labels.
Single-dose capsule skincare formats are replacing conventional jar and bottle packaging for travel and hygiene-conscious segments. Young male consumers in Seoul and Busan are adopting these portable formats at accelerating rates for gym and office use. This shift is miniaturizing average transaction values while multiplying purchase frequency and expanding addressable occasions.
MFDS strengthened cosmetic safety standards now mandate expanded stability testing and ingredient disclosure thresholds for all domestic manufacturers. The regulatory burden falls disproportionately on small and mid-sized brands lacking in-house toxicology capabilities. Premium essence and serum categories are responding by consolidating supplier relationships and pursuing pre-certified ingredient libraries.
Subscription-based replenishment is displacing episodic retail purchasing among multi-step regimen adherents. Olive Young's membership program and direct brand sites are capturing this behavioral shift, while traditional department store counters lose replenishment traffic. This pattern is most pronounced among skincare consumers in Seoul's Gangnam corridor aged twenty-five to thirty-four.
South Korea Beauty and Personal Care Products Market Segmentation
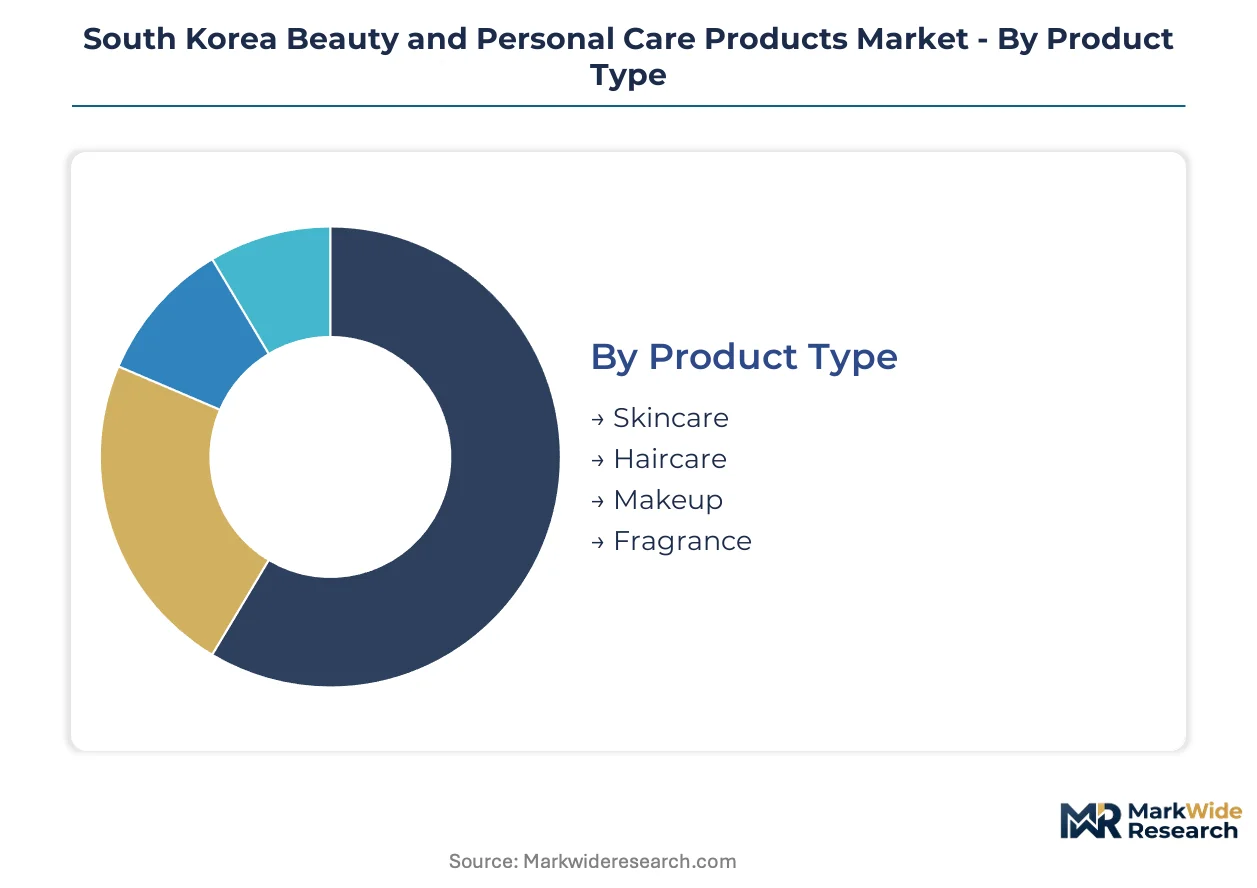
Segmentation reveals how South Korean beauty consumption fragments across channel preferences, generational skincare rituals, and clean-label priorities. Manufacturers must align formulation investments with the specific compliance and margin structures each segment demands.
Product Type:
Margin pools concentrate in multi-step skincare regimens where essence and serum pricing sustains premium positioning.
- Skincare:Emulsion, essence, and ampoule formulations dominate value generation through regimen stacking. Seoul's Gangnam corridor drives demand for fermented actives and pH-balanced toners as male consumers adopt multi-step routines.
- Haircare:Scalp-focused treatments and damage-repair masks anchor this category. Busan mass-market channels distribute volume, while salon-exclusive lines capture margin through professional endorsement.
- Makeup:Cushion foundations and lip tints lead innovation cycles with compressed SKU lifespans.
- Fragrance:Niche and unisex scents are gaining traction among younger demographics seeking differentiation from mainstream designer labels.
The dominant share belongs to Skincare, while Makeup is closing the gap fastest through cushion format innovation and male-targeted color correction products.
Distribution Channel:
Volume flows disproportionately through channels that merge physical trial with digital replenishment infrastructure.
- Online Retail:Live commerce platforms convert real-time engagement into immediate purchase across skincare and color cosmetics. Algorithm-driven skin-type matching and subscription replenishment are locking in recurring revenue for direct-to-consumer brands.
- Specialty Stores:Olive Young's dense urban network anchors offline discovery and sampling. These locations concentrate in Seoul's Hongdae and Gangnam districts where foot traffic sustains premium brand visibility.
- Pharmacies:Dermocosmetic credibility and clinical aesthetic cross-selling define this channel's growth trajectory.
- Supermarkets:Mass-market haircare and basic skincare drive volume through price-promotional mechanics.
Specialty Stores command the largest transaction value per visit, yet Online Retail is expanding its share most rapidly through live commerce adoption.
Customer Type:
Generational divides shape formulation complexity and channel selection with distinct intensity.
- Gen Z:Single-dose capsule formats and portable miniatures align with gym and office usage occasions. This cohort rotates brands frequently, prioritizing TikTok-discovered micro-labels over heritage houses.
- Millennials:Multi-step regimen adherence and ingredient literacy define purchasing behavior. Subscription replenishment and skin-type data tracking sustain loyalty for direct brands.
- Professionals:Time-compressed routines favor multifunctional BB creams and all-in-one essences.
- Seniors:Anti-aging efficacy claims and pharmacy-channel trust dominate selection criteria.
Millennials retain the deepest spending per capita, though Gen Z is gaining share fastest through discovery-driven purchase frequency.
Formulation Type:
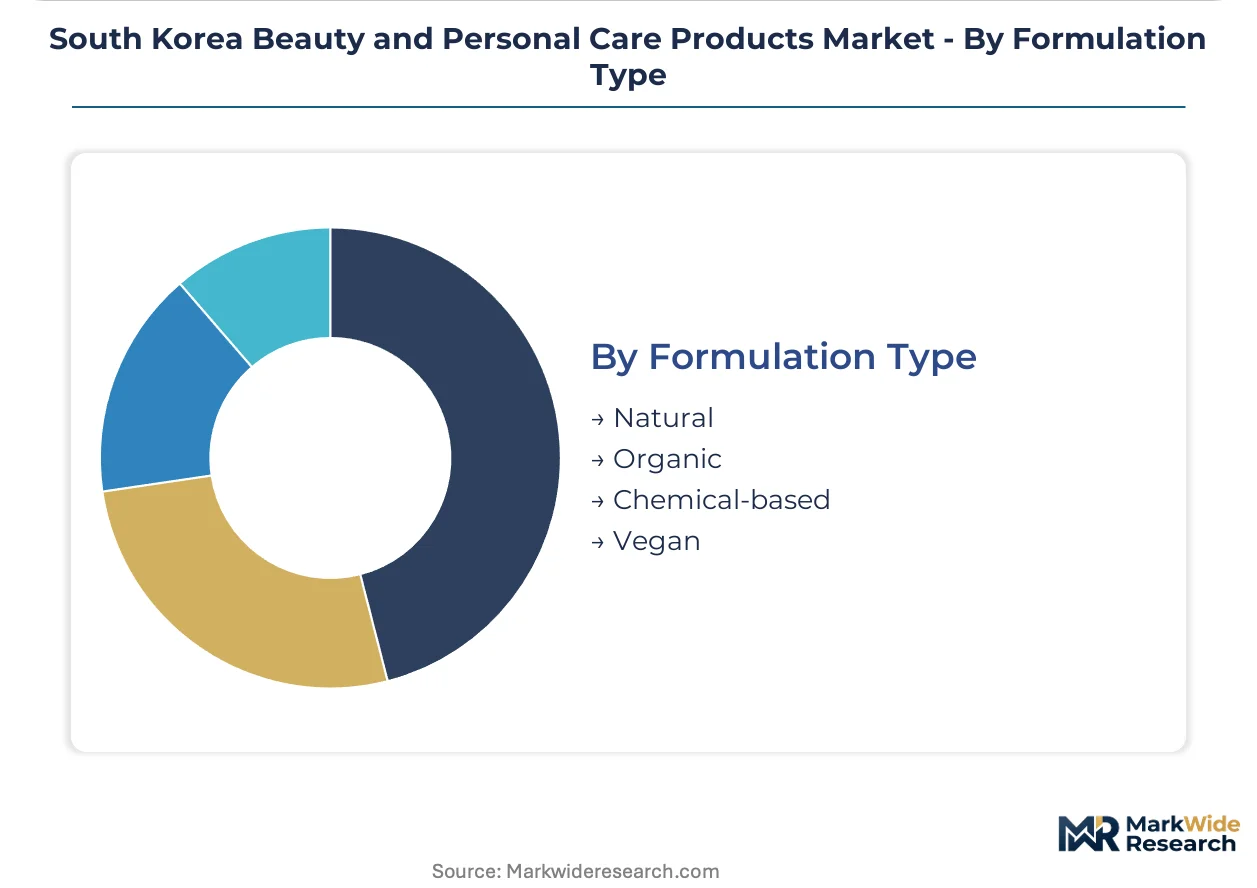
Clean-label positioning extracts margin premiums while elevating compliance burdens under MFDS disclosure mandates.
- Natural:Plant-derived extracts and fermentation-based actives require expanded stability testing. MFDS ingredient disclosure rules compress margins by fifteen to twenty-five percentage points versus synthetic alternatives.
- Organic:Certification requirements and clean-label sourcing constrain supplier flexibility. Premium essence categories are consolidating toward pre-certified ingredient libraries to accelerate registration timelines.
- Chemical-based:Synthetic emulsifiers and preservatives maintain cost efficiency for mass-market distribution.
- Vegan:Animal-free claims attract younger demographics in Seoul and Busan urban corridors.
Natural formulations hold the dominant position by value, yet Vegan is climbing the fastest as cruelty-free positioning resonates with Gen Z purchasing criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Incheon International Airport cargo terminals and Busan Port container infrastructure underwrite South Korea's dual role as domestic consumption hub and K-beauty export gateway. These logistics assets connect Seoul's formulation clusters to Asian retail networks and North American duty-free channels.
Seoul Capital Area
Gangnam and Hongdae retail corridors concentrate premium skincare demand through flagship stores and experiential beauty zones. Seoul Metropolitan Government cluster policies draw formulation labs and brand headquarters into proximity, amplifying talent density. The district anchors live commerce production studios that convert real-time engagement into immediate purchase across skincare categories.
Busan-Ulsan
Mass-market distribution channels drive volume through price-promotional mechanics and pharmacy-network penetration. The Busan Port free trade zone facilitates raw material import for fermentation-derived actives sourced from Japanese and Chinese suppliers. Secondary city retail corridors remain underpenetrated by premium domestic brands, creating whitespace for tier-two positioning.
Daegu-Gyeongbuk
Textile and chemical industry spillovers support cosmetic packaging and secondary packaging material supply chains. The region's industrial base supplies synthetic emulsifiers and preservatives for mass-market haircare formulations. Local manufacturing parks face talent competition from Seoul-based R&D facilities offering premium compensation for formulation chemists.
Daejeon-Sejong
Government research institutes and MFDS regulatory offices concentrate compliance expertise and pre-market safety assessment capabilities. The Sejong administrative city hosts cosmetic ingredient database management and adverse event reporting infrastructure. Proximity to national regulators accelerates registration timelines for domestic manufacturers versus foreign entrants facing extended documentation requirements.
Gwangju-Honam
Agricultural processing infrastructure supports plant-derived extract supply for natural and organic formulation categories. The region's botanical raw material base feeds clean-label ingredient sourcing demands from Seoul-based premium brands. Organic certification requirements and stability testing protocols compress margins for mid-sized manufacturers lacking in-house toxicology capabilities.
South Korea Beauty and Personal Care Products Market Competitive Landscape
Concentration sits with multi-brand conglomerates and specialized retail platforms that span formulation, distribution, and channel control. The market structure tiers across heritage houses with fermentation-based active expertise, pharmacy-channel dermocosmetic specialists, and algorithm-driven direct-to-consumer platforms. Three archetypes dominate: vertically integrated beauty conglomerates, specialized retail discovery networks, and contract manufacturing laboratories serving private-label entrants. Competitive moves center on multi-brand portfolio diversification to capture male consumer rotation and backward integration into captive ingredient supply.
Within the heritage conglomerate tier, Amorepacific anchors multi-brand architecture across price tiers, while LG Household and Health Care occupies pharmacy-channel credibility through dermocosmetic positioning. Among specialized retail platforms, Olive Young exemplifies offline discovery density through urban store networks. These three entities represent distinct competitive vectors: fermentation-based active development, clinical aesthetic cross-selling, and algorithm-driven membership replenishment.
| Leading Market Players |
|---|
| Innisfree |
| Olive Young |
| Amorepacific |
| Blup |
| Sephora |
| LG Household and Health Care |
| The Face Shop |
| CJ CheilJedang |
| Cosmax |
| Others |
Value Network & Pricing Analysis
MFDS cosmetic safety regulations gate both supplier qualification timelines and price tier separation simultaneously, as pre-certified ingredient libraries command premiums while uncertified alternatives face extended registration delays. Clean-label formulation mandates compress margins for mid-tier manufacturers lacking in-house toxicology capabilities, forcing strategic choices between premium positioning and mass-market volume.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between mass-market retailers and fermentation-active suppliers, with three-tier pricing separating premium essence lines from standard emulsion tiers and economy haircare positioning. Price differentiation rests on MFDS certification status and organic claim verification, with certified suppliers extracting fifteen to twenty-five point margin premiums. Cost compression in natural formulation tiers is intensifying because stability testing requirements have lengthened development cycles. Gen Z discovery-driven buyers show highest price elasticity, while Millennial regimen adherents demonstrate lowest sensitivity due to subscription lock-in effects.
Supply Chain Analysis
Just-in-time inventory strategies dominate Seoul-based formulation labs serving live commerce replenishment cycles, while strategic stockpiling of fermentation-derived actives concentrates among premium essence manufacturers hedging Chinese and Japanese supply volatility. Raw material dependencies center on specialty actives from China, fermentation compounds from Japan, and botanical extracts from domestic Gwangju-Honam agricultural processors. Single-source vulnerability runs through Japanese fermentation biotechnology suppliers. Distribution runs through Olive Young's urban store network for offline discovery, with direct-to-consumer platforms capturing replenishment velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's beauty market sits in early-cycle expansion as male consumer rotation into skincare categories broadens addressable demand beyond historically female-centric positioning.
For Market Incumbents: Consolidate backward integration into captive fermentation-active supply to defend against Chinese ingredient cost volatility and MFDS registration delays. Lock in multi-year pre-certified ingredient library contracts with Japanese biotechnology suppliers before capacity constraints tighten. Channel control through Olive Young membership program penetration offers defensive moat against direct-to-consumer algorithmic challengers. For New Entrants and Emerging Players: Lead with Busan mass-market corridor penetration where premium domestic brands remain underrepresented, targeting tier-two positioning between heritage house credibility and private-label economy. Capture Gen Z gym-and-office usage occasions through single-dose capsule format specialization. Go-to-market through TikTok-native discovery rather than legacy retail slotting fee structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed contract manufacturing laboratories serving private-label K-beauty exporters seeking MFDS compliance infrastructure. Five-to-ten year viability hinges on regulatory capability depth rather than brand equity alone. Watch live commerce platform consolidation signals as inflection indicator for distribution margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation-Active Supply | Captive biotechnology capacity insulates Amorepacific and LG Household from Japanese supplier concentration risk. |
| Direct-to-Consumer Algorithmic Replenishment Launch | Skin-type data subscriptions reduce customer acquisition costs for emerging brands competing against Olive Young membership density. |
| Busan Mass-Market Distribution Expansion | Tier-two positioning in secondary corridors captures whitespace between Gangnam premium flagship and supermarket promotional tiers. |
| MFDS Pre-Certified Ingredient Library Investment | Accelerated registration timelines compress new product development cycles for domestic manufacturers versus foreign documentation burdens. |
| Live Commerce Production Studio Buildout | Seoul-based real-time engagement infrastructure converts discovery into immediate purchase across skincare and color cosmetics categories. |
Research Methodology
Desk research of MFDS regulatory filings, customs import records for fermentation actives, and Seoul Metropolitan Government cluster policy documents preceded structured interviews with formulation R&D directors, Olive Young category buyers, pharmacy channel procurement managers, and contract manufacturing laboratory executives. Primary fieldwork across Gangnam and Hongdae retail corridors validated channel traffic patterns and live commerce conversion metrics. Secondary validation drew from Korean Customs Service trade data, K-beauty export certification frameworks, and industry association membership directories. Bottom-up SKU-level demand modeling triangulated against top-down macro consumption projections.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension. Modeled dimensions span product type, distribution channel, generational cohort, and formulation certification status. CAGRs derive from regression-weighted historical trajectory analysis adjusted for regulatory inflection points. Industry-specific forecast inputs include live commerce penetration curves and male consumer adoption rates for multi-step skincare regimens.
Underlying assumptions cover MFDS regulatory stability, Chinese-Japanese supply corridor continuity, and live commerce platform competitive dynamics, with deviation risk concentrated in raw material import disruption or accelerated platform consolidation. Forecasts reflect these documented conditions. Revision becomes warranted when male consumer penetration crosses threshold saturation or when MFDS disclosure mandates expand beyond current stability testing requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Lip Care Products Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Germany Lip Care Products Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Saudi Arabia Hair Care Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Europe Hair and Skincare Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
France Sustainable Personal Care Market