
 France Dermocosmetics Market | 2026-2036
France Dermocosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
France Dermocosmetics Market Insights
French dermocosmetic manufacturing capacity is expanding across the Île-de-France and Rhône-Alpes corridors, where contract laboratories serve both heritage houses and science-driven labels. L'Oréal S.A. leverages its Dermatological Beauty division to anchor pharmacy channel dominance through La Roche-Posay and Vichy. NAOS Group sustains its Bioderma-led position via biology-first positioning in skin barrier repair. Clarins Group competes through botanical extraction expertise tied to its historic Domaine Clarins sourcing.
Dermocosmetics comprise dermatologically tested skincare formulations containing active ingredients at concentrations sufficient to modulate skin physiology, manufactured under pharmaceutical-grade hygiene standards with documented tolerability profiles. These products serve consumers seeking clinically substantiated solutions for sensitive, compromised, or aging skin without prescription escalation. Serums containing peptides and stabilized vitamins command the fastest growth trajectory within product type classifications, while natural extracts dominate ingredient-led purchasing decisions among French consumers prioritizing traceability. Pharmacy distribution channels retain the highest margin pools due to professional recommendation leverage, though online retail segments are capturing incremental volume from subscription-based replenishment models.
ANSM enforces post-market surveillance and cosmetic claims verification under EU Regulation (EC) No 1223/2009, compelling manufacturers to maintain toxicological dossiers for every marketed formulation. REACH and the EU Green Deal framework are progressively restricting certain synthetic compounds, redirecting R&D investment toward biodegradable alternatives and green chemistry processes. Stakeholders must monitor evolving CSRD disclosure obligations and ingredient blacklist expansions to preserve market access and consumer trust positioning.
Market Dynamics
ANSM enforcement of post-market surveillance under EU Regulation (EC) No 1223/2009 is compressing formulation timelines and elevating toxicological documentation requirements across French manufacturing facilities. This regulatory pressure is redirecting R&D investment toward clinically validated actives with pre-substantiated safety profiles.
Growth Catalysts
- EU Green Deal framework:REACH restrictions on synthetic compounds are accelerating biodegradable alternative development among Île-de-France contract laboratories. Green chemistry processes now attract premium positioning in pharmacy channels.
- Pharmacy channel consolidation:Professional recommendation leverage in Paris and Lyon metropolitan clusters is strengthening margin pools for dermatologist-endorsed formulations. Urban pharmacy networks are expanding dedicated dermocosmetic shelf space.
- Peptide stabilization technology:Advances in encapsulation systems are enabling higher active concentrations without tolerability compromise. Serums incorporating these delivery mechanisms command preferential positioning.
Market Restraints
- Active ingredient supply concentration:Pharmaceutical-grade peptide and stabilized vitamin manufacturing concentrates among a limited cohort of specialized chemical suppliers. Input cost volatility from this concentration affects formulation economics.
- CSRD disclosure obligations:Expanding corporate sustainability reporting requirements are extending compliance timelines and documentation burdens for mid-scale manufacturers. Smaller houses face disproportionate administrative load.
- Natural extract substitution pressure:Botanical sourcing from Domaine Clarins and comparable estates creates premium tier competition that compresses synthetic-positioned product margins. Traceability marketing intensifies this substitution dynamic.
Strategic Opportunities
- Rhône-Alpes corridor expansion:Lyon-cluster manufacturing capacity remains underutilized relative to Paris-Île-de-France concentration. Secondary metropolitan pharmacy networks in Grenoble and Saint-Étienne present white-space access.
- Subscription replenishment models:Online retail segments are capturing incremental volume through automated reordering systems. Direct-to-consumer channels bypass traditional pharmacy margin structures.
- Biology-first positioning convergence:Skin barrier repair science is merging with microbiome research to create next-generation tolerability claims. NAOS Group's Bioderma precedent demonstrates category expansion potential.
Industry Challenges
- Toxicological dossier expertise scarcity:Qualified safety assessors capable of ANSM-compliant documentation are concentrated among legacy pharmaceutical service providers. Recruitment competition with broader life sciences sector elevates personnel costs.
- Legacy ERP integration friction:Manufacturing facilities upgrading to pharmaceutical-grade hygiene tracking systems face data migration complexity with existing inventory platforms. Batch traceability requirements compound this technical burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Dermocosmetics Market |
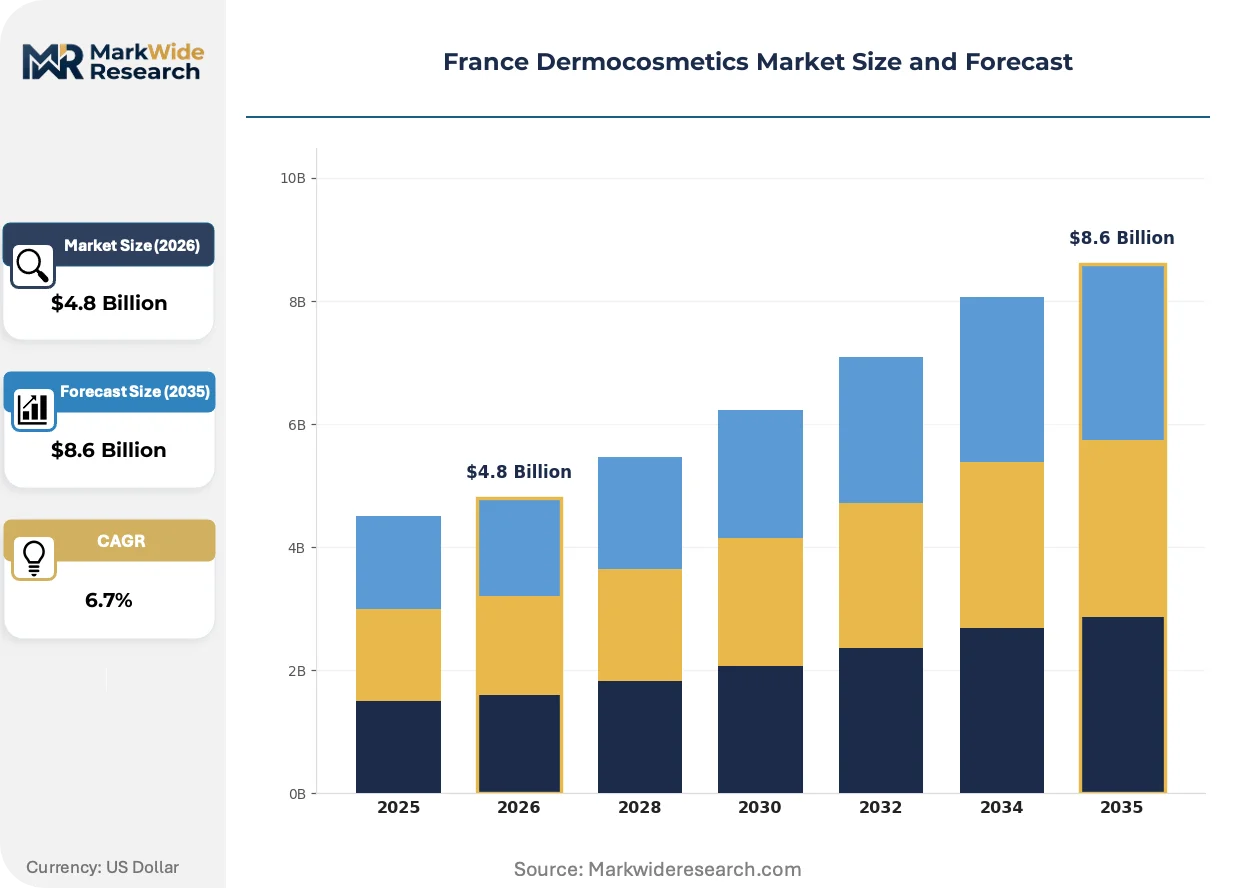
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Serums, Sunscreens Ingredient Type: Natural Extracts, Synthetic Compounds, Vitamins, Peptides Distribution Channel: Pharmacies, Online Retail, Supermarkets, Specialty Stores End User: Adults, Teens, Children, Seniors |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Chanel S.A., Clarins Group, Caudalie, Nuxe, La Roche-Posay, Vichy, NAOS Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Dermocosmetics Market Trends and Innovations
Biotechnology-derived actives and digital skin diagnostics are converging to redefine product development cycles and consumer engagement models across French dermocosmetics. This dual transformation is elevating clinical substantiation standards while compressing traditional marketing lead times.
Encapsulation systems deploying lipid nanoparticle technology are enabling precise dermal penetration of previously unstable vitamins and peptides. Pharmacy buyers in Paris metropolitan clusters are prioritizing these delivery mechanisms for sensitive-skin formulations. The structural consequence is electrifying competitive differentiation around bioavailability metrics rather than concentration claims alone.
REACH authorization requirements under the EU Green Deal are progressively restricting certain synthetic preservatives and UV filters. French manufacturers are reformulating toward biodegradable alternatives with accelerated stability testing protocols. The sensitive-skin serum category faces the most acute reformulation pressure due to its reliance on traditional preservation systems.
Consumer verification behavior is shifting toward ingredient-lot traceability and clinical-study accessibility before purchase commitment. Pharmacy consultation channels are being partially displaced by digital verification platforms that host toxicological summaries and sourcing documentation. This pattern is most visible among Lyon-based consumers aged 25-40 prioritizing transparency over professional recommendation.
France Dermocosmetics Market Segmentation
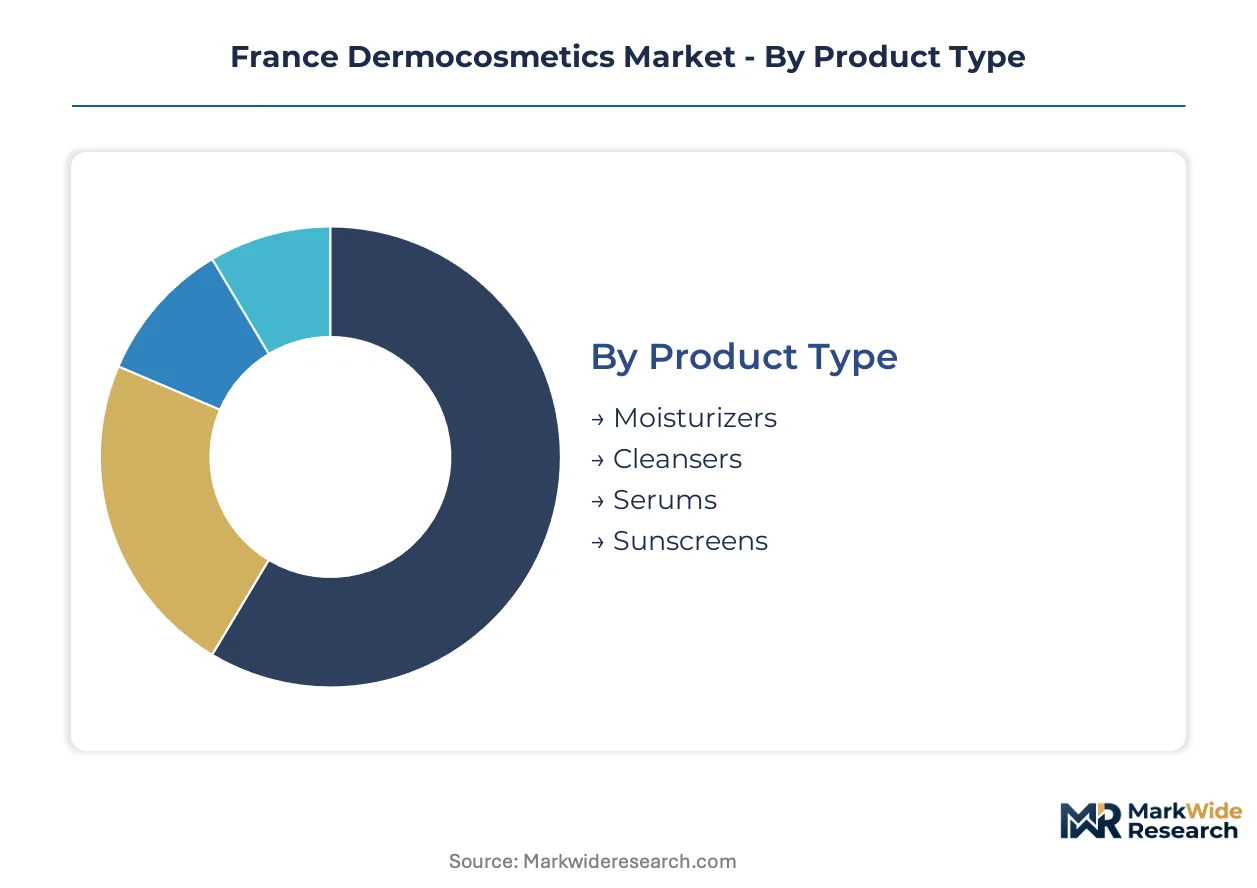
France's dermocosmetic segmentation reveals distinct demand profiles across product formats, ingredient philosophies, and channel preferences. Pharmacy professionals and online platforms are fragmenting the traditional recommendation pathway, while peptide serums and botanical extracts compete for formulation dominance.
Product Type:
Standalone daily-use formulations dominate pharmacy shelf positioning, whereas intensive treatment serums embed into multi-step regimens requiring professional guidance.
- Moisturizers:Barrier-repair formulations with ceramide complexes anchor pharmacy channel volume in Paris and Lyon metropolitan clusters. ANSM documentation requirements favor heritage houses with established tolerability dossiers over newer entrants.
- Serums:Peptide and stabilized vitamin concentrates command premium positioning through encapsulation technology advances. Île-de-France contract laboratories are scaling lipid nanoparticle production to serve this accelerating demand from dermatologist-recommended brands.
- Cleansers:Micellar water and syndet formulations maintain baseline volume across all channels with lower margin capture.
- Sunscreens:Reformulation pressure from REACH UV filter restrictions is compressing SKU diversity while elevating mineral alternative development costs.
Volume placements concentrate in Moisturizers; the faster expansion belongs to Serums.
Ingredient Type:
Cost tier stratification separates premium-positioned botanical sourcing from commodity synthetic positioning, with peptide and vitamin actives occupying the technology-premium middle ground.
- Natural Extracts:Domaine Clarins and comparable estate-sourced botanicals command traceability premiums in Lyon-cluster pharmacy networks. CSRD disclosure obligations are elevating documentation costs for smaller houses lacking captive agricultural assets.
- Peptides:Pharmaceutical-grade manufacturing concentrates among specialized Rhône-Alpes chemical suppliers, creating input cost volatility that squeezes mid-tier formulation economics. Encapsulation delivery systems are differentiating stable from commodity peptide offerings.
- Vitamins:Stabilized retinol and ascorbic acid variants require sophisticated packaging to prevent oxidation degradation.
- Synthetic Compounds:REACH authorization restrictions are accelerating substitution toward biodegradable alternatives, particularly in preservative systems.
Natural Extracts capture the highest margin tier; Peptides are climbing the fastest as encapsulation technology matures.
Distribution Channel:
Professional recommendation leverage in physical pharmacy networks contrasts with algorithm-driven replenishment convenience in digital channels, fragmenting customer acquisition economics.
- Pharmacies:Paris and Lyon metropolitan clusters sustain margin pools through dermatologist endorsement leverage, with dedicated dermocosmetic shelf space expanding across urban pharmacy networks. ANSM post-market surveillance requirements reinforce professional channel credibility.
- Online Retail:Subscription-based replenishment models are capturing incremental volume from consumers aged 25-40 prioritizing convenience over consultation. Direct-to-consumer channels bypass traditional pharmacy margin structures while demanding logistics investment.
- Supermarkets:Mass-market dermocosmetic lines compete on price accessibility with reduced clinical substantiation claims.
- Specialty Stores:Sephora and comparable beauty retailers occupy an intermediate positioning between pharmacy authority and digital convenience.
Pharmacies retain the dominant share position; Online Retail is gaining share fastest through subscription mechanics.
End User:
Maturity-based segmentation aligns formulation tolerability with skin barrier condition, directing R&D investment toward sensitive-skin adult positioning and pediatric safety dossiers.
- Adults:Anti-aging and sensitive-skin positioning concentrates demand in the 30-55 demographic across all French metropolitan centers. Peptide serums and stabilized retinol formulations target this segment with the highest per-capita expenditure.
- Seniors:Barrier-compromised skin conditions drive pharmacy channel loyalty and professional consultation frequency.
- Teens:Acne-targeted formulations with salicylic acid and niacinamide compete between pharmacy and specialty retail channels.
- Children:Minimal-ingredient safety requirements favor heritage houses with established pediatric tolerability documentation.
Adults represent the revenue anchor; Seniors show the steepest expansion trajectory as population aging intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thermal spring water sourcing from the Auvergne volcanic basin anchors French dermocosmetic formulation heritage. Île-de-France and Auvergne-Rhône-Alpes concentrate manufacturing capacity, pharmacy distribution networks, and dermatological research infrastructure.
Île-de-France
Paris metropolitan pharmacy networks command premium shelf positioning for dermatologist-recommended brands. ANSM post-market surveillance requirements under EU Regulation (EC) No 1223/2009 elevate documentation burdens for entrants lacking established toxicological dossiers. Contract laboratories across the Paris basin scale lipid nanoparticle encapsulation production to serve peptide serum demand.
Auvergne-Rhône-Alpes
Lyon-cluster urban pharmacies sustain margin pools through professional consultation leverage. REACH authorization restrictions on synthetic UV filters are accelerating mineral alternative development among Rhône-Alpes formulators. Grenoble and Saint-Étienne secondary metropolitan networks present underutilized pharmacy channel access.
Provence-Alpes-Côte d'Azur
Marseille-Nice corridor consumers aged 25-40 prioritize ingredient traceability over professional recommendation. CSRD disclosure obligations elevate documentation costs for smaller houses lacking captive agricultural assets. Grasse-area botanical extraction expertise supplies heritage houses with estate-sourced actives.
Hauts-de-France
Lille metropolitan pharmacy networks extend Belgian border-region distribution access. EU Green Deal biodegradable alternative mandates redirect R&D investment toward green chemistry processes. Contract manufacturing facilities near the Belgian frontier serve cross-border pharmacy chains.
Nouvelle-Aquitaine
Bordeaux urban consumers demonstrate subscription-based replenishment model adoption through direct-to-consumer channels. CNIL data governance requirements shape digital verification platform development for ingredient-lot traceability. Thermal spring water bottling from Dax and Saint-Paul-lès-Dax feeds regional formulation supply.
France Dermocosmetics Market Competitive Landscape
Global majors compete with regional champions across pharmacy channel access and dermatological endorsement leverage. Market structure concentrates around heritage houses with captive thermal water rights and biology-first specialists with barrier-repair science positioning. Three archetypes dominate: conglomerate-backed dermatological beauty divisions, independent biology-driven laboratories, and botanical extraction heritage houses. Competitive moves center on pharmacy shelf space expansion and encapsulation technology licensing.
Within the conglomerate-backed tier, L'Oréal S.A. anchors pharmacy channel dominance through its Dermatological Beauty division. NAOS Group occupies a distinct biology-first position exemplified by its Bioderma-led skin barrier repair focus. Clarins Group represents botanical extraction heritage, leveraging its historic Domaine Clarins sourcing for traceability premiums. These three entities collectively illustrate the competitive tension between pharmaceutical-grade clinical substantiation and estate-sourced natural positioning.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Chanel S.A. |
| Clarins Group |
| Caudalie |
| Nuxe |
| La Roche-Posay |
| Vichy |
| NAOS Group |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal REACH restrictions on synthetic compounds gate qualified supply and premium-tier pricing access for French dermocosmetic manufacturers. Biodegradable alternative development elevates input costs while creating tiered market access based on green chemistry certification.
Pricing Analysis
After-sales service bundling separates pharmacy channel premiums from unbundled direct-to-consumer pricing. Three-tier pricing structure across premium, standard, and economy levels reflects brand heritage, thermal water provenance, and encapsulation technology sophistication. Cost compression in mid-tier peptide formulations intensifies as pharmaceutical-grade active suppliers concentrate pricing power. Mass-market supermarket buyers exhibit highest price sensitivity; pharmacy-loyal consumers aged 45-65 demonstrate lowest elasticity.
Supply Chain Analysis
Skilled toxicological assessor scarcity in Île-de-France and Rhône-Alpes manufacturing corridors elevates personnel costs and extends batch release timelines. Pharmaceutical-grade peptide production draws from specialized Rhône-Alpes chemical suppliers, stabilized vitamin inputs hinge on Swiss and German packaging technology, and thermal spring water sourcing anchors in Auvergne volcanic basin rights. Single-source vulnerability concentrates in lipid nanoparticle encapsulation equipment. Distribution runs through pharmacy networks in Paris and Lyon metropolitan clusters, with subscription logistics expanding through Île-de-France fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Regulation (EC) No 1223/2009 toxicological dossier requirements construct a cost-of-compliance moat that favors heritage houses with established ANSM documentation over capital-constrained entrants.
For Market Incumbents: Anticipate REACH authorization expansion by accelerating biodegradable preservative reformulation pipelines. Consolidate peptide encapsulation capacity through backward integration into Rhône-Alpes contract laboratory networks. Channel control through dedicated pharmacy shelf space expansion defends margin pools against subscription-based displacement.
For New Entrants and Emerging Players: Subscription platform partnerships offer the most penetrable channel architecture for bypassing pharmacy endorsement gatekeeping. Target Grenoble and Saint-Étienne secondary metropolitan networks where dermatologist-recommended brand presence remains underdeveloped. Biology-first positioning around microbiome science provides differentiation leverage against heritage thermal water claims.
For Investors and Strategic Acquirers: Accelerated CSRD disclosure obligation compliance among mid-scale manufacturers is the leading indicator that consolidation pressure is intensifying. Biology-driven laboratories with established skin barrier repair science demonstrate strongest long-term viability within a five-to-ten-year window. Acquisition target archetype: independent formulators with captive encapsulation technology and incomplete pharmacy channel coverage.
| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Lipid nanoparticle delivery systems differentiate peptide serum bioavailability claims for pharmacy buyers. |
| Biodegradable Reformulation Program | REACH-compliant preservative alternatives preserve market access under EU Green Deal authorization timelines. |
| Pharmacy Channel Expansion | Dedicated shelf space in Lyon-cluster urban networks captures professional recommendation leverage. |
| Direct-to-Consumer Subscription Launch | Automated replenishment models bypass traditional pharmacy margin structures for convenience-prioritized demographics. |
| Thermal Water Rights Acquisition | Auvergne volcanic basin sourcing anchors heritage positioning and traceability marketing premiums. |
Research Methodology
ANSM post-market surveillance filings, EU REACH authorization databases, and pharmacy channel sales audit data formed the secondary backbone of this analysis. Primary interviews with dermatology pharmacy buyers, contract laboratory R&D directors, toxicological safety assessors, and dermocosmetic brand managers combined with secondary validation. Bottom-up and top-down triangulation cross-referenced manufacturing capacity estimates against channel inventory velocity.
Bottom-up modeling anchored volume projections in pharmacy network expansion rates and online subscription adoption curves across the analysis window. Segmentation dimensions included product format, ingredient philosophy, distribution channel, and metropolitan cluster demand intensity. CAGRs derived from historical growth pattern analysis adjusted for regulatory intervention timing and green chemistry investment cycles. Encapsulation technology maturity curves and thermal water sourcing constraints informed industry-specific forecast inputs.
Caveats apply where ANSM enforcement intensity, REACH blacklist expansion, or CSRD disclosure timeline acceleration could materially shift the outlook. Forecasts reflect assumptions about biodegradable alternative development cost trajectories and pharmacy channel consolidation pace. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Powdered Hand Soap Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Delivery Systems in Personal Care Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Handmade False Eyelash Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
E-Pharmacy Beauty and Personal Care (BPC) Market
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Cosmetics Foundation Market